
 Global Decorative Print Market | 2026-2036
Global Decorative Print Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decorative Print Market Foresight
Buyer fragmentation across small-batch interior designers and custom furniture builders is repositioning volume patterns away from mass-market retail chains. Schattdecor AG leverages its European production network to sustain leadership in melamine-faced decorative papers for flooring laminates. Surteco Group SE anchors its position through specialized surface solutions for furniture and interior applications. Ahlstrom-Munksjö Oyj competes in fiber-based substrates by controlling technical paper supply chains for high-performance print receptive layers.
Decorative print encompasses surface imaging processes that transfer pigmented or dyed patterns onto substrates using resolutions typically ranging from 300 to 2400 dpi for digital systems, serving primarily to enhance aesthetic value and brand differentiation in finished goods. Gravure retains dominance in high-volume flooring and furniture surface runs where cylinder-based consistency outweighs setup costs, while digital printing captures fastest expansion in wallcoverings and textile decoration by eliminating plate changeover for short runs. Screen printing occupies stable niche positions in ceramic and glass decoration where ink deposit thickness determines visual depth and durability.
EPA regulations on hazardous air pollutants from printing operations constrain solvent-based flexography adoption in the United States, while REACH and the EU F-Gas Regulation shape ink formulation requirements across European converting facilities. China's MEE enforces emission controls on printing clusters in Zhejiang and Guangdong provinces, redirecting investment toward compliant water-based and energy-curable systems. Stakeholders must monitor evolving chemical restriction timelines and assess digital press retrofit economics against cylinder gravure replacement cycles.
Market Dynamics
Digital printing systems are compressing run-length economics across flooring and furniture surfacing, while REACH and EU Green Deal mandates on volatile organic compound emissions force ink formulation changes that favor water-based gravure and UV-cured digital platforms.
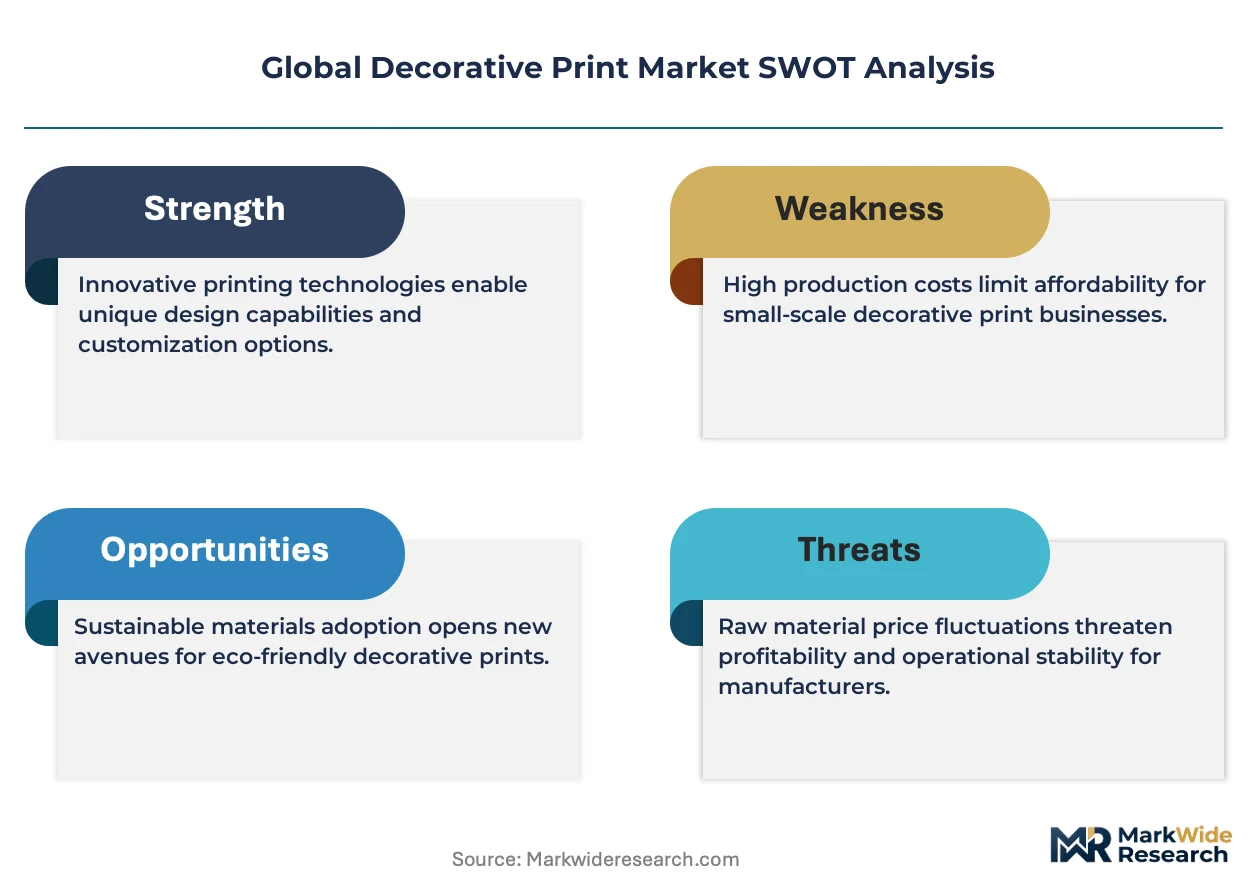
Growth Catalysts
- EU Green Deal VOC mandates:Emission ceilings on solvent-based systems are redirecting converter investment toward compliant water-based and energy-curable ink platforms across German and Italian production clusters.
- Short-run customization demand:Interior designers and bespoke furniture builders are fragmenting order patterns, pulling volume away from mass retail chains toward digitally enabled job shops.
- China MEE enforcement:Emission controls on printing clusters in Zhejiang and Guangdong provinces are accelerating facility upgrades to compliant systems, expanding the addressable base for digital press vendors.
Market Restraints
- Pigment and resin input volatility:Titanium dioxide and acrylic resin supply fluctuations constrain margin predictability for decorative paper and film converters serving flooring laminators.
- Gravure cylinder supply concentration:High-volume flooring runs depend on engraved cylinder availability from a narrow supplier base concentrated in Germany and Japan, creating bottleneck risk.
- Digital press capex thresholds:Single-pass UV inkjet systems require capital commitments that exclude smaller converters from competitive short-run segments.
Strategic Opportunities
- India furniture manufacturing expansion:Domestic production growth under PLI scheme incentives is creating unmet demand for decorative surfacing substrates in Gujarat and Tamil Nadu industrial corridors.
- Wallcovering textile hybridization:Digital printing on nonwoven and woven backings is opening specification channels in hospitality and healthcare interiors previously served by coated papers.
- CSRD supply chain disclosure:Corporate sustainability reporting requirements are favoring converters with certified low-emission production, creating differentiation premiums in European specification markets.
Industry Challenges
- Color management specialist scarcity:ICC profiling and expanded-gamut calibration expertise remains concentrated among aging gravure technicians, constraining digital press utilization rates.
- Legacy ERP integration friction:Digital workflow management platforms require reconfiguration of existing order-to-production systems, delaying payback periods for hybrid gravure-digital operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decorative Print Market |
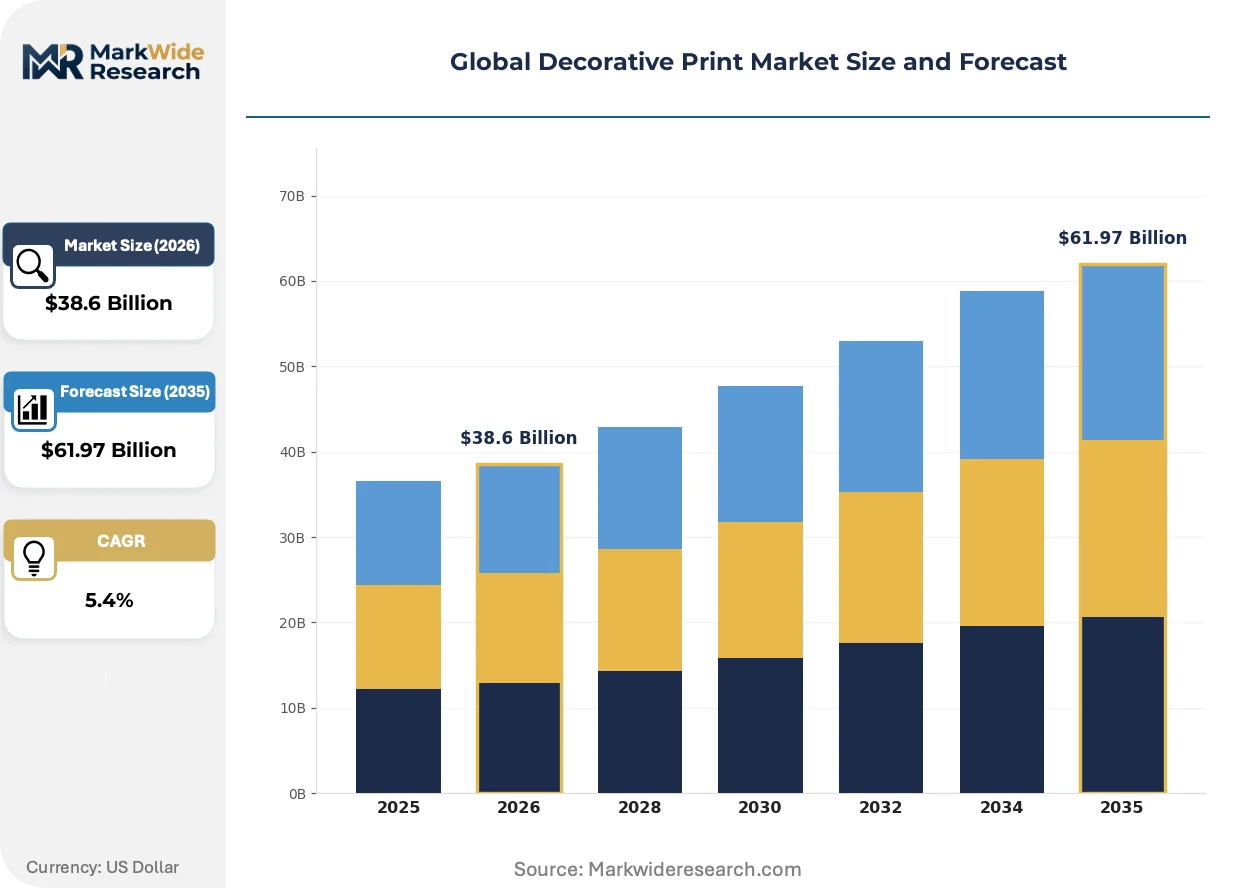
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Digital Printing, Screen Printing, Flexography, Gravure, Sublimation, Letterpress Application: Wallcoverings, Flooring, Furniture Surfaces, Textile Decoration, Packaging Design, Automotive Interiors Material Type: Vinyl, Paper, Fabric, Glass, Metal, Ceramic End User: Interior Designers, Textile Manufacturers, Packaging Firms, Vehicle Upholstery Makers, Flooring Producers, Furniture Builders |
| Companies Covered | Schattdecor AG, Surteco Group SE, Ahlstrom-Munksjö Oyj, Felix Schoeller Group, Interprint GmbH, Impress Surfaces GmbH, ITC Limited, Stora Enso Oyj, Papierfabrik August Koehler SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decorative Print Market Shifts & Advancements
Surface imaging technology is fragmenting along run-length lines, with digital platforms capturing specification-driven segments while gravure defends commodity volume through cylinder efficiency.
Single-pass UV inkjet printing is converging with in-line priming and coating systems to enable direct-to-substrate decoration of engineered wood and fiber cement panels. Flooring manufacturers in Germany and the United States are piloting these integrated lines for sample and short-run production. The technology is converging with traditional lamination workflows, compressing the gap between digital proofing and full-scale gravure deployment.
EPA hazardous air pollutant regulations on printing operations are constraining solvent-based flexography adoption in the United States. Converters serving furniture and flooring markets face retrofit deadlines that favor water-based ink systems or digital alternatives. California and Northeast state implementation plans are accelerating compliance timelines beyond federal minimums, pressuring regional production economics.
Specification procurement is fragmenting across architect and designer direct channels, bypassing traditional distributor networks for project-specific substrate sourcing. Large-format printing clusters in China and Germany are establishing direct digital sample programs that compress the specification cycle from months to weeks. Hospitality and multi-family residential verticals in the United States and United Kingdom are most exposed to this channel disintermediation.
Global Decorative Print Market Segmentation
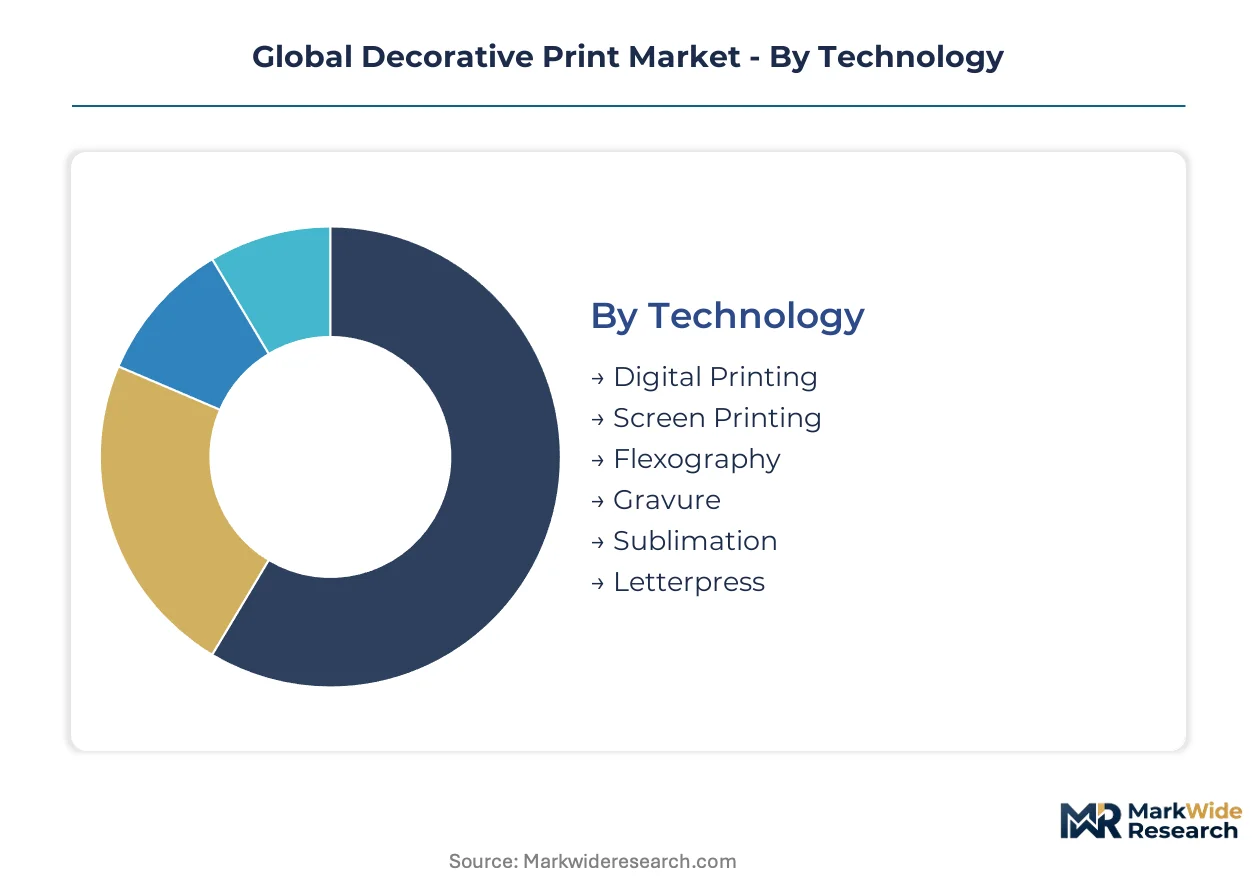
Technology and material choices in decorative print determine capital deployment, regulatory exposure, and margin structure across converter operations. Segment boundaries are blurring as digital platforms compress run-length thresholds and hybrid substrates expand specification possibilities.
Technology:
Gravure and digital printing demand the heaviest upfront capital, with cylinder engraving infrastructure and single-pass UV inkjet systems representing multi-million dollar commitments that shape competitive entry.
- Gravure:Cylinder-based rotogravure achieves unmatched consistency across high-volume flooring and furniture laminate runs. German and Japanese cylinder suppliers concentrate engraving capacity, creating supply bottlenecks for converters serving mass-market flooring producers.
- Digital Printing:UV-cured inkjet and water-based systems eliminate plate changeover costs, capturing specification-driven wallcovering and textile decoration from fragmented interior designer demand. REACH VOC mandates accelerate converter migration toward compliant digital platforms.
- Screen Printing:Thick ink deposit suits ceramic and glass decoration where visual depth and durability outweigh speed requirements.
- Flexography:Solvent-based systems face EPA hazardous air pollutant constraints in US operations, redirecting investment toward water-based alternatives.
- Sublimation:Heat-transfer chemistry dominates polyester textile decoration with dye penetration achieving wash-fast performance.
- Letterpress:Raised-plate mechanics persist in premium packaging design applications requiring tactile impression quality.
Gravure absorbs the bulk of installed capacity; digital printing is expanding most quickly.
Application:
End-use diversification spreads converter revenue across cyclical construction activity and steadier consumer goods demand.
- Flooring:Laminate and vinyl plank surfacing commands the largest substrate volumes, with German and Chinese printing clusters feeding regional manufacturing hubs. Water-based gravure and UV digital systems compete for specification based on run length and emission compliance.
- Furniture Surfaces:Melamine-faced decorative papers and direct-to-substrate digital printing serve residential and commercial furniture builders. Short-run customization demand fragments order patterns away from mass retail chains.
- Wallcoverings:Digital printing on nonwoven backings opens hospitality and healthcare specification channels previously served by coated papers.
- Textile Decoration:Sublimation and digital inkjet capture apparel and home furnishing applications with design refresh cycles compressing from seasons to weeks.
- Packaging Design:Premium brand differentiation drives flexographic and digital investment in folding carton and label decoration.
- Automotive Interiors:Seating and panel surfacing demands UV-stable, abrasion-resistant imaging for vehicle upholstery makers in Germany and the United States.
Flooring commands the deepest converter commitment; wallcoverings are climbing the fastest as digital sample programs compress specification cycles.
Material Type:
Substrate selection dictates ink chemistry, drying systems, and lamination requirements that lock converters into specific technology platforms.
- Paper:Decorative papers for flooring laminates and furniture surfacing represent the highest volume substrate category. Ahlstrom-Munksjö and comparable technical paper suppliers control fiber-based receptive layer supply chains.
- Vinyl:Wallcovering and flooring applications favor PVC and bio-based alternatives with print-receptive topcoats enabling direct digital decoration.
- Fabric:Woven and nonwoven textile backings for hospitality interiors require specialized priming systems before digital inkjet imaging.
- Glass:Architectural and decorative glass decoration relies on screen printing for ink deposit thickness and firing durability.
- Metal:Appliance and signage applications favor UV-cured systems on aluminum and steel substrates.
- Ceramic:Tile decoration persists as a screen printing stronghold where pigment fusion determines wear resistance.
Paper dominates current substrate throughput; vinyl is gaining share fastest as wallcovering textile hybridization accelerates.
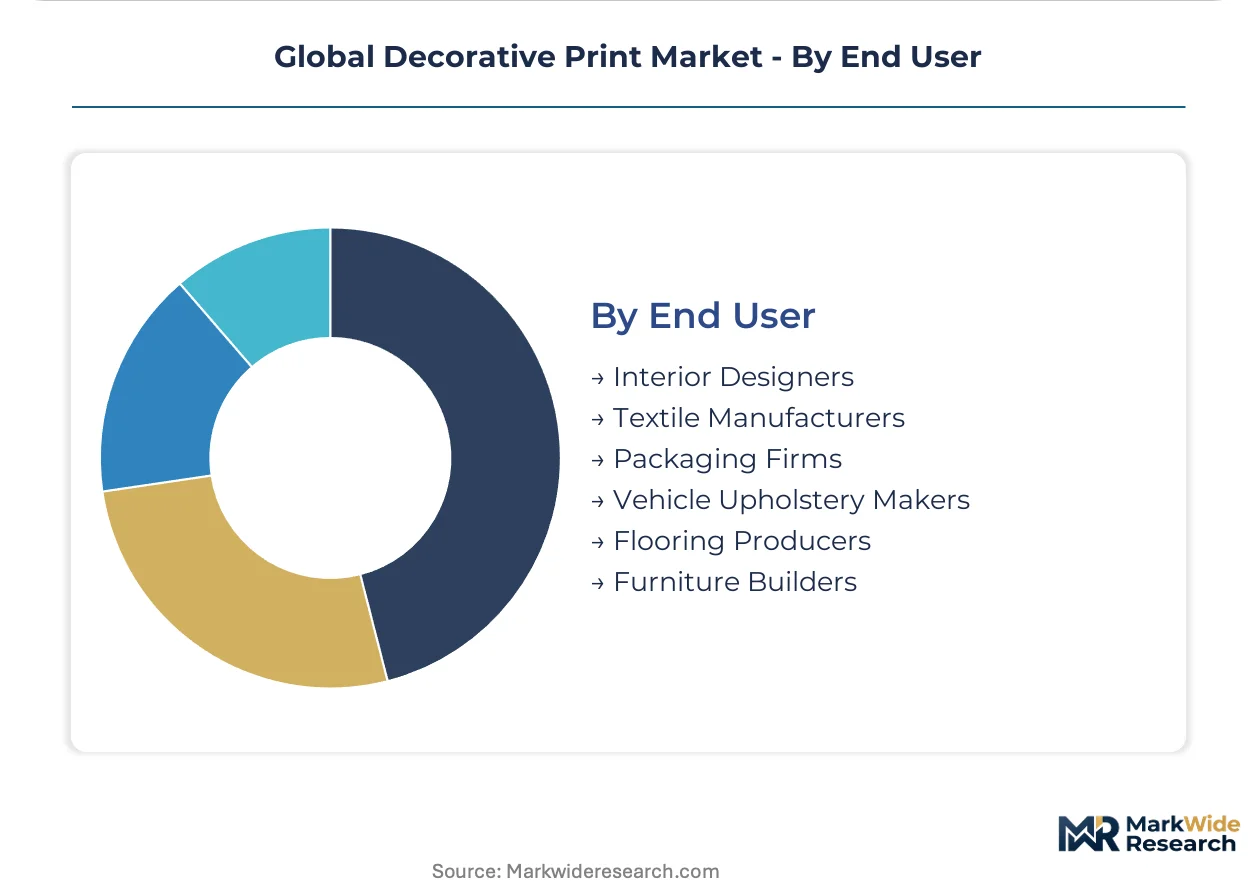
End User:
Customer fragmentation between mass manufacturers and bespoke builders reshapes converter service models and margin capture.
- Flooring Producers:Large-format laminate and LVT manufacturers in Germany and the United States drive gravure volume with cylinder-based consistency requirements.
- Furniture Builders:Residential and commercial manufacturers source decorative papers and direct-print panels, with custom builders fragmenting demand toward digital job shops.
- Interior Designers:Project-specific specification bypasses traditional distribution, pulling volume toward digital sample programs and short-run production.
- Textile Manufacturers:Apparel and home furnishing converters sublimate or digitally print polyester and cotton blends for retail brand customers.
- Packaging Firms:Folding carton and label printers serve consumer goods brands with premium decoration requirements.
- Vehicle Upholstery Makers:Automotive tier suppliers in Germany and the United States demand UV-stable imaging for seating and interior panel programs.
Flooring producers anchor converter volume; interior designers are expanding fastest as direct digital channels disintermediate traditional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States, where large-format printing clusters serve regional furniture and flooring manufacturing hubs. Interior designers and custom furniture builders are fragmenting order patterns across all three markets. Regulatory pressure on volatile organic compound emissions is accelerating facility upgrades in each concentration zone.
United States
Flooring manufacturers in Tennessee and North Carolina drive gravure volume for laminate and vinyl plank surfacing. EPA hazardous air pollutant regulations constrain solvent-based flexography adoption, redirecting investment toward water-based alternatives. California and Northeast state implementation plans accelerate compliance timelines beyond federal minimums.
Germany
Technical paper suppliers and cylinder engraving infrastructure anchor European decorative print supply chains. REACH compliance and EU Green Deal mandates on VOC emissions push converters toward water-based gravure and UV-cured digital systems. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate gravure capacity for flooring laminators.
China
Zhejiang and Guangdong province printing clusters supply domestic furniture builders and export-oriented flooring producers. MEE enforcement of emission controls redirects investment toward compliant water-based and energy-curable systems. Shanghai and Shenzhen hubs are expanding digital press installations for short-run customization demand.
India
Domestic furniture manufacturing growth under PLI scheme incentives creates unmet demand for decorative surfacing substrates. BIS standards on laminate flooring and panel products shape substrate specification requirements. Industrial corridors in Gujarat and Tamil Nadu are attracting converter investment for regional supply.
Japan
Automotive interior panel and seating surfacing demands UV-stable, abrasion-resistant imaging from vehicle upholstery makers. METI guidelines on chemical substance management influence ink formulation choices among converters. Industrial concentration in Aichi Prefecture around Nagoya anchors automotive-tier supplier networks.
Global Decorative Print Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digitally enabled short-run segments and hybrid substrate applications. The market structures around three tiers: cylinder-gravure specialists serving mass-market flooring runs, digital-native job shops capturing fragmented interior designer demand, and integrated technical paper suppliers controlling substrate supply chains. Consolidation pressure concentrates among gravure cylinder engraving capacity holders, while digital press vendors fragment across regional job shop networks. Strategic moves center on M&A for cylinder engraving assets and partnerships between ink suppliers and digital press OEMs.
Within the gravure-specialist tier, Schattdecor AG and Surteco Group SE exemplify established European producers with integrated surface solution portfolios. Ahlstrom-Munksjö Oyj occupies a position among fiber-based substrate specialists controlling technical paper supply chains for print-receptive layers. These three entities represent distinct archetypes: the full-service surface solutions provider, the gravure-anchored laminate supplier, and the upstream substrate controller.
| Leading Market Players |
|---|
| Schattdecor AG |
| Surteco Group SE |
| Ahlstrom-Munksjö Oyj |
| Felix Schoeller Group |
| Interprint GmbH |
| Impress Surfaces GmbH |
| ITC Limited |
| Stora Enso Oyj |
| Papierfabrik August Koehler SE |
| Others |
Supply & Pricing Matrix
Single-pass UV inkjet press adoption across German and Chinese converting clusters is compressing per-unit production economics while concentrating supply power among digital press OEMs and specialized ink formulators. This technology transition simultaneously erodes gravure cylinder amortization advantages and elevates consumables pricing leverage for compliant water-based and energy-curable chemistry suppliers.
Pricing Analysis
High-volume flooring runs trade margin for throughput while specification-driven wallcovering and furniture surfacing commands premium capture. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under REACH and EPA hazardous air pollutant frameworks. Pricing pressure stems from titanium dioxide and acrylic resin input volatility constraining converter margin predictability. Mass-market flooring producers exhibit highest price sensitivity; hospitality and healthcare specification buyers prioritize emission compliance and design flexibility over unit cost.
Supply Chain Analysis
Skilled cylinder engraving technicians and ICC profiling specialists concentrate in Bavaria and Aichi Prefecture, constraining gravure capacity expansion and digital press utilization rates. Raw material flows draw from German technical paper suppliers, Japanese cylinder engraving infrastructure, and Chinese ink chemistry manufacturers. Single-source vulnerability runs through the narrow base of engraved cylinder suppliers in Germany and Japan. Distribution feeds from large-format printing clusters through regional laminate manufacturers to flooring and furniture assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into substrate production and captive ink formulation capabilities is accelerating as converters defend margin erosion from input volatility and regulatory compliance costs. Players securing upstream control over technical paper supply chains and specialized chemistry access will outcompete pure-play decorators.
For Market Incumbents: Deepen cylinder engraving asset consolidation to defend high-volume flooring positions against digital press vendors capturing specification-driven segments. Prioritize water-based gravure retrofit investments ahead of EU Green Deal VOC enforcement timelines. Secure long-term titanium dioxide supply agreements to buffer pigment cost volatility.
For New Entrants and Emerging Players: Capture wallcovering textile hybridization opportunities in hospitality and healthcare interiors where digital sample programs disintermediate traditional distribution. Target interior designer direct channels in United States and United Kingdom markets with short-run customization capabilities. Deploy direct digital sampling as primary go-to-market mechanism to compress specification cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in cylinder engraving specialists and technical paper substrate controllers with certified low-emission production assets. Long-term viability favors integrated surface solution providers spanning substrate supply through decoration execution. Monitor CSRD supply chain disclosure adoption rates as signal for premium capture differentiation in European specification markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Paper Production | Captures margin from Ahlstrom-Munksjö-dominated substrate supply chains for flooring laminators. |
| Digital Press Fleet Expansion | Positions converters to serve fragmented interior designer demand bypassing mass retail procurement. |
| Water-Based Ink Formulation Partnership | Secures REACH and EPA compliant chemistry access ahead of VOC mandate enforcement deadlines. |
| Cylinder Engraving Asset Acquisition | Consolidates scarce German and Japanese capacity serving high-volume flooring manufacturers. |
| Direct Digital Sampling Program Launch | Compresses specification cycles from months to weeks for hospitality and healthcare verticals. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with gravure cylinder engraving specialists, digital press OEM technical directors, flooring manufacturer procurement leads, and interior designer specification consultants provided operational validation. ECHA REACH registration databases, EPA hazardous air pollutant compliance records, China MEE emission control disclosures, and EU Green Deal implementation timelines supplied regulatory trajectory inputs. Bottom-up converter capacity assessments triangulated against top-down substrate demand modeling from furniture and flooring manufacturing clusters.
Granularity-level modeling deployed technology-platform splits by run-length economics, application-specific ink chemistry requirements, and regional regulatory compliance tiers across the analysis window. Segmentation dimensions included printing technology, substrate material type, end-use application, and geographic production hub concentration. CAGRs derived from installed capacity growth rates, technology substitution curves, and regulatory compliance investment cycles. Forecast inputs incorporated gravure cylinder replacement cycles, digital press retrofit economics, and VOC mandate enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pigment and resin supply disruptions, regulatory enforcement acceleration, and digital press technology cost trajectories. Forecasts reflect documented assumptions regarding technology substitution elasticities and compliance investment lag structures. Material deviation in titanium dioxide supply availability, cylinder engraving capacity expansion, or EU Green Deal VOC ceiling revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Squid Ink Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Security Printing Market
Printing Inks
Zink Printing Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Ink Resins Market
Printing Inks
Waterborne Ink Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Textile Printing Ink Market