
 Refractories Market | 2026-2036
Refractories Market Size, Share, and Industry Trends Forecast 2026-2036
Refractories Market Analysis
Digital twin modeling of thermal wear patterns is rewriting how furnace operators schedule refractory replacement cycles. RHI Magnesita leverages its vertical integration from raw magnesite mining to finished brick production across Austrian and Chinese operations. Vesuvius anchors its competitiveness in advanced flow control systems for continuous steel casting, while Imerys specializes in high-alumina solutions for cement kiln applications.
Refractories are non-metallic materials engineered to withstand temperatures above 1,000°C, typically composed of alumina, silica, magnesia, or clay bonded with ceramic or chemical matrices, and manufactured through firing, casting, or gunning processes to protect industrial vessels from thermal, chemical, and mechanical degradation. Monolithic and unshaped formulations now capture expanding share as plant operators favor gunnable and castable installations that reduce downtime versus traditional bricklaying. Steel end-use demand dominates volume, though glass and non-ferrous segments offer higher margin pools where custom precast shapes command premium positioning.
EPA regulations in the US tighten allowable emissions from metallurgical processes, directly accelerating demand for longer-lasting linings that minimize furnace rebuild frequency. REACH and the EU Green Deal in Europe impose stricter chemical disclosure and carbon accounting on refractory producers, reshaping material sourcing toward recycled and lower-carbon feedstocks. China's MEE enforces dual carbon compliance targets that push domestic steelmakers toward energy-efficient furnace designs with advanced refractory insulation. Stakeholders must track how carbon border adjustments and evolving kiln efficiency standards redirect procurement criteria across major steel-producing jurisdictions.
Market Dynamics
Steel decarbonization mandates are compressing furnace rebuild cycles and forcing refractory specification upgrades across integrated mills and electric arc operators worldwide.
Growth Catalysts
- EPA metallurgical emissions caps:US steelmakers face tighter particulate and NOx limits, requiring magnesia-carbon linings with extended campaign life to reduce maintenance shutdown frequency.
- Electric arc furnace conversion:Scrap-based steelmaking expands across Germany, Japan, and Brazil, generating demand for high-thermal-shock dolomite and magnesia spinel formulations.
- China's dual carbon enforcement:MEE compliance deadlines push domestic producers toward energy-efficient kiln insulation and advanced refractory layers that cut fuel consumption per ton of steel.
Market Restraints
- Fused magnesia supply concentration:Chinese producers control over 70% of high-purity dead-burned magnesia output, creating price volatility exposure for European brick manufacturers.
- REACH chemical disclosure burden:ECHA registration requirements for chrome-bearing and resin-bonded formulations add compliance costs and formulation reformulation timelines.
- Ceramic fiber substitution:Bio-soluble alkaline earth silicate wools displace traditional aluminosilicate insulation in sub-1200°C applications, eroding volume in non-critical zones.
Strategic Opportunities
- India's secondary steel expansion:Mini-mill capacity additions in Raipur, Indore, and Bellary create demand for gunnable monolithics and precast tundish furniture.
- Hydrogen-ready furnace retrofits:H2-DRI shaft kilns and hydrogen-fired reheat furnaces require new lining chemistries resistant to reducing atmospheres and water vapor attack.
- Refractory recycling mandates:EU Green Deal circular economy targets incentivize spent magnesia-carbon brick recovery and synthetic aggregate reprocessing.
Industry Challenges
- Refractory engineering talent scarcity:Ceramic materials science programs contract across Western universities while experienced furnace lining designers retire.
- Digital twin integration complexity:Legacy heat management systems resist API connectivity with new thermal wear prediction platforms, delaying predictive maintenance deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refractories Market |
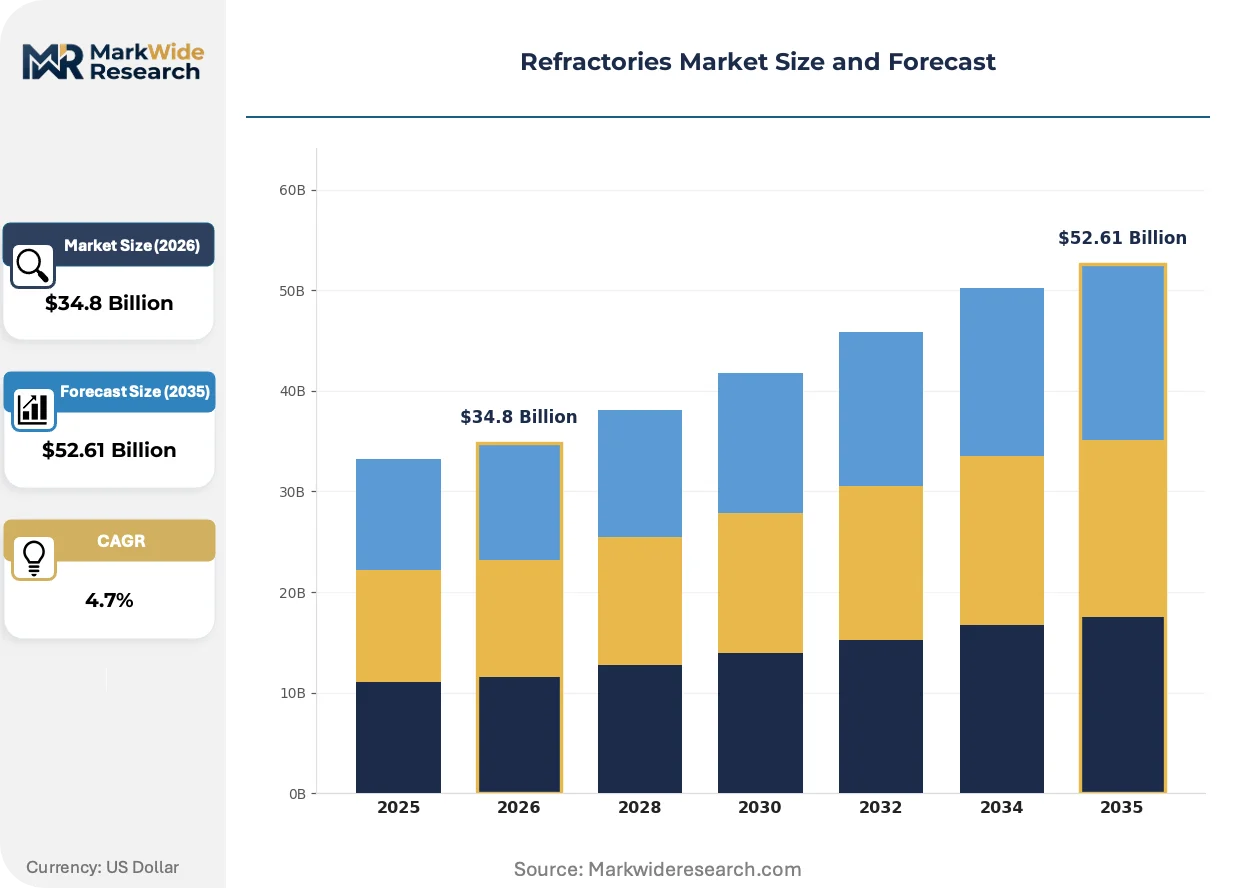
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $52.61 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
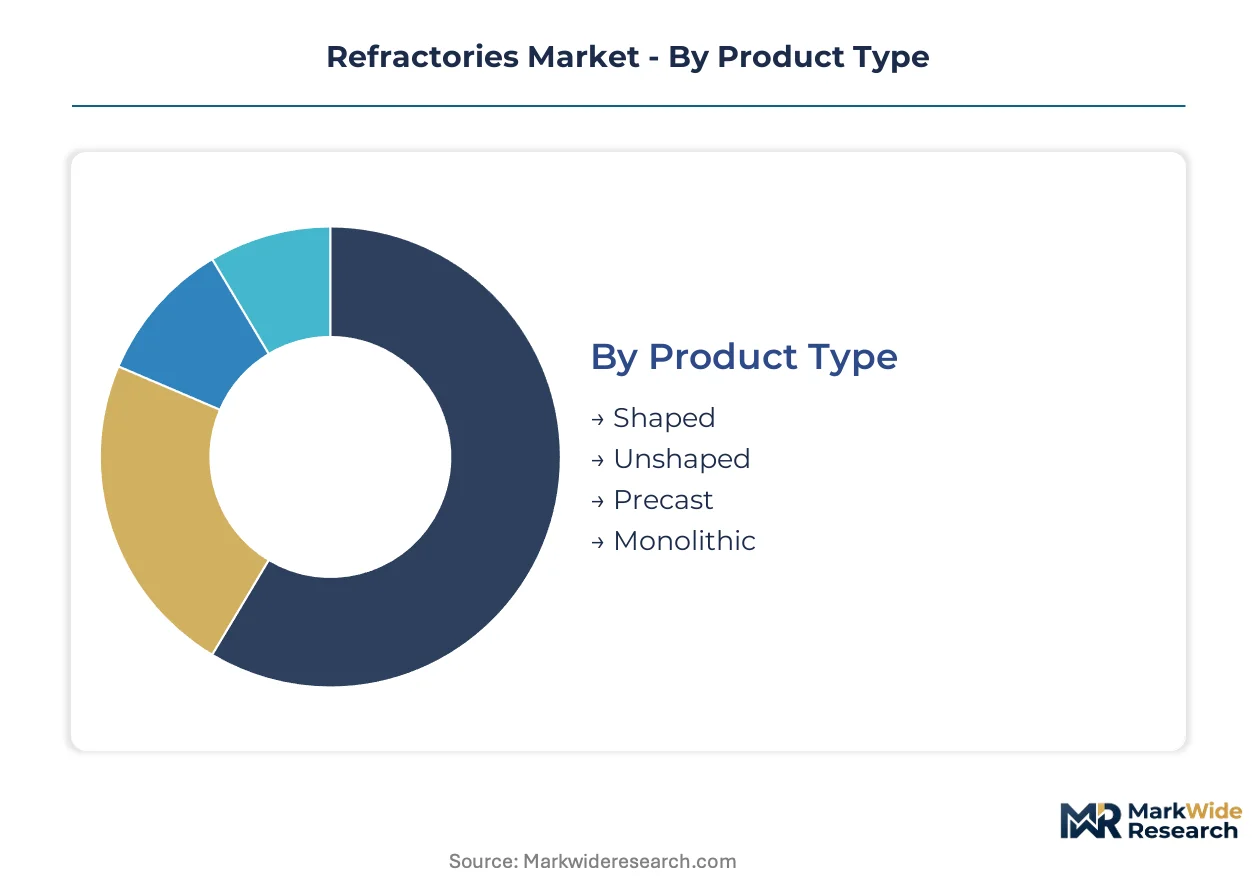
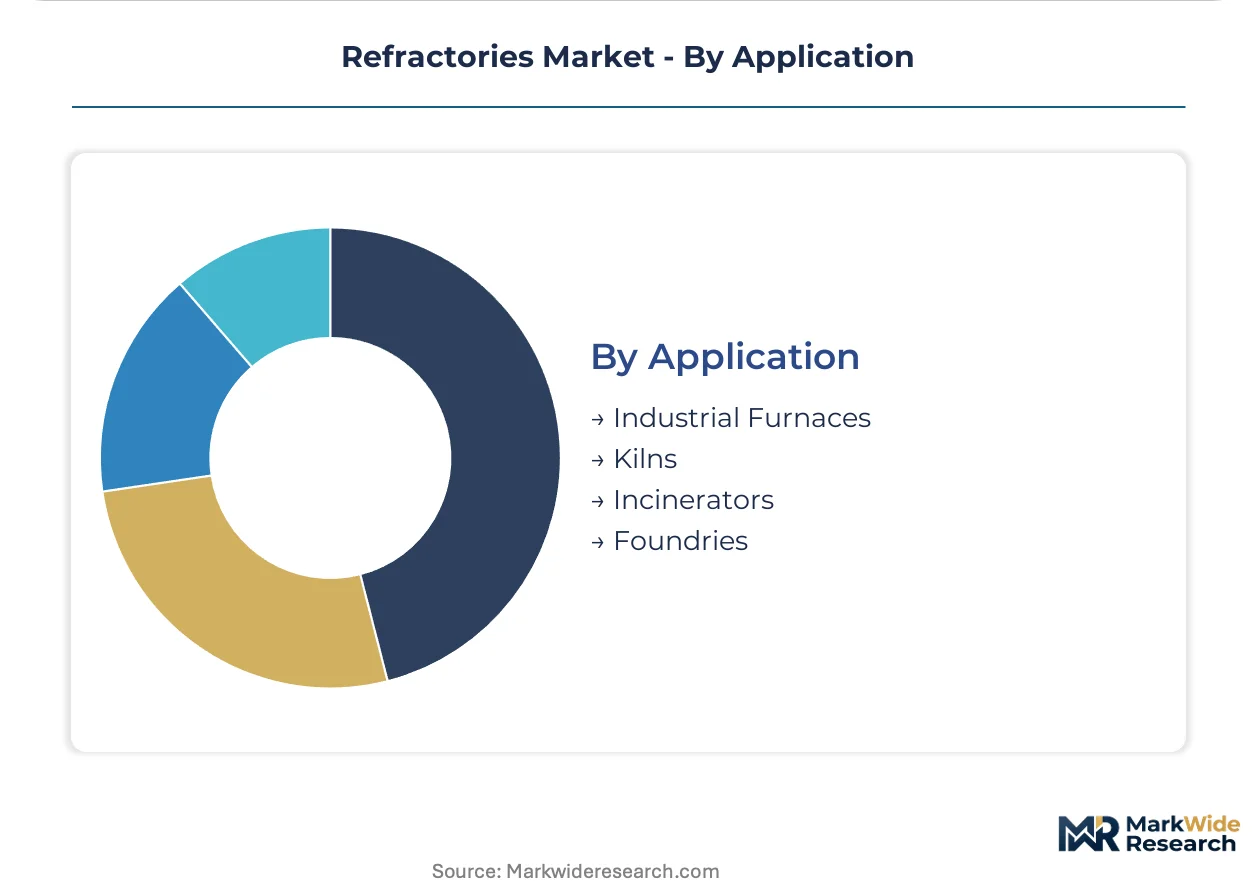
| Segmentation | Product Type: Shaped, Unshaped, Precast, Monolithic End User: Cement, Glass, Steel, Non-Ferrous Material: Clay, Silica, Magnesia, Alumina Application: Industrial Furnaces, Kilns, Incinerators, Foundries |
| Companies Covered | RHI Magnesita, Vesuvius, Krosaki Harima Corporation, Shinagawa Refractories Co., Ltd., Saint-Gobain, Imerys, HarbisonWalker International, Morgan Advanced Materials, Chosun Refractories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refractories Market Emerging Trajectories
Digitalization of thermal asset management and low-carbon feedstock sourcing are restructuring how refractory value is captured and delivered.
AI-driven thermal wear prediction is collapsing traditional preventive maintenance schedules into condition-based replacement protocols. Integrated steel mills in South Korea and Finland deploy sensor arrays that map hot spot evolution in real time. This compression of uncertainty intervals is collapsing inventory holding requirements and emergency procurement premiums.
REACH and the EU Green Deal are forcing carbon footprint disclosure across refractory supply chains. ECHA's SCIP database mandates traceability for chrome and zircon-containing articles entering European markets. German and Italian cement kiln operators now require Environmental Product Declarations as standard bid prerequisites.
Buyer consolidation among multinational steel groups is compressing supplier rosters and lengthening contract tenors. ArcelorMittal and Nippon Steel now centralize refractory procurement through multi-year framework agreements covering multiple plant sites. This concentration is most visible in Western Europe and Japan, where three-buyer clusters account for majority regional volume.
Refractories Market Segmentation
Refractory procurement patterns diverge sharply across product forms and end-use intensities, with furnace rebuild cycles and installation labor costs driving specification choices. Steelmakers prioritize campaign life extension, while cement and glass operators balance thermal efficiency against capital constraints.
Product Type:
After-sales service intensity varies dramatically: brick installations demand specialized mason crews and lengthy cooldown periods, while monolithic gunning permits rapid patch repairs during brief maintenance windows.
- Shaped:Fired bricks and blocks with precise dimensional tolerances suit permanent furnace linings where structural integrity under mechanical load is critical. Demand concentrates in blast furnace hearths and BOF vessels across integrated steel mills in India and Germany, constrained by skilled installation labor scarcity.
- Unshaped:Dry or wet-mix formulations including ramming masses and plastic mixes adapt to irregular geometries without custom mold fabrication. Electric arc furnace operators in Brazil and Japan favor these for delta section repairs where thermal shock resistance governs specification.
- Precast:Factory-cured shapes reduce field curing time and quality variability. Cement kiln nose rings and ladle well blocks deploy these for critical wear zones requiring consistent properties.
- Monolithic:Castables and gunnables dominate new construction and maintenance cycles where installation speed outweighs material cost premiums. Mini-mill expansions in Raipur and Indore drive volume for tundish linings and ladle walls.
By volume, Monolithic leads. By growth pace, Precast is ahead.
End User:
Cost tier stratification separates commodity steel specifications from premium non-ferrous and glass applications where custom engineering commands margin premiums.
- Steel:Integrated mills and electric arc operators consume the majority of magnesia-carbon and alumina-silicate linings for converters, ladles, and tundishes. EPA emissions caps and China's MEE enforcement compress rebuild cycles and force specification upgrades.
- Cement:Rotary kiln burning zones and preheater towers require alkali-resistant and thermal-shock-tolerant formulations. German and Italian operators now mandate Environmental Product Declarations as standard bid prerequisites under EU Green Deal pressure.
- Glass:Regenerator checkers and furnace crowns demand high-purity zircon and alumina-zirconia-silica refractories with extreme creep resistance. Container and float glass producers in Japan and South Korea specify these for 10-15 year campaign targets.
- Non-Ferrous:Copper smelting converters and aluminum holding furnaces utilize chrome-magnesite and fused-cast alumina blocks resistant to slag penetration and metal attack. Custom precast shapes for these applications capture premium positioning.
Steel dominates absolute volume. Non-ferrous and glass segments yield superior margins per ton.
Material:
Supply concentration for high-purity dead-burned magnesia creates price volatility exposure that reshapes procurement strategies across formulation categories.
- Clay:Fireclay and high-alumina fireclay refractories serve lower-temperature applications including boiler linings and ceramic kiln furniture. Cost sensitivity in these segments limits specification flexibility.
- Silica:High-silica formulations excel in coke oven walls and glass furnace crowns where thermal expansion matching and creep resistance are paramount. Scarcity of super-duty silica rock constrains supply security.
- Magnesia:Dead-burned and fused magnesia provide the backbone of steelmaking refractories, from BOF and EAF linings to secondary metallurgy vessels. Chinese producers control over 70% of high-purity output, amplifying price risk for European brick manufacturers.
- Alumina:Tabular and white fused alumina anchor high-performance castables and precast shapes for cement and petrochemical applications. Bauxite sourcing diversification toward Guinea and Australia reduces concentration risk.
Magnesia commands the largest share. Alumina formulations are expanding most quickly into hydrogen-ready furnace retrofits.
Application:
Customer type segmentation separates original equipment furnace builders from maintenance contractors and plant operators with divergent technical capabilities and procurement authority.
- Industrial Furnaces:Steel reheat furnaces, heat treatment chambers, and aluminum melting furnaces require linings balancing thermal efficiency against mechanical durability. Hydrogen-fired retrofits demand new chemistries resistant to reducing atmospheres.
- Kilns:Cement rotary kilns and lime kilns represent the most intensive wear environments, with coating formation and thermal cycling driving magnesia-spinel and dolomite specification. India's clinker capacity additions sustain demand.
- Incinerators:Municipal and hazardous waste units face corrosive flue gas chemistries and thermal shock from batch feeding. Chrome-alumina and SiC-based formulations address these aggressive conditions.
- Foundries:Iron and steel foundry cupolas, induction furnaces, and pouring ladles utilize alumina-silicate and magnesia-carbon refractories where metal contact and slag erosion dominate wear mechanisms.
Kilns lead by installed base. Industrial furnaces show the steepest specification upgrade trajectory amid decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape regional refractory flows, with Chinese magnesia shipments dominating raw material trade while finished brick and monolithic formulations move from European and Japanese producers toward steelmaking centers in India and Southeast Asia.
China
Domestic steel output exceeding one billion tons annually sustains massive internal consumption of magnesia-carbon linings for converters and ladles. MEE enforcement of dual carbon targets accelerates kiln efficiency retrofits requiring advanced insulation layers. Liaoning Province hosts the concentrated dead-burned magnesia mining and processing complex that supplies both domestic brick plants and export markets.
United States
Electric arc furnace operators in Indiana, Ohio, and Alabama drive demand for high-thermal-shock dolomite formulations as scrap-based steelmaking expands. EPA metallurgical emissions caps tighten allowable particulate limits, forcing specification upgrades toward longer-campaign magnesia-carbon grades. The Great Lakes industrial corridor maintains dense clusters of integrated mill maintenance contractors with specialized gunning capabilities.
India
Secondary steel capacity additions in Raipur, Indore, and Bellary create sustained pull for gunnable monolithics and precast tundish furniture. BIS quality standards for refractory products tighten import certification requirements for Chinese and European suppliers. The Chhattisgarh-Jharkhand steel belt represents the fastest-growing regional consumption cluster as mini-mill investments accelerate.
Germany
Thyssenkrupp and Salzgitter furnace rebuild cycles sustain premium demand for magnesia-spinel and alumina-silicate formulations with extended service life. REACH chemical disclosure requirements and the EU Green Deal carbon accounting rules reshape procurement toward recycled feedstocks and EPD-certified suppliers. The Ruhr industrial region and Lower Saxony steel corridor concentrate specification-intensive demand.
Japan
Nippon Steel and JFE Holdings centralize refractory procurement through multi-year framework agreements covering multiple plant sites. METI energy efficiency standards for industrial furnaces push specification upgrades toward advanced insulation systems. The Chubu and Kansai manufacturing belts host sophisticated maintenance contractor networks with digital thermal monitoring capabilities.
Refractories Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated magnesia producers and specialized formulation houses with distinct technical capabilities. Tier-one positions cluster among Austrian, Belgian, and Japanese groups with captive raw material access and furnace engineering service bundling. Mid-scale regional fabricators compete on installation speed and maintenance responsiveness. Dominant competitive moves include backward integration into magnesite mining and strategic partnerships with steel mill operators for multi-year supply frameworks.
Among the named European and Japanese groups, RHI Magnesita and Vesuvius exemplify contrasting strategic positions—one anchored in upstream raw material control, the other in advanced flow control systems for continuous casting. Imerys occupies a specialty position in high-alumina solutions. These three represent the archetype spectrum spanning integrated resource-backed supply, process-technology specialization, and application-specific formulation expertise.
| Leading Market Players |
|---|
| RHI Magnesita |
| Vesuvius |
| Krosaki Harima Corporation |
| Shinagawa Refractories Co., Ltd. |
| Saint-Gobain |
| Imerys |
| HarbisonWalker International |
| Morgan Advanced Materials |
| Chosun Refractories |
| Others |
Supply Flow & Price Mechanics
Liaoning Province's concentrated dead-burned magnesia mining complex supplies over two-thirds of global high-purity refractory feedstock, amplifying Chinese producers' pricing leverage over European brick manufacturers and Japanese steel mill operators. This geographic chokepoint forces downstream buyers into long-term offtake contracts or spot market exposure, with MEE enforcement tightening domestic supply availability.
Pricing Analysis
Conventional magnesia-carbon formulations trade at substantial discounts to next-generation hydrogen-ready lining chemistries and AI-optimized precast shapes. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified European suppliers from Chinese commodity producers and regional fabricators. Pricing pressure stems from REACH compliance costs and raw material volatility, with integrated steel mills showing lowest price sensitivity due to campaign life prioritization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for magnesia-dependent refractory producers. Raw material sourcing draws from Liaoning Province, Australian bauxite deposits, and Brazilian dolomite reserves, with fused magnesia and tabular alumina anchoring formulation costs. Single-source vulnerability concentrates in Chinese dead-burned magnesia output. Distribution runs through regional maintenance contractor networks and direct mill supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refractory procurement fragmentation creates niche opportunities as steel decarbonization mandates splinter specification requirements across hydrogen-ready, EAF-optimized, and legacy blast furnace segments.
For Market Incumbents: Harden supply security through backward integration into magnesite mining or captive recycling facilities, addressing Chinese supply concentration risk. Deepen furnace engineering service bundling to lock in multi-year framework agreements with ArcelorMittal-scale buyers, defending against specialized flow control competitors. For New Entrants and Emerging Players: Establish a beachhead in India's secondary steel corridor, where mini-mill capacity additions outpace established supplier coverage. Target gunnable monolithic formulations for Raipur and Bellary operators, leveraging faster installation turnaround versus brick-based competitors as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital-thermal-asset specialists with AI-driven wear prediction capabilities over conventional formulation houses. Five-to-ten year viability hinges on hydrogen furnace retrofit exposure and circular economy compliance infrastructure. Watch for EU carbon border adjustment implementation as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesite Mining | Liaoning supply concentration demands captive raw material security for margin stability. |
| Digital Twin Platform Deployment | RHI Magnesita and Vesuvius compete on thermal wear prediction API integration. |
| Hydrogen-Ready Lining Chemistry Development | H2-DRI shaft kilns require new formulations resistant to reducing atmospheres. |
| Spent Refractory Recycling Infrastructure | EU Green Deal circular economy targets incentivize magnesia-carbon brick recovery. |
| Multi-Year Steel Mill Framework Agreements | Nippon Steel procurement centralization compresses supplier rosters and extends contract tenors. |
Methodological Framework
Operator-level perspectives from furnace maintenance directors, steel mill procurement leads, refractory R&D chemists, and EPC contractors anchored the qualitative base for this study. Primary fieldwork combined with secondary validation from SEC filings, trade customs databases, ECHA registration disclosures, and EU EPD certification records. Bottom-up demand modeling across steel, cement, glass, and non-ferrous end-uses triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation dimensions spanning product form, material chemistry, end-use intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating steel production forecasts, kiln efficiency retrofit pipelines, and carbon accounting implementation timelines. Hydrogen furnace technology readiness and circular economy mandate enforcement served as key sensitivity inputs.
Sensitivities concentrate around Chinese environmental policy enforcement, EU carbon border adjustment timing, and electric arc furnace conversion pace across major steel-producing jurisdictions. Forecasts reflect documented assumptions on raw material price trajectories and regulatory implementation schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
China Clay Market
Ceramics
US Kaolin Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Ceramic Kilns Market
Ceramics
Technical Ceramics Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
India Kaolin Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Ceramic Proppant Market
Ceramics
Industrial Ceramics Market
Ceramics
Dielectric Ceramics Market
Ceramics
Automotive Ceramics Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
2N High Purity Alumina Market