
 Rubber Flooring Market | 2026-2036
Rubber Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Flooring Market Outlook
A shift from single-source to multi-source raw material procurement is restructuring supply economics for rubber flooring manufacturers. Nora Systems leverages captive polymer compounding capabilities to sustain margin control across premium sheet lines. Tarkett competes through broad distribution reach in European healthcare and education channels. Forbo Flooring Systems anchors its position with specialized linoleum-rubber hybrid formulations that navigate sustainability specifications.
Rubber flooring comprises elastomer-based surfacing materials, typically formulated from natural rubber, synthetic SBR, or EPDM polymers bonded with vulcanizing agents and compressed at pressures exceeding 500 psi to achieve density ratings above 1,400 kg/m³. Its primary commercial purpose centers on impact absorption, slip resistance, and acoustic dampening in high-traffic environments. Sheet rubber dominates healthcare and laboratory installations where seamless hygiene barriers command premium positioning, while interlocking tiles capture fastest growth in DIY residential and temporary commercial deployments due to reduced installation labor. Sports facilities represent a concentrated margin pool for high-profile extruded systems with point-elasticity certifications.
EMA's Medical Device Regulation and REACH chemical restrictions in Europe, alongside OSHA slip-resistance mandates and ADA accessibility standards in the United States, shape product certification requirements and market access barriers. These frameworks elevate testing costs for entrants while rewarding incumbent manufacturers with established compliance infrastructure. Stakeholders must monitor evolving PFAS restrictions and bio-based content thresholds as specification criteria in public procurement programs tighten without grandfathering existing installations.
Market Dynamics
REACH chemical restrictions and RoHS compliance mandates in Europe are forcing wholesale reformulation of rubber flooring compounds, eliminating phthalate-based plasticizers and accelerating bio-based binder adoption across manufacturing footprints.
Growth Catalysts
- Healthcare Infrastructure Modernization:Hospital renovation programs in Germany specify seamless sheet rubber for infection control barriers. Surgical suites and patient corridors drive specification upgrades.
- REACH Phthalate Bans:ECHA restrictions on ortho-phthalates accelerate migration to bio-based plasticizers and non-vulcanized polymer systems. Compliance deadlines compress formulation timelines.
- EPDM Polymer Performance:Ethylene propylene diene monomer compounds deliver superior UV stability and chemical resistance for laboratory and pharmaceutical manufacturing environments.
Market Restraints
- Petrochemical Feedstock Volatility:Styrene-butadiene rubber and EPDM prices track naphtha and ethylene propylene monomer markets. Energy-intensive vulcanization compounds input cost exposure.
- East Asian Supply Concentration:Synthetic rubber polymer production clusters in China and South Korea create geographic dependency for European and North American compounders.
- Luxury Vinyl Tile Substitution:LVT with enhanced acoustic underlayment captures budget-sensitive healthcare and education projects. Lower installed cost pressures rubber flooring specification rates.
Strategic Opportunities
- Indian Healthcare Expansion:Ayushman Bharat hospital construction targets 150,000 health and wellness centers. CDSCO medical device facility standards create specification entry points for antimicrobial flooring.
- Sports Performance Certification:DIN 18032-2 and EN 14904 point-elasticity standards for indoor athletics open margin-rich extruded system contracts. Olympic training facilities and professional arenas drive premium positioning.
- Digital Specification Platforms:Building information modeling integration allows real-time acoustic and slip-resistance simulation. Architects and contractors reduce sampling cycles through virtual product selection.
Industry Challenges
- Polymer Compounding Expertise Scarcity:Formulation chemists with vulcanization kinetics and filler dispersion knowledge retire faster than training programs replace them.
- Multi-Jurisdiction Certification Overlap:simultaneous EMA Medical Device Regulation, REACH SVHC screening, and OSHA slip-resistance testing extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Flooring Market |
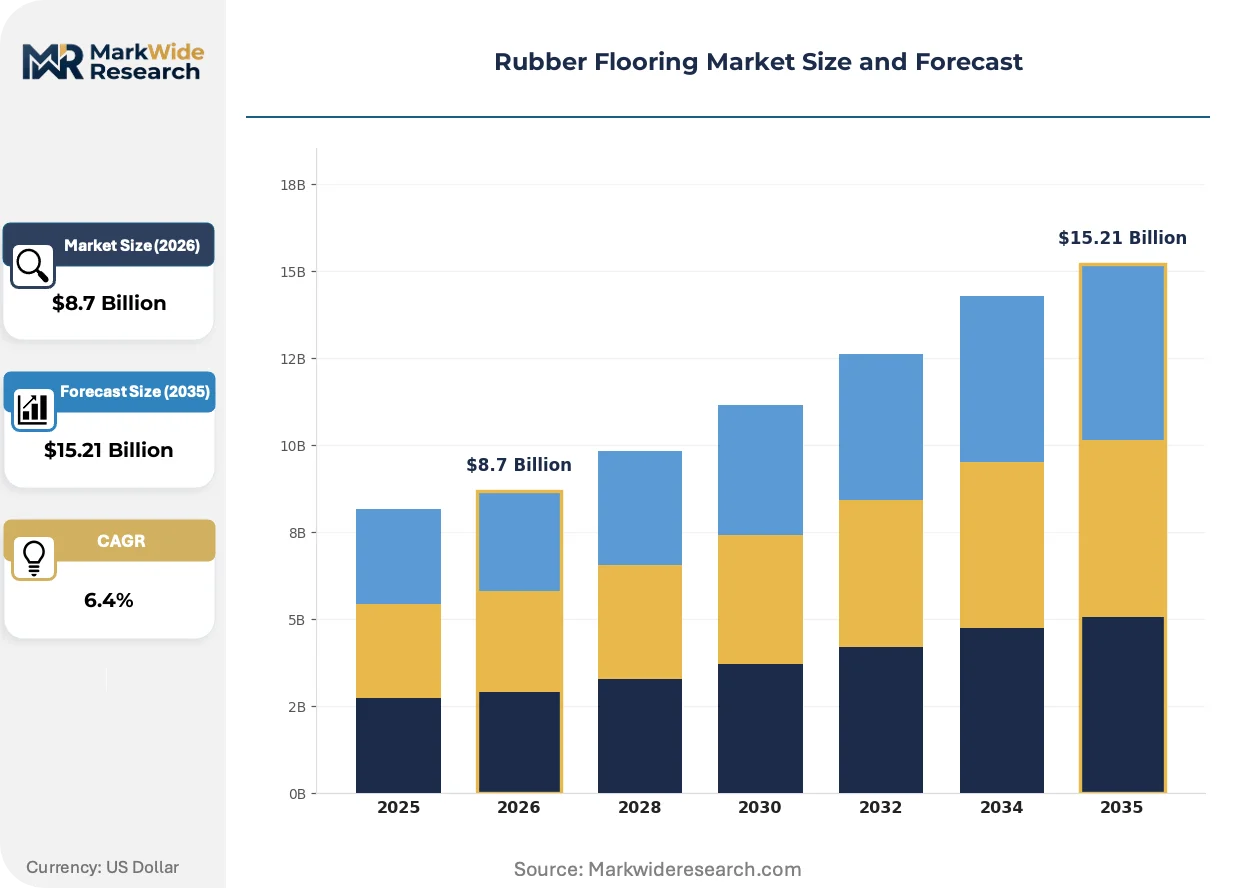
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Tiles, Rolls, Interlocking End User: Residential, Commercial, Industrial, Sports Facilities Thickness: Low-profile, Medium-profile, High-profile, Extruded Texture: Smooth, Textured, Studded, Patterned |
| Companies Covered | Gerflor, Nora Systems, Tarkett, Roppe Corporation, LG Hausys, Shaw Industries, Forbo Flooring Systems, Armstrong Flooring, Mannington Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Flooring Market Strategic Shifts
Digital manufacturing and bio-based chemistry are restructuring how rubber flooring compounds are formulated, produced, and specified. These shifts compress development cycles while elevating performance verification requirements.
Water-based polyurethane binders are consolidating position in sheet and tile production, replacing solvent-based systems that face VOC emission restrictions. German hospital networks and Dutch laboratory builders specify these compounds for indoor air quality compliance. The technology is consolidating market share among premium sheet manufacturers who invested in aqueous dispersion capabilities before regulatory deadlines.
EU Green Deal taxonomy alignment and CSRD reporting mandates now require embodied carbon disclosure for construction materials procured with public funds. Rubber flooring manufacturers must document cradle-to-gate emissions through third-party verified EPDs. Healthcare and education sectors in France, Belgium, and the Netherlands are rejecting products without standardized environmental declarations.
Direct-to-contractor digital sampling and specification platforms are compressing traditional distributor-led sales cycles. Commercial flooring contractors in the United Kingdom and Ireland now expect same-day acoustic performance data and virtual mockup generation. This channel shift disadvantages manufacturers dependent on legacy rep networks for technical consultation and project specification.
Rubber Flooring Market Segmentation
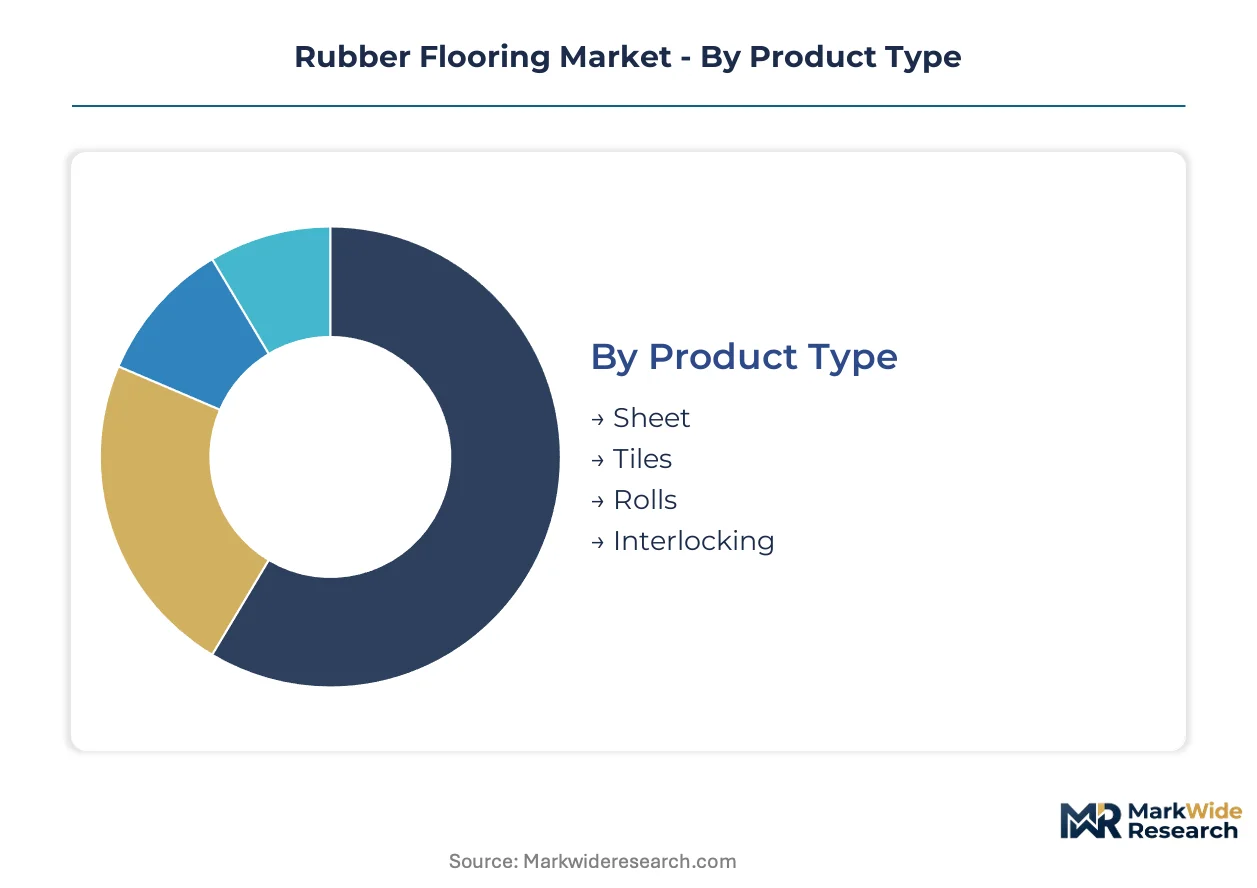
Rubber flooring specifications diverge sharply across installation environments, with product geometry and performance tiers dictating procurement economics. Each segmentation dimension carries distinct margin profiles and supply chain requirements that reshape competitive positioning.
Product Type:
Supply concentrates in sheet and tile manufacturing, with polymer compounding capabilities determining regional production footprints and export competitiveness.
- Sheet:Continuous vulcanized rubber manufactured in widths up to two meters delivers seamless hygiene barriers critical for hospital surgical suites and pharmaceutical cleanrooms. German hospital networks and Dutch laboratory builders specify sheet systems for infection control compliance, with REACH phthalate bans accelerating bio-based binder migration in European production.
- Tiles:Precision-cut square or rectangular units enable rapid installation and localized replacement in high-traffic commercial corridors. Demand concentrates in UK education facilities and Scandinavian transit stations where acoustic underlayment and slip-resistance ratings drive specification, though luxury vinyl tile substitution pressures budget segments.
- Rolls:Extended-length sheet configurations reduce seam count in warehouse and logistics environments. Industrial facilities in Belgium and northern France favor rolls for forklift traffic durability.
- Interlocking:Puzzle-edge tile systems eliminate adhesive requirements and enable DIY residential deployment. Fastest expansion in German home gym installations and temporary commercial fit-outs.
Sheet absorbs the bulk of installed capacity; interlocking is expanding most quickly.
End User:
Cost tier stratification separates specification-grade healthcare systems from price-sensitive residential applications, with certification requirements widening the gap.
- Commercial:Office complexes, retail environments, and hospitality venues specify medium-duty systems balancing durability with aesthetic flexibility. UK and Irish contractors increasingly demand digital acoustic simulation and virtual mockup capabilities before procurement.
- Sports Facilities:Point-elasticity certified systems for indoor athletics command premium positioning through DIN 18032-2 and EN 14904 compliance. Olympic training facilities and professional arenas in Germany and France drive extruded system contracts with superior impact absorption.
- Residential:Home gym and basement applications favor interlocking tiles and budget rolls with basic slip-resistance ratings. Price sensitivity limits specification to entry-level EPDM and recycled content compounds.
- Industrial:Heavy manufacturing and warehousing operations prioritize abrasion resistance and static load tolerance. Chemical processing plants in the Netherlands specify high-density vulcanized sheet for solvent exposure.
Commercial installations dominate current volume; sports facilities are climbing the fastest.
Thickness:
Volume distribution tracks building code minimums and performance certification thresholds, with extruded systems capturing specialized high-margin niches.
- High-profile:Systems exceeding eight millimeters deliver maximum impact absorption for gymnastics facilities and senior care fall protection. German rehabilitation centers and Belgian eldercare facilities specify these compounds for ADA accessibility compliance.
- Extruded:Continuously manufactured profiles with uniform density achieve point-elasticity certification for professional athletics. Production requires specialized twin-screw extrusion equipment concentrated among German and Austrian manufacturers.
- Medium-profile:Four-to-eight millimeter systems balance cost and performance for general commercial traffic. Standard specification in French hospital corridors and Dutch educational institutions.
- Low-profile:Sub-four millimeter sheets and tiles serve light commercial and residential retrofit. Minimal material content limits margin but enables competitive pricing against LVT alternatives.
Medium-profile systems absorb the bulk of installed capacity; extruded configurations are gaining share fastest.
Texture:
Customer type and application risk profile dictate surface finish selection, with OSHA and EN slip-resistance mandates elevating textured and studded specifications.
- Textured:Embossed surface patterns enhance slip resistance in wet environments without aggressive profiling that impedes maintenance. Swimming pool surrounds and food processing areas in Germany and France specify textured finishes for hygiene cleanability.
- Studded:Raised circular or diamond patterns maximize traction in industrial wet areas and exterior transitions. Chemical resistance requirements in Belgian pharmaceutical manufacturing favor studded EPDM compounds.
- Smooth:Flat surfaces enable rapid cleaning and cart maneuverability in healthcare corridors and cleanrooms. Seamless sheet installations in Dutch laboratories specify smooth finishes for particle control.
- Patterned:Decorative embossing mimics wood grain or stone for aesthetic-driven commercial environments. Limited to premium segments in UK hospitality and French retail.
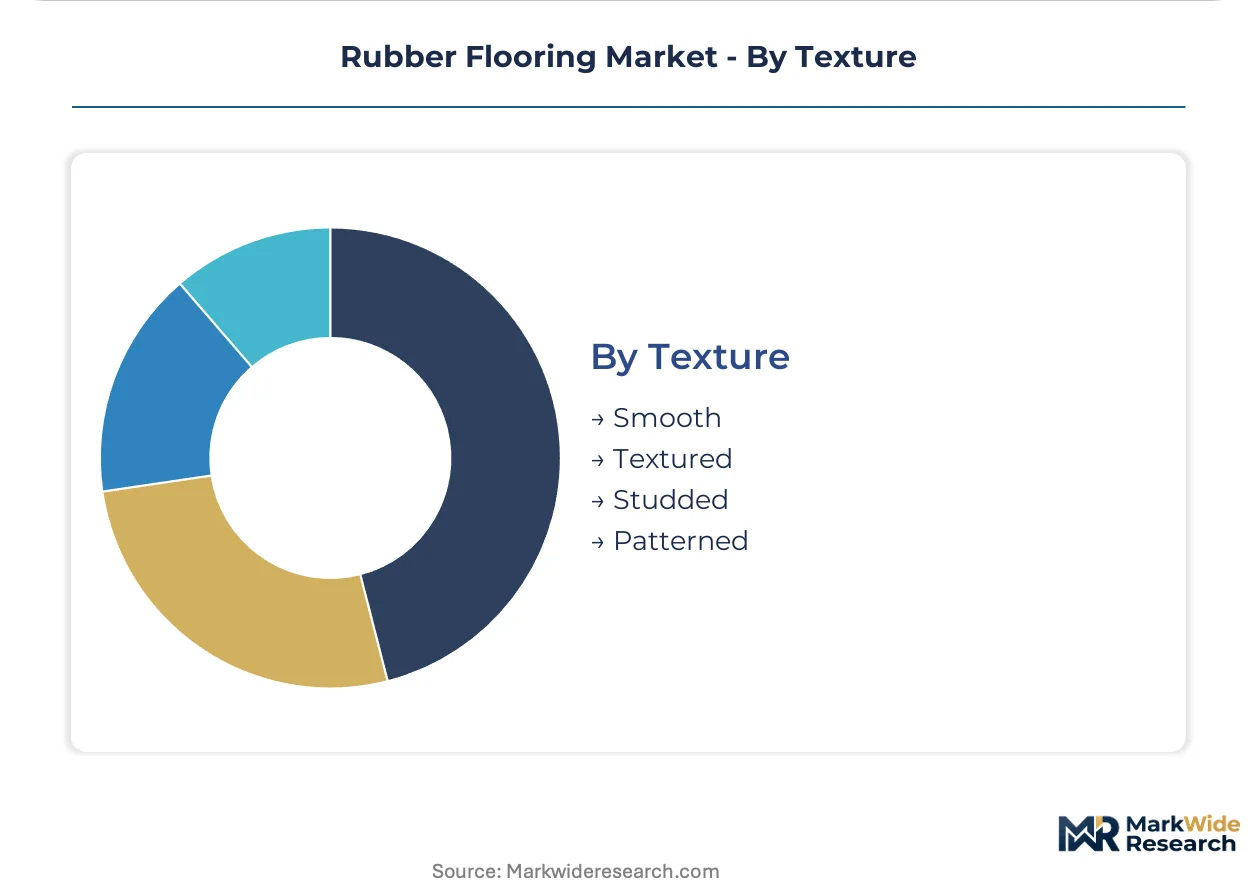
Textured finishes absorb the bulk of installed capacity; studded surfaces are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber feedstock availability in Southeast Asia and synthetic polymer production clusters in Germany and China anchor regional supply economics for rubber flooring manufacturing.
Germany
Hospital renovation programs in Bavaria and North Rhine-Westphalia specify seamless sheet rubber for surgical suite infection control. REACH phthalate restrictions enforced by ECHA accelerate bio-based plasticizer migration across domestic compounding facilities. Cologne-based polymer specialists supply vulcanized compounds to Dutch laboratory builders.
United States
OSHA slip-resistance mandates and ADA accessibility standards drive specification upgrades in healthcare and education construction. Federal procurement guidelines for bio-based content influence public sector flooring selection. Georgia and Ohio manufacturing clusters serve East Coast corridor hospital networks.
China
Domestic EPDM and SBR production capacity in Shandong and Jiangsu provinces supplies regional compounders with cost-advantaged feedstock. GB standards for indoor air quality tighten VOC emission limits in commercial buildings. Shanghai and Beijing specification architects prioritize acoustic performance certification.
India
Ayushman Bharat hospital construction targets health and wellness centers in Maharashtra and Karnataka. CDSCO medical device facility standards create antimicrobial flooring entry points for domestic and imported suppliers. Gujarat pharmaceutical manufacturing zones specify chemical-resistant EPDM systems.
Netherlands
Laboratory and cleanroom construction in Eindhoven and Rotterdam drives demand for seamless smooth-finish sheet systems. EU Green Deal taxonomy alignment requires embodied carbon disclosure through third-party verified EPDs. Dutch healthcare procurement rejects products without standardized environmental declarations.
Rubber Flooring Market Competitive Environment
Global majors compete with regional champions across formulation expertise and distribution reach in rubber flooring. Market structure shows moderate consolidation among polymer compounders with captive manufacturing capabilities, while tile and interlocking segments retain fragmentation. Three archetypes dominate: integrated polymer specialists with in-house compounding, broad-line flooring conglomerates with multi-channel distribution, and regional fabricators serving price-sensitive retrofit segments. Capacity expansion in bio-based binder systems and strategic partnerships for digital specification platforms represent the dominant competitive moves.
Within the integrated specialist tier, Nora Systems and Forbo Flooring Systems exemplify compounder-controlled supply economics. Among diversified flooring groups, Tarkett occupies a position spanning healthcare and education channels. These three anchors represent distinct strategic postures: captive polymer capability, hybrid linoleum-rubble formulation specialization, and broad distribution infrastructure.
| Leading Market Players |
|---|
| Gerflor |
| Nora Systems |
| Tarkett |
| Roppe Corporation |
| LG Hausys |
| Shaw Industries |
| Forbo Flooring Systems |
| Armstrong Flooring |
| Mannington Mills |
| Others |
Value Chain & Pricing Dynamics
Captive polymer compounding capabilities at German and Austrian manufacturers anchor both supply security and premium pricing power for specification-grade sheet systems. Nora Systems and Forbo Flooring Systems leverage in-house vulcanization expertise to command margin premiums while insulating against raw material volatility that pressures tile-focused competitors.
Pricing Analysis
Warranty-backed installation service bundles separate premium sheet manufacturers from unbundled tile suppliers competing on material-only quotes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant bio-based formulations command substantial premiums over phthalate-containing alternatives still clearing residual inventory. Cost compression in the residential interlocking segment intensifies as Chinese EPDM imports and recycled rubber compounds flood DIY channels. Healthcare procurement committees demonstrate lowest price sensitivity, prioritizing infection control warranties and seamless installation guarantees over per-square-meter economics.
Supply Chain Analysis
CE marking and DIN point-elasticity certification gating restricts qualified supply to established European compounders with testing infrastructure investments. Manufacturing concentrates in Germany, China, and the United States—Shandong province EPDM feedstock feeds Asian tile fabricators while Ohio and Georgia facilities serve North American healthcare networks. Styrene-butadiene rubber, ethylene propylene monomer, and vulcanizing agent inputs draw from petrochemical clusters vulnerable to naphtha price swings. Single-source dependency on South Korean synthetic rubber intermediates creates tariff exposure risk. Distribution runs through specification-focused commercial flooring distributors and direct-to-contractor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer compounding chemist scarcity constrains formulation capacity expansion, propping pricing for manufacturers with retained technical expertise. Qualified compounders capture sustained margin premiums as certification requirements tighten.
For Market Incumbents: Acquire specialized vulcanization kinetics expertise through targeted hiring or small-formulator acquisition to defend formulation leadership against bio-based binder disruptors. Deepen backward integration into EPDM polymer sourcing to offset East Asian supply concentration risk. Secure hospital network sole-source agreements before REACH compliance deadlines force competitor reformulation. For New Entrants and Emerging Players: Indian hospital construction contractors represent an underserved buyer archetype with specification authority but limited incumbent relationship lock-in. Target Ayushman Bharat health center builders with CDSCO-compliant antimicrobial flooring offerings. Pursue digital specification platform partnerships to bypass traditional distributor gatekeepers and compress sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap compounders with captive manufacturing and established healthcare channel relationships. Five-to-ten year viability favors specialists with bio-based formulation capabilities and verified EPD documentation infrastructure. Monitor ECHA SVHC list expansion announcements as inflection signals for accelerated phthalate substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Polymer Supply | Captive feedstock secures margin control against naphtha volatility and Korean supply concentration. |
| Bio-Based Plasticizer Formulation Investment | REACH compliance readiness opens German hospital renovation procurement to qualified suppliers. |
| Digital Specification Platform Partnership | Real-time acoustic simulation capabilities meet UK contractor expectations for rapid project quoting. |
| Point-Elasticity Certification Achievement | DIN 18032-2 compliance unlocks Olympic training facility and professional arena contracts. |
| Third-Party EPD Verification Program | EU Green Deal taxonomy alignment enables Dutch and French public sector procurement access. |
Study Parameters
Independent corroboration across formulation chemists at polymer compounders, procurement managers at German hospital networks, and specification architects at Dutch laboratory builders underwrites the qualitative findings. Primary interviews with commercial flooring distributors, UK and Irish contractors, and EPD verification specialists combined with secondary validation from ECHA regulatory filings, REACH SVHC candidate list updates, and customs trade data for synthetic rubber imports. Bottom-up capacity assessments at manufacturing facilities triangulated against top-down demand modeling from healthcare construction permits and sports facility investment announcements.
Rate-of-change decomposition across product type, end-use environment, thickness profile, and surface texture dimensions structures the analytical framework. Volume and value trajectories over the projection horizon reflect segment-specific CAGRs derived from elasticity-adjusted demand curves and substitution threat modeling. Forecast inputs incorporate REACH compliance deadline impacts on formulation migration timelines and Ayushman Bharat hospital construction phase commitments.
Revisions become necessary when ECHA expands SVHC restrictions beyond ortho-phthalates, when Indian CDSCO facility standards tighten antimicrobial performance requirements, or when major EPDM feedstock suppliers announce capacity rationalization. Forecasts reflect documented assumptions regarding polymer price elasticity and certification adoption curves. A model refresh is warranted upon material change in EU Green Deal taxonomy implementation timelines or PFAS restriction scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Polybutadiene Elastomers Market
Rubber
Recycled Elastomers Market
Rubber
Rubber Ropes Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Rubber Extruder Market
Rubber
Reclaimed Rubber Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Synthetic Rubber Market
Rubber
EPDM Rubber Market
Rubber
Europe Rubber Hose Market
Rubber
Europe Neoprene Market
Rubber
Rubber Chemicals Market
Rubber
Rubber Seal Plugs Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Global Styrene Butadiene Styrene Market