
 Asia-Pacific Ceramic Coatings Market | 2026-2036
Asia-Pacific Ceramic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ceramic Coatings Market Outlook
Performance-based maintenance contracts and coating lifecycle subscriptions is recalibrating how Asian industrial buyers budget for surface protection. Praxair S.T. Technology leverages Linde's industrial gas infrastructure to sustain captive supply of coating-grade powders across China and India. Saint-Gobain anchors its regional position through specialized refractory ceramic formulations for extreme-temperature turbine applications. Morgan Advanced Materials competes via R&D intensity in plasma-sprayed environmental barrier coatings for next-generation jet engines.
Asia-Pacific ceramic coatings comprise inorganic, non-metallic layers—typically oxides, carbides, nitrides, or composite formulations deposited via thermal spray, chemical vapor deposition, or sol-gel processes—engineered to withstand thermal shock, corrosion, and abrasive wear in demanding operational environments. Thermal spray coatings dominate current volume due to mature equipment ecosystems and broad substrate compatibility across automotive and power generation sectors. Plasma sprayed coatings represent the fastest-expanding product category, driven by aerospace OEM qualification cycles and medical implant surface functionalization requirements. Sol-gel coatings command premium positioning in electronics end users where nanoscale thickness control and optical clarity prove critical.
China's MEE enforces volatile organic compound emission limits that compel coating houses to shift from solvent-based systems toward waterborne and powder ceramic alternatives. Japan's METI mandates industrial energy efficiency standards that accelerate adoption of low-temperature curing technologies including advanced sol-gel and dip coating processes. India's BIS certification requirements for automotive components create compliance barriers for imported coating systems while privileging localized formulation and application service providers. Stakeholders must monitor how tightening carbon accounting across China's eastern provinces reshapes coating process energy sourcing and equipment upgrade cycles.
Market Dynamics
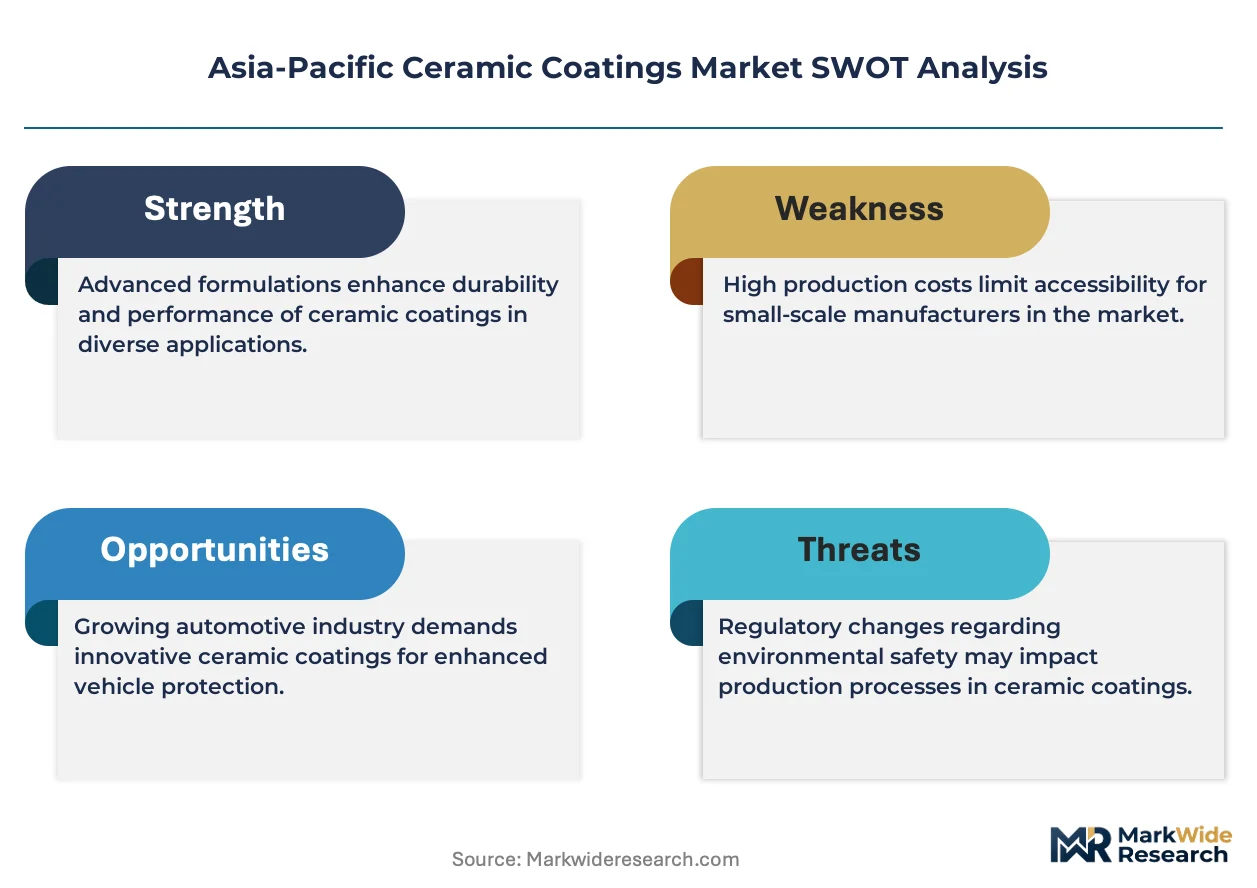
China's MEE volatile organic compound emission limits are compressing solvent-based coating capacity while forcing capital reallocation toward plasma spray and sol-gel infrastructure across the eastern manufacturing corridor.
Growth Catalysts
- Japan's METI efficiency mandates:Industrial energy standards accelerate low-temperature curing technology deployment, expanding addressable substrate markets previously excluded by thermal damage constraints.
- Aerospace OEM qualification cycles:Thermal barrier coating specifications for next-generation turbine architectures pull advanced plasma-sprayed formulations through multi-year validation pipelines.
- Medical implant surface functionalization:Nanoscale thickness control requirements in orthopedic and dental applications drive sol-gel coating precision investments across specialized application service providers.
Market Restraints
- Yttria-stabilized zirconia powder concentration:Coating-grade ceramic feedstock supply concentrates among limited thermal spray powder specialists, creating input cost volatility and qualification bottlenecks for second-tier applicators.
- India's BIS certification barriers:Automotive component coating standards privilege localized formulation expertise, extending compliance timelines for imported system providers and fragmenting procurement across state-level testing protocols.
- Waterborne ceramic formulation performance gaps:MEE-driven solvent restrictions expose adhesion and durability limitations in current water-based alternatives, constraining high-wear industrial applications.
Strategic Opportunities
- India's domestic manufacturing incentives:PLI scheme benefits for automotive and electronics production create captive coating demand requiring localized application infrastructure and technical service partnerships.
- Environmental barrier coating convergence:Plasma-sprayed ceramic-topcoat systems combining thermal protection with corrosion resistance open new specification slots in marine and chemical processing equipment.
- Performance-based maintenance subscriptions:Lifecycle coating contracts displace transactional procurement in power generation and aviation MRO, locking recurring revenue and technical advisory relationships.
Industry Challenges
- Plasma spray technician scarcity:Specialized thermal spray equipment operation and parameter optimization skills concentrate among aging workforces in Japan and Australia, constraining capacity expansion.
- Dual carbon compliance capital intensity:China's eastern province carbon accounting requirements force coating houses to fund renewable energy sourcing and emission monitoring infrastructure alongside process equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ceramic Coatings Market |
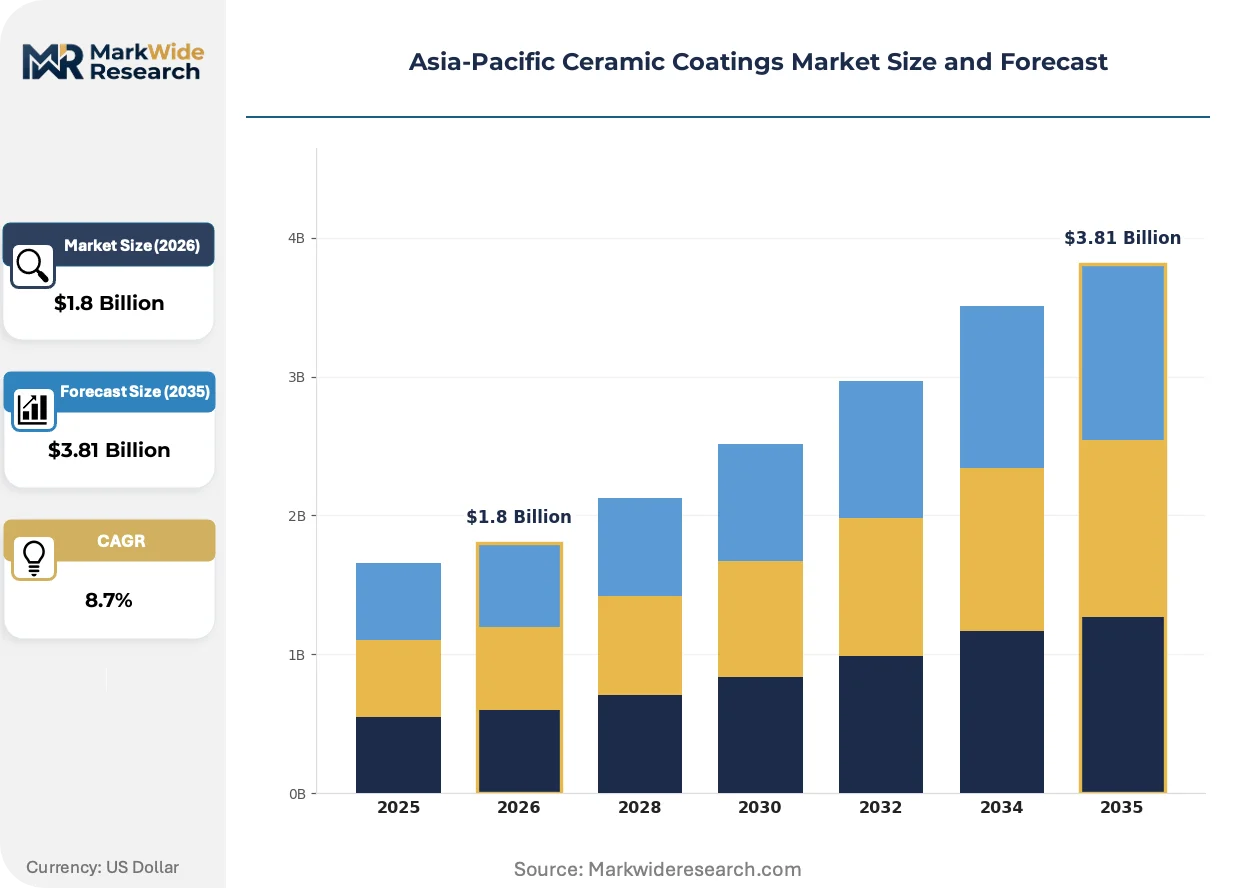
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Spray Coatings, Chemical Vapor Deposition, Plasma Sprayed Coatings, Sol-Gel Coatings Application: Aerospace, Automotive Parts, Medical Devices, Consumer Goods End User: Manufacturing, Healthcare, Electronics, Military Technology: Spray Coating, Dip Coating, Brush Coating, Roll Coating |
| Companies Covered | APS Materials, Inc., Praxair S.T. Technology, Inc. (Linde Plc), Saint-Gobain, Bodycote, Morgan Advanced Materials, OC Oerlikon Management AG, Aremco, Kurt J. Lesker Company, Keronite Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ceramic Coatings Market Strategic Shifts
Process automation and in-situ coating quality monitoring are compressing qualification cycles while elevating specification thresholds across aerospace and medical verticals.
Environmental barrier coatings engineered from rare-earth silicate compositions are rewriting turbine hot-section protection economics. Aerospace OEMs in Japan and South Korea are adopting these formulations ahead of next-generation engine platform launches. The technology is rewriting supplier qualification hierarchies by privileging R&D-intensive plasma spray specialists over commodity thermal spray operators.
China's dual carbon goals enforce provincial-level emission trading schemes that reshape coating process energy sourcing decisions. Industrial facilities in Jiangsu and Zhejiang provinces now face carbon intensity audits affecting equipment replacement timelines. Thermal spray operators respond by retrofitting oxy-fuel systems with hydrogen-capable burners and renewable electricity-fed plasma generators.
Subscription-based coating lifecycle management displaces transactional powder-and-application procurement in aviation MRO and power generation maintenance. Japanese trading houses and Chinese industrial gas distributors capture this shift through integrated supply contracts bundling feedstock, application services, and performance warranties. The model concentrates procurement authority among buyers with balance-sheet capacity for multi-year commitments.
Asia-Pacific Ceramic Coatings Market Segmentation
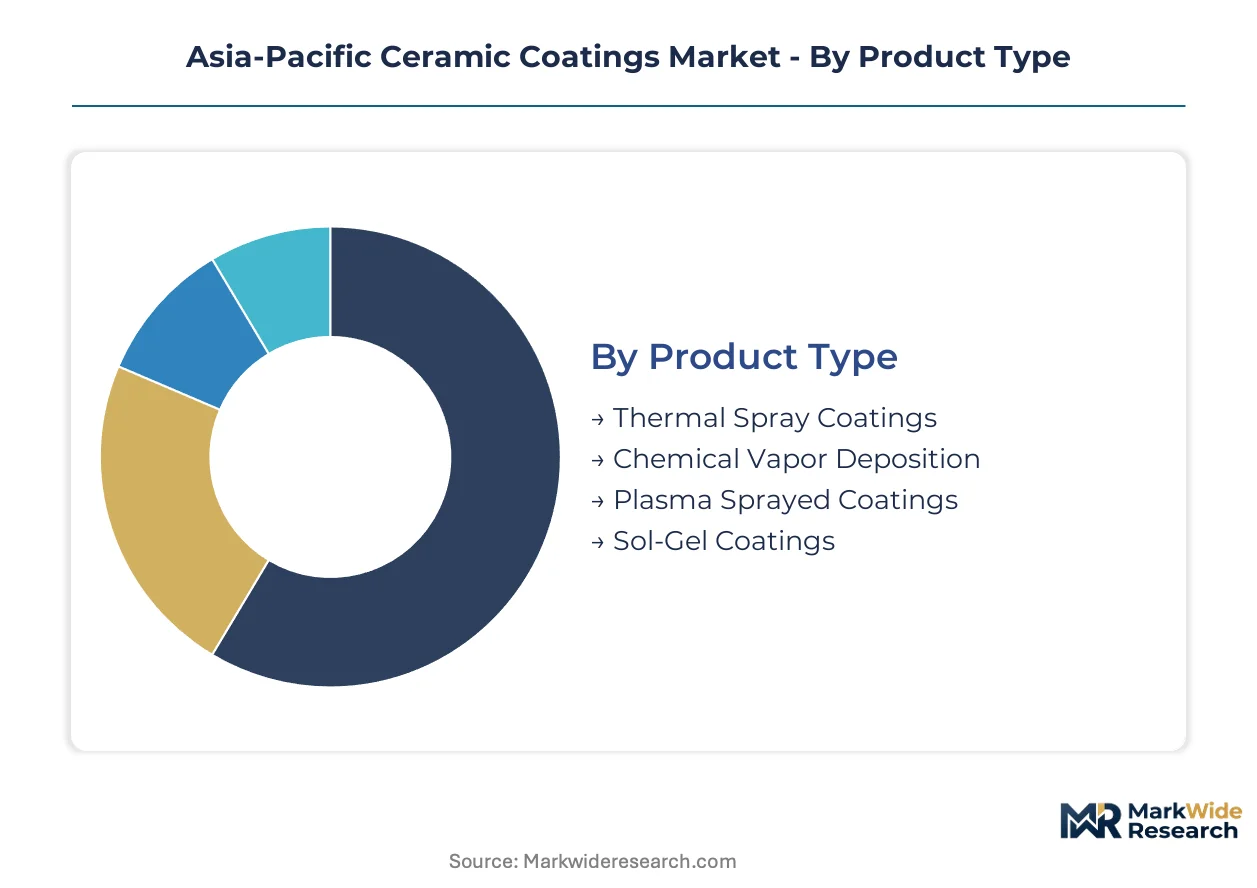
Segmentation in Asia-Pacific ceramic coatings reveals how deposition methods, application environments, and end-use performance requirements fragment procurement specifications across the region's industrial base. Each dimension carries distinct qualification protocols and supplier capability thresholds that reshape competitive positioning.
Product Type:
Customization intensity spans from standardized thermal spray commoditization to precision-engineered sol-gel nanostructures requiring substrate-specific parameter tuning.
- Thermal Spray Coatings:Oxide and carbide layers deposited via combustion or electric arc systems dominate automotive exhaust components and power generation turbine blades across China's eastern manufacturing corridor. MEE emission limits are compressing solvent-based pretreatment capacity while pulling demand toward plasma-enhanced thermal spray variants in Jiangsu province coating houses.
- Plasma Sprayed Coatings:Yttria-stabilized zirconia and rare-earth silicate formulations achieve the temperature gradients required for next-generation jet engine hot-section protection. Japanese and South Korean aerospace OEM qualification cycles are validating these systems through multi-year performance pipelines, concentrating R&D investment among specialized applicators.
- Chemical Vapor Deposition:Ultra-thin ceramic films deposited from gas-phase precursors serve semiconductor fabrication equipment and precision optical substrates.
- Sol-Gel Coatings:Nanoscale thickness control via colloidal suspension gelation addresses medical implant surface functionalization and electronics optical clarity requirements.
Most installed capacity flows through thermal spray infrastructure. Expansion is steepest in plasma sprayed formulations.
Application:
Performance validation intensity escalates from consumer goods cosmetic durability testing to aerospace multi-thousand-hour thermal cycling certification.
- Aerospace:Thermal barrier and environmental barrier coatings protect turbine blades, combustor liners, and exhaust nozzles in commercial and military propulsion systems. China's COMAC and Japan's IHI engine programs are qualifying next-generation ceramic-topcoat architectures through accelerated oxidation and thermal shock protocols.
- Automotive Parts:Piston crowns, valve faces, and exhaust manifold coatings withstand combustion temperatures and corrosive exhaust chemistry. India's PLI scheme for automotive manufacturing is creating captive coating demand requiring localized thermal spray infrastructure in Tamil Nadu and Gujarat component clusters.
- Medical Devices:Orthopedic implants and dental prostheses require biocompatible ceramic surfaces promoting osseointegration.
- Consumer Goods:Wear-resistant and decorative ceramic films protect cookware, watch components, and mobile device housings.
Procurement authority concentrates in aerospace specification engineering. Fastest volume gains are appearing in automotive powertrain applications.
End User:
Buyer sophistication ranges from electronics purchasing managers negotiating nanometer thickness tolerances to military procurement officers mandating domestic supply chain security.
- Manufacturing:Industrial equipment, tooling, and process machinery operators specify abrasion-resistant and corrosion-protective ceramic systems. China's dual carbon enforcement is forcing manufacturing facilities in Zhejiang province to fund renewable-energy-fed plasma generators alongside coating equipment upgrades.
- Electronics:Semiconductor fabrication and display manufacturing require dielectric and optical ceramic films with atomic-layer precision.
- Healthcare:Hospital systems and medical device OEMs source implantable-grade coatings meeting biocompatibility and sterilization resistance standards.
- Military:Defense procurement agencies specify thermal protection and radar-absorptive ceramic systems with supply chain security protocols.
Manufacturing sector procurement represents the largest addressable spend. Healthcare coating specifications are climbing the fastest.
Technology:
Capital intensity and throughput scalability separate automated spray lines from precision dip and brush application methods.
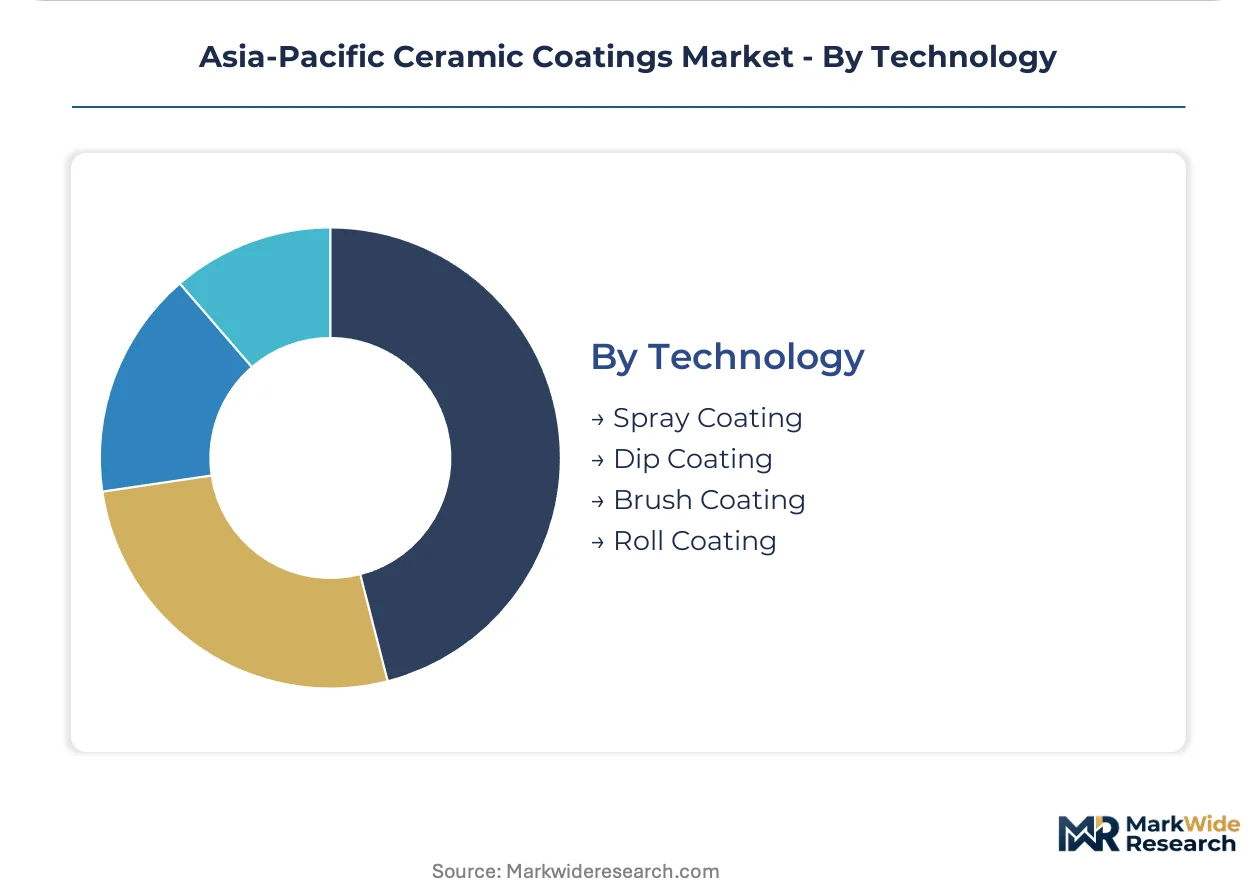
- Spray Coating:Thermal and plasma spray systems deposit thick ceramic layers across large component surface areas. Japan's METI efficiency mandates are accelerating adoption of low-temperature curing spray variants that expand substrate compatibility to temperature-sensitive alloys.
- Dip Coating:Submersion in ceramic slurries achieves uniform coverage on complex geometries for medical and electronics applications.
- Brush Coating:Manual or automated brush application serves repair operations and small-batch custom work.
- Roll Coating:Continuous web processing deposits thin ceramic films on flexible substrates and sheet metal.
Spray coating infrastructure commands the dominant share of regional installed base. Dip coating is gaining share fastest in medical and electronics verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's aerospace OEM qualification cycles pull advanced ceramic formulations through multi-year validation pipelines faster than India's PLI-driven automotive coating infrastructure can localize. China's eastern manufacturing corridor concentrates thermal spray capacity under tightening MEE emission limits, while South Korea and Australia face distinct technician scarcity constraints.
China
COMAC's commercial aircraft engine programs and IHI joint ventures drive thermal barrier coating demand through Shanghai-Jiangsu-Zhejiang industrial clusters. MEE volatile organic compound limits are compressing solvent-based pretreatment capacity across Jiangsu province coating houses. Zhejiang manufacturers now fund renewable-energy-fed plasma generators alongside equipment upgrades to meet provincial carbon accounting requirements.
Japan
IHI and Kawasaki Heavy Industries anchor aerospace ceramic coating specifications for next-generation turbine architectures. METI industrial energy efficiency mandates accelerate low-temperature curing technology deployment, expanding substrate compatibility to temperature-sensitive superalloys. Nagoya-based thermal spray operators face aging workforce constraints that limit plasma spray technician availability for capacity expansion.
India
Automotive component PLI scheme benefits in Tamil Nadu and Gujarat clusters create captive coating demand requiring localized thermal spray infrastructure. BIS certification requirements privilege domestic formulation expertise, extending compliance timelines for imported system providers. Chennai and Ahmedabad coating houses are building technical service partnerships to capture maintenance contract opportunities from expanding OEM operations.
South Korea
Hyundai-Rolls-Royce and Hanwha Aerospace engine programs validate environmental barrier coating formulations ahead of next-generation platform launches. Rare-earth silicate plasma-sprayed systems are rewriting supplier qualification hierarchies by privileging R&D-intensive specialists. Busan-Ulsan industrial zones concentrate marine and power generation coating applications requiring corrosion-thermal protection convergence.
Australia
Mining equipment refurbishment and power generation maintenance drive thermal spray coating demand across Western Australia and Queensland resource corridors. Specialized plasma spray equipment operation skills concentrate among aging workforces in Perth and Brisbane, constraining capacity expansion for high-wear industrial applications. Local applicators are exploring performance-based lifecycle contracts to lock recurring revenue from remote site maintenance operations.
Asia-Pacific Ceramic Coatings Market Competitive Environment
Top-tier vendors anchor aerospace and industrial gas infrastructure positions, while mid-tier specialists compete on R&D intensity and regional application service networks. The market structure reflects consolidation around thermal spray powder supply chains and fragmentation across localized coating service providers. Three archetypes dominate: industrial gas distributors leveraging captive feedstock supply, refractory ceramic formulators targeting extreme-temperature applications, and plasma spray R&D specialists pursuing environmental barrier coating qualifications. Competitive moves concentrate on strategic partnerships bundling feedstock and application services, plus geographic expansion through technical service joint ventures.
Among industrial gas-integrated operators, Praxair S.T. Technology exemplifies the captive powder supply archetype through Linde's regional infrastructure. Saint-Gobain occupies a position representing specialized refractory ceramic formulation capabilities for turbine hot-section protection. Morgan Advanced Materials sits within the R&D-intensive plasma spray specialist tier, with its focus on environmental barrier coating development for next-generation engine platforms. These three anchors illustrate how feedstock control, material science depth, and aerospace qualification pipelines separate competitive tiers.
| Leading Market Players |
|---|
| APS Materials, Inc. |
| Praxair S.T. Technology, Inc. (Linde Plc) |
| Saint-Gobain |
| Bodycote |
| Morgan Advanced Materials |
| OC Oerlikon Management AG |
| Aremco |
| Kurt J. Lesker Company |
| Keronite Group |
| Others |
Value Chain & Pricing Dynamics
Yttria-stabilized zirconia powder spot indices cascade through Asia-Pacific ceramic coatings markets into three-tier pricing structures across premium aerospace-qualified, standard industrial-grade, and economy thermal spray tiers. China's eastern manufacturing corridor concentrates plasma spray powder production, amplifying feedstock cost volatility for second-tier applicators in India and Southeast Asia.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for thermal spray services while aerospace OEM qualification premiums sustain margin separation at the top. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with MEE emission compliance costs compressing margins in solvent-restricted segments. Price differentiation stems from plasma spray technician scarcity and after-sales technical advisory bundling. Japanese automotive buyers exhibit lowest price sensitivity due to METI-mandated performance standards, while Indian BIS-compliant component manufacturers face acute cost pressure from localized formulation requirements.
Supply Chain Analysis
Dual-sourcing mandates from Japanese and South Korean aerospace OEMs force qualification of secondary yttria-stabilized zirconia powder suppliers beyond dominant Chinese thermal spray feedstock producers. Geographic supply concentration centers on China for coating-grade ceramic powders, Japan for rare-earth silicate formulations, and Australia for mineral sand feedstocks. Raw material dependencies include zirconium ores, yttrium oxides, and rare-earth silicates. Single-source vulnerability concentrates in plasma spray powder specialists qualified for turbine hot-section applications. Distribution runs through industrial gas distributors bundling feedstock with application equipment and technical service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific ceramic coatings markets function as regulatory compounders where China's MEE volatile organic compound limits and dual carbon enforcement create sustained demand for emission-compliant deposition technologies.
For Market Incumbents: Extend captive powder supply advantages through hydrogen-capable burner retrofits and renewable-energy-fed plasma generator partnerships in Zhejiang province coating clusters. Consolidate technical service networks around performance-based lifecycle contracts to lock recurring revenue against emerging R&D-intensive plasma spray specialists. Vertical integration into rare-earth silicate formulation capabilities defends aerospace specification positions as environmental barrier coating qualifications rewrite supplier hierarchies. For New Entrants and Emerging Players: India's PLI scheme for automotive manufacturing opens a window for localized thermal spray infrastructure partnerships in Tamil Nadu and Gujarat component clusters. Target medical implant surface functionalization segments where sol-gel precision requirements and BIS certification barriers fragment procurement across specialized application service providers. White-space capture depends on technical service joint ventures with established industrial gas distributors rather than greenfield powder production. For Investors and Strategic Acquirers: Asymmetric upside sits with R&D-intensive plasma spray specialists holding active environmental barrier coating qualification pipelines with Japanese and South Korean aerospace OEMs. Five-to-ten year viability hinges on rare-earth silicate formulation depth and technician training infrastructure. Watch for COMAC engine program thermal barrier coating specification finalizations as inflection indicators for Chinese domestic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating-Grade Powder Production | Captive yttria-stabilized zirconia supply secures margin control against feedstock volatility from Chinese thermal spray specialists. |
| Hydrogen-Capable Burner Retrofit Programs | MEE carbon accounting compliance in Jiangsu province enables continued thermal spray capacity operation under tightening emission limits. |
| Performance-Based Lifecycle Contract Expansion | Subscription coating management displaces transactional procurement in Japanese aviation MRO and Australian mining equipment refurbishment. |
| Rare-Earth Silicate Formulation R&D Investment | Environmental barrier coating qualifications with IHI and Kawasaki Heavy Industries rewrite turbine hot-section protection supplier hierarchies. |
| Technical Service Joint Ventures in India | BIS certification expertise and localized application infrastructure capture PLI-driven automotive coating demand in Chennai and Ahmedabad clusters. |
Study Parameters
Coverage spans China, Japan, India, South Korea, and Australia, with primary inputs from each market through structured interviews with thermal spray equipment operators, aerospace procurement engineers, ceramic powder plant managers, and medical device coating specialists. Secondary validation draws from MEE emission filings, METI efficiency standard disclosures, BIS certification registries, customs trade data for zirconium and yttrium compounds, and SEC filings from industrial gas distributors. Bottom-up capacity and utilization estimates triangulate against top-down end-use demand modeling from aerospace OEM production schedules and automotive PLI beneficiary disclosures.
Granularity-level modeling operates at deposition technology, application environment, and end-use performance requirement dimensions across the projection horizon. Segmentation dimensions include thermal spray versus plasma spray versus sol-gel process categories, aerospace versus automotive versus medical device applications, and manufacturing versus electronics versus healthcare end-user sectors. CAGRs derive from equipment installation trajectories, qualification pipeline durations, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate COMAC engine program thermal barrier coating adoption timelines and India's PLI scheme automotive component production ramp schedules.
Revisions become necessary when MEE emission limit enforcement intensity deviates from provincial carbon accounting trajectories, when aerospace OEM qualification cycles accelerate or stall for environmental barrier coating formulations, or when India's BIS certification protocols expand to additional automotive component categories. Deviation in rare-earth silicate powder supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramics Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Strontium Carbonate Market
Ceramics
Ceramic Frit Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
Calcined Alumina Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
White Fused Alumina Market
Ceramics
Stoneware Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Cement Castables Market
Ceramics
Zirconium Dioxide Market