
 E House Market | 2026-2036
E House Market Size, Share, and Industry Trends Forecast 2026-2036
E House Market Intelligence
Direct-to-developer distribution is fragmenting as modular E House manufacturers bypass traditional general contractor networks to secure project-level contracts. ABB leverages its electrification portfolio to anchor prefabricated power-distribution skids within integrated E House packages. Siemens AG competes through digital twin capabilities that streamline factory-to-site logistics for modular residential units. Schneider Electric differentiates via IoT-enabled energy management systems embedded at the panel-assembly stage.
An E House is a prefabricated, factory-built electrical power distribution center or fully equipped modular building enclosure, typically housing switchgear, transformers, control systems, and HVAC in a steel-framed transportable structure rated for outdoor installation. These units eliminate on-site civil works and reduce commissioning time by consolidating electrical infrastructure into weatherproof, code-compliant enclosures delivered as plug-and-play assets. Modular Units command the dominant share of product-type revenue due to repeatability and scale economies in factory production, while Smart Homes represent the fastest-expanding category as home automation and renewable energy integration become standard specifications rather than upgrades. Energy-Efficient Houses capture concentrated margin pools where green building certifications and utility incentive programs reward superior insulation and integrated solar-battery systems.
The EU Green Deal and associated Energy Performance of Buildings Directive tighten efficiency thresholds across member states, compelling E House manufacturers to pre-certify thermal envelopes and embedded systems before site delivery. CE marking under the Construction Products Regulation governs structural safety and electromagnetic compatibility for units sold across European markets, while national building codes in Germany, France, and the Netherlands impose additional fire-resistance and accessibility standards that shape product design. Buyers and suppliers must monitor how upcoming EU taxonomy alignment rules will reclassify eligible green construction assets and redirect capital toward factory-built solutions with verifiable lifecycle carbon data.
Market Dynamics
Factory prefabrication is compressing project timelines for electrical infrastructure delivery, as developers prioritize speed-to-occupancy over traditional on-site construction methods in Germany's dense urban corridors.
Growth Catalysts
- EU Green Deal building performance standards:Tightening energy efficiency mandates for new construction are accelerating specification of pre-certified thermal envelopes in modular electrical housing units.
- Urban labor shortages:Germany's construction sector faces acute skilled worker deficits, pushing developers toward factory-built solutions that minimize on-site electrical trades.
- Digital twin integration:Siemens AG and competitors embed simulation capabilities that streamline factory-to-site logistics, reducing commissioning errors and rework cycles.
Market Restraints
- Steel input cost volatility:Fluctuating prices for structural steel framing materials compress margins on standardized modular units during contract bidding phases.
- CE marking complexity:Construction Products Regulation compliance for electromagnetic compatibility adds certification overhead that delays cross-border unit shipments.
- Transport dimensional limits:Road freight regulations constrain maximum module sizes, fragmenting larger electrical assemblies into multiple shipments that raise logistics costs.
Strategic Opportunities
- Netherlands residential densification zones:Amsterdam and Rotterdam corridor projects present concentrated demand for compact, high-density electrical distribution solutions.
- IoT-enabled energy management convergence:Integration of Schneider Electric's panel-embedded sensors with home automation platforms creates premium positioning for smart E House variants.
- French utility incentive programs:Subsidies for integrated solar-battery systems in new construction drive specification of energy-efficient house configurations with pre-wired renewable interfaces.
Industry Challenges
- Electrical commissioning specialist scarcity:Factory technicians capable of integrating switchgear, transformers, and HVAC controls in prefabricated enclosures command wage premiums that inflate production costs.
- Legacy grid interconnection protocols:Municipal distribution operators in older German cities maintain non-standard connection requirements that complicate plug-and-play deployment claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E House Market |
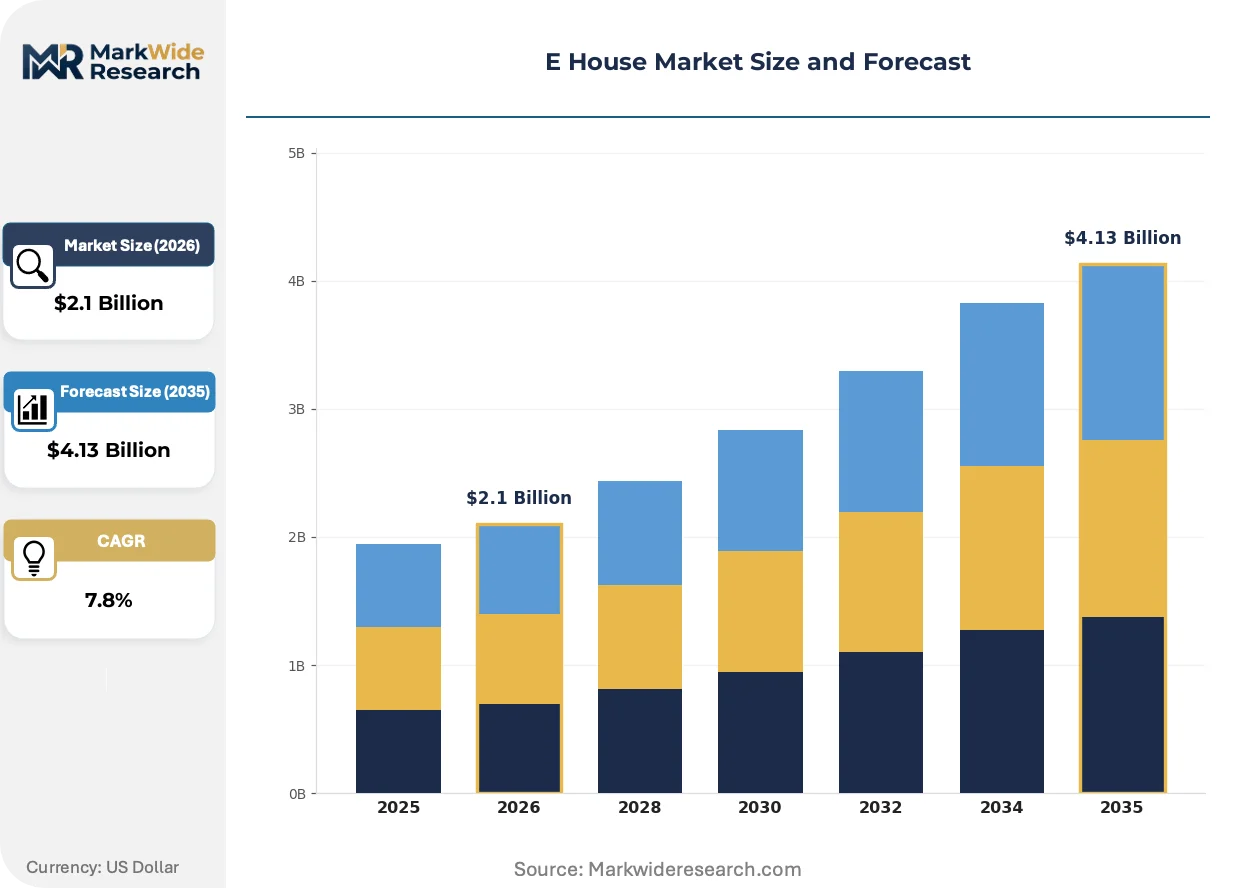
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Homes, Modular Units, Energy-Efficient Houses, Traditional Structures Technology: IoT Devices, Renewable Energy Systems, Home Automation, Smart Security Solutions End User: Homeowners, Real Estate Developers, Construction Firms, Property Managers Application: Residential Living, Vacation Homes, Rental Properties, Commercial Space |
| Companies Covered | ABB, Siemens AG, Schneider Electric, Eaton Corporation, General Electric, Powell Industries, WEG, Larsen & Toubro, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E House Market Strategic Shifts & Innovations
Digital fabrication and embedded intelligence are redefining how electrical infrastructure moves from factory floor to operational asset, compressing traditional boundaries between manufacturing, logistics, and field commissioning.
Modular switchgear skids with integrated cooling and fire suppression are collapsing the distinction between electrical equipment and building envelope, enabling ABB to deliver complete power-distribution centers as single-source assets. Residential developers in Berlin and Munich are specifying these consolidated units at accelerating rates. The resulting compression of supplier tiers is eliminating traditional general contractor intermediaries from electrical procurement chains.
EU taxonomy alignment rules for green construction assets are reclassifying eligible investments based on verifiable lifecycle carbon data, compelling manufacturers to document factory energy inputs and transport emissions. Prefabricated E House producers with embedded metering capabilities gain preferential financing access. German banks and institutional investors are steering capital toward suppliers demonstrating panel-level energy transparency.
Direct contracting between manufacturers and project developers is displacing distributor-mediated procurement in France's social housing sector, where public procurement rules now favor single-source responsibility for electrical infrastructure performance. This channel compression concentrates volume with integrated suppliers capable of warranting both equipment and enclosure. The shift is most visible in Île-de-France, where housing agencies prioritize total-cost-of-ownership metrics over upfront capital expenditure minimization.
E House Market Segmentation
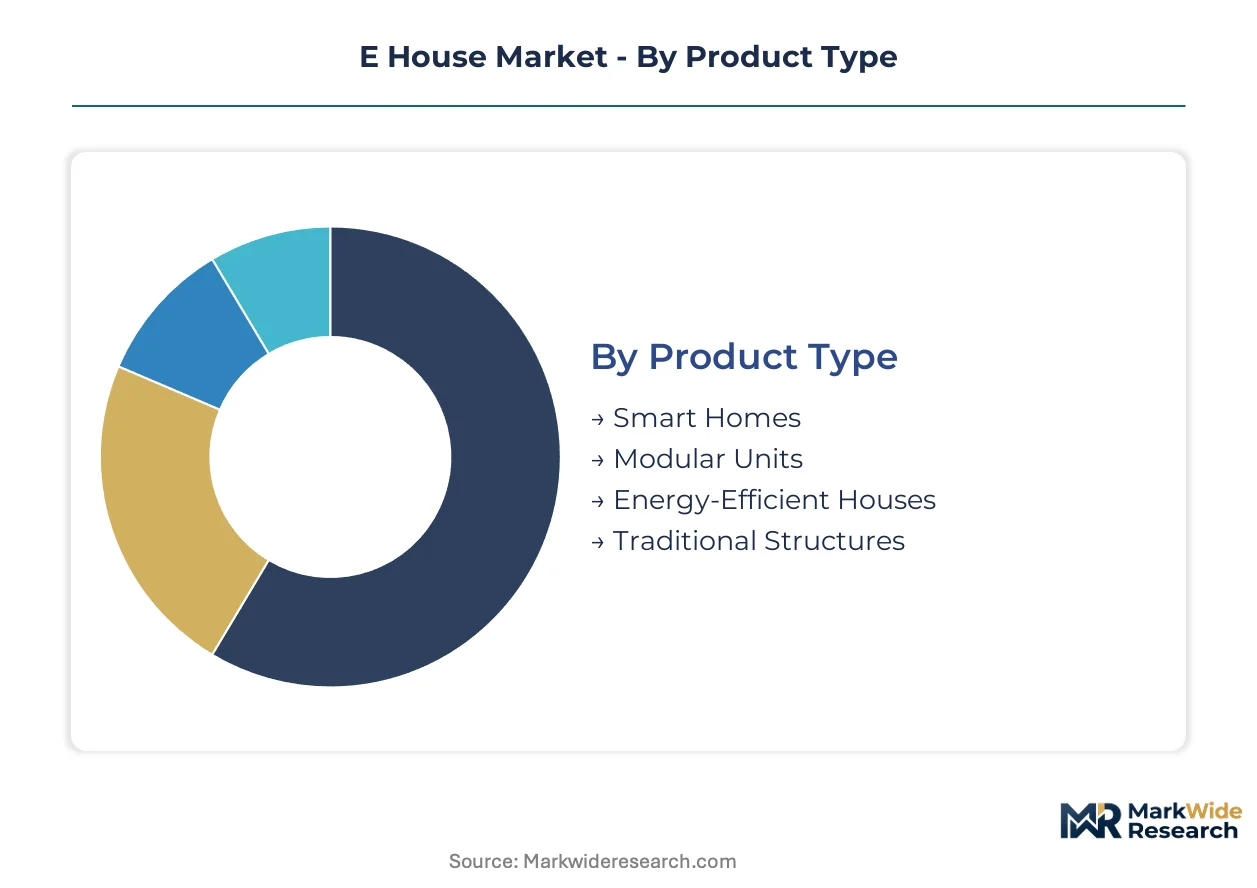
E House manufacturers calibrate production lines, certification protocols, and distribution channels around distinct segment profiles. Product architecture, technology integration depth, buyer procurement patterns, and end-use deployment contexts each reshape factory workflows and margin structures differently.
Product Type:
Cost tier differentiation separates standardized commodity enclosures from performance-optimized configurations commanding premium positioning.
- Modular Units:Factory-built electrical distribution centers consolidate switchgear, transformers, and HVAC into steel-framed transportable structures. German urban housing corridors concentrate specification where labor shortages accelerate plug-and-play deployment over site-built alternatives.
- Smart Homes:Embedded IoT infrastructure and home automation platforms transform electrical enclosures into intelligent building nodes. Amsterdam and Rotterdam densification projects drive specification as renewable integration becomes baseline rather than upgrade.
- Energy-Efficient Houses:Pre-certified thermal envelopes with integrated solar-battery interfaces capture utility incentive flows in France and green financing preferences under EU taxonomy alignment.
- Traditional Structures:Conventional on-site electrical construction persists in markets with limited modular supply chain maturity or restrictive transport infrastructure.
Modular Units hold installed capacity. Smart Homes is rotating up the share rankings.
Technology:
Application maturity varies sharply across embedded systems, with some technologies already standardized and others still negotiating interoperability protocols.
- IoT Devices:Panel-embedded sensors enable real-time energy monitoring and predictive maintenance workflows. Schneider Electric's factory-floor integration of metering capabilities streamlines commissioning and satisfies EU Green Deal documentation requirements for lifecycle carbon transparency.
- Renewable Energy Systems:Pre-wired solar-battery interfaces reduce field installation complexity. French utility incentive programs concentrate demand where subsidies reward integrated renewable configurations in new construction.
- Home Automation:Centralized control platforms for lighting, climate, and security systems embed at the enclosure assembly stage. Berlin and Munich residential developers increasingly specify these capabilities.
- Smart Security Solutions:Integrated access control and surveillance infrastructure consolidates into modular electrical housings for vacation home and rental property applications.
IoT Devices anchor current production volumes. Renewable Energy Systems is climbing the fastest.
End User:
Customer type determines contracting structure, with direct manufacturer relationships displacing traditional distribution channels in specific buyer categories.
- Real Estate Developers:Project-level procurement of complete electrical infrastructure packages eliminates general contractor intermediaries. Île-de-France housing agencies prioritize total-cost-of-ownership metrics that favor single-source responsibility.
- Construction Firms:Legacy procurement through electrical distributors persists where project scale or geographic dispersion complicates direct manufacturer engagement.
- Homeowners:Individual purchasers access modular E House solutions through developer-installed packages rather than standalone procurement.
- Property Managers:Rental portfolio operators specify standardized units for operational consistency across multi-site holdings.
Real Estate Developers command decision authority. Property Managers is gaining procurement sophistication fastest.
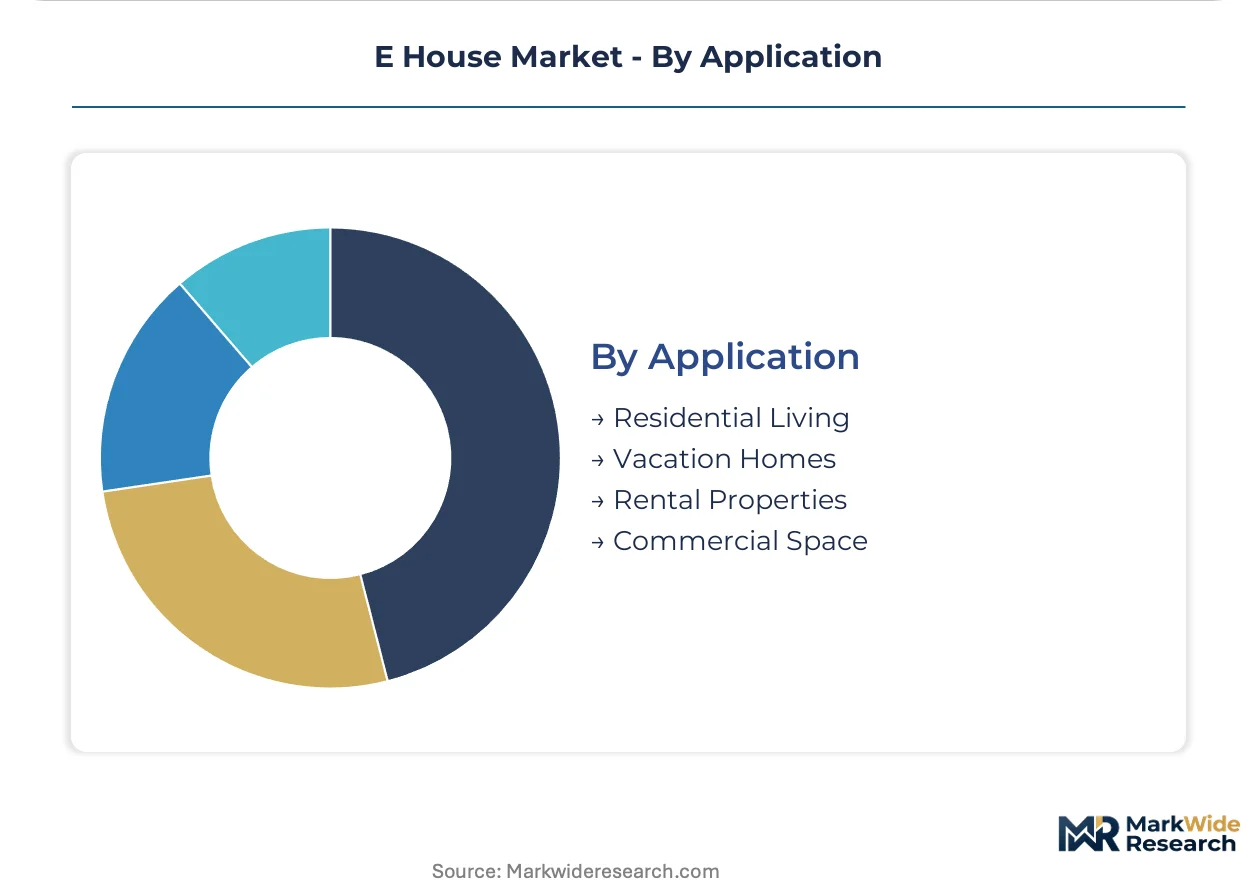
Application:
Deployment context shapes enclosure specifications, with occupancy patterns and regulatory exposure varying across use cases.
- Residential Living:Permanent occupancy applications drive the highest performance standards for thermal efficiency and grid interconnection reliability. Germany's building energy codes impose stringent requirements on these deployments.
- Rental Properties:Operational durability and remote monitoring capabilities prioritize IoT-enabled configurations that reduce maintenance dispatch frequency.
- Vacation Homes:Seasonal occupancy patterns favor simplified automation and security-focused specifications over full home automation integration.
- Commercial Space:Mixed-use electrical loads and extended operating hours demand enhanced cooling and fire suppression integration within modular enclosures.
Residential Living anchors specification volume. Rental Properties is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power over Eastern European markets due to pre-certified thermal envelope standards, while French buyers extract concessions through utility-linked incentive programs.
Germany
Urban labor shortages in Berlin and Munich accelerate factory-built electrical housing adoption over site-built alternatives. The EU Green Deal's Energy Performance of Buildings Directive tightens efficiency thresholds for new construction. The Rhine-Ruhr corridor concentrates modular unit demand where developers prioritize speed-to-occupancy.
France
Social housing agencies in Île-de-France prioritize total-cost-of-ownership metrics that favor single-source electrical infrastructure responsibility. French utility incentive programs subsidize integrated solar-battery systems in new construction. The Paris metropolitan area drives specification of energy-efficient house configurations with pre-wired renewable interfaces.
Netherlands
Amsterdam and Rotterdam densification projects present concentrated demand for compact, high-density electrical distribution solutions. CE marking under the Construction Products Regulation governs structural safety and electromagnetic compatibility for cross-border unit shipments. The Randstad urban agglomeration accelerates smart home specification as renewable integration becomes baseline rather than upgrade.
United States
Real estate developers in Texas and Florida expand adoption of modular prefabricated units across residential projects. FERC interconnection standards shape grid integration requirements for factory-built electrical housing. The Sun Belt corridor concentrates demand where climate resilience and rapid deployment timelines converge.
India
Construction firms in Maharashtra and Gujarat face skilled electrical trades deficits that push toward prefabricated solutions. BIS certification requirements for electrical enclosures add compliance overhead that favors established factory producers. The Delhi-Mumbai Industrial Corridor drives specification of modular power distribution centers for industrial zone electrification.
E House Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying switchgear, transformers, and control systems to enclosure assemblers. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with electrification portfolios, pure-play modular housing fabricators, and electrical equipment manufacturers extending into integrated enclosures. Consolidation pressures favor players with captive supply of steel framing and HVAC systems. Geographic expansion and technology licensing represent the dominant competitive vectors as manufacturers seek CE marking economies across EU member states.
Within the diversified industrial tier, ABB leverages its electrification portfolio to anchor prefabricated power-distribution skids, while Siemens AG exemplifies digital twin integration capabilities that streamline factory-to-site logistics. Schneider Electric occupies a position in IoT-enabled energy management convergence, embedding panel-level sensors that satisfy EU Green Deal documentation requirements. These three conglomerates represent distinct strategic postures: equipment-led integration, software-enabled logistics, and embedded intelligence specialization.
| Leading Market Players |
|---|
| ABB |
| Siemens AG |
| Schneider Electric |
| Eaton Corporation |
| General Electric |
| Powell Industries |
| WEG |
| Larsen & Toubro |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
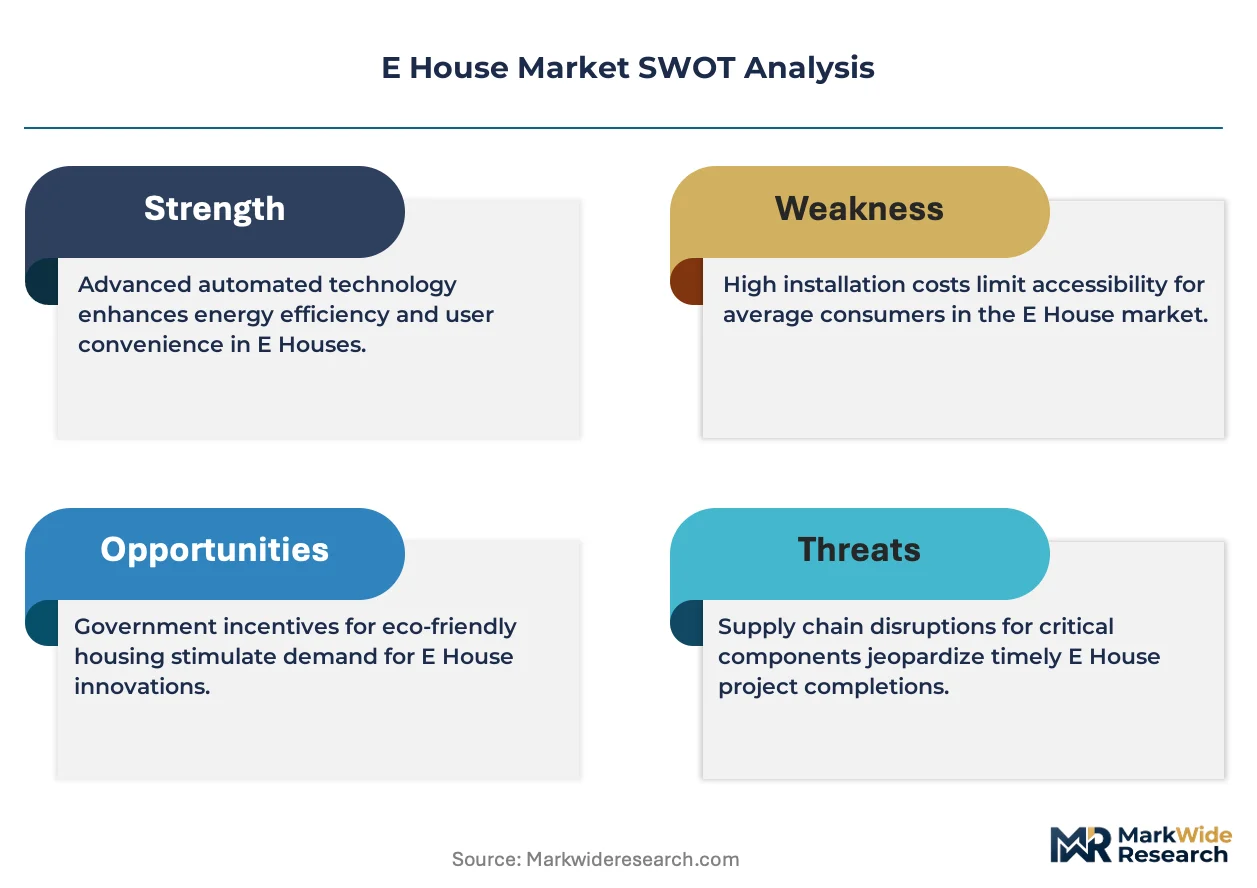
Steel framing fabrication in Germany concentrates upstream supply leverage, compressing margin pools for standardized modular enclosures while premium configured-to-order units retain pricing power through CE marking complexity and factory commissioning specialization.
Pricing Analysis
Configured-to-order pricing commands a substantial premium over standardized modular unit quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal envelope certification grade and embedded IoT capability depth. Cost compression in economy-tier standardized units is intensifying because steel input volatility and transport dimensional constraints fragment larger assemblies. Real estate developers exhibit the highest price sensitivity, while social housing agencies in France prioritize total-cost-of-ownership metrics that absorb upfront premiums.
Supply Chain Analysis
EU dual-use export controls on power-distribution technologies constrain cross-border flows of embedded control systems and smart grid interfaces. Factory production draws from Germany, the Netherlands, and Poland for steel framing, switchgear components, and HVAC integration. Supply chain risk centers on single-source vulnerability for specialized electrical commissioning technicians commanding wage premiums. Distribution runs through direct manufacturer-to-developer contracts that displace traditional general contractor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-built electrical housing sits in early-cycle expansion as EU Green Deal mandates convert on-site construction to pre-certified modular delivery across member states.
For Market Incumbents: Harden factory-floor digital twin capabilities against Siemens AG's logistics-streamlining advantage. Deepen backward integration into captive steel framing supply to buffer margin compression from commodity volatility. Secure CE marking economies across multiple EU member states before taxonomy alignment rules harden documentation requirements. For New Entrants and Emerging Players: Pursue Netherlands residential densification corridors where Amsterdam and Rotterdam projects concentrate demand for compact electrical distribution solutions. Target smart home configurations in the Randstad urban agglomeration where renewable integration has become baseline specification. Lead with IoT-enabled energy management convergence as the primary go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play modular housing fabricators with demonstrated factory energy transparency and embedded metering capabilities. Long-term viability across the next decade hinges on lifecycle carbon documentation that satisfies EU taxonomy alignment for green financing access. Watch for inflection when German banks and institutional investors complete their reclassification of eligible green construction assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Framing | Captive supply of structural materials buffers margin compression from commodity volatility cycles. |
| CE Marking Economies Expansion | Cross-border certification coverage accelerates unit shipments across multiple EU member states. |
| Digital Twin Capability Deployment | Factory-to-site logistics simulation reduces commissioning errors and accelerates speed-to-occupancy. |
| IoT Sensor Factory-Floor Integration | Panel-embedded metering satisfies EU Green Deal lifecycle carbon transparency requirements. |
| Direct Developer Contracting | Single-source responsibility for electrical infrastructure performance displaces general contractor intermediaries. |
Research Approach
Desk research of EU regulatory filings, construction product certification databases, and utility incentive program documentation preceded structured interviews with electrical infrastructure procurement managers at real estate developers, factory commissioning specialists, and social housing agency technical directors. Primary fieldwork with modular unit manufacturers and steel framing suppliers combined with secondary validation against national building code repositories and customs trade records. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations.
Assumptions held fixed include EU Green Deal implementation timelines and CE marking regulatory frameworks, while steel price trajectories and labor shortage severity varied across sensitivity scenarios. The analytical framework modeled product type, technology integration depth, end user procurement pattern, and application deployment context across the analysis window. CAGRs derived from segment-level unit economics and replacement cycle dynamics, with inputs from factory capacity utilization rates and urban housing permit flows.
Sensitivities concentrate around EU taxonomy alignment rule finalization and national building code amendments in Germany, France, and the Netherlands. Forecasts reflect assumptions about continued skilled electrical trades scarcity and transport infrastructure capacity. Material shifts in steel input cost volatility or CE marking compliance timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market