
 United States Real Estate Brokerage Market | 2026-2036
United States Real Estate Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Real Estate Brokerage Market Insights
Institutional buyers and build-to-rent operators is redrawing transaction flow in United States residential brokerage. Compass leverages proprietary technology platforms to capture high-value listings in coastal metros. Keller Williams sustains its agent-centric franchise model across suburban and exurban territories. eXp Realty competes through cloud-based operations that reduce fixed overhead in secondary markets.
Real estate brokerage encompasses the intermediation of property transactions through licensed agents who facilitate valuation, marketing, negotiation, and closing services under state regulatory frameworks, typically earning commission fees calculated as a percentage of final sale price. The practice serves as the primary distribution channel connecting property owners with buyers, lessees, and investors in fragmented asset markets. Residential brokerage anchors the largest revenue pool given homeownership depth and transaction frequency, while commercial segments command premium fee structures due to complexity and principal size. Online service models are gaining fastest as iBuyer platforms and digital listing aggregators compress traditional search costs.
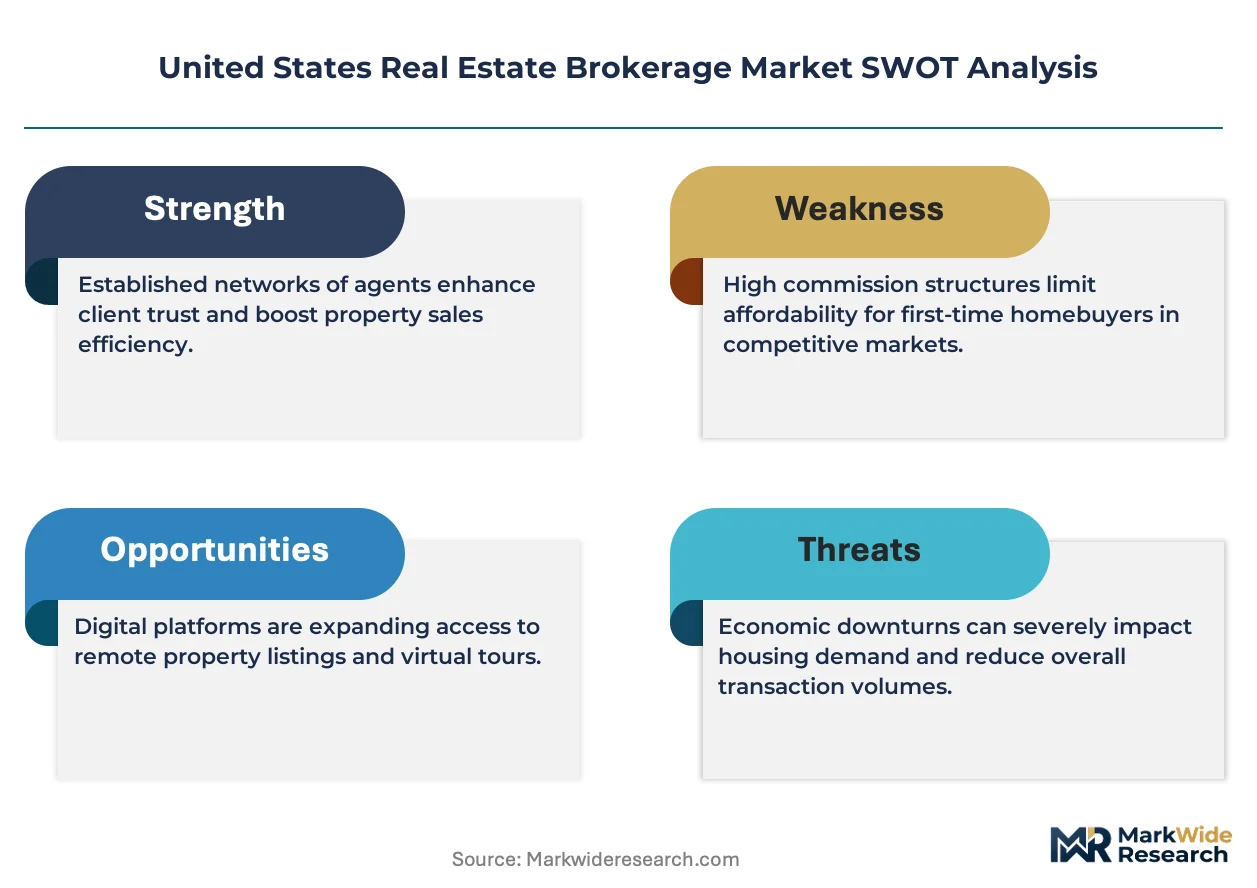
NAR settlement terms, state-level licensing boards, and CFPB mortgage disclosure rules collectively reshape how brokers disclose compensation and compete for consumer representation. State regulators in California, Texas, and Florida are scrutinizing minimum service requirements and referral fee arrangements. Stakeholders must monitor whether commission compression triggers consolidation among independent brokerages or accelerates technology substitution for traditional agent functions.
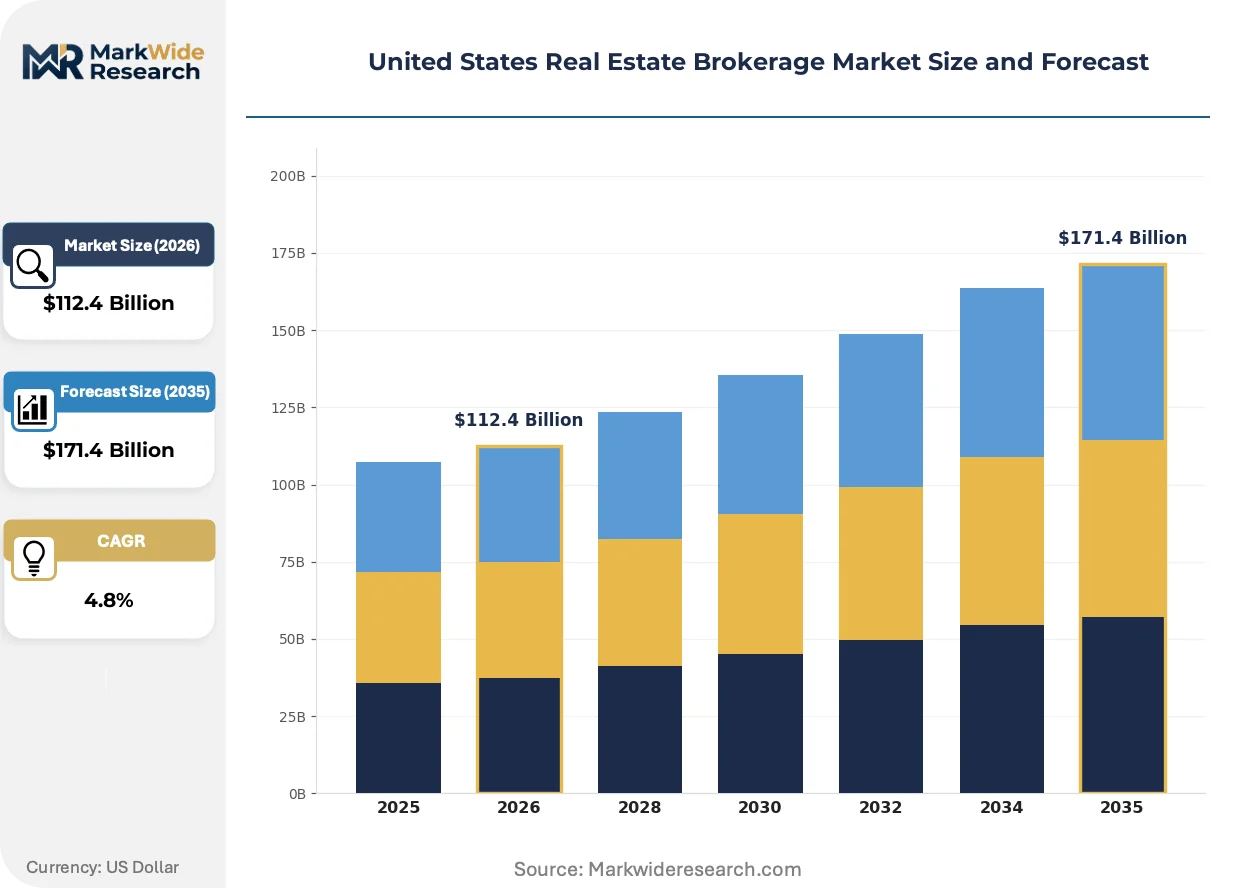
Market Dynamics
The National Association of Realtors settlement is dismantling the traditional commission-sharing architecture that has governed residential transactions for decades. This regulatory inflection point is compressing fee structures and forcing brokerages to rebuild revenue models around transparent buyer-agent compensation.
Growth Catalysts
- Sun Belt Migration:Austin, Phoenix, and Tampa are absorbing population inflows that sustain transaction velocity and listing turnover. Institutional multifamily investors target these metros for build-to-rent deployment.
- Cloud-Based Operations:Virtual brokerage platforms reduce fixed office overhead and expand agent recruitment into secondary markets without physical infrastructure investment.
- CFPB Disclosure Alignment:Standardized mortgage cost presentation improves consumer comparison shopping and accelerates digital lead conversion for compliant brokerages.
Market Restraints
- Commission Compression:The NAR settlement triggers fee renegotiation between buyers and agents, squeezing per-transaction revenue for traditional full-service models.
- Regulatory Fragmentation:California, Texas, and Florida maintain divergent minimum service requirements that complicate national platform standardization.
- iBuyer Substitution:Instant offer platforms from institutional operators capture price-sensitive sellers seeking transaction certainty over representation.
Strategic Opportunities
- Secondary Market Penetration:Brokerages with lightweight technology stacks can capture share in exurban territories where transaction density previously excluded full-service presence.
- Referral Fee Restructuring:State-level scrutiny of referral arrangements creates opening for transparent fee-splitting platforms that document compliance.
- Agent Productivity Tools:AI-powered valuation and marketing automation converges with mobile CRM to reduce time-per-transaction for independent contractors.
Industry Challenges
- Agent Retention Economics:Commission compression threatens the split-based compensation that sustains recruiting pipelines at franchise networks.
- Legacy System Integration:MLS data feeds and transaction management platforms require costly API reconfiguration to support alternative compensation structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Real Estate Brokerage Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Brokerage Type: Residential, Commercial, Industrial, Mixed-Use Service Model: Full-Service, Discount, Limited-Service, Online Client Type: First-Time Buyers, Investors, Landlords, Corporations Transaction Type: Sales, Rentals, Leases, Auction |
| Companies Covered | Compass, Anywhere Advisors, eXp Realty, HomeServices of America, Berkshire Hathaway HomeServices, RE/MAX Holdings, Keller Williams, CBRE Group, Realogy Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Real Estate Brokerage Market Trends and Innovations
Digital intermediation is recoding how property discovery, valuation, and closing execution connect buyers with inventory. Brokerages are racing to embed automation into agent workflows before technology platforms eliminate the intermediary function entirely.
Artificial intelligence valuation models are supplanting traditional comparative market analysis prepared by individual agents. Institutional investors and iBuyer operators deploy these tools to generate instant offers at scale. The compression of pricing discovery into algorithmic outputs is reducing the information advantage that historically justified agent representation fees.
The NAR settlement terms are mandating upfront buyer-agent compensation disclosure before property tours commence. State regulators in Texas and Florida are drafting implementation rules that define enforceable transparency standards. Residential brokerages in these states are restructuring buyer representation agreements to comply while preserving service differentiation.
Consumers are unbundling transaction services and purchasing à la carte support rather than comprehensive representation. Flat-fee listing services and limited-scope buyer consultation are displacing traditional full-commission packages in price-sensitive segments. This fragmentation is most pronounced in markets with elevated home prices where percentage-based fees generate absolute dollar resistance.
United States Real Estate Brokerage Market Segmentation
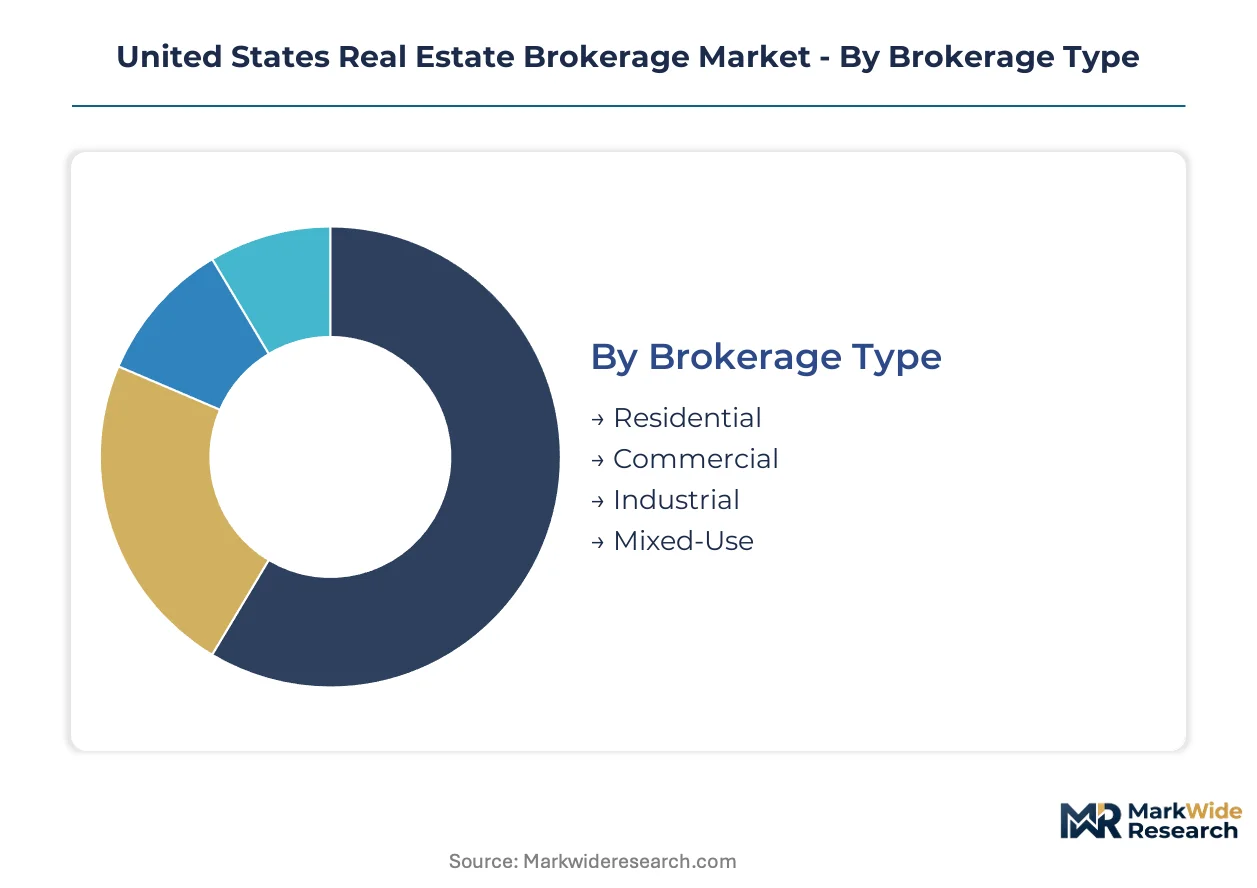
Brokerage segmentation reveals how commission compression and technology substitution are reshaping revenue pools across transaction types and client relationships. Structural variation in service intensity and principal sophistication determines which models withstand margin pressure.
Brokerage Type:
Geographic demand concentration varies sharply: residential and mixed-use segments track domestic migration flows into Sun Belt metros, while commercial and industrial segments serve export-led capital deployment from institutional investors.
- Residential:Single-family and condominium transactions dominate transaction volume. Demand clusters in Austin, Phoenix, and Tampa where migration sustains listing turnover and agent productivity.
- Commercial:Office, retail, and hospitality assets command premium fee structures due to due diligence complexity and principal size. Institutional capital from pension funds and REITs drives cross-border investment into gateway cities.
- Industrial:Warehouse and logistics facilities near port infrastructure and interstate corridors attract foreign capital seeking yield. E-commerce fulfillment demand reshapes site selection criteria.
- Mixed-Use:Developments combining residential, retail, and office components require coordinated leasing and sales execution. Urban infill projects in densifying metros absorb domestic household formation.
Residential holds the largest share; momentum sits with mixed-use as zoning liberalization accelerates.
Service Model:
Cost tier stratification separates technology-enabled platforms from labor-intensive representation, with fee compression forcing migration toward lighter overhead structures.
- Full-Service:Comprehensive valuation, marketing, negotiation, and closing support delivered by licensed agents under traditional commission splits. High-touch representation persists in luxury segments and complex transactions where principal risk aversion justifies premium fees.
- Discount:Reduced commission rates achieved through streamlined marketing and limited showing schedules. Volume-dependent operators in high-velocity Sun Belt markets capture price-sensitive sellers through scale economics.
- Limited-Service:À la carte menu of specific transaction functions—listing entry, contract review, or closing coordination—unbundled from comprehensive representation. Flat-fee structures appeal to experienced sellers in appreciating markets.
- Online:Digital-first platforms with cloud-based agent support and algorithmic valuation tools. Virtual brokerage models expand fastest in secondary markets where physical office infrastructure was previously uneconomical.
Full-service retains dominant share; online platforms are climbing the fastest as fixed-cost elimination attracts agent recruitment.
Client Type:
Customer sophistication and transaction frequency determine service economics, with repeat clients commanding differentiated retention strategies.
- First-Time Buyers:Purchasers navigating mortgage qualification, inspection contingencies, and closing complexity for initial homeownership. NAR settlement transparency requirements reshape how buyer-agent compensation is disclosed pre-tour.
- Investors:Individual and small-group purchasers of rental properties or fix-and-flip assets. Acquisition velocity in build-to-rent corridors demands rapid market analysis and off-market access.
- Landlords:Property owners seeking tenant placement, lease renewal, or portfolio disposition. Multi-unit operators in institutional multifamily markets require specialized property management integration.
- Corporations:Relocation management companies and employer-sponsored home sale programs. Volume-based referral arrangements face state-level scrutiny over disclosure compliance.
First-time buyers represent the largest client base; investors are gaining share fastest as rental yield chasing intensifies.
Transaction Type:
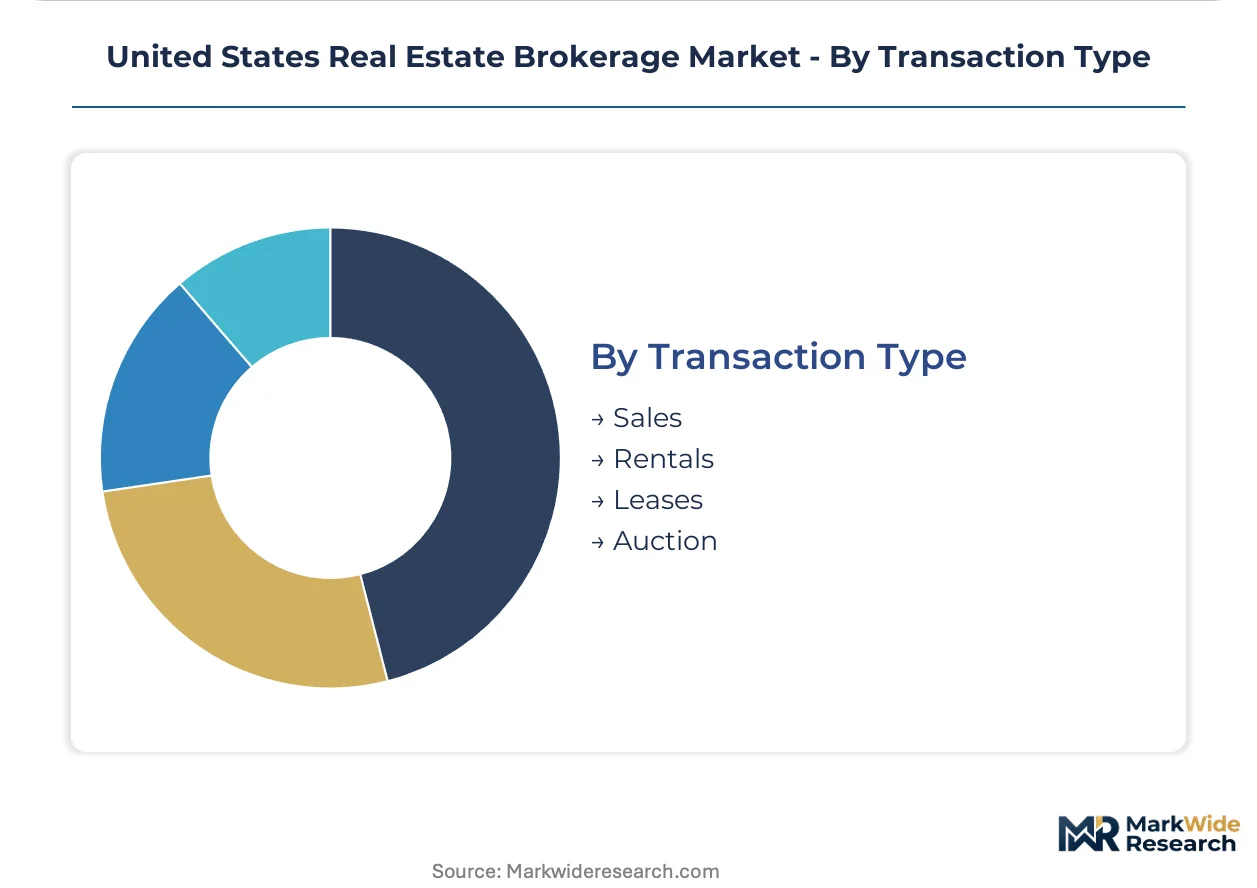
Volume-maturity dynamics separate high-frequency rental markets from cyclical sales activity, with auction formats emerging for distressed inventory clearance.
- Sales:Fee-based representation for property transfer with deed conveyance and title clearance. Commission compression from NAR settlement terms directly pressures per-transaction revenue.
- Rentals:Tenant placement and lease execution for residential and commercial units. High-turnover multifamily markets in migration destinations sustain recurring fee income.
- Leases:Commercial tenant representation and landlord leasing for office, retail, and industrial space. Renewal rates and concession negotiations determine brokerage attachment.
- Auction:Accelerated disposition for distressed, estate, or unique properties requiring price discovery through competitive bidding. Institutional iBuyer platforms encroach on certainty-seeking sellers.
Sales transactions hold dominant share; rentals demonstrate steepest expansion trajectory as institutional single-family rental portfolios scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate highway system and Class I rail networks anchor regional transaction velocity across the United States. Metropolitan clusters with intermodal freight access concentrate institutional capital deployment and sustain listing turnover.
Texas
Austin and Dallas-Fort Worth absorb domestic migration flows that sustain residential transaction density. The Texas Real Estate Commission enforces broker licensing standards and disclosure requirements for buyer representation agreements. Houston's energy corridor attracts corporate relocation programs that generate volume for relocation management brokerages.
Florida
Tampa and Miami metro areas lead Sun Belt population absorption with sustained multifamily investor activity. The Florida Department of Business and Professional Regulation oversees commission disclosure rules following NAR settlement implementation. Orlando's tourism economy supports vacation rental brokerage specialization and second-home transaction velocity.
California
Los Angeles and San Francisco Bay Area markets command premium fee structures despite transaction volume compression. The California Department of Real Estate maintains stringent minimum service requirements that complicate discount model penetration. San Diego's biotech corridor sustains corporate relocation brokerage demand.
New York Metro
Manhattan and Brooklyn concentrate commercial brokerage revenue with institutional investor cross-border capital flows. The New York Department of State regulates co-op and condominium transaction disclosure standards. Long Island and Westchester suburbs sustain traditional full-service residential representation.
Arizona
Phoenix and Tucson metro areas lead national population growth rates with build-to-rent institutional deployment. The Arizona Department of Real Estate implements NAR settlement transparency rules for buyer-agent compensation disclosure. Scottsdale's luxury segment sustains high-touch brokerage models resistant to commission compression.
United States Real Estate Brokerage Market Competitive Landscape
Concentration sits with technology-enabled platforms and legacy franchise networks competing for agent recruitment and listing inventory. The market structure fragments across cloud-based virtual brokerages, traditional brick-and-mortar franchises, and institutional holding companies. Three archetypes dominate: proprietary technology platforms reducing fixed overhead, agent-centric franchise models emphasizing training and culture, and diversified real estate services conglomerates integrating brokerage with mortgage and title operations. Competitive moves center on M&A consolidation of independent brokerages and geographic expansion into secondary markets through lightweight technology deployment.
Among technology-forward operators, Compass and eXp Realty exemplify the platform archetype with divergent capital structures. Compass represents the venture-backed model with proprietary tools targeting coastal luxury markets. eXp Realty occupies a position within cloud-native brokerage with agent equity participation. Keller Williams anchors the franchise archetype with independent contractor scale across suburban territories. Anywhere Advisors and Realogy Holdings sit within the diversified services tier integrating transaction components. RE/MAX Holdings exemplifies the global franchise brand with recurring revenue from agent fees. CBRE Group and Berkshire Hathaway HomeServices represent distinct institutional holding structures serving commercial and residential segments respectively.
| Leading Market Players |
|---|
| Compass |
| Anywhere Advisors |
| eXp Realty |
| HomeServices of America |
| Berkshire Hathaway HomeServices |
| RE/MAX Holdings |
| Keller Williams |
| CBRE Group |
| Realogy Holdings |
| Others |
Pricing and Supply Chain Analysis
Cloud-based transaction management platforms are displacing legacy MLS infrastructure investments, simultaneously redistributing supply geography toward virtual brokerages and compressing pricing economics for fixed-cost operators in high-rent metros.
Pricing Analysis
Volume-discount tiering structures separate full-service representation from limited-service and flat-fee alternatives. Premium tiers attach to luxury listings in coastal markets where principal risk aversion sustains higher splits, while economy tiers capture price-sensitive sellers through streamlined marketing packages. Pricing pressure stems from NAR settlement-driven commission compression and iBuyer certainty premiums. First-time buyers demonstrate highest price sensitivity to buyer-agent compensation disclosure, whereas institutional investors prioritize transaction velocity over fee minimization.
Supply Chain Analysis
MLS data feed aggregation at the metropolitan level creates a chokepoint that constrains national platform standardization and elevates compliance costs for multi-state operators. Supply concentration rests on Texas, Florida, and California as the three largest state-level licensing jurisdictions with divergent minimum service requirements. Raw material dependencies include proprietary valuation algorithms, mobile CRM infrastructure, and transaction management software licenses. Tariff exposure sits minimal given domestic service delivery, though regulatory fragmentation across state real estate commissions fragments distribution through localized compliance overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against algorithmic valuation platforms and iBuyer instant-offer models that disintermediate traditional agent representation. Incumbents must navigate technology substitution while rebuilding revenue models around transparent compensation structures.
For Market Incumbents: Compound agent productivity through AI-powered valuation and marketing automation to offset per-transaction revenue compression from NAR settlement terms. Acquire independent brokerages in Austin, Phoenix, and Tampa to capture Sun Belt transaction velocity before cloud-native competitors establish secondary market presence. Backward integration into mortgage and title operations preserves attachment rate as commission splits tighten.
For New Entrants and Emerging Players: Buyer representation agreement transparency gaps in Texas and Florida implementation rules expose white-space for compliant disclosure platforms that document compensation pre-tour. Target exurban territories surrounding Sun Belt metros where transaction density previously excluded full-service presence. Deploy lightweight technology stacks with flat-fee listing entry as the primary go-to-market wedge against legacy franchise overhead.
For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors technology-enabled platforms with capital reserves to absorb MLS API reconfiguration costs. Long-term viability centers on brokerages that convert agent networks into proprietary data assets for algorithmic pricing. Acquisition targets should demonstrate cloud-native infrastructure and Sun Belt geographic concentration. Watch NAR settlement implementation variance across state regulators as the inflection signal for platform consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Integration | Proprietary AI valuation tools from Compass compress pricing discovery timelines for institutional investors. |
| Geographic Expansion | Cloud-based agent recruitment into secondary markets eliminates physical office overhead in exurban territories. |
| Regulatory Compliance Investment | Upfront buyer-agent compensation disclosure systems satisfy Texas and Florida implementation requirements. |
| Service Unbundling | Flat-fee listing entry and limited-scope consultation capture price-sensitive sellers in appreciating markets. |
| Backward Integration | In-house mortgage and title operations preserve revenue attachment as commission compression intensifies. |
Research Methodology
Operator-level perspectives from brokerage executives, state licensing board administrators, MLS data providers, and institutional multifamily investors anchored the qualitative base. Secondary validation drew from National Association of Realtors transaction surveys, state real estate commission regulatory filings, CFPB mortgage disclosure databases, and commercial property transaction records. Bottom-up agent productivity metrics and top-down market sizing triangulated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against NAR settlement implementation variance, Sun Belt migration velocity shifts, and iBuyer market share penetration scenarios. Segmentation dimensions modeled include brokerage type, service model tier, client sophistication level, and transaction format. CAGRs derived from transaction volume projections weighted by average commission rate trajectories. Forecast inputs incorporated housing turnover rates, institutional capital deployment patterns, and regulatory compliance cost escalations.
Forecasts assume regulatory continuity in Texas Real Estate Commission, Florida Department of Business and Professional Regulation, and California Department of Real Estate enforcement frameworks; material policy shifts would require re-modeling. Revision becomes warranted when commission compression velocity or iBuyer substitution rates cross thresholds that invalidate agent retention economics assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market