
 US E-House Market | 2026-2036
US E-House Market Size, Share, and Industry Trends Forecast 2026-2036
US E-House Market Analytics
Modular bundling of switchgear, transformers, and control systems into single-source E-House deliveries is realigning procurement patterns across US utilities and industrial buyers. ABB leverages its integrated power distribution portfolio to anchor large utility contracts in the Southeast. Schneider Electric differentiates through digital twin integration and IoT-enabled monitoring architectures. Eaton competes on manufacturing scale with domestic production footprints serving oil and gas customers in the Permian Basin.
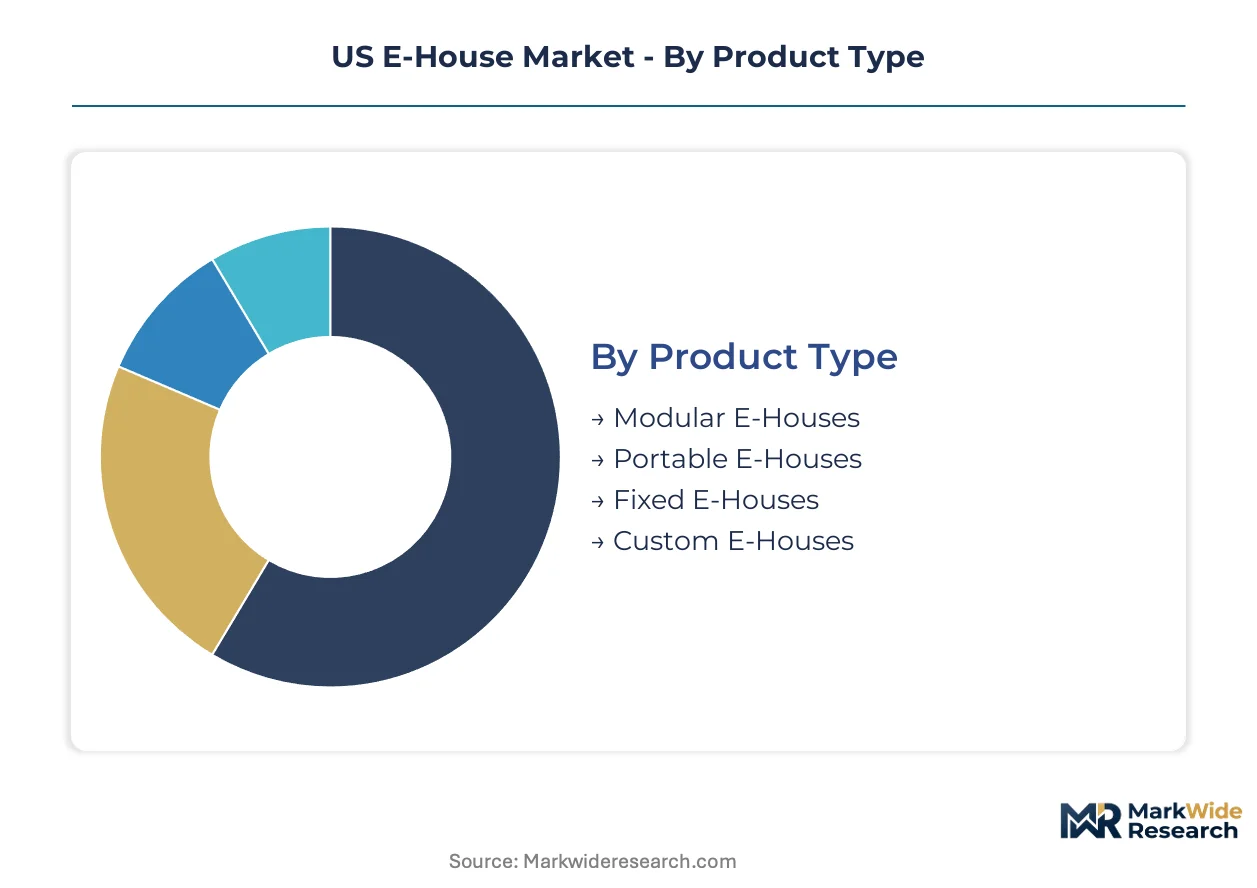
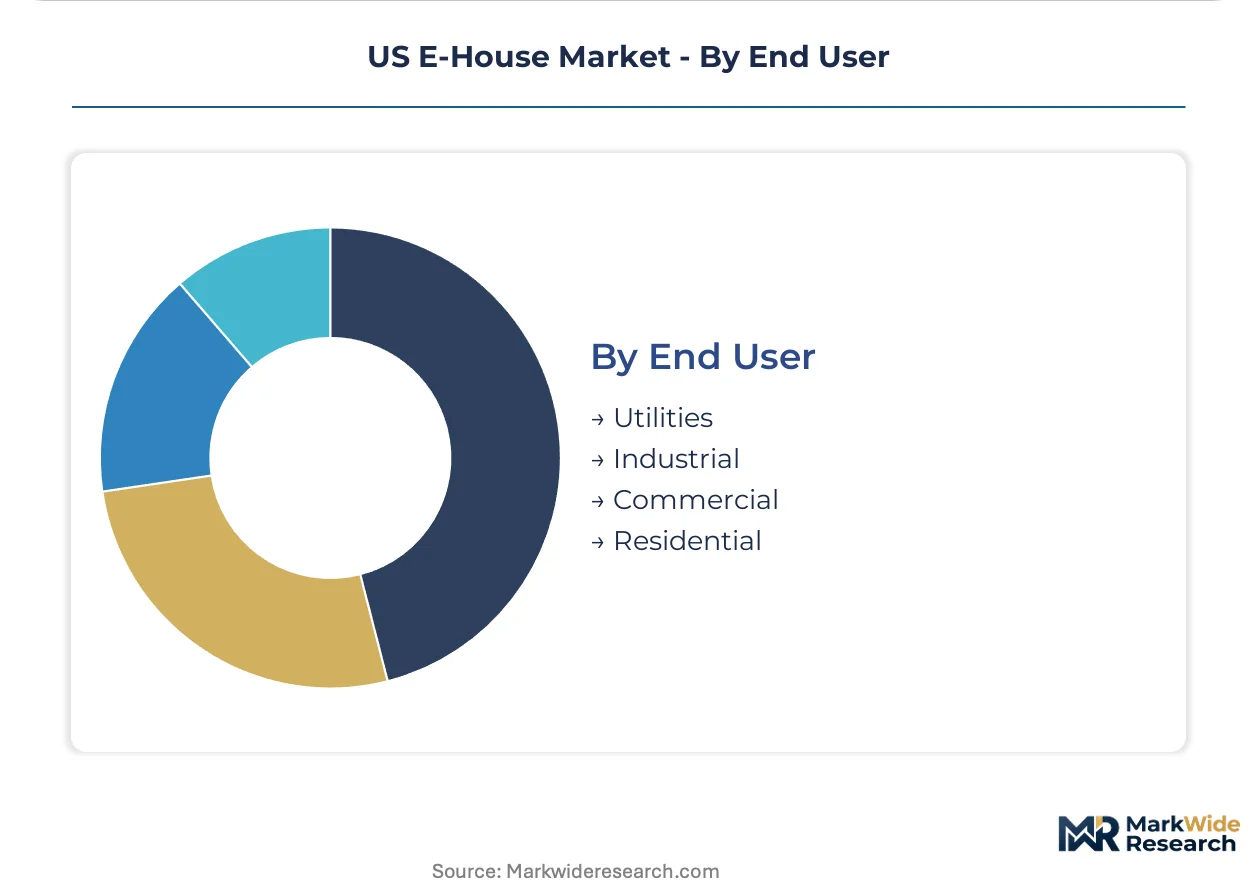
An E-House is a prefabricated, transportable enclosure housing medium-voltage switchgear, transformers, protection relays, and auxiliary control equipment, typically engineered to IEEE and NEMA standards for outdoor installation. Its primary purpose is to compress project schedules by shifting electrical assembly from field construction to factory-controlled environments. Modular E-Houses command the dominant share of new orders due to repeatability and shorter lead times, while Custom E-Houses capture premium margin pools in retrofit and space-constrained applications. Among end users, the Utilities segment leads absolute volume, though the Industrial category is expanding fastest behind onshore manufacturing reshoring initiatives.
NERC reliability standards, OSHA electrical safety requirements, and state-level NEC adoption cycles collectively shape product certification burdens and site acceptance protocols for E-House deployments. The EPA's evolving stance on SF6 emissions from switchgear insulation is pushing manufacturers toward alternative gas formulations and vacuum interrupter designs. Stakeholders must monitor how interconnection queue reforms and IRA-driven clean energy incentives reshape the geographic distribution and technical specifications of incoming E-House orders.
Market Dynamics
Prefabricated electrical infrastructure procurement is compressing traditional field construction timelines as data center operators and utilities confront interconnection queue bottlenecks across Texas, Virginia, and Arizona. This structural shift from stick-built substations to factory-integrated E-House deliveries is reordering supplier relationships and certification protocols.
Growth Catalysts
- IRA clean energy incentives:Tax credits under the Inflation Reduction Act accelerate utility-scale solar deployments requiring rapid electrical infrastructure commissioning.
- Hyperscale data center clustering:Cloud providers in Northern Virginia and Phoenix are procuring E-Houses to meet 18-month facility construction cycles.
- NERC reliability standard enforcement:Tighter compliance deadlines for CIP-014 physical security and PRC-005 protection system maintenance drive standardized, pre-certified equipment purchases.
Market Restraints
- Copper and electrical steel volatility:Transformer core material costs fluctuate with commodity markets, squeezing fixed-price contract margins for manufacturers.
- Specialized fabricator concentration:Domestic E-House production clusters among a limited set of Gulf Coast and Midwest facilities with certified welding and electrical assembly capabilities.
- SF6 regulatory pressure:EPA scrutiny of sulfur hexafluoride emissions from medium-voltage switchgear insulation complicates legacy product lines and extends redesign cycles.
Strategic Opportunities
- Offshore wind interconnection:Atlantic Coast projects from Massachusetts to North Carolina require marine-grade E-Houses with corrosion-resistant enclosures and modular expansion capacity.
- Battery energy storage integration:Hybrid E-House configurations combining switchgear with BESS power conversion systems address solar-plus-storage developer needs.
- Digital twin service layering:IoT-enabled predictive maintenance contracts create recurring revenue streams beyond equipment sales.
Industry Challenges
- Certified electrical assembler scarcity:Factory positions requiring NCCER certification and medium-voltage safety training remain unfilled across Texas and Arizona manufacturing hubs.
- State-by-state NEC adoption lag:Variations in National Electrical Code enforcement between jurisdictions force redundant engineering reviews and delay site acceptance.
- Legacy SCADA integration complexity:Brownfield utility deployments demand custom protocol bridging between new IEC 61850 architectures and existing DNP3 or Modbus infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US E-House Market |
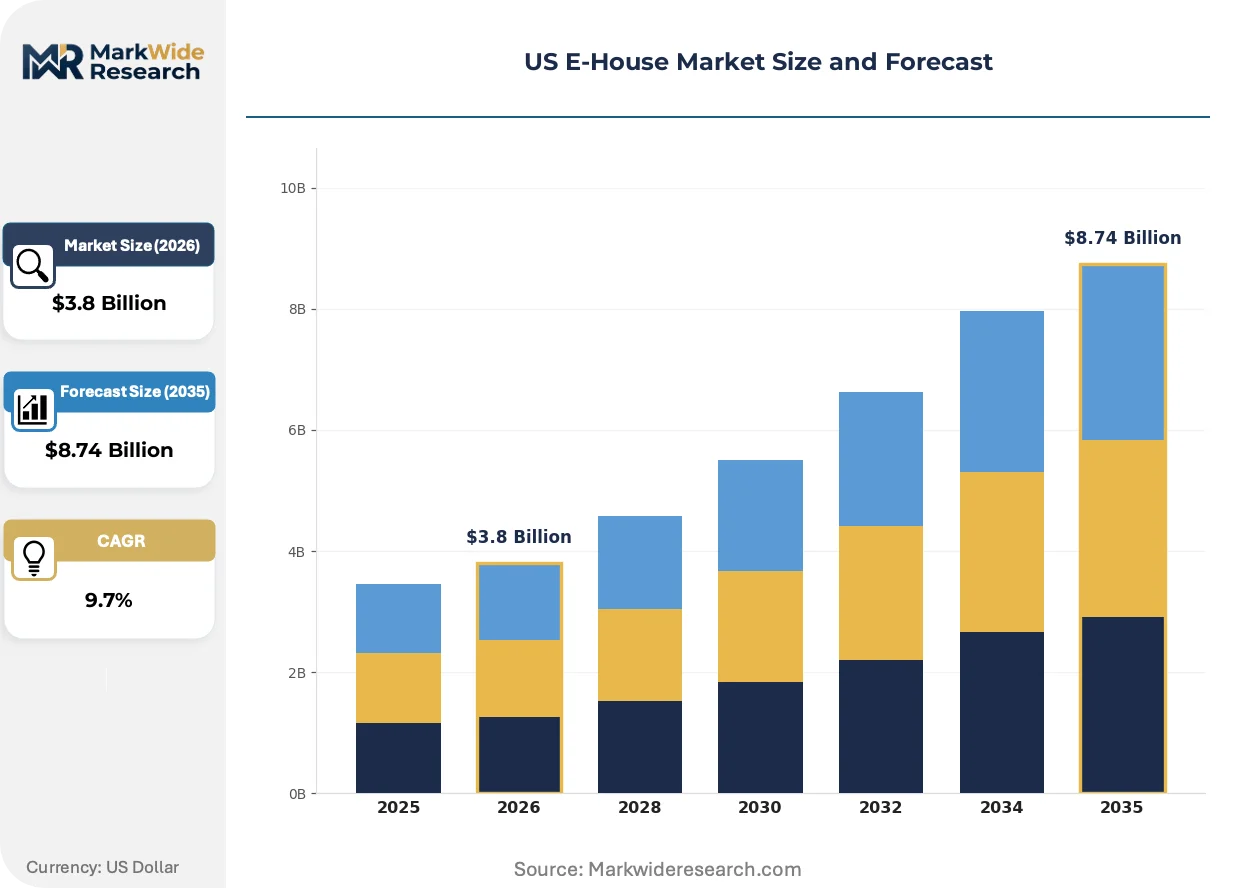
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular E-Houses, Portable E-Houses, Fixed E-Houses, Custom E-Houses Application: Power Generation, Oil & Gas, Mining, Construction Distribution Channel: Direct Sales, Distributors, Online Platforms, Dealers End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | ABB, Schneider Electric, Eaton, General Electric, Siemens, Powell Industries, BMarko Structures, Delta Star, Unit Electrical Engineering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US E-House Market Evolving Landscape
Digitalization and modularization are converging to redefine how electrical infrastructure is specified, manufactured, and commissioned. Factory-floor automation and embedded sensor architectures are displacing traditional build-test-ship sequences.
Vacuum interrupter technology is unifying medium-voltage switching functions previously separated by gas-insulated and air-insulated designs. Data center operators in Arizona and Texas are specifying vacuum-based E-Houses to eliminate SF6 handling complexity. This technology compression is unifying procurement specifications across hyperscale and utility buyer segments.
EPA's evolving SF6 emissions framework is compelling switchgear redesigns toward alternative insulation media. Manufacturers face accelerated R&D cycles to maintain product certifications under tightening environmental enforcement. Industrial buyers in the Permian Basin are piloting dry air and fluoronitrile formulations to preempt regulatory exposure.
Specification authority is migrating from general contractors to owner-engineers as repeat data center and solar developers internalize E-House technical standards. Engineering-procurement-construction firms are losing influence to direct utility and hyperscale procurement teams. This displacement concentrates most visibly in Northern Virginia where Dominion Energy and cloud operators maintain dedicated technical evaluation staff.
US E-House Market Segmentation
E-House procurement decisions hinge on project timeline pressure, site constraints, and standardization requirements. Buyers weigh factory-controlled quality against field flexibility, with each segment category reflecting distinct trade-offs between lead time, customization depth, and total installed cost.
Product Type:
Lead time sensitivity dominates buyer selection, with repeatability premiums compressing delivery windows for standardized configurations.
- Modular E-Houses:Pre-engineered enclosures with standardized switchgear and transformer configurations manufactured in repeatable production runs. Demand concentrates in Texas and Virginia utility-scale solar farms where developers face interconnection queue deadlines and need 12-16 week delivery cycles.
- Custom E-Houses:Site-specific engineered solutions accommodating non-standard dimensions, legacy equipment integration, or extreme environmental ratings. Procurement clusters in Arizona data center retrofits where space constraints and existing substation footprints demand dimensional flexibility at premium pricing.
- Portable E-Houses:Skid-mounted transportable units designed for temporary power or mobile substation applications. Mining operations in Nevada and Arizona specify these for remote site electrification with relocation requirements.
- Fixed E-Houses:Permanent foundation-mounted installations for long-duration infrastructure assets. Oil and gas producers in the Permian Basin deploy these for midstream compressor stations with 30-year asset horizons.
Volume sits with Modular E-Houses; growth tilts toward Custom E-Houses as data center retrofits multiply.
Application:
End-use sector volatility shapes specification rigor, with uptime requirements driving protection system redundancy and enclosure environmental ratings.
- Power Generation:Utility-scale solar, wind, and gas turbine facilities requiring medium-voltage interconnection infrastructure. IRA tax credit deadlines accelerate procurement across Arizona and Texas where renewable developers face construction completion windows tied to incentive eligibility.
- Oil & Gas:Upstream drilling, midstream compression, and downstream refining applications demanding explosion-proof ratings and harsh environment durability. Permian Basin operators prioritize NEMA 4X enclosures with corrosion-resistant finishes for salt-laden atmospheric exposure.
- Mining:Surface and underground extraction operations requiring portable or semi-permanent electrical distribution. Nevada gold and copper producers specify ruggedized enclosures with enhanced seismic bracing for remote mountain sites.
- Construction:Temporary power for large infrastructure projects including highways, bridges, and commercial developments. Urban tunneling projects in California and New York procure rental-oriented portable units with rapid deployment capabilities.
Power Generation commands absolute volume; Oil & Gas delivers the steepest expansion trajectory behind Permian electrification intensity.
Distribution Channel:
Buyer sophistication and project scale determine channel selection, with direct relationships consolidating around repeat utility and hyperscale purchasers.
- Direct Sales:Manufacturer-to-end-user transactions for large-volume, technically complex orders. Dominion Energy and Arizona Public Service maintain dedicated procurement teams negotiating multi-unit utility contracts with factory acceptance testing protocols.
- Distributors:Electrical supply houses providing local inventory, credit terms, and logistics coordination. Regional distributors serve Texas and Arizona contractor markets where project bundling across multiple material categories reduces procurement friction.
- Online Platforms:Digital quotation and specification tools for standardized, smaller-scale orders. Industrial maintenance teams in the Midwest utilize these for replacement unit sourcing with documented lead time transparency.
- Dealers:Authorized representatives with territory-exclusive relationships providing local engineering support. Oil and gas producers in Louisiana and Oklahoma rely on dealer networks for field modification services and startup commissioning assistance.
Direct Sales capture the largest transaction values; Online Platforms are climbing the fastest as procurement digitization penetrates mid-market industrial buyers.
End User:
Asset ownership structure and regulatory exposure differentiate procurement priorities across customer categories.
- Utilities:Investor-owned utilities, municipal power departments, and rural electric cooperatives deploying transmission and distribution infrastructure. NERC CIP-014 physical security compliance drives standardized, pre-certified equipment purchases across Texas and Virginia grid expansion projects.
- Industrial:Manufacturing, chemical processing, and materials production facilities requiring on-site substations or power distribution centers. Reshoring initiatives in Arizona, Texas, and the Southeast accelerate demand for rapid-commission electrical infrastructure.
- Commercial:Data centers, hospitals, and large retail complexes with critical power reliability requirements. Northern Virginia hyperscale facilities specify E-Houses to compress 18-month construction cycles and meet utility interconnection schedules.
- Residential:Large master-planned communities and multi-family developments with centralized electrical distribution needs. Arizona and Nevada retirement community builders deploy compact E-Houses for aesthetic concealment and reduced footprint requirements.
Utilities anchor absolute volume; Industrial end users gain share fastest behind manufacturing reshoring and onshoring momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of E-House units concentrates in Gulf Coast and Midwest fabrication hubs, while consumption clusters in states with hyperscale data center buildouts and utility-scale solar interconnection queues.
Texas
Utility-scale solar developers in West Texas face ERCOT interconnection deadlines that compress electrical infrastructure commissioning schedules. NERC CIP-014 physical security compliance drives standardized E-House procurement across transmission expansion projects. The Permian Basin anchors oil and gas demand for fixed E-House installations at midstream compressor stations.
Virginia
Hyperscale data center operators in Loudoun County specify modular E-Houses to meet 18-month facility construction cycles tied to Dominion Energy interconnection agreements. State-level clean energy mandates under the Virginia Clean Economy Act accelerate utility-scale solar procurement requiring rapid substation deployment. Northern Virginia hosts the densest concentration of cloud computing electrical infrastructure investment.
Arizona
Phoenix-area data center clusters drive custom E-House demand where space constraints and existing substation footprints require dimensional flexibility. Arizona Public Service interconnection queue reforms compress project timelines for solar-plus-storage developers. Tucson and Phoenix metro areas concentrate manufacturing reshoring initiatives requiring on-site substation infrastructure.
California
CPUC resource adequacy requirements and SB-100 clean energy targets accelerate battery energy storage system integration with E-House switchgear configurations. Urban tunneling projects in Los Angeles and San Francisco procure portable units for temporary power with rapid deployment capabilities. Central Valley solar farms face interconnection bottlenecks that favor factory-integrated electrical infrastructure.
Nevada
Gold and copper mining operations in northern Nevada specify ruggedized E-Houses with enhanced seismic bracing for remote mountain site electrification. NV Energy transmission expansion projects incorporate modular substations to serve growing industrial load centers. Las Vegas retirement community builders deploy compact units for aesthetic concealment in master-planned developments.
US E-House Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the E-House procurement landscape, creating a tiered market structure where scale advantages clash with customization agility. The vendor base segments into integrated electrical equipment manufacturers, specialized enclosure fabricators, and regional system integrators. Strategic moves concentrate on factory automation investments and geographic proximity to demand clusters.
Among diversified electrical equipment manufacturers, ABB, Schneider Electric, and Eaton occupy positions that span switchgear production through integrated E-House delivery. These companies exemplify the scale-driven archetype, leveraging captive transformer and protection relay portfolios to anchor large utility contracts. Their market presence reflects backward integration into enclosure fabrication and control system engineering.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton |
| General Electric |
| Siemens |
| Powell Industries |
| BMarko Structures |
| Delta Star |
| Unit Electrical Engineering |
| Others |
Value Network & Pricing Analysis
Vacuum interrupter adoption across medium-voltage switchgear designs is compressing manufacturing cost curves while concentrating certified production among Gulf Coast fabricators with NEMA-rated welding capabilities. This technology transition simultaneously reduces SF6 compliance burdens and tightens supplier qualification thresholds, reshaping how procurement teams evaluate total cost of ownership.
Pricing Analysis
Margin tightening in standard modular configurations reflects copper and electrical steel commodity volatility pressuring fixed-price utility contracts. Three-tier pricing structure across premium certified, standard pre-engineered, and economy portable units differentiates by NERC compliance depth and factory acceptance testing rigor. Cost-down pressure on economy portable units accelerates because mining operators in Nevada prioritize rapid deployment over long-term service bundling. Data center developers in Virginia exhibit lowest price sensitivity, accepting premium positioning for 18-month construction cycle guarantees.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale buyer demand across Texas and Virginia, bypassing traditional electrical distributor markups for multi-unit transmission expansion awards. Domestic production clusters in Texas, Louisiana, and Ohio with certified NCCER electrical assembly capabilities. Transformer core laminations and medium-voltage vacuum interrupters remain critical inputs with concentrated sourcing. Single-source vulnerability in specialized enclosure fabrication creates procurement risk for rapid-turnaround solar interconnection projects. Distribution runs through manufacturer-direct relationships for utility-scale orders, with regional distributors serving contractor markets in Arizona and the Permian Basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US E-House market is consolidating around manufacturers with captive transformer production and NERC pre-certification capabilities, as EPA SF6 enforcement and interconnection queue deadlines eliminate smaller fabricators lacking environmental compliance infrastructure.
For Market Incumbents: Acquire certified enclosure fabrication capacity in Texas and Arizona to secure proximity to utility-scale solar and data center demand clusters. Defend market position by accelerating vacuum interrupter R&D to preempt EPA regulatory exposure on legacy SF6 switchgear lines. Backward integration into electrical steel core processing mitigates commodity margin volatility on transformer assemblies. For New Entrants and Emerging Players: Launch via online specification platforms targeting mid-market industrial maintenance teams in the Midwest with standardized replacement unit catalogs. White-space opportunities concentrate in Arizona custom E-House retrofits where space-constrained data center expansions demand dimensional flexibility. Battery energy storage integration represents the most penetrable application segment for hybrid switchgear-BESS configurations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified electrical equipment conglomerates seeking NERC-certified production assets. Long-term viability favors manufacturers with digital twin service layering capabilities creating recurring revenue beyond equipment sales. Monitor EPA SF6 enforcement timeline acceleration as the critical inflection signal for technology transition winners and losers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Gulf Coast Fabrication Hubs | Texas and Louisiana facilities with NEMA-rated welding capabilities capture utility-scale solar interconnection demand. |
| Backward Integration into Transformer Core Production | In-house electrical steel processing insulates margins from commodity volatility on utility fixed-price contracts. |
| Digital Twin Service Layering | IoT-enabled predictive maintenance contracts with Dominion Energy and Arizona Public Service create recurring revenue streams. |
| Vacuum Interrupter Technology Transition | SF6-free switchgear designs preempt EPA enforcement exposure while unifying procurement specifications across hyperscale and utility segments. |
| NERC CIP-014 Pre-Certification Investment | Pre-certified physical security configurations accelerate site acceptance for Texas ERCOT transmission expansion projects. |
Research Methodology
Document review covered FERC interconnection queue filings, EIA power plant construction databases, and NERC reliability standard enforcement records, complemented by interviews with utility planning officers, EPC contractor procurement leads, data center facility engineers, and Gulf Coast enclosure fabricator operations managers. Primary fieldwork with Arizona Public Service and Dominion Energy procurement teams validated secondary data on specification migration trends. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure disclosures.
Segment-level projections across modular, custom, portable, and fixed product types incorporated power generation capacity additions, oil and gas Permian Basin electrification intensity, and data center construction pipeline tracking. Modeled variables included IRA tax credit eligibility windows, state-level NEC adoption cycles, and NERC compliance deadline schedules. CAGRs were derived from regression analysis of historical utility procurement patterns against interconnection queue depth metrics.
Commodity price volatility, EPA SF6 regulatory acceleration, and interconnection queue reform implementation delays are the dominant revision risks to base case assumptions. Forecasts reflect documented assumptions on technology transition timelines and utility procurement centralization trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
E House Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
France Condominiums and Apartments Market