
 France Residential Real Estate Market | 2026-2036
France Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
France Residential Real Estate Market Insights
Traditional sales channel hierarchies in French residential real estate is fragmenting as digital platforms and hybrid advisory models erode the dominance of conventional agency networks. Nexity leverages its integrated development-to-management pipeline to control project timelines from land acquisition through delivery. BNP Paribas Real Estate anchors institutional capital flows into residential portfolios, sustaining liquidity for large-scale urban regeneration. Kaufman & Broad differentiates through standardized modular construction techniques that compress build schedules across its regional developments.
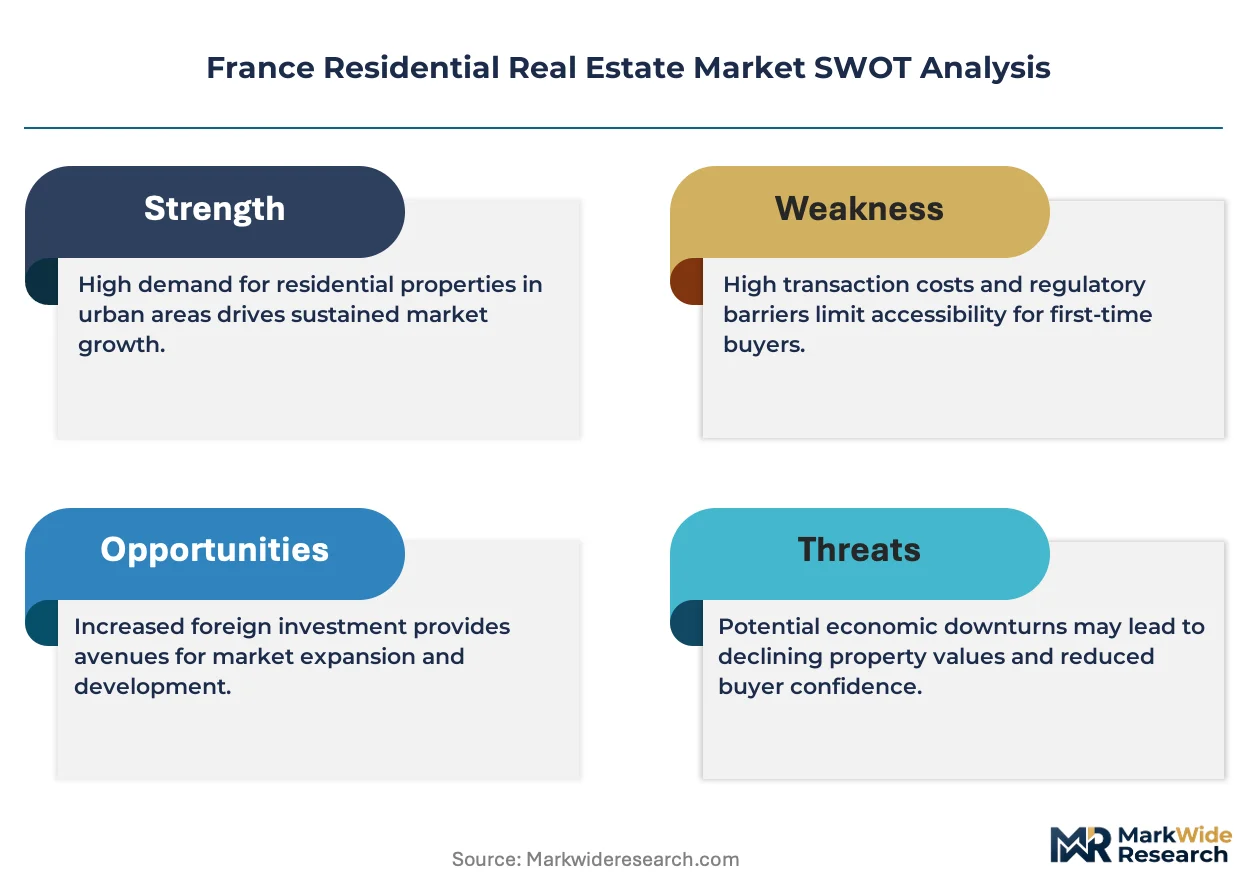
France residential real estate encompasses all dwelling units intended for non-commercial habitation, including apartments, detached houses, semi-detached houses, and townhouses, typically constructed with reinforced concrete frameworks, timber framing, or masonry systems meeting RE2020 thermal performance thresholds and designed for permanent or seasonal occupancy. The primary commercial purpose centers on providing shelter assets traded through ownership or leasehold arrangements, generating returns via capital appreciation or rental yield streams. Apartment stock dominates transaction volumes in Paris and Lyon, where land scarcity elevates per-square-meter valuations and compresss yield spreads. First-time buyer segments face structural affordability constraints as deposit requirements and mortgage qualification criteria tighten, pushing demand toward mid-range price brackets in secondary cities. Luxury and high-end inventory concentrates in coastal Provence-Alpes-Côte d'Azur locations and select Paris arrondissements, where foreign capital inflows sustain premium pricing.
ANSM and CNIL frameworks govern data handling in digital property transactions, while RE2020 building codes enforced by regional prefectures mandate progressive carbon intensity reductions in new construction. These regulatory layers elevate compliance costs for developers and reshape material specifications across supply chains. Stakeholders must monitor evolving ESG disclosure obligations under EU CSRD alignment and local zoning liberalization experiments to anticipate where regulatory relief or constraint will next redirect development capital.
Market Dynamics
France's residential real estate sector is undergoing a structural recalibration as RE2020 carbon intensity mandates compress development timelines and force material substitution across concrete and timber supply chains. Developers now face simultaneous pressure to deliver housing units while decarbonizing embodied emissions in foundations and superstructures.
Growth Catalysts
- RE2020 Thermal Performance Mandates:Stricter envelope standards are accelerating demand for cross-laminated timber and low-carbon concrete alternatives, creating procurement premiums for certified suppliers.
- Île-de-France Population Concentration:Persistent net migration into Greater Paris sustains transaction velocity for mid-density apartment stock despite affordability headwinds.
- Digital Transaction Platforms:Hybrid advisory models combining algorithmic valuation with localized expertise are compressing search-to-close timelines for first-time buyer segments.
Market Restraints
- Construction Input Cost Volatility:Reinforcement steel and engineered timber prices fluctuate with Nordic supply disruptions, squeezing gross margins on fixed-price development contracts.
- Mortgage Qualification Tightening:French banking regulators have elevated stress-test thresholds for debt-to-income ratios, excluding younger households from prime urban locations.
- Land Scarcity in Target Municipalities:Zoning conservatism in high-demand arrondissements limits greenfield pipeline replenishment for volume developers.
Strategic Opportunities
- Modular Prefabrication Convergence:Factory-built volumetric units integrated with building-integrated photovoltaics offer 30-40% schedule compression versus traditional masonry construction.
- Secondary City Price Tiers:Lyon, Bordeaux, and Nantes present undersupplied mid-market segments where land costs permit attainable pricing for excluded first-time buyers.
- CSRD-Aligned ESG Disclosure:Early compliance with EU corporate sustainability reporting standards positions developers for green bond issuance and institutional capital allocation.
Industry Challenges
- Certified Craftsman Shortages:RE2020-compliant envelope installation and heat pump integration require specialized labor pools that training institutes have not yet scaled.
- Supply Chain Reconfiguration Friction:Shifting from regional concrete suppliers to mass timber fabricators demands new logistics partnerships and quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Residential Real Estate Market |
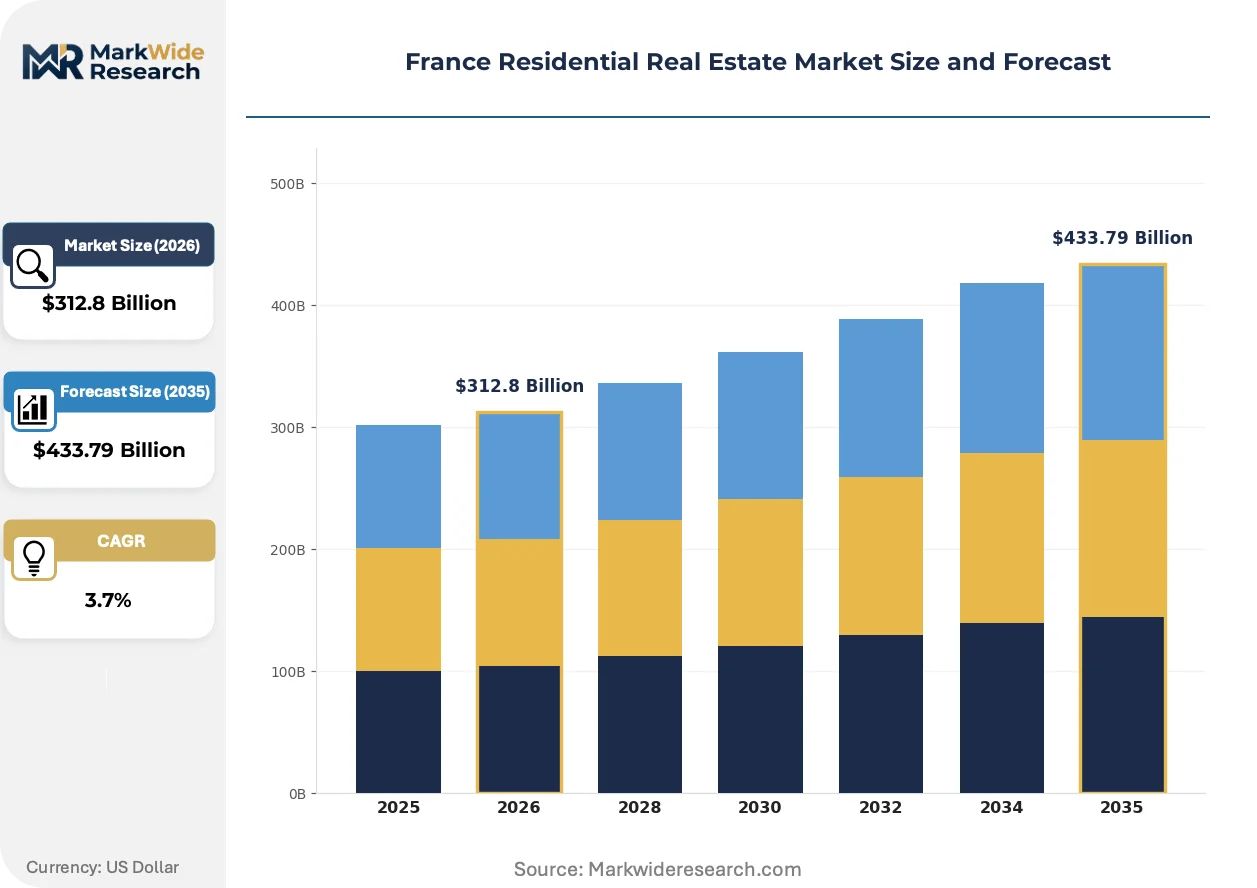
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $433.79 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartment, Detached House, Semi-Detached House, Townhouse Buyer Type: First-Time Buyer, Investor, Upsizer, Downsizer Price Range: Affordable, Mid-Range, Luxury, High-End Sales Channel: Real Estate Agency, Online Listing, Auction, Private Sale |
| Companies Covered | Nexity, BNP Paribas Real Estate, Altarea Cogedim, Kaufman & Broad, Advenis, Citya Descampiaux, Nacarat, JLL France, Bouygues Immobilier, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Residential Real Estate Market Trends and Innovations
Digital tooling and prefabrication methods are compressing traditional development cycles while regulatory carbon accounting forces transparency through construction supply chains. Three distinct vectors are restructuring how residential assets are delivered and transacted.
Mass timber engineering is rendering obsolete conventional reinforced concrete frameworks for mid-rise residential construction. Developers in Lyon and Bordeaux are specifying glued-laminated beams and cross-laminated floor plates to meet RE2020 embodied carbon thresholds. This substitution is compressing foundation loads and enabling faster superstructure assembly on constrained urban sites.
ANSM and CNIL data governance frameworks are mandating encrypted handling of biometric identity verification in digital property transactions. Notaries and hybrid platforms must now implement segmented data architectures that separate financial qualification data from property search histories. First-time buyer segments face additional friction layers during mortgage pre-approval workflows.
Institutional rental demand is fragmenting traditional ownership pathways as pension funds and REITs acquire stabilized residential blocks. This capital rotation is crowding individual buyers from core Paris arrondissements and compressing yield spreads to levels that challenge private landlord economics. Secondary cities see parallel but delayed penetration of this ownership-to-rental shift.
France Residential Real Estate Market Segmentation
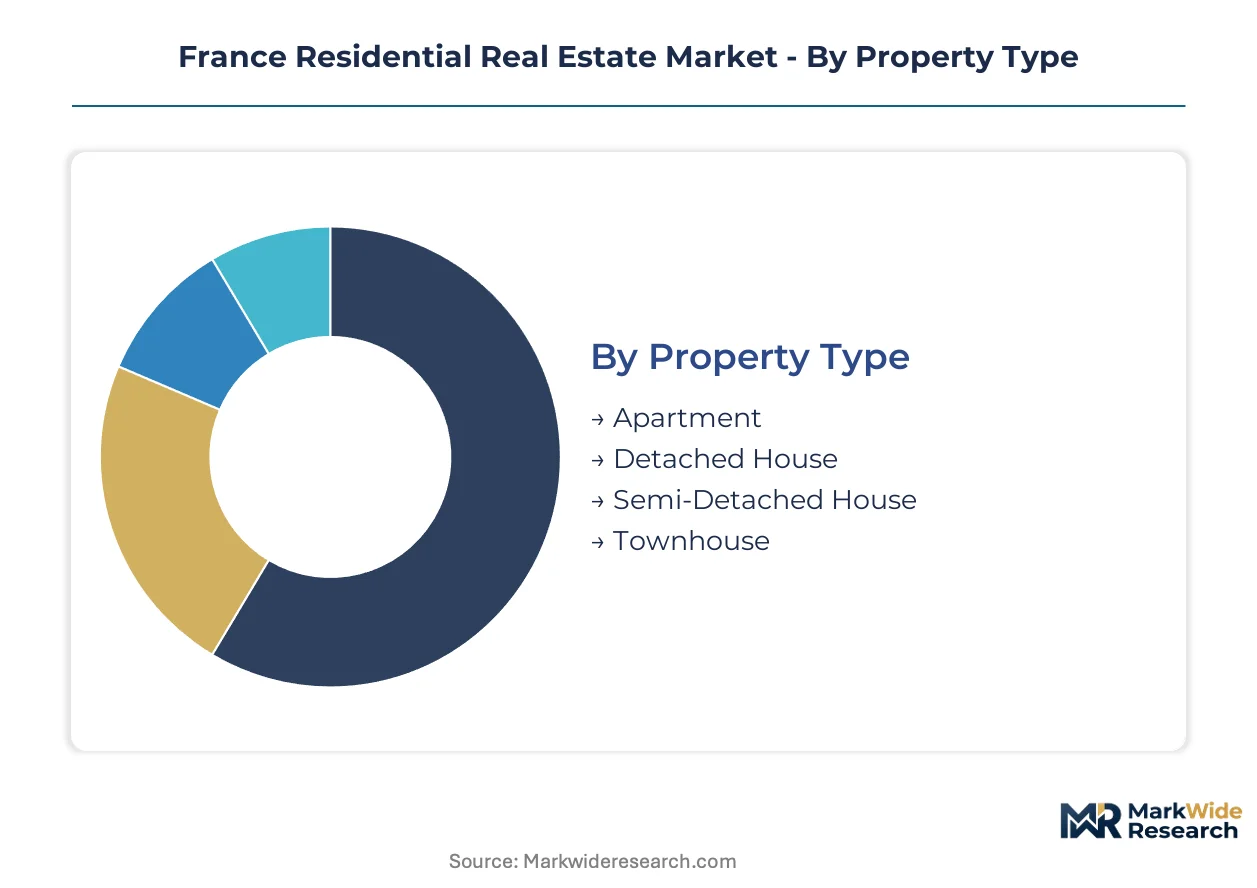
Segmentation reveals how distinct buyer motivations and property characteristics fragment transaction flows across French residential markets. Understanding these divides exposes where capital concentrates and where regulatory pressure reshapes competitive positioning.
Property Type:
Structural form determines construction methodology, carbon compliance burden, and urban density potential across French development pipelines.
- Apartment:Multi-unit structures dominate Paris, Lyon, and Marseille transaction volumes. RE2020 thermal mandates favor mid-rise concrete and timber hybrid construction in Île-de-France, where land scarcity compresses unit footprints and elevates per-square-meter valuations.
- Detached House:Standalone dwellings concentrate in exurban rings around Bordeaux, Nantes, and Toulouse. Single-family buyers face acute affordability constraints as mortgage stress-test thresholds exclude younger households from peripheral communes with inadequate transit links.
- Semi-Detached House:Paired dwellings balance privacy with density in secondary city suburbs. Builders favor standardized modular techniques to compress delivery schedules while meeting regional prefecture envelope standards.
- Townhouse:Terraced row housing persists in historic cores and new urbanist developments. Mediterranean coastal municipalities restrict greenfield townhouse approvals, channeling demand toward rehabilitation of existing stock.
Apartment stock commands the established base. The steepest expansion runs through detached house segments in exurban corridors beyond mortgage-constrained prime zones.
Buyer Type:
Purchaser motivation stratifies financing structures, holding periods, and sensitivity to interest rate movements across French mortgage markets.
- First-Time Buyer:Entry-level purchasers face structural exclusion as debt-to-income ratio thresholds tighten. Digital hybrid platforms compress search-to-close timelines for this segment, though deposit requirements push demand toward mid-range brackets in secondary cities.
- Investor:Institutional and private landlords acquire stabilized blocks for rental yield streams. Pension fund capital rotation crowds individual investors from core Paris arrondissements, compressing yield spreads below private landlord economics.
- Upsizer:Households trading toward larger units drive volume in family-oriented communes with school quality premiums. Transaction timing correlates with equity release from appreciated starter properties.
- Downsizer:Empty-nesters reduce maintenance burdens and unlock capital for retirement. This segment sustains demand for smaller apartments in well-serviced urban centers with healthcare proximity.
First-time buyers anchor transaction velocity despite qualification headwinds. Investor acquisition is expanding most quickly as institutional capital reweights toward residential real assets.
Price Range:
Cost tiers align with construction material grades, location premiums, and buyer financing capacity across French metropolitan markets.
- Affordable:Subsidized and social housing segments operate under strict income eligibility and rent control frameworks. Public-private partnerships dominate supply, with RE2020 compliance adding cost layers that strain municipal budgets.
- Mid-Range:Mass-market segments concentrate demand from excluded first-time buyers pushed outward by prime affordability constraints. Lyon, Bordeaux, and Nantes present undersupplied tiers where land costs permit attainable pricing.
- Luxury:Premium inventory clusters in coastal Provence-Alpes-Côte d'Azur locations and select Paris arrondissements. Foreign capital inflows sustain pricing decoupled from domestic mortgage markets.
- High-End:Ultra-premium assets command bespoke construction and concierge services. Notarial transaction volumes remain thin but generate disproportionate fee revenue and cross-selling opportunities.
Mid-range stock commands the established base. The steepest expansion runs through luxury segments fueled by non-resident capital seeking eurozone stability.
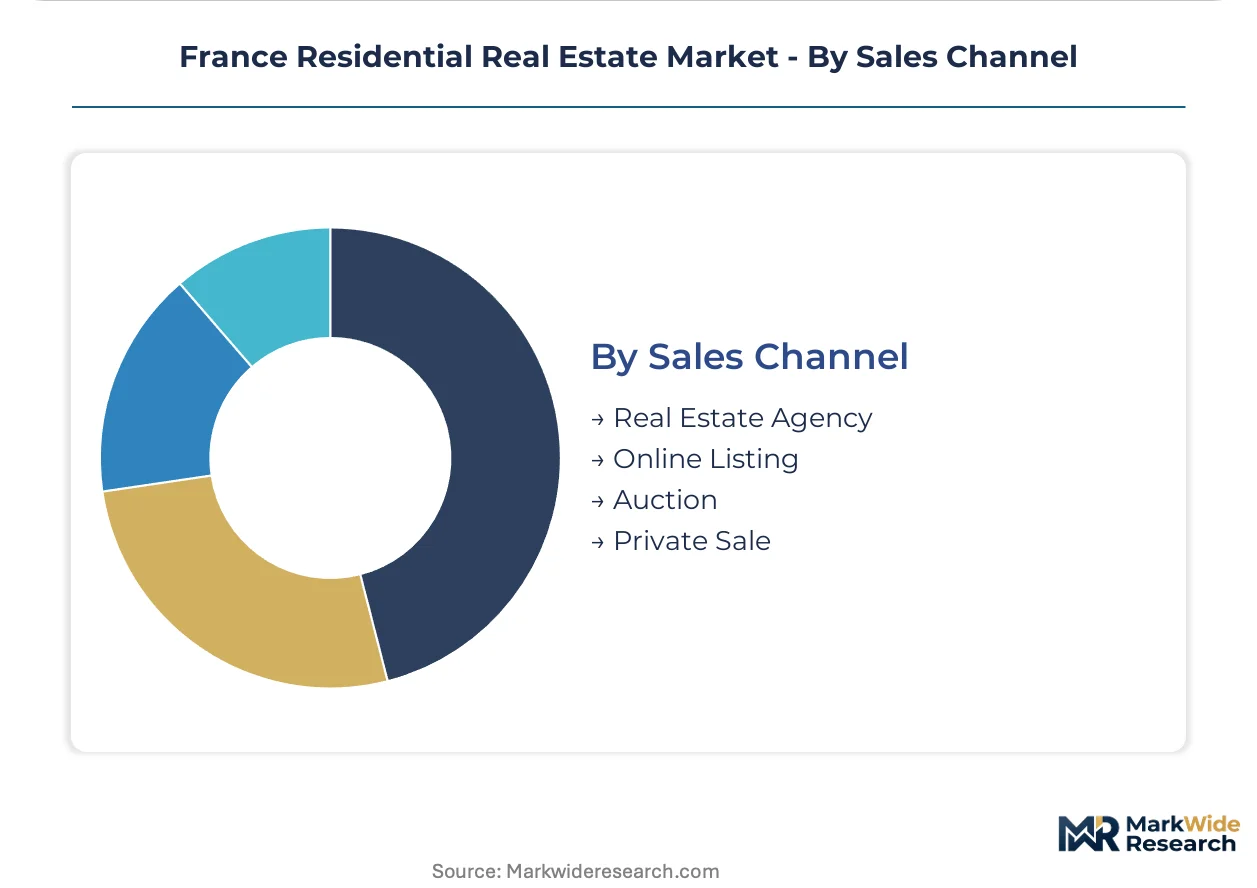
Sales Channel:
Transaction pathways determine fee structures, data governance obligations, and buyer-seller matching efficiency across French property markets.
- Real Estate Agency:Traditional networks retain dominance in high-touch segments requiring localized market knowledge. Agency commissions face compression as digital alternatives erode fee transparency.
- Online Listing:Algorithmic valuation platforms aggregate inventory and standardize property presentations. ANSM and CNIL frameworks mandate encrypted biometric identity handling, adding friction layers to pre-approval workflows.
- Auction:Accelerated disposal mechanisms serve distressed sellers and unique assets requiring price discovery. Notarial oversight ensures regulatory compliance for title transfer.
- Private Sale:Direct transactions bypass intermediary fees but demand sophisticated legal navigation. Usage concentrates among repeat buyers with established notarial relationships.
Real estate agency channels command the established base. Online listing platforms are gaining share fastest as first-time buyer segments prioritize search efficiency over advisory depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LGV Sud-Est high-speed rail corridor and its extensions into Rhône-Alpes and Provence underpin residential demand patterns across eastern France. These trunk lines compress commute times from secondary cities into Paris and Lyon, redrawing viable catchment areas for daily labor migration.
Île-de-France
Grand Paris Express metro construction and orbital rail extensions are activating peripheral communes for residential densification. RE2020 thermal standards enforced by regional prefectures are elevating construction costs for mid-rise apartment stock in Seine-Saint-Denis and Val-de-Marne. Developers concentrate activity around Saint-Denis Pleyel and Champigny-sur-Marne stations where land assembly permits scalable projects.
Auvergne-Rhône-Alpes
Lyon's Part-Dieu business district expansion and Grenoble's semiconductor cluster are drawing skilled households into the metropolitan orbit. The Auvergne-Rhône-Alpes regional council operates housing solidarity funds that subsidize first-time buyer deposits in qualifying communes. Construction activity clusters in Villeurbanne and Vénissieux where brownfield remediation unlocks parcels for mid-density development.
Provence-Alpes-Côte d'Azur
Nice Côte d'Azur Airport connectivity and Monaco's spillover demand sustain premium pricing in Alpes-Maritimes coastal municipalities. The Loi Littoral restricts greenfield construction within 100 meters of shorelines, channeling development toward inland hill towns and rehabilitation of existing stock. Aix-en-Provence and Marseille's Euroméditerranée district concentrate volume housing for healthcare and logistics workforces.
Nouvelle-Aquitaine
Bordeaux's LGV connection to Paris and the Atlantic port complex are accelerating population inflow from constrained Île-de-France markets. The Nouvelle-Aquitaine region administers land value capture mechanisms that recycle transport infrastructure gains into affordable housing programs. Developers target Eysines and Mérignac for detached and semi-detached family housing where land costs permit mortgage-accessible pricing.
Hauts-de-France
Lille's Eurostar and TGV hub position and proximity to Belgian labor markets sustain cross-border residential demand. The Hauts-de-France prefecture applies differentiated RE2020 enforcement timelines that grant temporary compliance flexibility for social housing providers. Roubaix and Tourcoing are seeing rehabilitation-led densification as municipal planners relax height restrictions near transit nodes.
France Residential Real Estate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying modular units and carbon-compliant materials. The French residential development sector exhibits tiered consolidation where vertically integrated developers control land-to-delivery pipelines while specialized contractors occupy niche technical segments. Three archetypes dominate: development-management platforms with captive construction arms, institutional capital allocators sourcing stabilized portfolios, and modular prefabrication specialists compressing build schedules. Competitive moves center on land banking in transport-adjacent municipalities and backward integration into low-carbon material supply chains.
Within the integrated development tier, Nexity and Bouygues Immobilier exemplify platform operators controlling project timelines from site acquisition through warranty periods. Kaufman & Broad occupies a position among standardized construction specialists leveraging modular techniques across regional footprints. These three entities anchor distinct competitive vectors: land pipeline depth, manufacturing scale, and institutional capital relationships respectively.
| Leading Market Players |
|---|
| Nexity |
| BNP Paribas Real Estate |
| Altarea Cogedim |
| Kaufman & Broad |
| Advenis |
| Citya Descampiaux |
| Nacarat |
| JLL France |
| Bouygues Immobilier |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Nordic mass timber fabrication is elevating procurement premiums for RE2020-compliant developers while compressing gross margins on fixed-price contracts across Île-de-France and Auvergne-Rhône-Alpes. This utilization squeeze forces developers toward alternative material sourcing and accelerates backward integration into captive supply chains.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with Nexity and Bouygues Immobilier extracting preferential rates on cross-laminated timber through multi-project offtake commitments. Price differentiation hinges on certification grade for low-carbon concrete alternatives and geographic delivery cost from Nordic versus domestic fabricators. Cost compression in mid-range apartment stock is intensifying because mortgage stress-test thresholds exclude price-sensitive first-time buyers from prime locations. Institutional investors exhibit least price sensitivity, absorbing premium valuations for stabilized Paris rental blocks, while individual landlords face yield spreads that challenge private economics.
Supply Chain Analysis
Contract-manufacturing concentration sits with Austrian and German mass timber fabricators supplying glulam beams and CLT floor plates to French developers. Geographic supply concentration draws from Nordic forestry operations, Austrian engineered wood plants, and domestic low-carbon concrete batching facilities near Lyon and Bordeaux. Raw material dependencies rest on spruce and pine feedstock from Scandinavian sustainable forestry, cement clinker with reduced kiln emissions, and reinforcement steel subject to energy-cost volatility. Single-source vulnerability runs through Nordic timber suppliers exposed to shipping route disruptions. Distribution runs through regional prefabrication hubs that stage volumetric units for final-mile delivery to constrained urban sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's residential development sector sits in early-cycle expansion as RE2020 regulatory mandates force material substitution and create first-mover advantages for certified suppliers. Modular prefabrication adoption is penetrating beyond pilot projects into scaled deployment, opening white-space for technical specialists.
For Market Incumbents: Insulate land pipeline positions in transport-adjacent municipalities through preemptive zoning engagement and option structures on brownfield parcels. Secure captive supply of mass timber through equity stakes in Austrian fabricators or domestic joint ventures, countering substitution risk from emerging modular specialists. Deepen relationships with regional prefectures on RE2020 compliance timelines to accelerate permitting velocity versus competitors. For New Entrants and Emerging Players: Secondary city corridors around Nantes and Bordeaux present geographic underpenetration where land costs permit mortgage-accessible pricing for excluded first-time buyer segments. Target mid-range detached and semi-detached housing in exurban rings with standardized modular techniques that compress delivery schedules. Pursue municipal partnership structures that recycle land value capture into affordable housing programs, securing pipeline visibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mass timber-integrated development platforms as fabrication equipment and quality assurance protocols demand upfront investment. Long-term viability favors developers with backward integration into low-carbon material supply and scalable land banking in Grand Paris Express catchment zones. Acquisition screening should prioritize modular prefabrication specialists with regional manufacturing footprints. Monitor quarterly permitting velocity from regional prefectures as inflection indicator for supply pipeline health.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Timber Supply Agreement | Secures RE2020-compliant material streams from Nordic fabricators for mid-rise developments. |
| Land Banking in Transit Corridors | Positions developers for Grand Paris Express activation around Saint-Denis Pleyel and Champigny-sur-Marne. |
| Modular Manufacturing Scale-Up | Compresses build schedules through factory-built volumetric units with integrated photovoltaics. |
| CSRD-Aligned ESG Disclosure | Enables green bond issuance and institutional capital allocation from pension fund investors. |
| Municipal Partnership Structure | Recycles transport infrastructure gains into affordable housing programs in Nouvelle-Aquitaine. |
Research Methodology
Initial hypotheses were tested against primary input from development executives, regional prefecture planning officers, mortgage underwriters at French banking groups, and modular fabrication plant managers, then refined through secondary validation. Bottom-up triangulation combined notarial transaction databases, RE2020 compliance filings with regional prefectures, and customs records on mass timber imports. Top-down cross-checks applied national housing production statistics and institutional investment flow tracking from REIT disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling transaction velocity against construction permit issuance and household formation rates. Segmentation dimensions included property type, buyer motivation, price tier, and sales channel, with regional regulatory cluster as an added dimension reflecting differentiated RE2020 enforcement timelines. CAGRs were derived from trend extrapolation of transaction volumes and value aggregation, calibrated against mortgage qualification threshold shifts and material cost indices.
The forecast holds incumbent behavior within observed patterns; aggressive land assembly moves by institutional capital allocators or accelerated modular adoption by emerging developers would shift outcomes beyond modeled ranges. Quarterly review of permitting velocity from regional prefectures, mass timber import volumes, and mortgage origination rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Egypt Residential Real Estate Market