
 Vietnam Residential Real Estate Market | 2026-2036
Vietnam Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Residential Real Estate Market Analytics
Aluminum composite panel cladding is decoupling from traditional ceramic tile facades as developers chase faster construction cycles and lighter structural loads. Vinhomes leverages captive concrete supply chains to compress delivery timelines across its mega-project portfolio. Novaland Group differentiates through integrated township planning that bundles residential units with retail and education infrastructure. Khang Dien House anchors its position in mid-range townhouses across Ho Chi Minh City's eastern corridor, where land scarcity intensifies.
Vietnam residential real estate encompasses privately owned housing structures—ranging from high-rise reinforced concrete condominiums to steel-frame townhouses and poured-concrete villas—designed for permanent or long-term occupancy, typically delivered through leasehold land rights with 50-to-70-year tenure structures. The primary commercial purpose centers on capital preservation and rental yield extraction for domestic investors, plus occupancy utility for end-user families. Condominiums dominate transaction volume in Hanoi and Ho Chi Minh City, where vertical density solves acute land constraints, while single-family homes retain premium pricing power in satellite provinces where plot availability persists. First-time buyers concentrate in the installment plan and mortgage loan channels, yet cash purchases still command developer discounts and priority unit selection, creating a bifurcated payment ecosystem.
The Ministry of Construction enforces fire safety and structural load standards through national building codes, while provincial People's Committees issue land-use certificates that gate project legality. The State Bank of Vietnam regulates mortgage-to-value ratios and foreign currency lending restrictions, directly constraining buyer leverage capacity. Developers must navigate both national green building directives and local infrastructure contribution requirements, which vary by province. Stakeholders should monitor whether the central bank relaxes foreign ownership caps or tightens developer escrow account rules, as either shift would reorder capital flows and inventory clearing velocity.
Market Dynamics
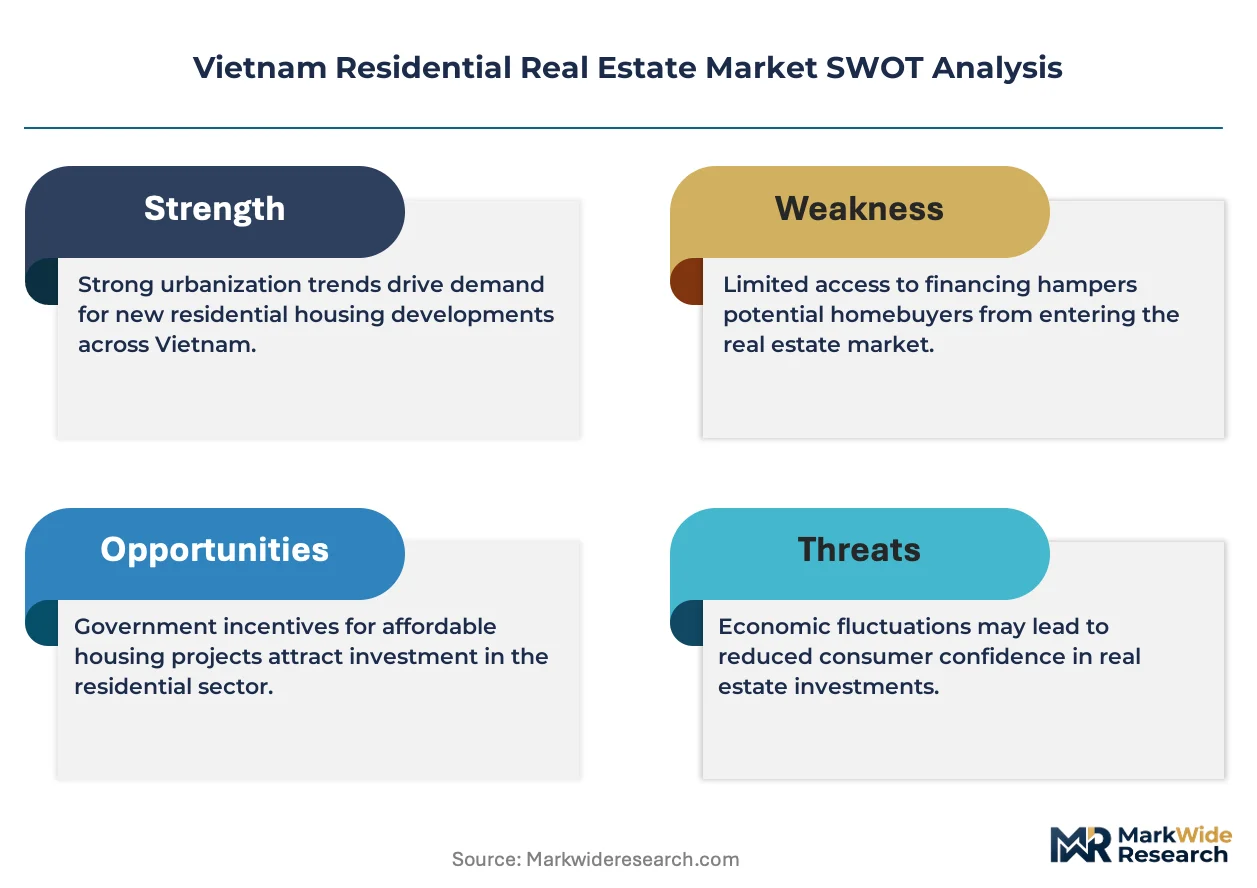
Young urban professionals in Ho Chi Minh City and Hanoi are compressing condominium sales cycles, while the Ministry of Construction's tightened fire safety standards force developers to absorb compliance costs or pass them through pricing.
Growth Catalysts
- Industrial Zone Expansion:Binh Duong and Dong Nai provinces are generating sustained worker housing demand as manufacturing clusters densify.
- Green Building Directives:National codes mandating energy-efficient envelopes are accelerating aluminum composite panel adoption over ceramic tile facades.
- Leasehold Structure Clarity:Standardized 50-to-70-year tenure documentation is reducing title risk perception among domestic investors.
Market Restraints
- Foreign Ownership Caps:The State Bank of Vietnam's currency lending restrictions constrain buyer leverage capacity for non-resident purchasers.
- Land Scarcity in Eastern HCMC:Plot availability constraints in Khang Dien House's core corridor are inflating land acquisition premiums.
- Escrow Account Rigidity:Developer capital lock-up requirements slow project recycling velocity and extend breakeven timelines.
Strategic Opportunities
- Integrated Township Models:Bundling residential units with retail and education infrastructure captures recurring revenue streams beyond unit sales.
- Captive Concrete Supply:Backward integration into ready-mix production compresses delivery timelines and insulates margin from commodity volatility.
- Mid-Range Townhouse Density:Ho Chi Minh City's satellite corridors offer underpenetrated volume for standardized product lines targeting first-time buyers.
Industry Challenges
- Fire Safety Compliance Timelines:Ministry of Construction certification delays for high-rise reinforced concrete structures extend pre-sales windows.
- Skilled Project Management Scarcity:Mega-project coordination across multiple provincial People's Committees strains developer execution capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Residential Real Estate Market |
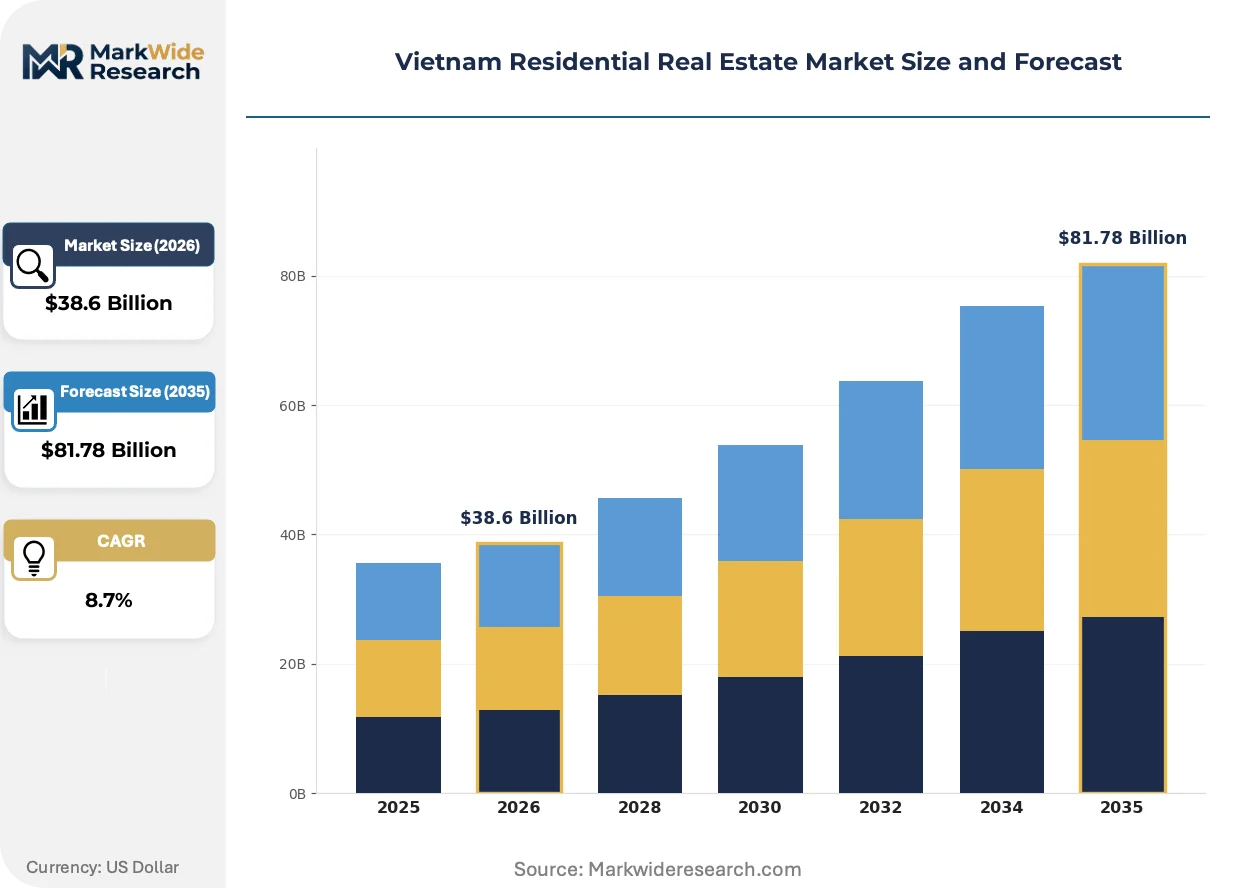
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominiums, Single-Family Homes, Townhouses, Villas Buyer Profile: First-Time Buyers, Investors, Foreign Nationals, Luxury Buyers Payment Structure: Cash Purchase, Mortgage Loan, Lease-to-Own, Installment Plans Development Stage: Pre-Construction, Under Construction, Completed, Renovated |
| Companies Covered | Phat Dat Corporation, Sun Group, Vinhomes, Hung Thinh Corporation, FLC Group, Novaland Group, Khang Dien House, SonKim Land, Dat Xanh Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Residential Real Estate Market Evolving Landscape
Construction material substitution and buyer financing fragmentation are actively restructuring how Vietnamese residential projects reach completion and how purchasers access inventory.
Aluminum composite panel cladding is overtaking traditional ceramic tile facades as the standard envelope solution for mid-rise and high-rise developments. Developers targeting faster construction cycles and lighter structural loads are specifying composite systems for 12-to-25-story towers. This material shift is compressing facade installation schedules by eliminating wet-trade curing periods.
The Ministry of Construction's tightened fire safety standards and green building codes are mandating enhanced structural load documentation and energy performance certification. Industrial consequence includes elevated compliance consulting costs and extended design review phases. High-rise reinforced concrete condominiums in Hanoi and Ho Chi Minh City are responding by front-loading regulatory engagement and pre-certifying material assemblies.
Buyer payment fragmentation is splitting the market between mortgage-dependent first-time purchasers and cash-ready investors seeking developer discounts. Installment plan channels are capturing price-sensitive entry buyers, while cash purchases command priority unit selection and bulk pricing. This bifurcation is most visible in Ho Chi Minh City's eastern corridor townhouses, where land scarcity intensifies competition for inventory access.
Vietnam Residential Real Estate Market Segmentation
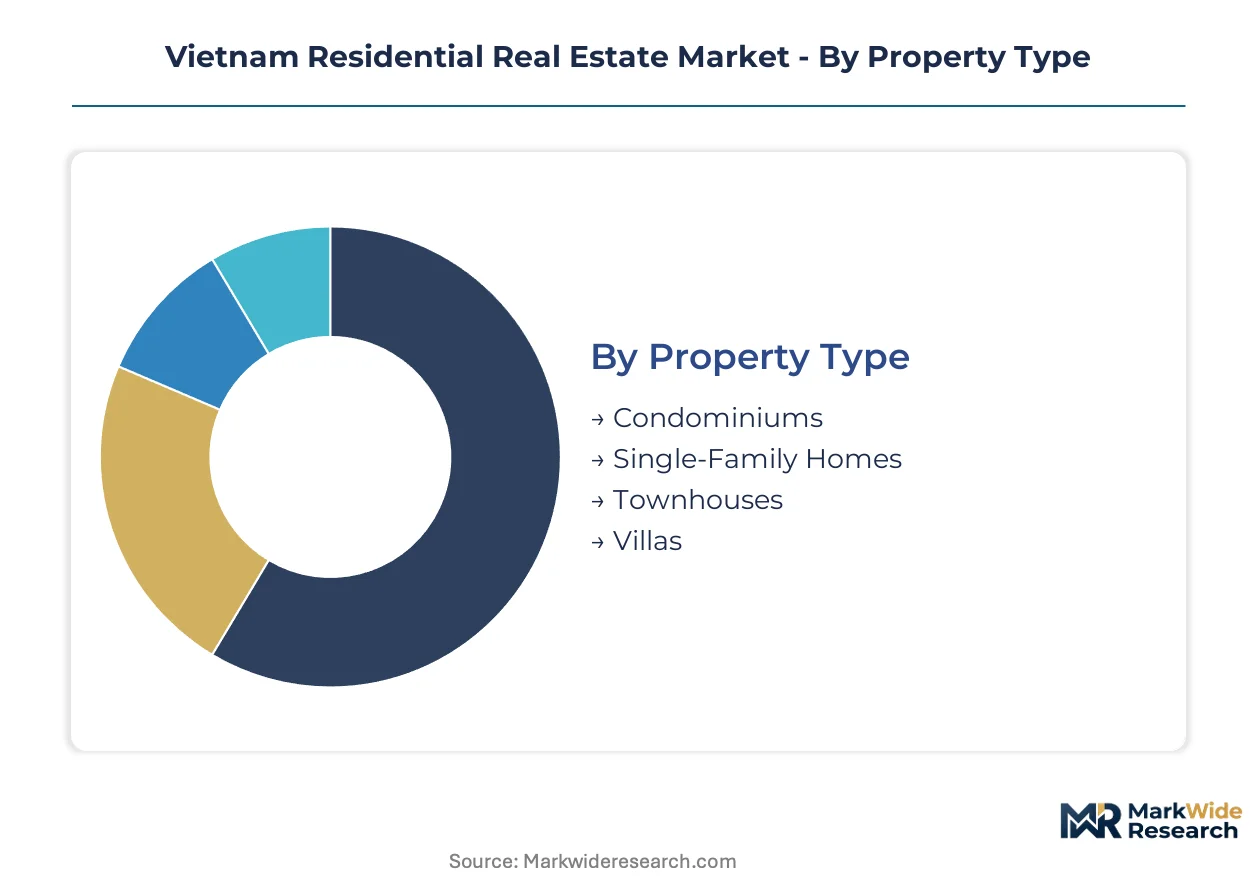
Segmentation in Vietnam's residential real estate reveals how payment capacity, tenure preferences, and construction timelines fragment buyer behavior across Ho Chi Minh City and Hanoi. Developers calibrate product mix and financing partnerships to match these divergent profiles.
Property Type:
Urban density pressures and land scarcity intensity separate buyers by vertical versus horizontal living preferences.
- Condominiums:High-rise reinforced concrete towers dominate transaction volume in Hanoi and Ho Chi Minh City, where vertical construction solves acute land constraints. Young urban professionals concentrate demand here, compressing sales cycles in districts with metro access.
- Single-Family Homes:Detached poured-concrete structures retain premium pricing power in satellite provinces where plot availability persists. Dong Nai and Binh Duong industrial zone workers drive demand for these units, prioritizing ground-floor living and vehicle parking.
- Townhouses:Steel-frame attached units fill the mid-range gap in Ho Chi Minh City's eastern corridor, where Khang Dien House anchors standardized product lines for first-time buyers facing land scarcity.
- Villas:Low-density poured-concrete estates target luxury buyers seeking privacy and garden space, concentrated in gated compounds outside central districts.
Volume sits with Condominiums; growth tilts toward Townhouses.
Buyer Profile:
Capital source and residency status determine which buyers access priority unit selection versus installment-dependent channels.
- First-Time Buyers:Price-sensitive entrants concentrate in mortgage loan and installment plan channels, particularly for townhouses in satellite corridors where land costs remain manageable.
- Investors:Cash-ready domestic purchasers command developer discounts and priority unit selection, extracting rental yields from completed condominiums in central Ho Chi Minh City districts.
- Foreign Nationals:Non-resident buyers face State Bank of Vietnam currency lending restrictions and ownership caps, constraining leverage capacity and limiting transaction participation.
- Luxury Buyers:High-net-worth individuals target villas and premium condominiums with integrated retail and education infrastructure, valuing township bundling over standalone units.
Investors dominate transaction velocity; First-Time Buyers are expanding most quickly.
Payment Structure:
Financing fragmentation splits the market between leverage-dependent purchasers and capital-preservation buyers.
- Cash Purchase:Full upfront payment commands priority unit selection and bulk pricing discounts, prevalent among investors and luxury buyers seeking immediate title transfer.
- Mortgage Loan:Bank-financed purchases dominate first-time buyer channels, with State Bank of Vietnam regulations constraining loan-to-value ratios and foreign currency lending.
- Lease-to-Own:Structured tenure arrangements align with Vietnam's 50-to-70-year leasehold land rights, reducing title risk perception among cautious domestic investors.
- Installment Plans:Developer-backed payment schedules capture price-sensitive entry buyers in pre-construction phases, spreading completion risk across construction timelines.
Cash Purchase anchors developer cash flow; Installment Plans gain share fastest.
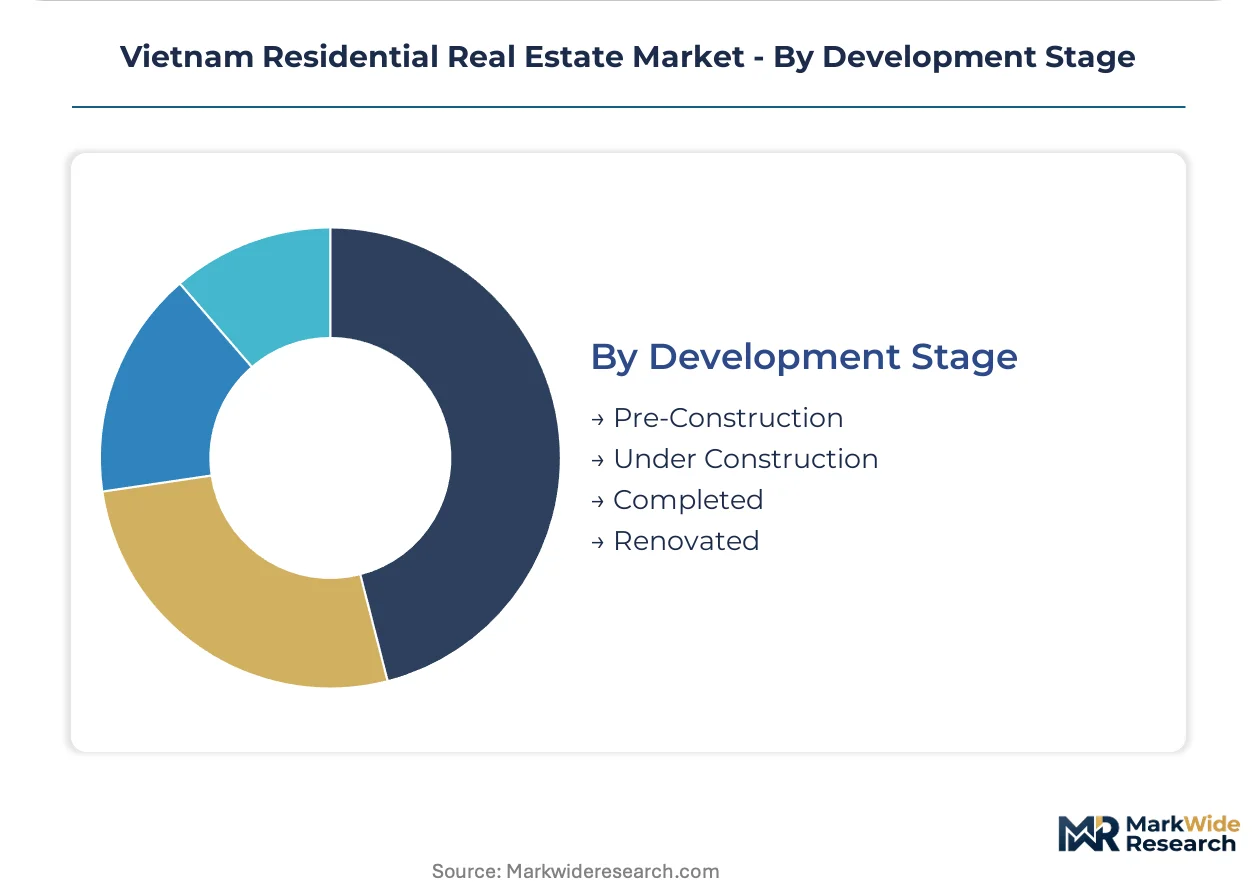
Development Stage:
Risk tolerance and capital commitment timing separate buyers across construction timelines.
- Pre-Construction:Early-phase purchases offer maximum pricing discounts but carry Ministry of Construction certification delays and fire safety compliance uncertainties for high-rise reinforced concrete structures.
- Under Construction:Mid-phase buyers trade some discount for reduced delivery risk, particularly in Vinhomes mega-projects where captive concrete supply chains compress timeline uncertainty.
- Completed:Finished inventory commands premium pricing but eliminates construction risk, preferred by investors seeking immediate rental yield extraction.
- Renovated:Retrofitted existing stock targets value-conscious buyers in land-scarce central districts where new supply is constrained.
Completed units dominate transaction volume; Pre-Construction shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Vietnam's southern industrial corridor, where manufacturing expansion feeds worker housing needs across Binh Duong and Dong Nai provinces. Ho Chi Minh City and Hanoi anchor transaction volume through young urban professional demand for vertical density. Provincial People's Committees issue land-use certificates that gate project legality, while the Ministry of Construction enforces fire safety standards nationwide.
Ho Chi Minh City Metro
Young urban professionals compress condominium sales cycles in Districts 2, 7, and 9, where metro access drives vertical density preferences. The Ministry of Construction's tightened fire safety standards extend pre-sales windows for high-rise reinforced concrete towers. Khang Dien House anchors standardized townhouse product lines in the eastern corridor, where land scarcity inflates acquisition premiums.
Hanoi Capital Region
Government and technology sector employees concentrate demand in western districts such as Ha Dong and Nam Tu Liem, prioritizing leasehold tenure security. The State Bank of Vietnam regulates mortgage-to-value ratios that constrain first-time buyer leverage in this high-cost corridor. Industrial zone workers from neighboring Bac Ninh and Vinh Phuc provinces commute into satellite townships.
Binh Duong Province
Manufacturing cluster densification around Thuan An and Di An generates sustained demand for single-family homes among factory workers and supervisors. Provincial People's Committees issue 50-year leasehold land-use certificates that reduce title risk perception for domestic investors. Developers target standardized housing products near Vietnam-Singapore Industrial Park and VSIP II.
Dong Nai Province
Long Thanh International Airport construction and adjacent logistics zones accelerate worker housing demand in Bien Hoa and Long Thanh districts. The Ministry of Construction's green building codes mandate energy-efficient envelopes for new residential permits. Novaland Group and Hung Thinh Corporation position integrated township developments along the Ho Chi Minh City-Dong Nai corridor.
Da Nang Central Coast
Tourism sector recovery and medical university expansion drive condominium demand among hospitality workers and healthcare trainees. The State Bank of Vietnam's foreign currency lending restrictions constrain non-resident purchaser participation in this coastal market. Sun Group and FLC Group target mixed-use developments bridging beachfront leisure and residential utility.
Vietnam Residential Real Estate Market Competitive Landscape
Backward integration into captive concrete supply dominates the current landscape as developers compress delivery timelines and insulate margins from commodity volatility. The vendor base organizes around three strategic archetypes: mega-project generalists with integrated township capabilities, mid-range specialists in standardized townhouses, and luxury-focused coastal developers. Capacity expansion and portfolio diversification constitute the dominant competitive moves, with players extending geographic reach across provincial industrial corridors.
Among Vietnam-based developers, Vinhomes, Novaland Group, and Khang Dien House occupy representative positions across distinct strategic tiers. Vinhomes exemplifies the mega-project generalist archetype through its captive supply chain integration and multi-province portfolio scale. Novaland Group sits within the integrated township tier, bundling residential units with retail and education infrastructure to capture recurring revenue streams. Khang Dien House anchors the mid-range specialist position in Ho Chi Minh City's eastern corridor, where standardized townhouse products target first-time buyers facing land scarcity constraints.
| Leading Market Players |
|---|
| Phat Dat Corporation |
| Sun Group |
| Vinhomes |
| Hung Thinh Corporation |
| FLC Group |
| Novaland Group |
| Khang Dien House |
| SonKim Land |
| Dat Xanh Group |
| Others |
Value Network & Pricing Analysis
Young urban professionals in Ho Chi Minh City and Hanoi compressing condominium sales cycles force developers to absorb Ministry of Construction fire safety compliance costs or pass them through pricing, tightening margins across mid-range townhouse segments where land scarcity already inflates acquisition premiums.
Pricing Analysis
Volume concentrates in standardized townhouses for first-time buyers where price sensitivity peaks, while margin pools in premium condominiums with integrated township bundling. Three-tier pricing structure across luxury villas, standard condominiums, and economy townhouses separates buyers by payment capacity. Pricing pressure stems from elevated compliance consulting costs for green building codes and fire safety certification. Cash-ready investors command priority unit selection and bulk discounts, whereas mortgage-dependent first-time buyers face State Bank of Vietnam leverage constraints.
Supply Chain Analysis
Dual-sourcing requirements for aluminum composite panel cladding and ready-mix concrete push developers to qualify multiple suppliers across Vietnam's northern and southern manufacturing corridors. Geographic supply concentration centers on domestic concrete batching plants, Chinese aluminum composite panel imports, and regional steel frame fabricators. Raw material dependencies span cement, aluminum coil, and structural steel. Single-source vulnerability persists in specialty fire-rated cladding systems. Distribution runs through captive concrete supply chains at mega-project developers and third-party logistics networks for finishing materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's residential real estate operates as a cost-of-compliance story where Ministry of Construction fire safety standards and green building codes erect barrier-to-entry moats favoring developers with pre-certified material assemblies and regulatory engagement capacity.
For Market Incumbents: Anticipate prolonged certification timelines for high-rise reinforced concrete structures by front-loading Ministry of Construction engagement and pre-approving facade material assemblies. Defensive consolidation through backward integration into ready-mix concrete production insulates margin from commodity volatility. Priority lever rests on captive supply chain control compressing delivery timelines against emerging township competitors.
For New Entrants and Emerging Players: Capture underpenetrated volume in Binh Duong and Dong Nai industrial corridor worker housing where manufacturing cluster densification outpaces supply. White-space targets include standardized single-family homes for factory supervisors and integrated retail-residential bundling near Vietnam-Singapore Industrial Park. Go-to-market angle emphasizes leasehold tenure clarity and installment plan accessibility for first-time buyers.
For Investors and Strategic Acquirers: The window for entry favors developers with captive concrete supply and multi-province project pipelines over pure-play land aggregators. Long-term viability hinges on regulatory compliance infrastructure and township integration capabilities. Acquisition target archetype includes mid-range townhouse specialists in Ho Chi Minh City's eastern corridor with standardized product platforms. Signal to watch is State Bank of Vietnam relaxation of foreign ownership caps or escrow account rule tightening reordering capital flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ready-Mix Concrete | Vinhomes compresses delivery timelines across mega-projects by controlling captive supply chains. |
| Integrated Township Development | Novaland Group bundles residential units with retail and education infrastructure capturing recurring revenue. |
| Fire Safety Pre-Certification | Developers front-load Ministry of Construction engagement to reduce high-rise certification delays. |
| Provincial Corridor Expansion | Hung Thinh Corporation positions township developments along Ho Chi Minh City-Dong Nai logistics zones. |
| Mid-Range Townhouse Standardization | Khang Dien House anchors standardized product lines targeting first-time buyers in land-scarce eastern HCMC. |
Research Methodology
Document review covered Ministry of Construction building codes, State Bank of Vietnam lending regulations, and provincial People's Committee land-use certificate filings, complemented by interviews with real estate development executives, project management directors, concrete supply chain managers, and mortgage lending officers at domestic banks. Secondary validation drew from construction material trade data, property transaction registries, and green building certification databases. Bottom-up unit absorption modeling triangulated against top-down market value aggregation.
Market size and growth projections emerged from segmented demand modeling across property type, buyer profile, payment structure, and development stage dimensions throughout the projection horizon. CAGRs derived from historical transaction velocity analysis and forward-looking absorption rate assumptions. Industry-specific forecast inputs included industrial zone employment growth trajectories in Binh Duong and Dong Nai, plus metro line completion timelines affecting Ho Chi Minh City and Hanoi accessibility premiums.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to State Bank of Vietnam foreign ownership cap adjustments, Ministry of Construction escrow account rule modifications, and industrial zone expansion pace in southern provinces. Deviation in central bank leverage regulations or fire safety certification processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
Global Manufactured Housing Market