
 United States Residential Real Estate Market | 2026-2036
United States Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Residential Real Estate Market Insights
The Sun Belt region is tilting national transaction volume southward as population migration accelerates housing starts across Texas, Florida, and Tennessee. Keller Williams Realty leverages its extensive agent network to sustain commission-driven revenue across suburban expansion corridors. Berkshire Hathaway HomeServices anchors luxury positioning through affiliated brokerages in high-net-worth enclaves. Compass competes on technology infrastructure, deploying proprietary CRM and pricing analytics to differentiate agent productivity in competitive metros.
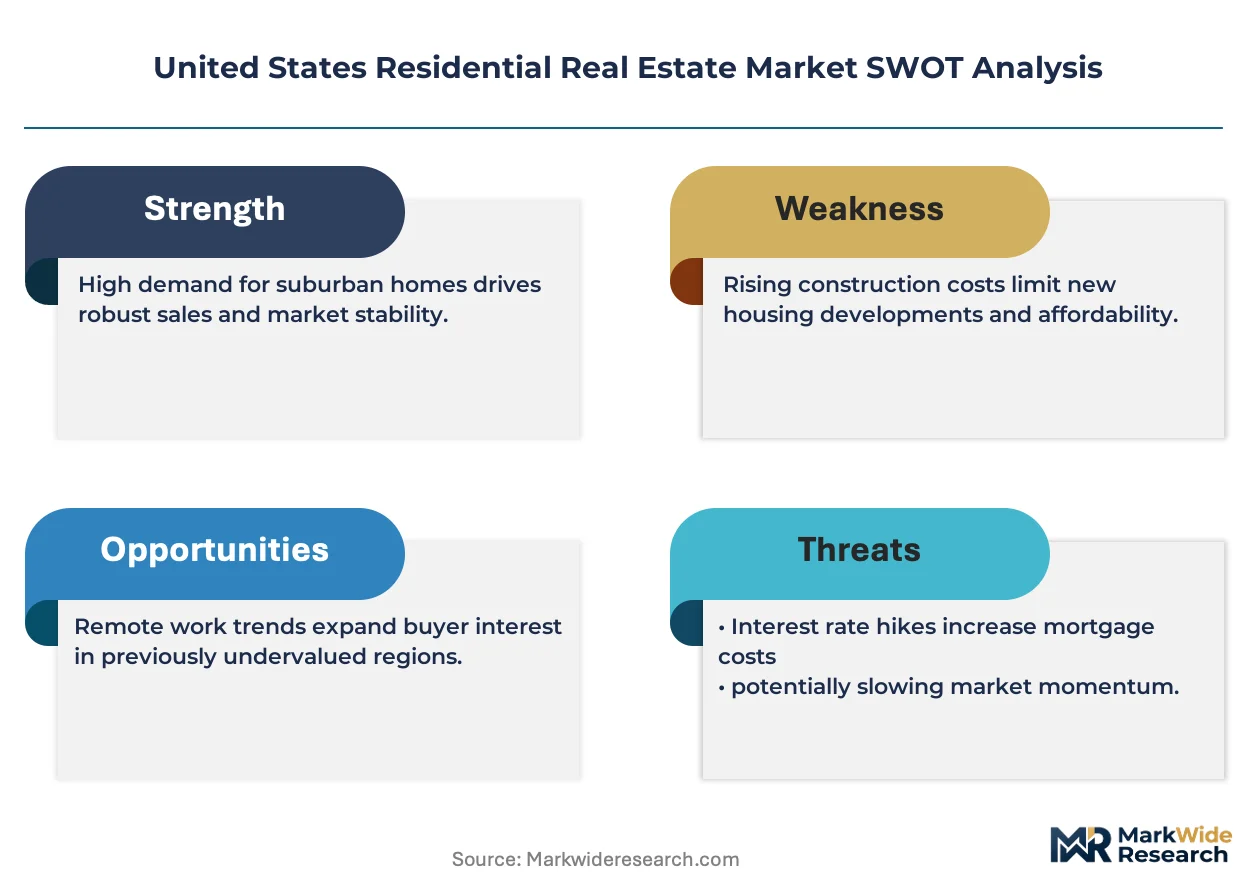
United States residential real estate encompasses land parcels, dwelling structures, and associated improvement rights traded for owner occupancy or rental income generation, with valuation methodologies integrating comparable sales analysis, cost depreciation schedules, and income capitalization approaches. Single-family homes dominate transaction flow and aggregate value, though multi-family units attract institutional capital seeking yield compression in supply-constrained urban cores. First-time buyers face structural affordability barriers as mortgage financing segments tighten underwriting standards, while luxury buyers concentrate in waterfront and premium urban sub-markets where inventory scarcity supports price resilience.
FHA, VA, and GSE conforming loan limits set by federal housing agencies directly shape demand accessibility for first-time and moderate-income purchasers across the country. NHTSA-adjacent zoning overlays and local building codes administered through municipal planning departments constrain new supply velocity in high-demand jurisdictions. Stakeholders must monitor interest rate trajectory signals from the Federal Reserve and corresponding mortgage rate pass-through effects on monthly payment affordability.
Market Dynamics
Interest rate pass-through from Federal Reserve policy decisions is compressing monthly payment affordability and forcing transaction velocity adjustments across price tiers. FHA and VA loan program recalibrations by federal housing agencies are redistributing purchasing power toward entry-level segments.
Growth Catalysts
- Millennial household formation:Demographic cohort aging into prime first-time buyer years concentrates demand in starter homes across Sun Belt metropolitan corridors.
- Remote work permanence:Employer policies sustaining distributed labor models enable geographic arbitrage from high-cost coastal markets to interior states.
- Build-to-rent institutional capital:Pension funds and REITs deploy capital into single-family rental development, expanding housing stock without traditional ownership transfer.
Market Restraints
- Lumber futures volatility:Input material cost swings from Canadian softwood tariff disputes and mill capacity constraints destabilize new construction pro formas.
- Municipal zoning inertia:NHTSA-adjacent overlay districts and local comprehensive plans restrict density increases in supply-constrained jurisdictions.
- Skilled trades scarcity:Electrician and plumber apprenticeship pipeline gaps extend construction timelines and elevate labor cost components.
Strategic Opportunities
- Accessory dwelling unit liberalization:California and Oregon state legislation preempting local exclusionary codes unlocks incremental supply on existing residential parcels.
- Climate resilience retrofitting:IRA tax credit extensions for heat pump and solar installations create renovation demand in hurricane and wildfire exposure zones.
- Proptech-enabled iBuying:Algorithmic pricing models and instant offer platforms compress transaction friction for seller liquidity needs.
Industry Challenges
- Appraisal bias remediation:Algorithmic valuation models and human appraiser training gaps perpetuate racial valuation gaps in minority neighborhoods.
- Title insurance blockchain integration:Legacy county recorder systems resist distributed ledger adoption, delaying cost reduction in closing processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Residential Real Estate Market |
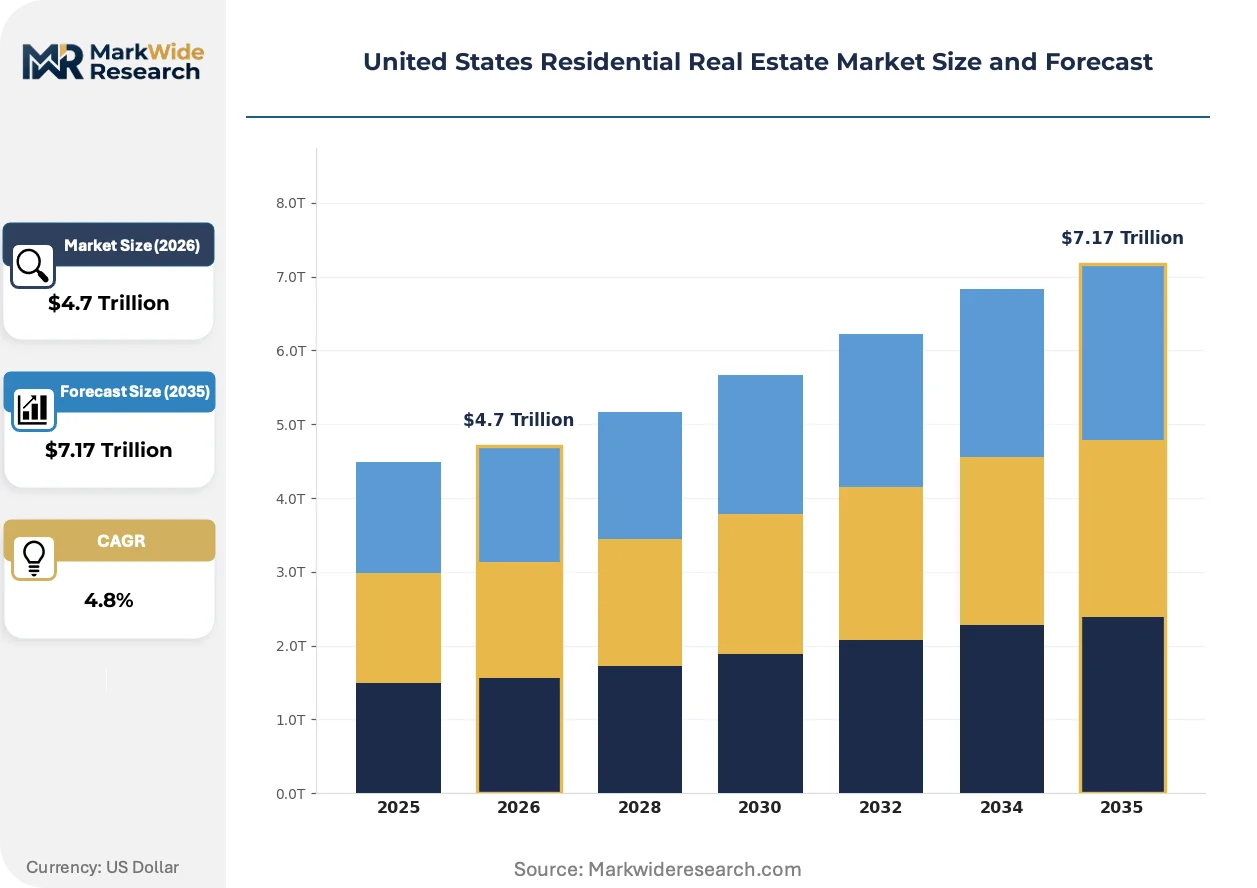
| Market Size in 2026 | $4.7 Trillion |
| Market Size in 2035 | $7.17 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Multi-Family Units Buyer Type: First-Time Buyers, Real Estate Investors, Retirees, Luxury Buyers Purchase Method: Cash Purchases, Mortgage Financing, Lease-to-Own, Foreclosures Market Segment: Urban, Suburban, Rural, Waterfront |
| Companies Covered | Keller Williams Realty, RE/MAX, Berkshire Hathaway HomeServices, eXp Realty, Anywhere Real Estate, Compass, Redfin, Sotheby’s International Realty, Howard Hanna Real Estate Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Residential Real Estate Market Trends and Innovations
Digital infrastructure is compressing transaction friction and reshaping how buyers discover, evaluate, and close residential purchases. Three converging developments are restructuring competitive advantage.
Matterport 3D capture and spatial data platforms are virtualizing property showings and inspection workflows. Remote buyers in migration corridors adopt immersive walkthroughs as primary evaluation tools. This compression of physical site visits is virtualizing geographic constraints on search behavior.
FHA loan limit adjustments by the Department of Housing and Urban Development expand conforming access in high-cost counties. Entry-level purchasers in California and Northeast metropolitan areas gain leverage previously reserved for jumbo borrowers. Regional lender operations are recalibrating underwriting automation to capture this expanded addressable base.
Institutional single-family rental operators are unbundling property management services from ownership structures. Build-to-rent developers in Texas and Florida sublease maintenance and leasing functions to specialized operators. This operational fragmentation concentrates capital deployment velocity while dispersing tenant-facing execution risk.
United States Residential Real Estate Market Segmentation
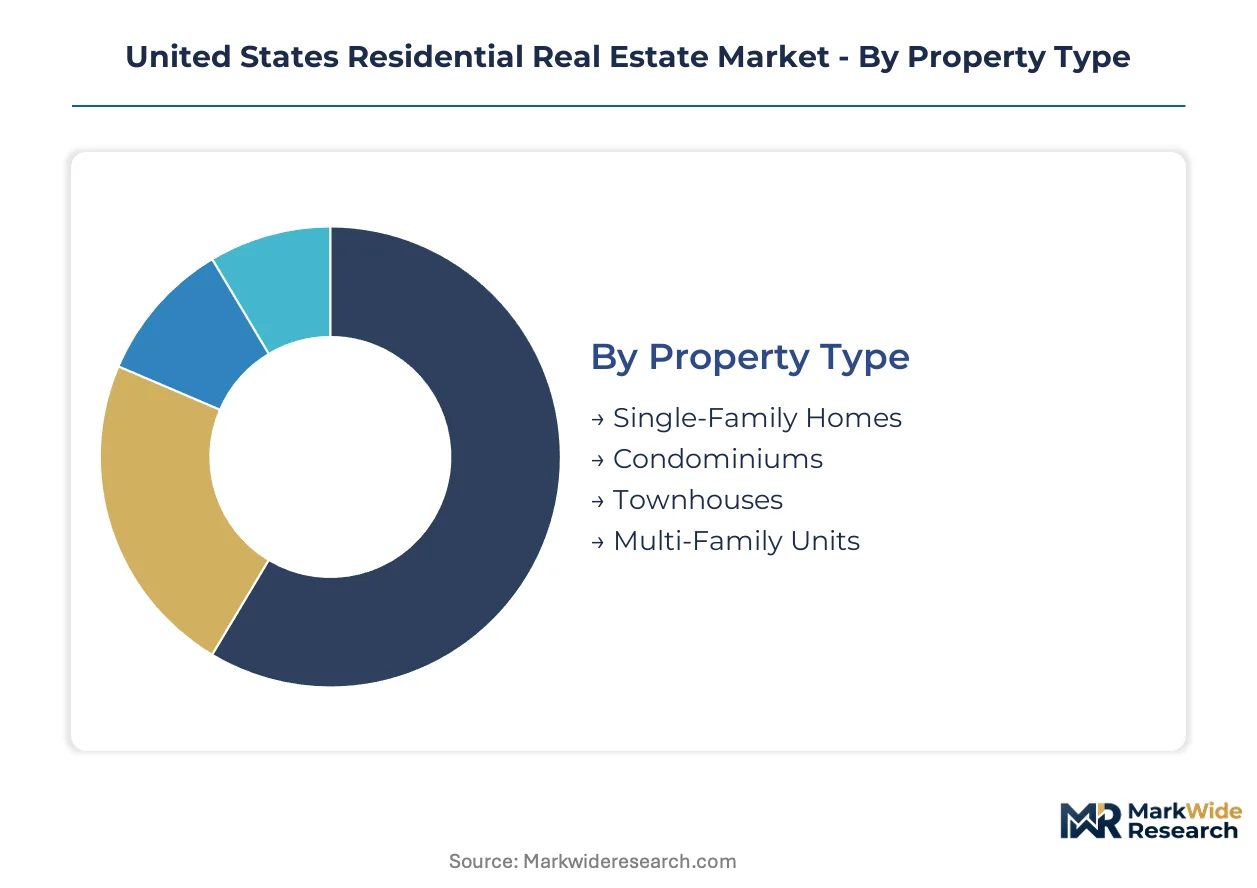
Property type segmentation reveals divergent turnover velocities across the United States residential real estate market. Transaction cycle times range from rapid condo flips in Miami to generational holds on rural acreage. Understanding these velocity differentials helps stakeholders align capital deployment with liquidity requirements.
Property Type:
Single-family homes turn over fastest in Sun Belt migration corridors, while multi-family assets trade on institutional hold periods measured in decades.
- Single-Family Homes:Detached structures on individually titled land parcels constitute the dominant transaction volume. Demand concentrates in Austin, Nashville, and Tampa where remote work arbitrageurs seek square footage per dollar. Millennial household formation drives starter home velocity in these metros.
- Multi-Family Units:Apartment buildings and duplex-to-quadplex structures attract institutional capital seeking yield compression. Pension funds and REITs concentrate acquisition in supply-constrained urban cores where rent growth outpaces operating expense escalations.
- Condominiums:Individual unit ownership within multi-unit structures with shared common elements. Florida and California coastal markets see elevated investor participation in condo rentals.
- Townhouses:Attached single-family dwellings with fee-simple ownership and limited common areas. Suburban Washington DC and Seattle corridors favor this density-efficient format.
Single-family homes dominate installed base. Multi-family units are where expansion concentrates.
Buyer Type:
First-time buyers operate on compressed decision timelines driven by mortgage rate volatility, while luxury purchasers deliberate across seasons.
- First-Time Buyers:Entry-level purchasers leveraging FHA and VA loan programs with minimal down payment requirements. Sun Belt metropolitan areas absorb this cohort as affordability constraints push migration inland from coastal markets.
- Real Estate Investors:Individual and institutional purchasers acquiring properties for rental income or capital appreciation. Build-to-rent developers in Texas and Florida sublease operations to specialized property managers.
- Retirees:Downsizing empty-nesters seeking single-level living and proximity to healthcare infrastructure. Arizona and Florida retirement communities capture this demographic flow.
- Luxury Buyers:High-net-worth individuals acquiring waterfront and premium urban sub-markets where inventory scarcity supports price resilience. Manhattan penthouses and Hamptons estates trade on extended marketing periods.
First-time buyers represent the volume base. Real estate investors are climbing the fastest.
Purchase Method:
Cash transactions close in days while mortgage-dependent purchases stretch across underwriting timelines.
- Mortgage Financing:Conventional, FHA, VA, and jumbo loan products enabling leveraged acquisition. Federal housing agencies set conforming loan limits that reshape accessibility in high-cost counties.
- Cash Purchases:Unleveraged acquisitions by investors and high-net-worth individuals eliminating financing contingencies. Institutional single-family rental operators deploy capital without debt dependency.
- Foreclosures:Distressed asset acquisition through judicial and non-judicial proceedings. Florida and Illinois judicial foreclosure timelines extend investor capital lockup periods.
- Lease-to-Own:Rent-to-own arrangements converting tenancy into equity accumulation. Subprime credit households access this pathway where traditional underwriting excludes them.
Mortgage financing commands transaction volume. Cash purchases are gaining share fastest.
Market Segment:
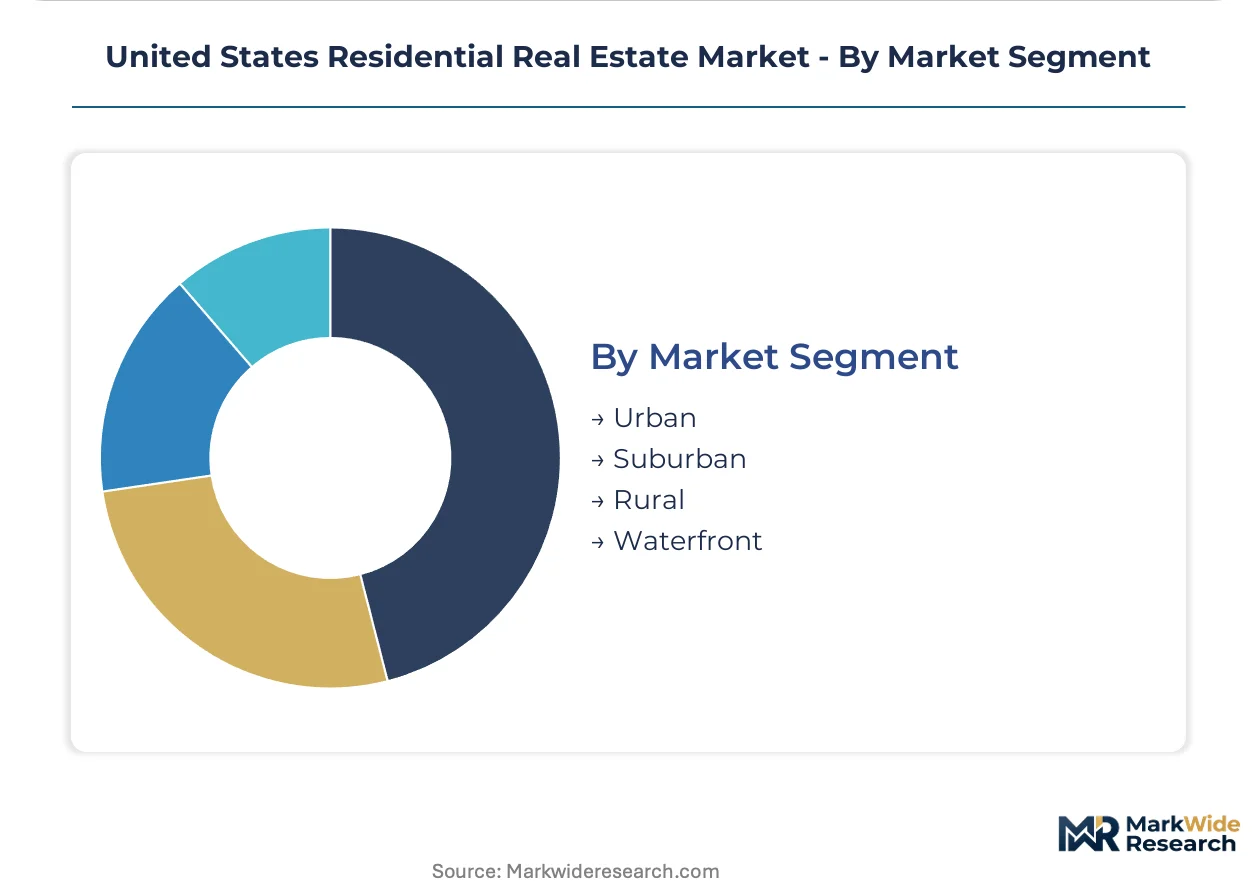
Urban cores trade on amenity density while rural parcels transact on generational timelines.
- Suburban:Residential areas surrounding urban cores with automobile-dependent accessibility. Keller Williams Realty sustains commission revenue across these expansion corridors.
- Urban:High-density central city locations with transit-oriented development patterns. Compass deploys proprietary pricing analytics to differentiate agent productivity here.
- Waterfront:Coastal and lake-adjacent properties commanding scarcity premiums. Berkshire Hathaway HomeServices anchors luxury positioning in these enclaves.
- Rural:Low-density agricultural and recreational land with limited infrastructure. Remote work permanence extends search radii into these territories.
Suburban inventory dominates installed base. Waterfront properties are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FHA, VA, and GSE conforming loan limits set by federal housing agencies anchor demand accessibility across the United States. Regional migration patterns and municipal zoning frameworks reshape transaction velocity in distinct sub-markets.
Southeast
Florida and Georgia absorb retiree inflows and remote worker migration from high-cost coastal metros. Local comprehensive plans and NHTSA-adjacent zoning overlays constrain density increases in supply-constrained jurisdictions. Tampa and Orlando metropolitan corridors concentrate build-to-rent institutional capital deployment.
Southwest
Texas metropolitan areas capture domestic migration arbitrageurs seeking square footage per dollar. Municipal planning departments in Austin and Dallas-Fort Worth administer building codes that extend construction timelines amid skilled trades scarcity. San Antonio anchors suburban expansion corridors where Keller Williams Realty sustains commission-driven revenue.
West Coast
California faces structural affordability barriers as mortgage financing segments tighten underwriting standards. State legislation preempting local exclusionary codes unlocks incremental supply through accessory dwelling unit liberalization. Los Angeles and San Francisco sub-markets trade on inventory scarcity supporting price resilience in luxury segments.
Mountain West
Denver and Phoenix benefit from remote work permanence enabling geographic arbitrage from coastal markets. Federal Reserve interest rate trajectory signals compress monthly payment affordability across first-time buyer cohorts. Salt Lake City corridors attract institutional single-family rental operators seeking yield compression.
Northeast Corridor
Washington DC and Boston metropolitan areas favor density-efficient townhouse formats with transit-oriented development patterns. Compass deploys proprietary pricing analytics to differentiate agent productivity in these competitive urban cores. New York sub-markets see extended marketing periods for Manhattan penthouses and premium waterfront inventory.
United States Residential Real Estate Market Competitive Landscape
Capability concentration sits with technology-enabled brokerages; scale advantage sits with agent network incumbents. The vendor base spans national franchisors, regional independents, and venture-backed proptech platforms competing on divergent vectors. Two strategic archetypes dominate: commission-driven agent networks and algorithmic pricing platforms. Consolidation through franchise acquisitions and technology licensing partnerships reshapes competitive positioning.
Among national franchisors, Keller Williams Realty and RE/MAX exemplify scale-driven agent network models. Berkshire Hathaway HomeServices occupies a position within the luxury-tier segment. Compass represents the technology-enabled archetype deploying proprietary infrastructure to differentiate productivity in competitive metropolitan corridors.
| Leading Market Players |
|---|
| Keller Williams Realty |
| RE/MAX |
| Berkshire Hathaway HomeServices |
| eXp Realty |
| Anywhere Real Estate |
| Compass |
| Redfin |
| Sotheby's International Realty |
| Howard Hanna Real Estate Services |
| Others |
Pricing and Supply Chain Analysis
Canadian softwood lumber concentration anchors construction cost volatility, feeding directly into margin compression for entry-level homebuilders while downstream pricing power accrues to land-bank holders in supply-constrained Sun Belt metros.
Pricing Analysis
Coastal-to-interior price spreads exceed two-fold in comparable square footage, with Manhattan and San Francisco premiums reflecting land scarcity against Austin and Nashville value positioning. Three-tier pricing structure across luxury waterfront, standard suburban, and economy starter segments differentiates by amenity density and school district ratings. Pricing pressure stems from Federal Reserve rate pass-through compressing monthly payment affordability for mortgage-dependent buyers. First-time buyers exhibit highest price sensitivity, while all-cash investors and luxury purchasers demonstrate inelastic demand.
Supply Chain Analysis
Extended payment terms from national lumber distributors to regional homebuilders have become standard practice, with supply-chain finance facilities bridging construction timeline gaps. Raw material sourcing concentrates in Canada, Mexico, and domestic Pacific Northwest timberlands. Framing lumber, copper wiring, and HVAC equipment constitute critical component dependencies. Single-source vulnerability runs through Canadian softwood tariff exposure. Distribution runs through national building material distributors serving regional contractor networks and direct-to-builder procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brokerage and development fragmentation creates entry points for specialized operators as remote work permanence fragments demand across non-traditional secondary metros.
For Market Incumbents: Build data moat through proprietary pricing algorithm refinement. Keller Williams Realty and RE/MAX franchise networks should deepen agent productivity tooling to defend against Compass technology differentiation. Anchor commission structures in Sun Belt expansion corridors where transaction velocity sustains revenue. Counter iBuying platforms by embedding instant-offer capabilities within existing agent workflows.
For New Entrants and Emerging Players: Build out accessory dwelling unit development specialization in California and Oregon markets where state preemption unlocks incremental supply. Target build-to-rent operations in Tampa and Orlando corridors where institutional capital concentrates. Penetrate through vertical integration of property management services, subleasing maintenance and leasing functions to capture operational fragmentation value.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional brokerage rollups seeking liquidity events. Five-to-ten year viability hinges on technology infrastructure amortization and agent retention economics. Acquisition targets should display proprietary CRM deployment and Sun Belt geographic concentration. Watch Federal Reserve policy trajectory as inflection signal for transaction velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Pricing Algorithm Investment | Compass-style analytics differentiate agent productivity in competitive metropolitan corridors. |
| Build-to-Rent Development Scale-Up | Pension fund and REIT capital deployment accelerates housing stock expansion without ownership transfer. |
| Accessory Dwelling Unit Liberalization | California and Oregon state legislation preempts local codes to unlock incremental supply. |
| iBuying Platform Integration | Algorithmic pricing models compress transaction friction for seller liquidity needs. |
| Climate Resilience Retrofitting Program | IRA tax credit extensions for heat pump and solar installations create renovation demand in exposure zones. |
Research Methodology
Initial hypotheses were tested against primary input from brokerage operations executives, mortgage underwriting officers, municipal planning directors, and institutional real estate investors and refined through secondary validation. Primary fieldwork encompassed franchise network operators, build-to-rent developers, and regional lender credit committees. Secondary sources included HUD loan limit filings, Federal Reserve policy statements, municipal comprehensive plans, and NAR transaction data. Bottom-up transaction volume modeling triangulated against top-down demographic cohort analysis.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions encompassed property type, buyer category, purchase method, and geographic market tier. CAGRs derived from cohort aging patterns, migration flow projections, and interest rate scenario modeling. Housing starts permits and mortgage origination volumes served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive technology investment by venture-backed proptech platforms or accelerated municipal zoning liberalization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market