
 France Manufactured Homes Market | 2026-2036
France Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
France Manufactured Homes Market Foresight
Vacation home seekers is consolidating as the fastest-rising buyer category in the France manufactured homes sector. Siblu leverages its coastal park network to dominate seasonal deployment across western France. Baluchon specializes in compact, transportable wooden units that anchor the tiny-home niche for rural municipalities. IRM competes through steel-framed product lines engineered for Mediterranean climate durability.
Manufactured homes are factory-built residential structures, typically assembled from pre-engineered modules or panels with standardized dimensions of 3.6 to 4.2 meters in transport width, designed for permanent or semi-permanent habitation. Their primary purpose is to deliver cost-controlled housing with reduced on-site construction duration compared to traditional masonry builds. Modular homes lead the product type category due to their compliance with France's permanent-building codes and eligibility for standard mortgage financing. Panelized homes represent the fastest-growing construction material segment as SIPs technology improves thermal performance ratings and reduces HVAC loads. Wood construction material maintains the deepest margin pool through established supply chains in the Massif Central and Jura timber regions.
France's RE2020 regulation and CE marking requirements under the EU Construction Products Regulation shape energy performance thresholds and market access conditions for all residential building systems. ANAH subsidies and Action Cœur de Ville program criteria direct demand toward urban infill and small-town renewal zones. Local urban planning documents governed by the Code de l'urbanisme determine zoning permissions that vary sharply between strict coastal conservation areas and designated tourist-residence zones. Stakeholders must monitor evolving bioclimatic performance thresholds and municipal zoning liberalization in secondary cities to align product portfolios with deployable land pipelines.
Market Dynamics
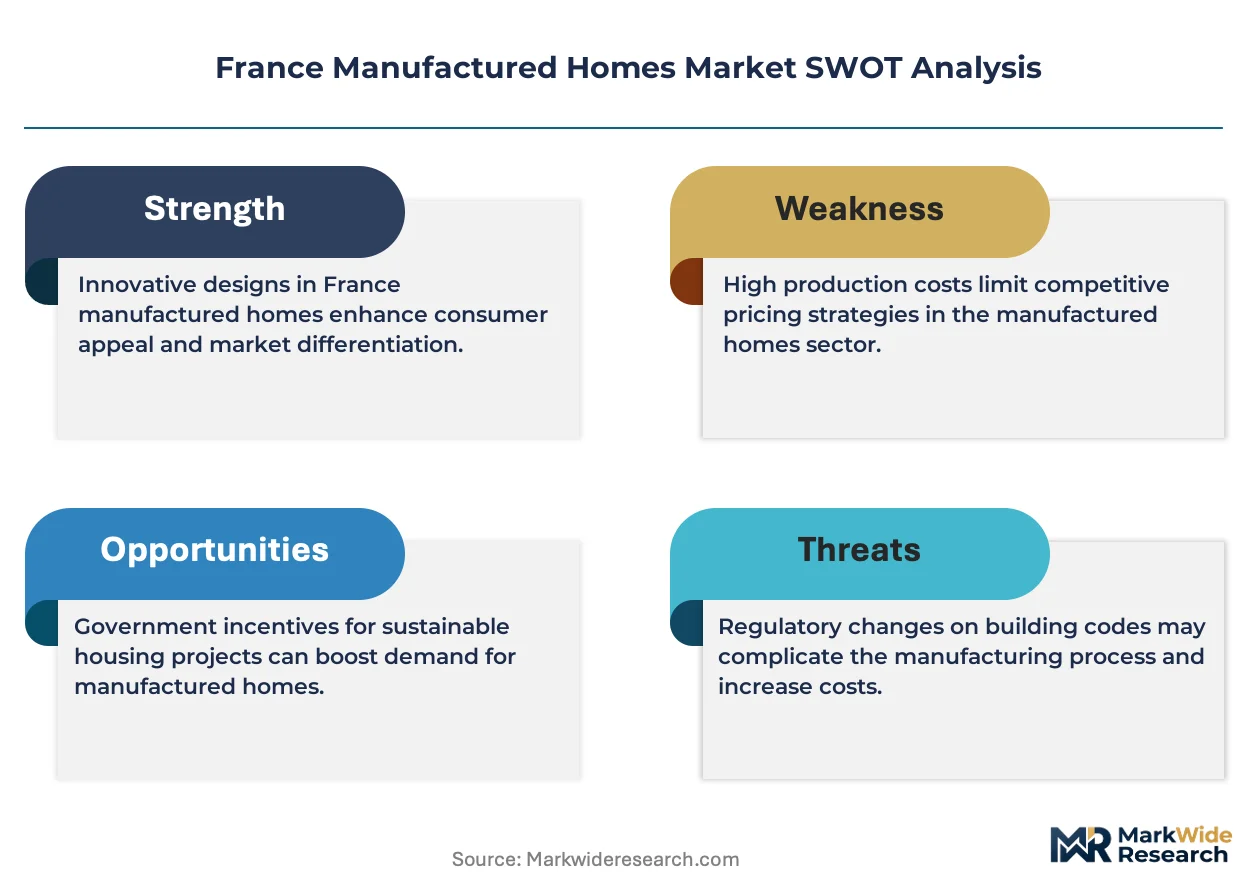
France's RE2020 environmental regulations are compressing permitted energy consumption thresholds for new residential structures, forcing manufacturers to redesign thermal envelopes and HVAC systems ahead of each tightening compliance cycle.
Growth Catalysts
- Rural first-time buyers:Young households priced out of urban masonry construction are pivoting toward modular alternatives that qualify for standard mortgage financing under French banking regulations.
- ANAH subsidies:The national housing agency's renovation and new-build incentives channel capital toward small-town renewal zones designated under Action Cœur de Ville criteria.
- SIPs technology:Structural insulated panels are improving thermal performance ratings while reducing on-site labor requirements for coastal and mountain deployment.
Market Restraints
- Timber supply concentration:Engineered wood products depend on sawmill capacity concentrated in the Massif Central and Jura regions, creating vulnerability to regional weather disruptions.
- Coastal zoning friction:Local urban planning documents governed by the Code de l'urbanisme impose strict conservation restrictions along Atlantic and Mediterranean shorelines, limiting park expansion.
- Foundation cost inflation:Steel-framed units engineered for Mediterranean durability require reinforced concrete anchoring that erodes the factory-built cost advantage in rocky or sloped terrain.
Strategic Opportunities
- Occitanie tourism corridors:Land availability around Carcassonne and the Pyrenees foothills intersects with expanding seasonal rental infrastructure for vacation home deployment.
- CE marking convergence:Harmonized EU Construction Products Regulation standards position French manufacturers to cross-serve Belgian and Luxembourg markets without duplicate certification.
- Tiny-home municipal pilots:Rural municipalities are testing compact wooden units from specialist producers as solutions for teacher and nurse housing shortages.
Industry Challenges
- Bioclimatic engineering talent:The shortage of designers fluent in passive-house simulation software delays RE2020-compliant product development cycles.
- CNIL data compliance:Smart-home energy monitoring systems embedded in manufactured units must satisfy France's data protection authority requirements for tenant privacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Manufactured Homes Market |
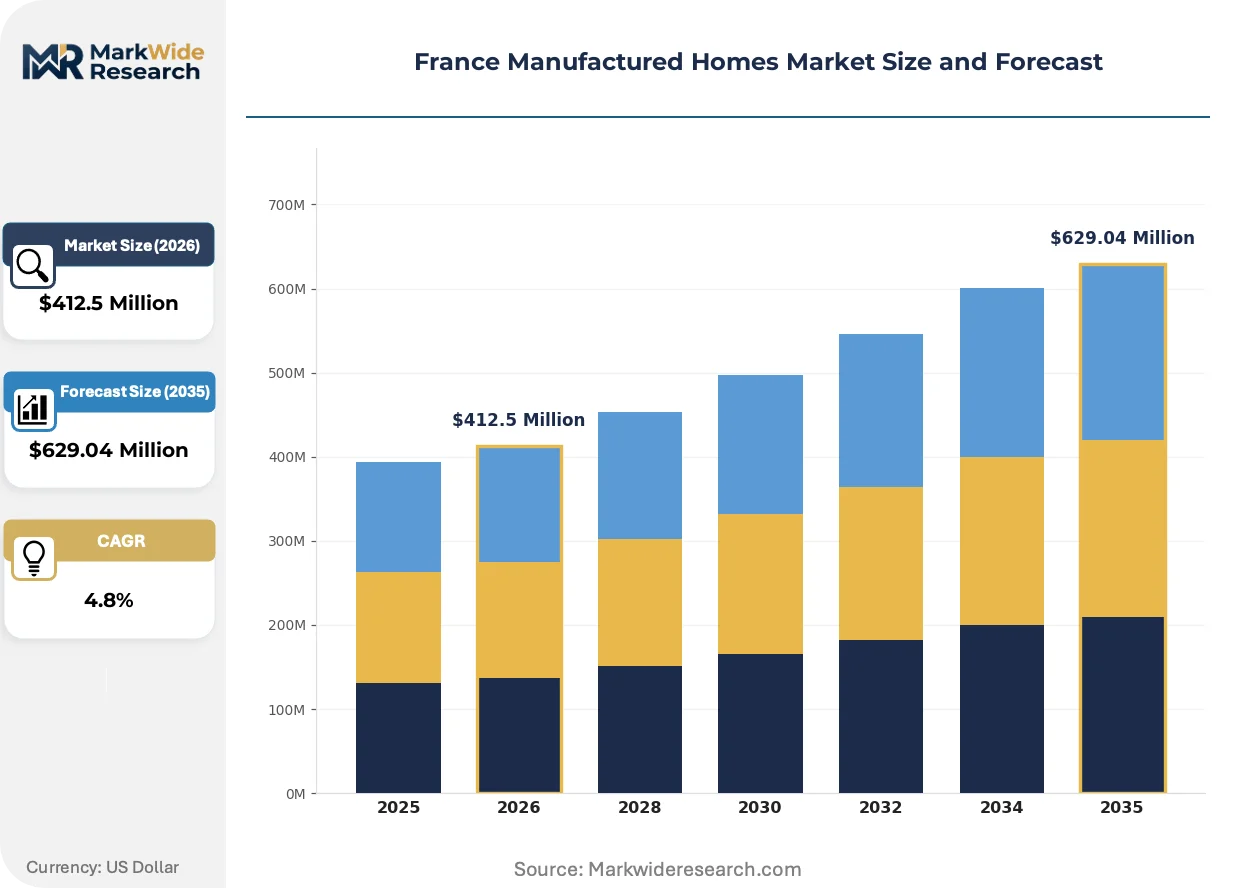
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Mobile Homes, Prefabricated Houses, Panelized Homes Construction Material: Wood, Steel, Concrete, SIPs, Aluminum End User: Residential Buyers, Vacation Home Seekers, Real Estate Developers, Rental Property Owners Distribution Channel: Direct Sales, Retail Dealers, Online Marketplaces, Housing Exhibitions |
| Companies Covered | Clayton, Siblu, Baluchon, IRM, Inhaus, Bimify, O'HARA, Adria Home, Tiny Living, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Manufactured Homes Market Shifts & Advancements
Factory-built housing in France is pivoting from cost-driven positioning toward performance-based differentiation as energy regulations tighten and buyer expectations professionalize.
Structural insulated panels are integrating into mainstream product lines as the core thermal envelope technology for RE2020-compliant units. Rural first-time buyers and vacation home seekers are specifying SIPs construction at accelerating rates after mortgage lenders began recognizing the reduced operating cost profiles. The technology is integrating permanent-building code compliance with transportable module dimensions, collapsing the historical trade-off between mobility and financing eligibility.
France's RE2020 regulation is mandating stepped reductions in primary energy consumption for all new residential construction through 2030. Manufacturers must now model lifecycle carbon emissions across material sourcing, factory production, and operational phases. Modular homes face the steepest redesign burden because their eligibility for standard mortgages depends on permanent-building certification that RE2020 progressively tightens.
Buyer preference is rotating toward turn-key service packages that bundle land identification, foundation preparation, and utility connection. Traditional self-build project management is losing share among time-constrained rural households and seasonal investors. This bundling trend concentrates in Nouvelle-Aquitaine where park operators and independent land brokers are formalizing referral partnerships to capture vacation home demand.
France Manufactured Homes Market Segmentation
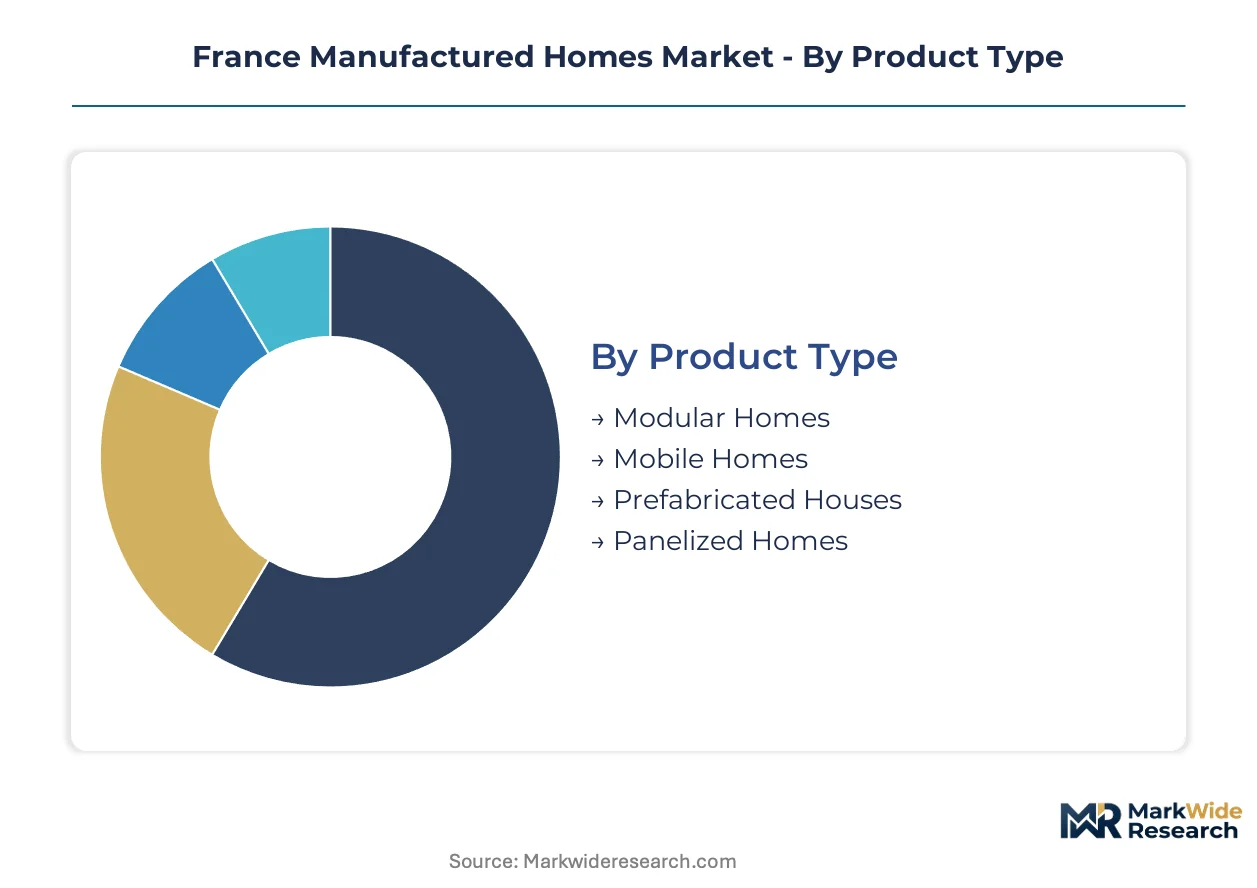
Segmentation in the France manufactured homes market reveals how regulatory frameworks and buyer preferences fragment demand across construction methodologies, material specifications, and acquisition channels. Understanding these divisions helps manufacturers align product portfolios with deployable land pipelines and financing eligibility requirements.
Product Type:
The customization-standardization spectrum stretches from fully bespoke modular assemblies to mass-produced mobile units, with regulatory certification status determining mortgage access and resale liquidity.
- Modular Homes:Factory-built permanent structures assembled from volumetric modules that comply with France's permanent-building codes and qualify for standard mortgage financing from traditional lenders. Demand concentrates among rural first-time buyers in Nouvelle-Aquitaine seeking primary residence solutions with full property rights. RE2020 energy performance thresholds force continuous thermal envelope redesign cycles.
- Mobile Homes:Transportable units mounted on chassis with wheels, typically deployed in licensed holiday parks under seasonal-use restrictions rather than permanent habitation permits. Vacation home seekers in Occitanie coastal corridors drive deployment, though strict Code de l'urbanisme conservation zones limit park expansion along Mediterranean shorelines.
- Prefabricated Houses:Complete dwelling systems manufactured off-site and craned onto prepared foundations, bridging the gap between modular permanence and mobile flexibility. Rural municipalities pilot these for teacher housing shortages.
- Panelized Homes:Flat-packed wall, floor, and roof panels assembled on-site, offering the most transport efficiency for mountain and remote terrain deployment. SIPs technology integration is accelerating thermal performance gains.
Most installed capacity flows through Modular Homes. Expansion is steepest in Panelized Homes.
Construction Material:
Cost tiers separate premium engineered systems from commodity framing, with regional supply concentration shaping procurement economics and vulnerability profiles.
- Wood:Traditional timber framing and engineered wood products leveraging established supply chains in the Massif Central and Jura regions. Rural first-time buyers specify wood construction for its renewable credentials and familiarity with local building traditions. Regional weather disruptions create supply vulnerability.
- SIPs:Structural insulated panels combining oriented strand board facings with rigid foam cores, delivering superior thermal performance ratings that satisfy RE2020 stepped reduction mandates. Vacation home seekers in Pyrenees foothills prioritize SIPs after mortgage lenders recognized reduced operating cost profiles.
- Steel:Galvanized or painted steel framing engineered for Mediterranean climate durability and seismic resistance. Foundation cost inflation erodes factory-built advantages in rocky terrain.
- Concrete:Precast concrete panels and insulated concrete forms providing thermal mass and fire resistance. Limited adoption outside hurricane-exposed overseas territories.
- Aluminum:Lightweight structural and cladding systems for coastal corrosion resistance. Niche deployment in salt-air environments.
Wood dominates current installation volumes. SIPs technology is climbing the fastest as RE2020 compliance deadlines tighten.
End User:
Customer type segmentation maps to distinct land access patterns, financing structures, and service bundling expectations across the deployment lifecycle.
- Residential Buyers:Permanent-dwelling purchasers including young households priced out of urban masonry construction and retirees downsizing to lower-maintenance alternatives. ANAH subsidies and Action Cœur de Ville criteria channel capital toward designated small-town renewal zones.
- Vacation Home Seekers:Seasonal-use investors and second-home owners targeting tourism corridors around Carcassonne and Atlantic coastal parks. Turn-key service packages bundling land identification and utility connection are displacing self-build project management.
- Real Estate Developers:Professional builders acquiring multiple units for speculative or build-to-rent portfolios. Concentrated in land-banked sites with pre-approved zoning.
- Rental Property Owners:Individual and institutional landlords deploying manufactured units for long-term or seasonal rental income streams. Limited by mortgage lender restrictions on non-owner-occupied financing.
Residential Buyers absorb the largest unit volumes. Vacation Home Seekers are gaining share fastest as tourism infrastructure expands.
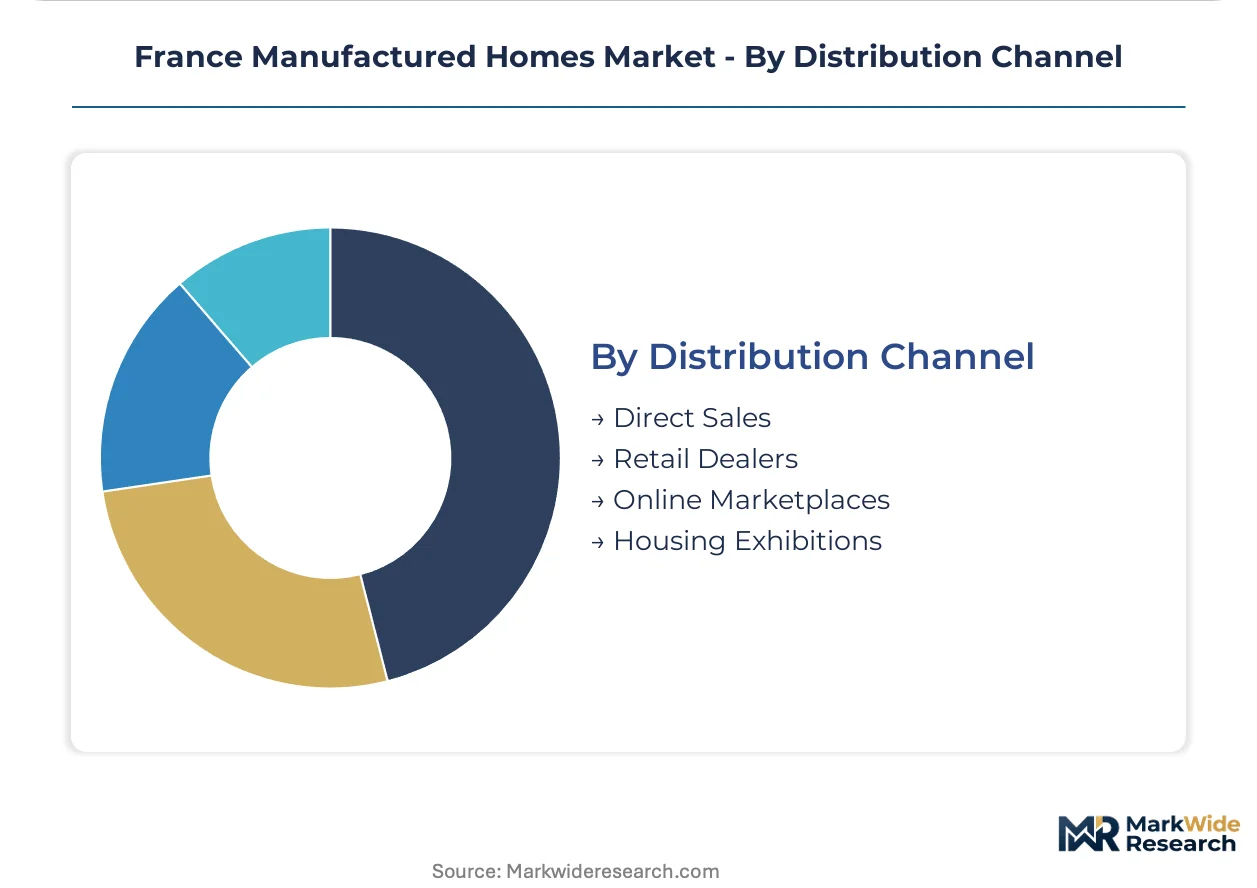
Distribution Channel:
Channel selection reflects buyer sophistication, geographic isolation, and the complexity of land-plus-product bundling requirements.
- Direct Sales:Manufacturer-to-consumer transactions with in-house design and project management services. Dominates premium modular segments requiring customization.
- Retail Dealers:Networked showrooms and independent sales agents with local land broker partnerships. Critical for Nouvelle-Aquitaine vacation home demand capture.
- Online Marketplaces:Digital platforms for configuration, pricing, and lead generation. Growing among time-constrained urban buyers researching rural relocation.
- Housing Exhibitions:Trade shows and permanent exhibition villages where manufacturers display finished units. Primary channel for SIPs technology demonstration and RE2020-compliant product launches.
Retail Dealers handle the majority of transaction volume. Online Marketplaces show the steepest expansion trajectory as digital-native buyers enter the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate toward regions with favorable zoning liberalization and streamlined CE marking pathways under the EU Construction Products Regulation.
Nouvelle-Aquitaine
Rural first-time buyers and vacation home seekers drive deployment across coastal and inland corridors. The region's local urban planning documents under the Code de l'urbanisme permit denser park configurations than Atlantic conservation zones to the north. Bordeaux and Biarritz anchor manufacturing clusters where SIPs-integrated modular units roll off production lines for immediate Mediterranean and Pyrenees distribution.
Occitanie
Land availability around Carcassonne and the Pyrenees foothills intersects with expanding seasonal rental infrastructure. ANAH subsidies channel capital toward small-town renewal zones designated under Action Cœur de Ville criteria. Toulouse and Montpellier host assembly yards specializing in steel-framed units engineered for seismic resistance in mountain terrain.
Île-de-France
Urban infill restrictions limit ground-up deployment, yet the region concentrates design and engineering talent for passive-house simulation software. CNIL data compliance requirements for smart-home energy monitoring systems are drafted and tested here before national rollout. Paris-based bioclimatic engineering consultancies service manufacturers nationwide.
Auvergne-Rhône-Alpes
The Massif Central timber belt supplies engineered wood products to modular builders, though regional weather disruptions create periodic supply vulnerability. Clermont-Ferrand and Grenoble maintain sawmill capacity and panel fabrication facilities. Local municipalities pilot compact wooden units for teacher and nurse housing shortages.
Provence-Alpes-Côte d'Azur
Strict coastal conservation zones under the Code de l'urbanisme compress park expansion along Mediterranean shorelines. Marseille and Nice nonetheless serve as logistics hubs for steel-framed units destined for Corsica and overseas territories. RE2020 thermal envelope redesign cycles are field-tested here before broader deployment.
France Manufactured Homes Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand from single-product positioning toward bundled land-plus-housing service packages. The vendor base clusters around three strategic archetypes: coastal park operators controlling seasonal deployment channels, compact wooden unit specialists serving rural municipal pilots, and steel-framed product engineers targeting Mediterranean climate durability. M&A activity concentrates on land broker networks and foundation preparation contractors. Technology licensing partnerships for SIPs fabrication equipment are accelerating as RE2020 compliance deadlines tighten.
Within the park-operator archetype, Siblu anchors coastal deployment across western France through its licensed holiday park network. Baluchon and IRM occupy distinct specialization vectors—Baluchon exemplifies the compact wooden unit tier for rural municipalities testing tiny-home housing solutions, while IRM represents steel-framed engineering positioned for Mediterranean climate durability. Clayton, as a multinational modular builder, sits within the scale-driven tier with manufacturing footprints spanning multiple European jurisdictions. These three archetypes—park-integrated, compact-wooden, and climate-engineered—collectively map the competitive terrain without exhaustive player enumeration.
| Leading Market Players |
|---|
| Clayton |
| Siblu |
| Baluchon |
| IRM |
| Inhaus |
| Bimify |
| O'HARA |
| Adria Home |
| Tiny Living |
| Others |
Supply & Pricing Matrix
Family-owned mid-caps in the Massif Central timber belt anchor supply-side discipline, translating regional sawmill consolidation into pricing power for engineered wood products while mortgage lender recognition of SIPs thermal performance creates tiered buyer willingness-to-pay across rural first-time and vacation home segments.
Pricing Analysis
Distributor margins absorb the primary channel economics, with retail dealers capturing 12-18 point markups on modular units versus direct-to-consumer transactions. Three-tier pricing structure across premium SIPs-integrated, standard timber-framed, and economy panelized levels separates buyers by RE2020 compliance certification and mortgage eligibility. Cost compression in steel-framed Mediterranean units intensifies because foundation preparation erodes factory-built advantages in rocky Pyrenees terrain. Rural first-time buyers exhibit highest price sensitivity, while vacation home seekers in Occitanie coastal corridors prioritize turn-key service bundling over unit cost.
Supply Chain Analysis
Freight costs from Massif Central sawmills to Nouvelle-Aquitaine assembly yards run 8-12% of landed panel costs, driving manufacturers toward barge and rail intermodal for Atlantic corridor distribution. Engineered wood products draw from French timber belts, Belgian laminate suppliers, and Austrian SIPs core manufacturers, creating cross-border dependency chains. Single-source vulnerability concentrates in rigid foam insulation cores where two Belgian chemical producers supply 70% of French panel fabricators. Distribution runs through manufacturer-owned assembly yards with crane-equipped lots for module staging and final fit-out.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France manufactured homes market compounds steadily as RE2020 regulatory tightening forces continuous product refresh cycles that reward incumbents with compliant thermal envelope capabilities and penalize laggards with obsolete inventory.
For Market Incumbents: Cement land-broker referral partnerships in Nouvelle-Aquitaine and Occitanie to capture vacation home demand before park operators consolidate distribution control. Deepen backward integration into Massif Central sawmill capacity to defend margin position against timber supply disruption from regional weather volatility. Prioritize bioclimatic engineering talent acquisition to accelerate RE2020-compliant product development cycles ahead of stepped energy reduction mandates.
For New Entrants and Emerging Players: Begin with compact wooden unit pilots for rural municipal housing shortages in Auvergne-Rhône-Alpes, where teacher and nurse accommodation gaps create procurement entry points outside park-operator channel dominance. Target the tiny-home segment underserved by steel-framed Mediterranean specialists and SIPs-integrated modular builders. Pursue direct municipal contracting with turn-key land-plus-housing service bundling to bypass retail dealer network establishment costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among panelized home specialists with unexploited CE marking pathways into Belgian and Luxembourg markets, where harmonized EU Construction Products Regulation standards eliminate duplicate certification barriers. The 5-10 year viability window favors manufacturers with proven SIPs fabrication partnerships and scalable assembly yard footprints. Monitor ANAH subsidy allocation shifts toward Action Cœur de Ville renewal zones as the inflection signal for demand geography rotation.
| Strategic Initiative | Industry Significance |
|---|---|
| SIPs Fabrication Partnership | Secures thermal envelope technology for RE2020 compliance deadlines without capital-intensive in-house panel production. |
| Land Broker Network Acquisition | Captures vacation home demand in Occitanie tourism corridors where deployable land pipelines constrain park expansion. |
| CE Marking Pathway Expansion | Positions French manufacturers to cross-serve Belgian and Luxembourg markets under harmonized EU Construction Products Regulation standards. |
| Bioclimatic Engineering Talent Investment | Accelerates passive-house simulation software deployment to compress RE2020-compliant product development cycles. |
| Turn-Key Service Bundling | Displaces self-build project management among time-constrained rural households and seasonal investors in Nouvelle-Aquitaine. |
Research Methodology
Bottom-up rural first-time buyer and vacation home seeker modeling reconciled against top-down modular and panelized production capacity tracking forms the analytical core of this study. Primary interviews with park operators, land brokers, mortgage underwriters, and municipal housing officers combined with secondary validation from ANAH subsidy disbursement records, Code de l'urbanisme zoning filings, and CE marking registration databases. Triangulation across manufacturer shipment data, regional sawmill output statistics, and bank mortgage origination reports for manufactured home eligibility cross-checks demand-side estimates against supply-side constraints.
Input-output matrices map structural insulated panel fabrication capacity, engineered wood product availability, and foundation preparation contractor density against regional deployment demand across the analysis window. Segmentation dimensions modeled include product type, construction material, end-user category, and distribution channel, with CAGRs derived from regression analysis of historical unit shipments against macroeconomic drivers and regulatory compliance cost trajectories. RE2020 stepped reduction mandates and ANAH subsidy allocation patterns feed directly into demand elasticity assumptions for rural first-time buyer segments.
Several conditions sit outside the modeled scope, including potential Code de l'urbanisme liberalization in strict coastal conservation zones, sovereign debt impacts on mortgage lending standards, and disruptive prefabrication technologies not yet CE marked. Forecasts reflect assumptions about regulatory timeline adherence and subsidy continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
Indonesia Residential Real Estate Market