
 France Luxury Residential Real Estate Market | 2026-2036
France Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
France Luxury Residential Real Estate Market Foresight
Multi-source brokerage networks is expanding across the French luxury residential sector as agencies diversify beyond exclusive listing arrangements. Sotheby's International Realty Affiliates LLC leverages its global referral infrastructure to anchor cross-border transactions. Daniel Feau competes through deep specialization in Paris arrondissement-level expertise. Barnes International Realty sustains its position by controlling bilingual advisory services for Anglo-Saxon clientele.
France luxury residential real estate encompasses freehold and leasehold dwellings exceeding premium price thresholds, typically featuring heritage architecture, bespoke interiors, and concierge-grade amenities with energy ratings increasingly scrutinized under renovation mandates. The segment serves wealth preservation, lifestyle migration, and generational asset transfer objectives for ultra-affluent households. Villas and penthouses command the deepest liquidity pools in Paris and coastal markets, while chateaux transactions concentrate among family office buyers seeking renovation-driven value creation. Private brokers and auction houses capture disproportionate margins on discreet off-market deals, whereas online marketplaces remain peripheral for trophy assets.
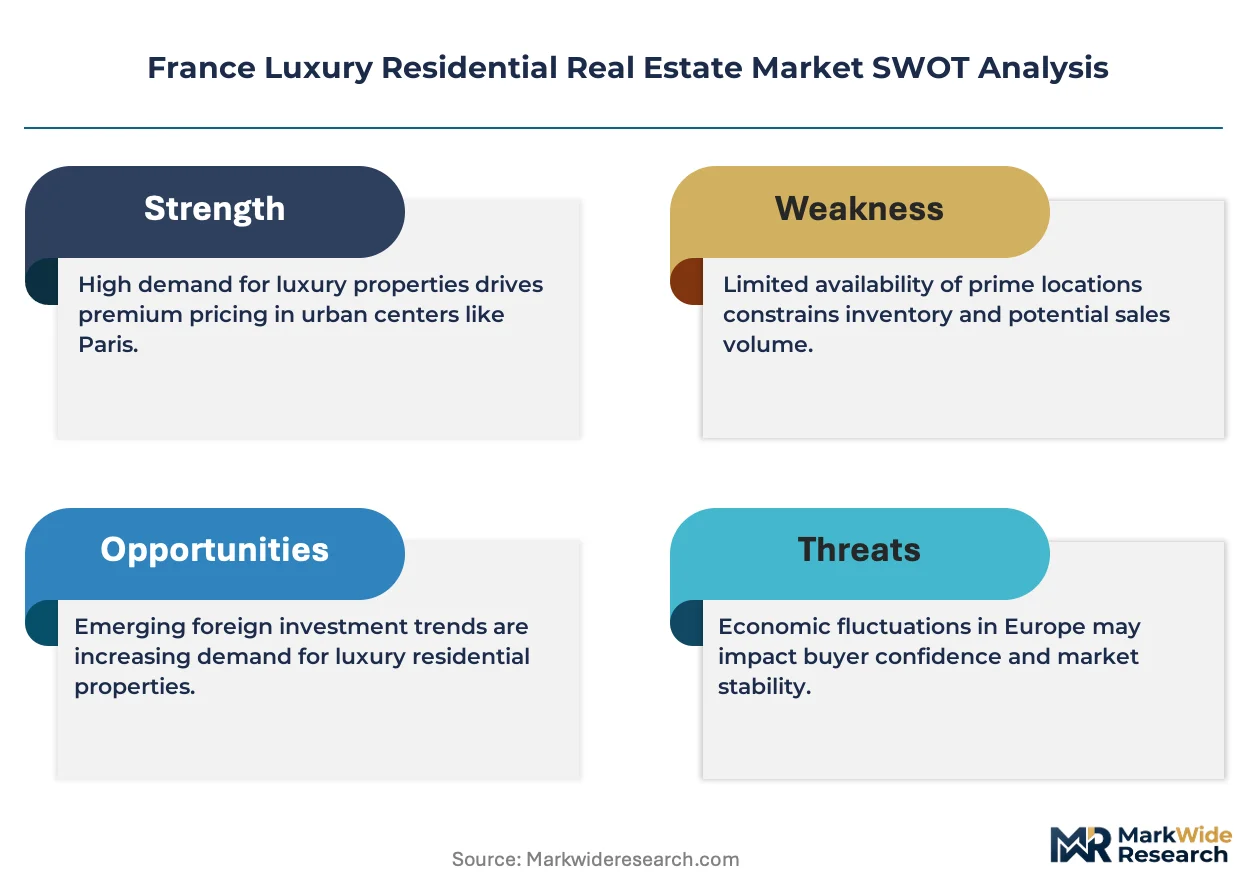
France's national building regulator enforces RE2020 environmental performance standards on renovation scope, while the EU Green Deal's building renovation requirements pressure energy upgrades in historic stock. ANSM/CNIL data governance rules complicate client onboarding for international transactions. Stakeholders must monitor regulatory compliance costs against buyer willingness to absorb premium pricing for certified sustainable heritage properties.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing transaction timelines for historic properties as buyers demand pre-certified energy compliance before closing. This regulatory pressure is restructuring broker specialization and renovation financing across Paris, Provence-Alpes-Côte d'Azur, and Alpine corridors.
Growth Catalysts
- RE2020 Standards:France's national building regulator mandates energy performance upgrades that create premium pricing tiers for compliant heritage assets, accelerating buyer preference for pre-renovated stock.
- Wealth Migration Patterns:Ultra-affluent households from the Middle East and North America are concentrating acquisition activity in Paris arrondissements and French Riviera coastal zones, deepening liquidity in trophy segments.
- Concierge-Grade Amenities:Integrated property management platforms embedding biometric access and predictive maintenance are differentiating penthouses and villas in competitive submarkets.
Market Restraints
- Artisan Labor Scarcity:Specialized restoration craftspeople for limestone façades and period woodwork command 40-60% premiums, inflating renovation budgets for châteaux and Belle Époque properties.
- Notarial Processing Bottlenecks:France's deed registration system creates 3-4 month transaction friction for international buyers, deterring time-sensitive acquisitions from non-EU sources.
- Heritage Protection Overlays:Architectes des Bâtiments de France review requirements freeze modification rights on 18th-19th century inventory, limiting value-add strategies for investors.
Strategic Opportunities
- Alpine Resort Corridors:Megève, Chamonix, and Courchevel show underpenetrated luxury inventory relative to Swiss and Austrian comparables, offering first-mover positioning for climate-resilient ski-accessible assets.
- CNIL-Compliant Onboarding:ANSM/CNIL data governance rules create competitive whitespace for brokerages investing in GDPR-aligned client verification infrastructure ahead of enforcement tightening.
- Generational Transfer Services:Family offices seeking renovation-driven value creation in châteaux segments lack integrated legal-technical advisory bundles, opening margin expansion for full-stack providers.
Industry Challenges
- Bilingual Advisory Talent:Brokerages serving Anglo-Saxon clientele face acute scarcity of French-English fluent agents with arrondissement-level micro-market knowledge and notarial liaison experience.
- Energy Audit Integration:RE2020 compliance documentation must be synthesized with heritage classification records, creating workflow complexity that extends pre-listing preparation by 6-8 weeks.
- Off-Market Verification:Discreet transactions through private networks lack standardized title and lien verification protocols, elevating counterparty risk in high-value bilateral deals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Luxury Residential Real Estate Market |
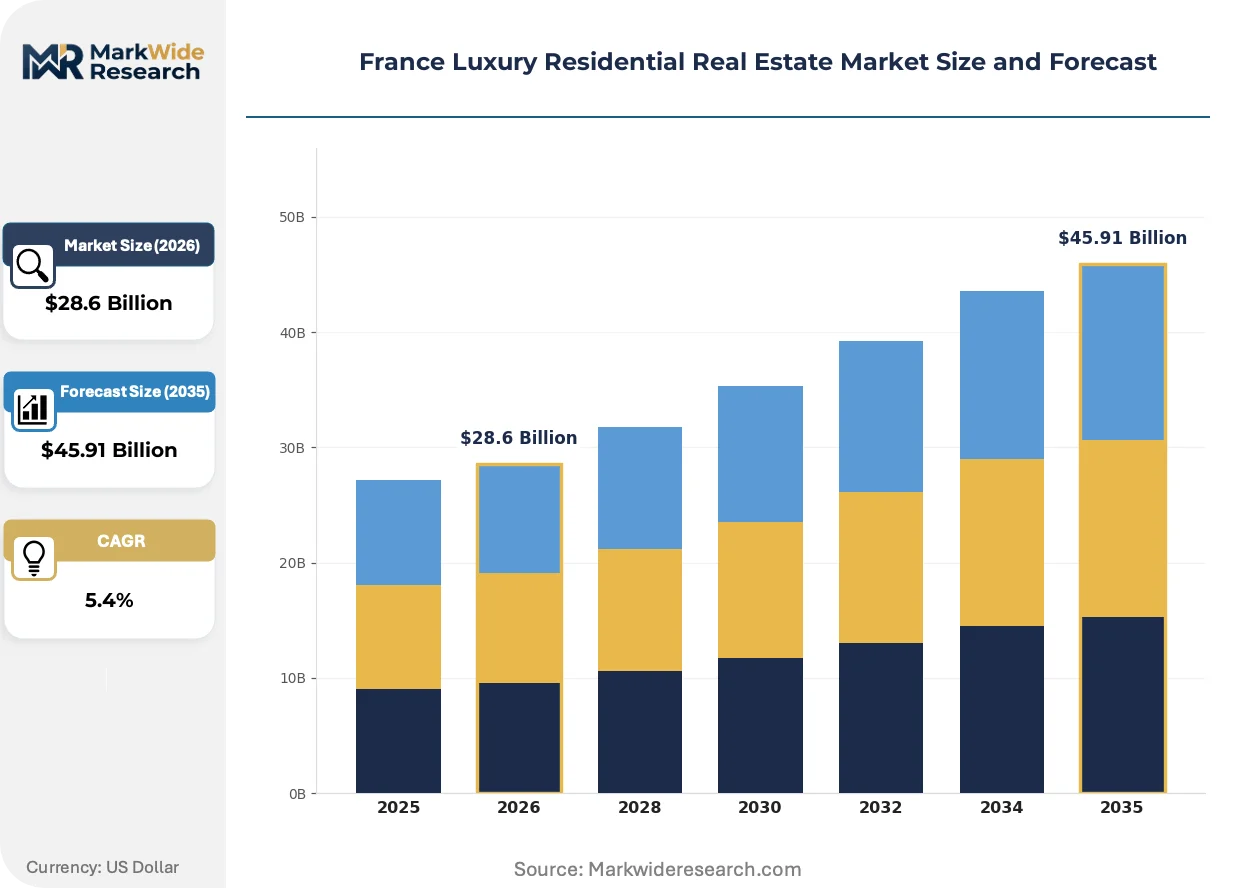
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Penthouses, Chateaux, Townhouses, Mansions Buyer Profile: High Net Worth Individuals, Private Investors, Family Offices, International Buyers, Real Estate Developers Investment Strategy: Buy to Hold, Vacation Rentals, Renovation Projects, Luxury Leasing, Portfolio Diversification Sales Channel: Real Estate Agencies, Online Marketplaces, Private Brokers, Auction Houses, Developer Direct Sales |
| Companies Covered | John Taylor, Haussmann Real Estate, Sotheby's International Realty Affiliates LLC, Homehunts, Groupe Immobilier Mercure, Daniel Feau, Propriétés Le Figaro, Belles Demeures, Barnes International Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Luxury Residential Real Estate Market Shifts & Advancements
Digital property intelligence platforms are compressing information asymmetry between international buyers and local market insiders, while regulatory technology embeds compliance verification directly into transaction workflows.
Blockchain-based title registries are decentralizing due diligence processes for cross-border acquisitions. Family offices and Middle Eastern sovereign wealth vehicles are piloting distributed ledger verification to accelerate notarial clearance. This architecture is compressing trust establishment timelines from months to weeks for buyers lacking established French banking relationships.
France's transposition of EU Green Deal renovation requirements into RE2020 enforcement protocols is mandating thermal performance audits for all pre-1948 inventory. Châteaux and period apartment segments face the steepest compliance cost curves, with sellers pre-emptively bundling renovation warranties to preserve pricing power. The French Riviera villa market is responding fastest, with new construction already embedding heat pump and solar infrastructure.
Buyer representation models are fragmenting traditional exclusive listing arrangements. Multi-source brokerage networks now aggregate inventory across competing agencies, with Anglo-Saxon clients particularly receptive to advisory relationships decoupled from seller commission structures. Paris and coastal submarkets show the deepest penetration of this unbundling, where procurement sophistication among North American investors is displacing legacy single-agency loyalty patterns.
France Luxury Residential Real Estate Market Segmentation
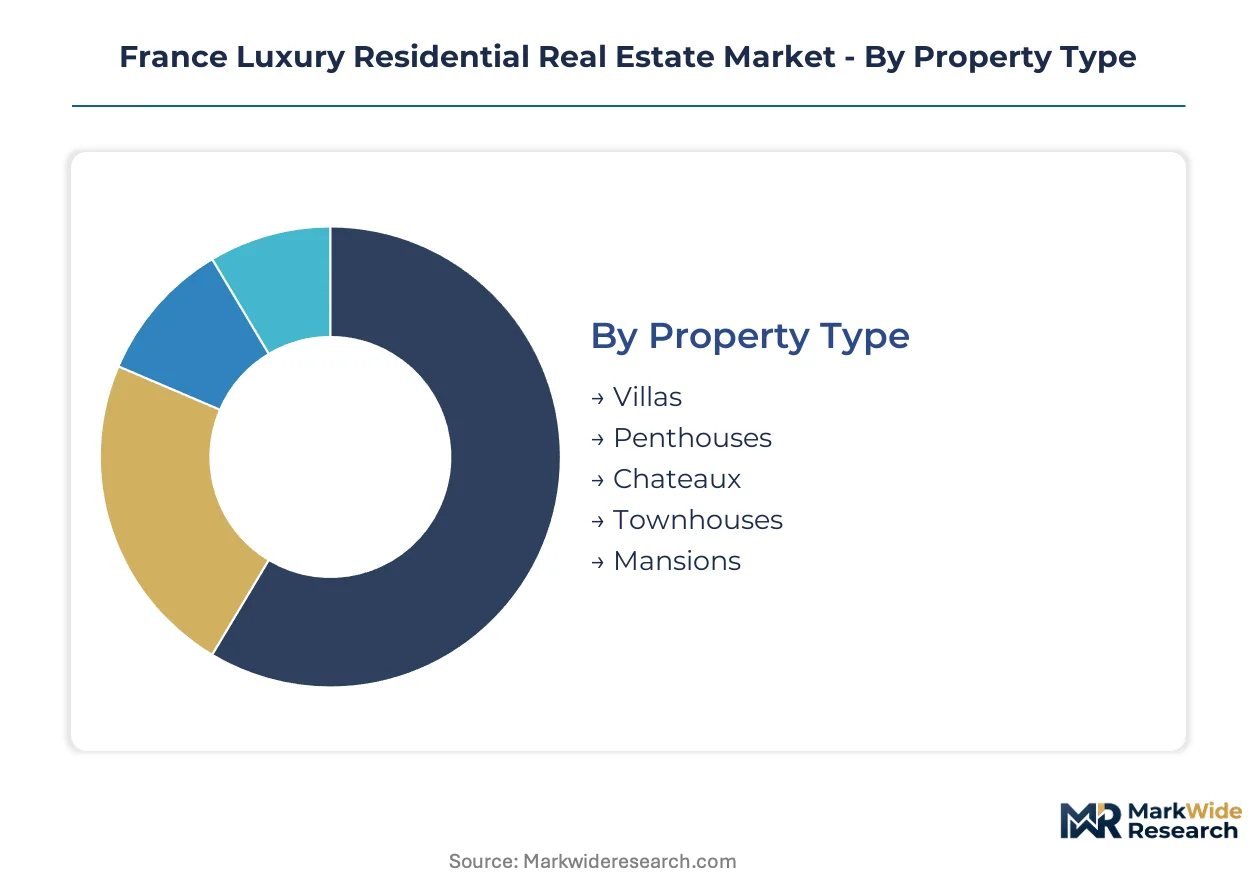
Segmentation in France's luxury residential market reveals how regulatory pressure, buyer origin, and transaction structure reshape competitive positioning. Each dimension exposes distinct margin pools and operational requirements for stakeholders navigating RE2020 mandates and cross-border capital flows.
Property Type:
Asset selection hinges on renovation feasibility under Architectes des Bâtiments de France oversight and liquidity depth in trophy corridors.
- Villas:Coastal and Alpine configurations dominate transaction velocity in Provence-Alpes-Côte d'Azur and Megève-Courchevel corridors. Buyers prioritize solar infrastructure and heat pump pre-installation to satisfy RE2020 compliance without heritage review delays.
- Penthouses:Haussmann-era buildings with concierge-grade amenities concentrate in Paris arrondissements 6, 7, and 16. Demand intensifies for biometric access systems and predictive maintenance platforms that differentiate inventory.
- Chateaux:Period estates requiring specialized limestone façade and woodwork restoration face 40-60% artisan labor premiums.
- Townhouses:Urban freehold units in Bordeaux and Lyon offer lower entry thresholds than Paris equivalents.
- Mansions:Belle Époque inventory carries heritage protection overlays that freeze modification rights.
Villas lead on scale; penthouses lead on momentum.
Buyer Profile:
Capital source determines transaction complexity, timeline tolerance, and advisory service requirements across French submarkets.
- International Buyers:Middle Eastern and North American households concentrate acquisition in Paris and French Riviera zones, navigating 3-4 month notarial processing friction through private banking relationships.
- Family Offices:Multi-generational wealth vehicles target châteaux segments for renovation-driven value creation, lacking integrated legal-technical advisory bundles in current market structure.
- High Net Worth Individuals:Lifestyle migration objectives prioritize concierge-grade amenities and energy certification.
- Private Investors:Yield-focused capital evaluates vacation rental potential in Alpine resort corridors.
- Real Estate Developers:New construction players embed RE2020 infrastructure preemptively in French Riviera villa supply.
International buyers lead on scale; family offices lead on momentum.
Investment Strategy:
Holding period and income expectations segment operational intensity and regulatory exposure for asset managers.
- Buy to Hold:Generational wealth preservation strategies prioritize freehold security and arrondissement-level scarcity in Paris core markets.
- Renovation Projects:Value creation through energy performance upgrades aligns with EU Green Deal enforcement timelines, compressing due diligence windows for pre-certified stock.
- Vacation Rentals:Alpine and coastal submarkets generate seasonal yield, subject to municipal registration requirements.
- Luxury Leasing:Corporate tenancy and diplomatic demand concentrates in furnished penthouses with integrated property management.
- Portfolio Diversification:Cross-asset allocation spreads exposure across property types and French regions.
Buy to hold leads on scale; renovation projects lead on momentum.
Sales Channel:
Channel selection governs information asymmetry, counterparty verification, and margin capture for sellers and buyers alike.
- Private Brokers:Discreet off-market transactions capture disproportionate margins but lack standardized title and lien verification protocols, elevating bilateral deal risk.
- Auction Houses:Trophy asset disposal for distressed or estate-settlement scenarios concentrates in Paris and coastal markets with established collector networks.
- Real Estate Agencies:Multi-source brokerage networks displace exclusive listing arrangements, particularly for Anglo-Saxon clientele seeking decoupled advisory relationships.
- Online Marketplaces:Digital platforms remain peripheral for trophy assets but compress information asymmetry for sub-premium inventory.
- Developer Direct Sales:New construction absorption in French Riviera and Alpine corridors bypasses intermediary commissions.
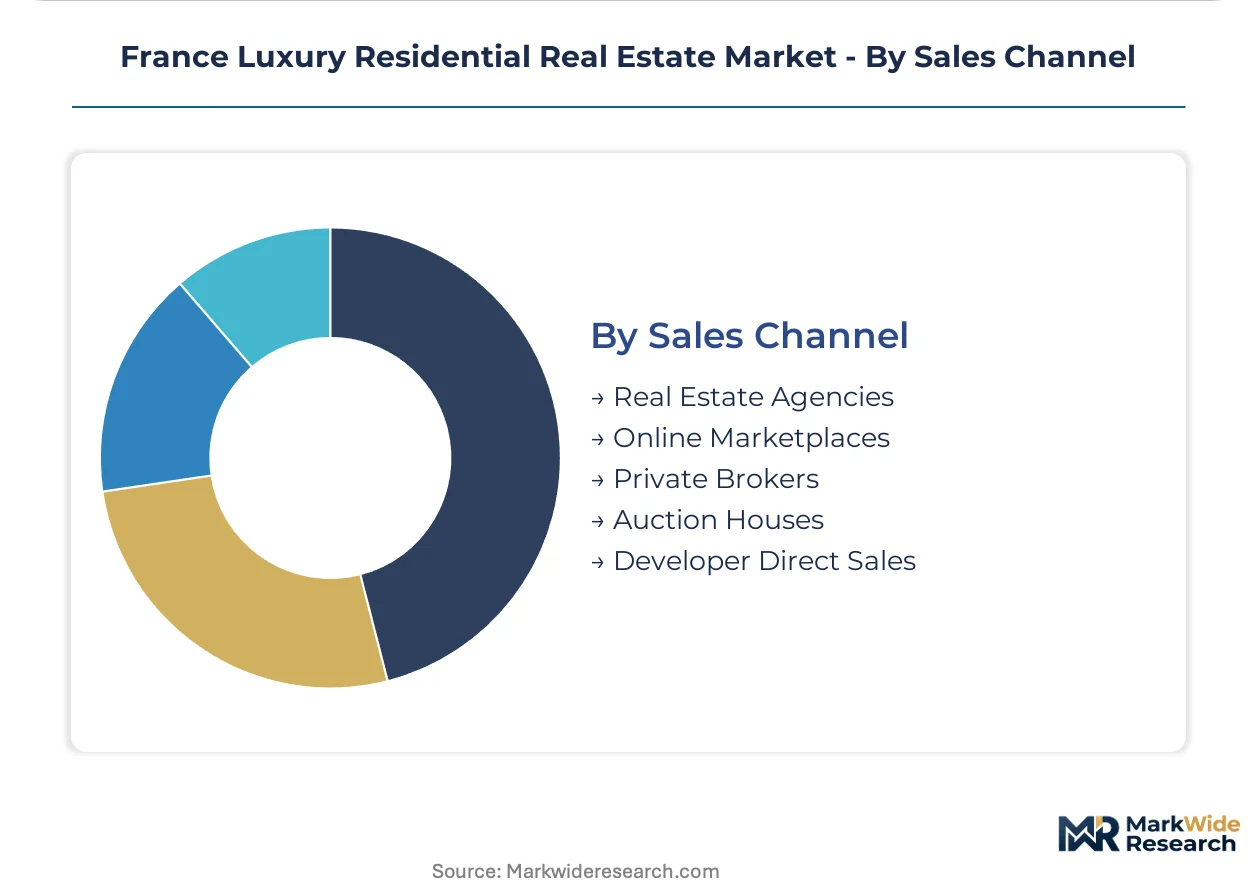
Real estate agencies lead on scale; private brokers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors national transaction velocity through its arrondissement-level scarcity and concentration of diplomatic and family office capital. The Île-de-France region generates disproportionate deal flow across trophy penthouses and private mansion segments.
Île-de-France
Paris arrondissements 6, 7, and 16 concentrate Haussmann-era penthouse demand from Middle Eastern and North American buyers. ANSM/CNIL data governance rules complicate client onboarding for international transactions. Notarial processing bottlenecks in Paris create 3-4 month friction for non-EU buyers navigating deed registration.
Provence-Alpes-Côte d'Azur
The French Riviera coastal zone draws wealth migration from Middle Eastern households seeking climate-resilient villa assets. EU Green Deal building renovation requirements accelerate solar infrastructure and heat pump pre-installation in new construction. Cannes and Nice host the deepest liquidity pools for compliant trophy inventory.
Auvergne-Rhône-Alpes
Alpine resort corridors including Megève, Chamonix, and Courchevel show underpenetrated luxury inventory relative to Swiss comparables. RE2020 environmental performance standards reshape energy upgrade mandates for ski-accessible chalets. Family offices target renovation-driven value creation in climate-resilient mountain assets.
Nouvelle-Aquitaine
Bordeaux and surrounding wine country attract lifestyle migration from Anglo-Saxon buyers seeking lower entry thresholds than Paris. Architectes des Bâtiments de France review requirements govern modification rights on 18th-19th century châteaux inventory. The Dordogne valley concentrates château transactions among generational wealth vehicles.
Occitanie
Toulouse and Mediterranean coastal submarkets extend Provence-Alpes-Côte d'Azur buyer spillover into less saturated territory. Heritage protection overlays limit value-add strategies on Belle Époque inventory in historic centers. Montpellier and Perpignan corridors attract private investors evaluating vacation rental yield potential.
France Luxury Residential Real Estate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technology-enabled advisory and concierge-integrated service bundles. The market structures around three distinct maturity tiers: heritage agencies with arrondissement-level specialization, global referral networks leveraging cross-border infrastructure, and digital-native platforms compressing information asymmetry. Strategic archetypes include concierge-integrated operators, heritage restoration specialists, and multi-source brokerage aggregators. Dominant competitive moves encompass bilingual advisory capacity expansion and GDPR-aligned client verification infrastructure investment.
Within the global referral network tier, Sotheby's International Realty Affiliates LLC represents the archetype of cross-border transaction infrastructure. Daniel Feau occupies a position exemplifying deep Paris arrondissement-level specialization. Barnes International Realty anchors the bilingual advisory segment for Anglo-Saxon clientele.
| Leading Market Players |
|---|
| John Taylor |
| Haussmann Real Estate |
| Sotheby's International Realty Affiliates LLC |
| Homehunts |
| Groupe Immobilier Mercure |
| Daniel Feau |
| Propriétés Le Figaro |
| Belles Demeures |
| Barnes International Realty |
| Others |
Supply & Pricing Matrix
Artisan restoration labor for limestone façades and period woodwork feeds directly into premium pricing tiers for châteaux and Belle Époque inventory, with specialized craftspeople commanding substantial markups that cascade through buyer willingness-to-pay thresholds across Paris and coastal submarkets.
Pricing Analysis
Input-cost pass-through from RE2020 compliance documentation and heritage classification synthesis extends pre-listing preparation timelines, compressing seller pricing power for non-certified stock. Price differentiation separates pre-renovated energy-compliant assets from pending-renovation inventory, with Middle Eastern and North American buyers showing lowest price sensitivity for certified trophy properties. Pricing pressure stems from notarial processing friction for international buyers, forcing discount absorption on time-sensitive transactions. Family offices and generational wealth vehicles exhibit highest price sensitivity for châteaux segments facing artisan labor scarcity.
Supply Chain Analysis
Logistics and freight costs for imported bespoke materials—Italian marble, English oak, Belgian limestone—accumulate at Alpine and coastal construction sites, inflating delivered-cost bases for villa and château renovations. Geographic supply concentration draws from Italy, Spain, and Belgium for heritage-compatible building materials. Raw material dependencies rest on specialized timber, natural stone, and period-appropriate fixtures. Supply chain risk centers on single-source vulnerability for certified restoration craftspeople. Distribution runs through notarial-governed deed registration with 3-4 month clearance timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's luxury residential market represents a late-cycle quality story as buyer preference shifts decisively toward pre-certified energy-compliant heritage assets with concierge-grade amenities integrated.
For Market Incumbents: Acquire specialized restoration craftsperson networks to secure artisan labor pipelines for châteaux renovation projects. Consolidate bilingual advisory capacity with arrondissement-level micro-market knowledge to defend against multi-source brokerage network displacement. Channel control through exclusive notarial liaison relationships anchors transaction velocity against emerging digital-native competitors. For New Entrants and Emerging Players: EU Green Deal building renovation requirements in France open a window for climate-resilient Alpine resort corridor positioning ahead of incumbent saturation. White-space targets include CNIL-compliant client verification infrastructure and integrated legal-technical advisory bundles for family office châteaux acquisitions. Go-to-market execution should anchor on GDPR-aligned onboarding workflows that compress international buyer friction. For Investors and Strategic Acquirers: Consolidation pressure builds where bilingual advisory talent scarcity intersects with RE2020 compliance workflow complexity. Long-term viability favors platforms controlling renovation-driven value creation pipelines with captive artisan labor relationships. Acquisition target archetype: regional brokerages with deep arrondissement specialization and established Middle Eastern buyer networks. Signal to watch: notarial processing digitization announcements that compress 3-4 month clearance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Artisan Labor Network Acquisition | Captive restoration capacity secures margin control on châteaux renovation projects facing 40-60% labor premiums. |
| CNIL-Compliant Onboarding Infrastructure | GDPR-aligned client verification creates competitive whitespace as ANSM enforcement tightens on international transactions. |
| Alpine Resort Corridor Expansion | Climate-resilient ski-accessible assets in Megève and Courchevel offer first-mover positioning against Swiss comparables. |
| Multi-Source Brokerage Platform Launch | Decoupled advisory relationships displace exclusive listing arrangements for Anglo-Saxon procurement sophistication. |
| Energy Certification Pre-Bundling | RE2020 compliance warranties preserve pricing power on pre-1948 inventory facing steepest upgrade cost curves. |
Research Methodology
Direct dialogue with luxury brokerage principals, heritage restoration contractors, notarial officers, and family office real estate directors grounded qualitative findings in operational reality. Secondary validation synthesized ANSM regulatory filings, EU Green Deal transposition documents, French national building regulator technical bulletins, and transacted property registry extracts. Bottom-up transaction velocity analysis triangulated against top-down wealth migration pattern assessments across Middle Eastern and North American buyer cohorts.
Segmented outputs across property type, buyer profile, investment strategy, and sales channel dimensions structured the projection framework throughout the analysis window. CAGRs derived from historical transaction flow trajectories adjusted for RE2020 enforcement phase-in timelines and notarial processing digitization assumptions. Forecast inputs incorporated energy performance standard adoption curves, artisan labor supply elasticity estimates, and cross-border capital flow volatility indices.
Revisions become necessary when EU Green Deal enforcement timelines accelerate, notarial processing digitization stalls, or Middle Eastern capital flow restrictions materialize beyond modeled scenarios. Forecasts reflect documented assumptions on wealth migration persistence and regulatory compliance cost absorption capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
North America Real Estate Brokerage Market