
 Netherlands Luxury Residential Real Estate Market | 2026-2036
Netherlands Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Luxury Residential Real Estate Market Foresight
International expatriates are reorganizing demand patterns in Dutch luxury residential real estate, displacing traditional domestic retiree buyers in Amsterdam's premium segments. BPD leverages its integrated development pipeline to dominate waterfront villa projects across Randstad cities. Van Wijnen anchors its position through specialized sustainable construction methods that exceed national energy performance requirements. Christie's International Real Estate extends its brokerage reach by controlling high-end listing channels for foreign ultra-high-net-worth buyers seeking canal-side heritage properties.
Netherlands luxury residential real estate comprises high-value dwellings typically exceeding premium price thresholds, constructed with superior material specifications including triple-glazed facades, geothermal heat systems, and reinforced concrete frameworks designed for century-scale durability. These properties serve primarily as status-bearing primary residences and portfolio-diversifying assets for affluent households. Villas command the deepest margin pools among property types due to land scarcity in protected Dutch landscapes and bespoke architectural commissioning cycles. Smart home technology integration represents the fastest-growing amenity dimension as buyers prioritize automated climate systems and integrated security platforms. The ultra-premium pricing tier remains structurally supply-constrained, with bespoke catalog offerings capturing disproportionate value per square meter through architect-led customization protocols.
The Netherlands' Environmental Planning Act and Building Decree establish mandatory energy performance standards that filter market access for developers unable to deliver near-zero-energy dwellings. Dutch central bank DNB macro-prudential mortgage rules cap loan-to-value ratios, directly shaping buyer liquidity and transaction velocity in upper price segments. Municipal zoning boards in Amsterdam, Rotterdam, and The Hague exercise discretionary height and density restrictions that constrain new luxury supply in core districts. Stakeholders must monitor whether forthcoming national nitrogen deposition rulings tighten construction permitting timelines in ecologically sensitive Randstad peripheries.
Market Dynamics
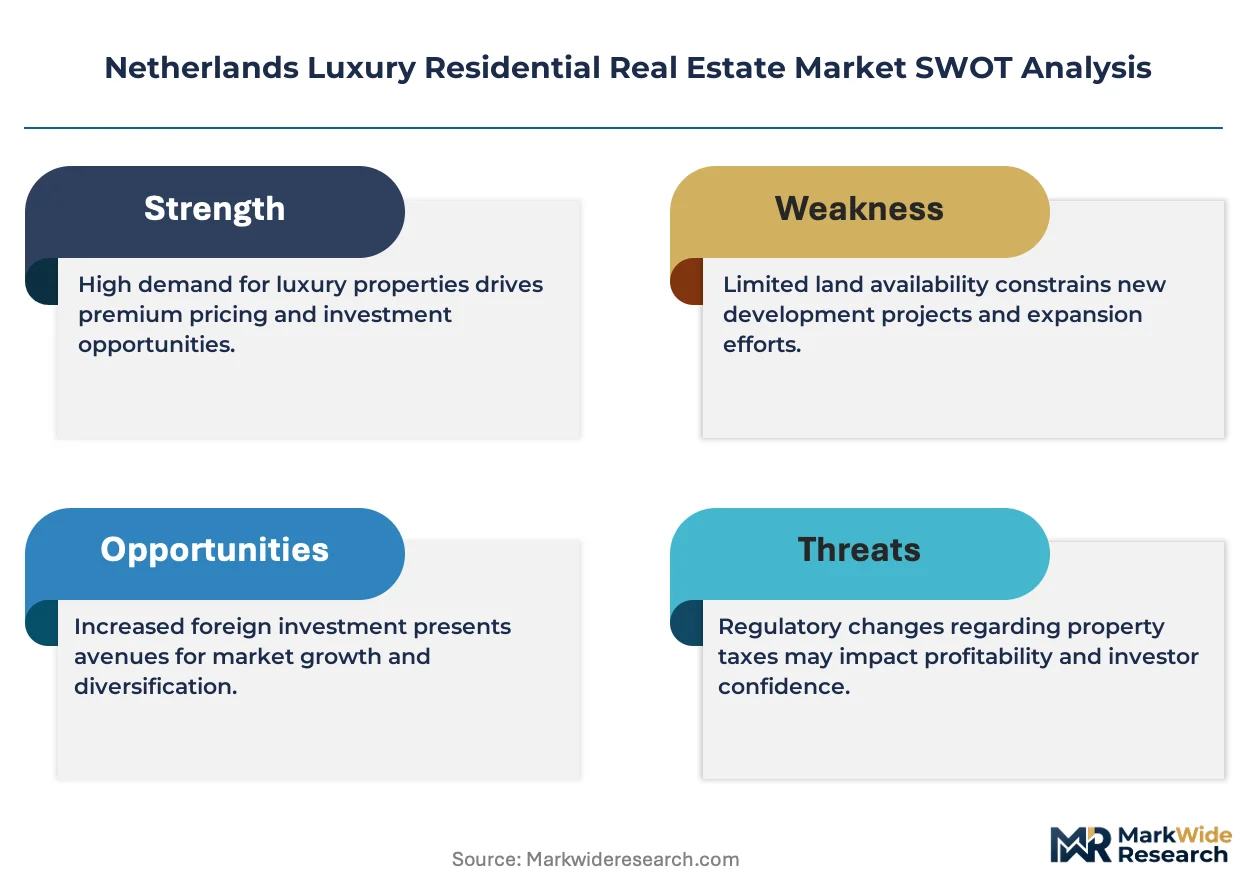
Amsterdam's canal district faces acute land scarcity while Dutch building codes mandate near-zero energy performance, forcing developers to reconcile heritage preservation constraints with stringent thermal efficiency requirements.
Growth Catalysts
- DNB Macro-Prudential Framework:The Dutch central bank's loan-to-value ratio caps stabilize buyer liquidity in upper segments, preventing speculative overheating that plagued comparable European luxury markets.
- International Expatriate Inflows:Relocation demand from financial services and technology professionals concentrates in Rotterdam's Kop van Zuid and Amsterdam's Zuidas corridor.
- Geothermal Heat Systems:Subsurface thermal extraction technology satisfies Building Decree energy mandates while preserving historic facade integrity in protected city centers.
Market Restraints
- Randstad Land Scarcity:Protected Dutch landscapes and municipal height restrictions in The Hague constrain greenfield villa development to peripheral provinces.
- Nitrogen Deposition Rulings:Pending national ecological rulings threaten construction permitting timelines in sensitive Randstad peripheries.
- Triple-Glazed Facade Costs:Heritage-compatible high-performance glazing carries material premiums that compress developer margins on conversion projects.
Strategic Opportunities
- North Brabant Secondary Cities:Eindhoven and Tilburg offer underpenetrated luxury segments with weaker incumbent developer presence.
- Smart Home Convergence:Integration of automated climate systems with integrated security platforms creates differentiation in new-build specifications.
- Environmental Planning Act Tailwinds:Near-zero-energy mandates filter out undercapitalized competitors, consolidating market access for compliant developers.
Industry Challenges
- Architect-Led Customization Timelines:Bespoke commissioning cycles for ultra-premium canal-side properties extend delivery windows and tie up working capital.
- Municipal Zoard Discretion:Amsterdam, Rotterdam, and The Hague exercise non-standardized density approvals that create project-level uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Luxury Residential Real Estate Market |
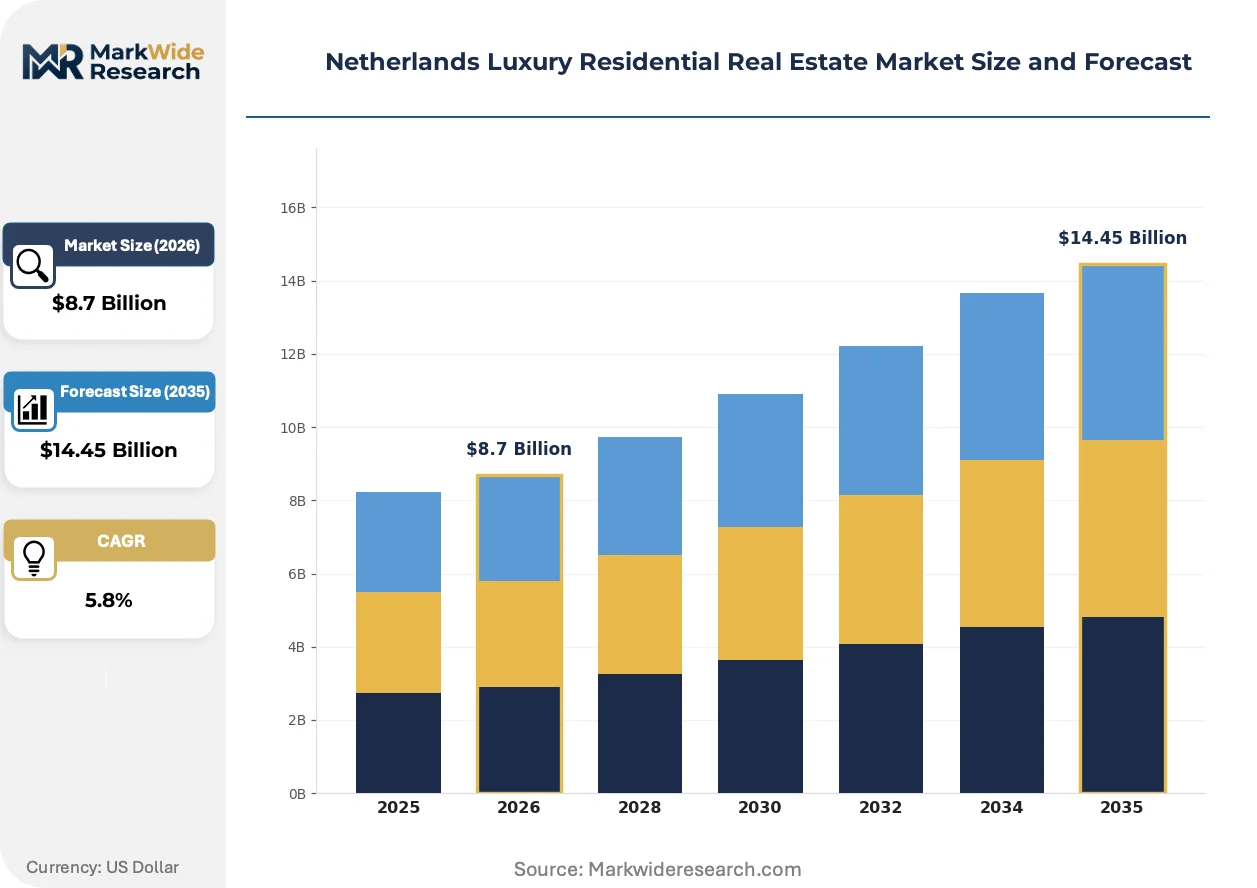
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Penthouses, Townhouses, Apartments Buyer Profile: High Net-Worth Individuals, Investors, Expats, Retirees Pricing Tier: Premium, Ultra-Premium, Exclusive, Bespoke Amenities: Smart Home Technology, Pools, Rooftop Terraces, Private Gardens |
| Companies Covered | Van Wijnen, VORM, BPD, Van Wanrooji Construction and Development, Dura Vermeer, Provast, VolkerWessels, Christie's International Real Estate, Heijmans, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Luxury Residential Real Estate Market Shifts & Advancements
Dutch luxury residential development is pivoting from speculative volume toward precision-engineered, regulation-compliant product that commands sustained price premiums through energy performance certification and automated amenity integration.
Geothermal heat pump networks paired with thermal storage aquifers are fragmenting the traditional gas-boiler heating paradigm in canal district renovations. Heritage property buyers now specify subsurface thermal extraction systems that satisfy Building Decree mandates without visible external modifications. This technology is fragmenting the market between compliant premium inventory and stranded legacy assets that face future retrofit obligations.
The Netherlands' Building Decree near-zero-energy standard is tightening envelope performance requirements faster than neighboring jurisdictions. Developers must achieve specified thermal transmittance values that exceed current EU Energy Performance of Buildings Directive baselines. North Holland province enforces these standards most stringently, with Amsterdam's municipal building inspectors rejecting submittals that marginally miss U-value thresholds.
International ultra-high-net-worth buyers are bypassing traditional brokerage channels for direct architect relationships and off-market acquisition structures. Canal-side heritage properties in Amsterdam's Grachtengordel now transact through private banking networks before public listing. This pattern concentrates in foreign buyer segments seeking portfolio diversification through Dutch residential assets.
Netherlands Luxury Residential Real Estate Market Segmentation
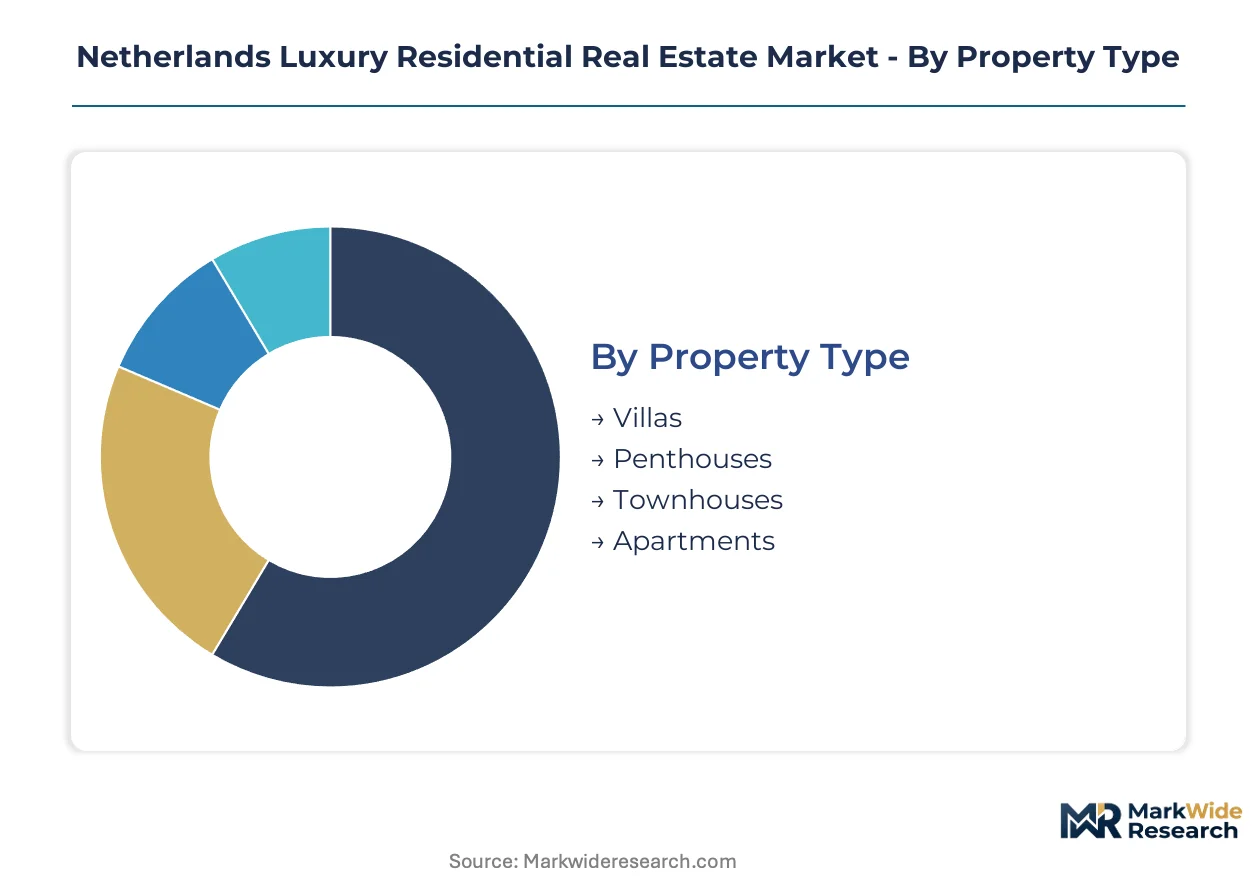
Channel differentiation across Dutch luxury residential real estate intensifies as international buyers favor direct architect relationships while domestic purchasers rely on traditional brokerage networks. Segmentation reveals how property type, buyer origin, and amenity specifications determine transaction velocity and margin capture in supply-constrained Randstad corridors.
Property Type:
Villas and penthouses dominate Amsterdam's canal district and Zuidas corridor through private banking networks, while townhouses and apartments flow through conventional high-end brokerage channels.
- Villas:Bespoke architectural commissioning on scarce greenfield land in protected Dutch landscapes commands the deepest margin pools. North Holland province concentrates demand where international ultra-high-net-worth buyers seek century-scale durability through reinforced concrete frameworks and geothermal heat systems.
- Penthouses:Vertical luxury inventory in Rotterdam's Kop van Zuid and Amsterdam's Zuidas corridor attracts financial services professionals relocating from London and Frankfurt. Municipal height restrictions constrain new supply, amplifying price premiums for existing stock with automated climate systems.
- Townhouses:Heritage-compatible renovations in Amsterdam's Grachtengordel satisfy Building Decree energy mandates through subsurface thermal extraction. Triple-glazed facade premiums compress developer margins on conversion timelines.
- Apartments:Standardized luxury specifications in The Hague and Utrecht serve domestic retiree segments displaced from premium Amsterdam inventory.
By volume, apartments lead. By growth pace, villas are expanding most quickly.
Buyer Profile:
Cost tier stratification separates expatriate demand concentrated above ultra-premium thresholds from retiree activity anchored in premium segments.
- High Net-Worth Individuals:Dutch domestic wealth concentrates in North Holland province canal-side acquisitions, prioritizing status-bearing primary residences with integrated security platforms.
- Investors:Portfolio diversification demand from German and Belgian capital seeks rental yield in Rotterdam's secondary luxury corridors.
- Expats:Technology and financial services professionals drive Zuidas corridor transactions, displacing traditional domestic buyers through off-market acquisition structures.
- Retirees:Downsizing demand shifts toward Eindhoven and Tilburg as Amsterdam price thresholds exclude traditional segments.
By transaction count, retirees dominate. By price per square meter, expats command the steepest expansion trajectory.
Pricing Tier:
Application-based stratification aligns bespoke catalog offerings with architect-led customization protocols while standardized premium inventory serves volume segments.
- Premium:Entry luxury threshold properties in Utrecht and The Hague feature superior material specifications without full customization cycles.
- Ultra-Premium:Amsterdam canal district inventory with geothermal integration and smart home convergence captures foreign buyer attention through private banking channels.
- Exclusive:Limited-release developments in Rotterdam's Kop van Zuid with rooftop terraces and private garden access target relocating corporate executives.
- Bespoke:Architect-led commissioning on scarce Randstad land with century-scale durability specifications serves ultra-high-net-worth portfolio diversification.
By unit volume, premium leads. By value concentration, bespoke is gaining share fastest.
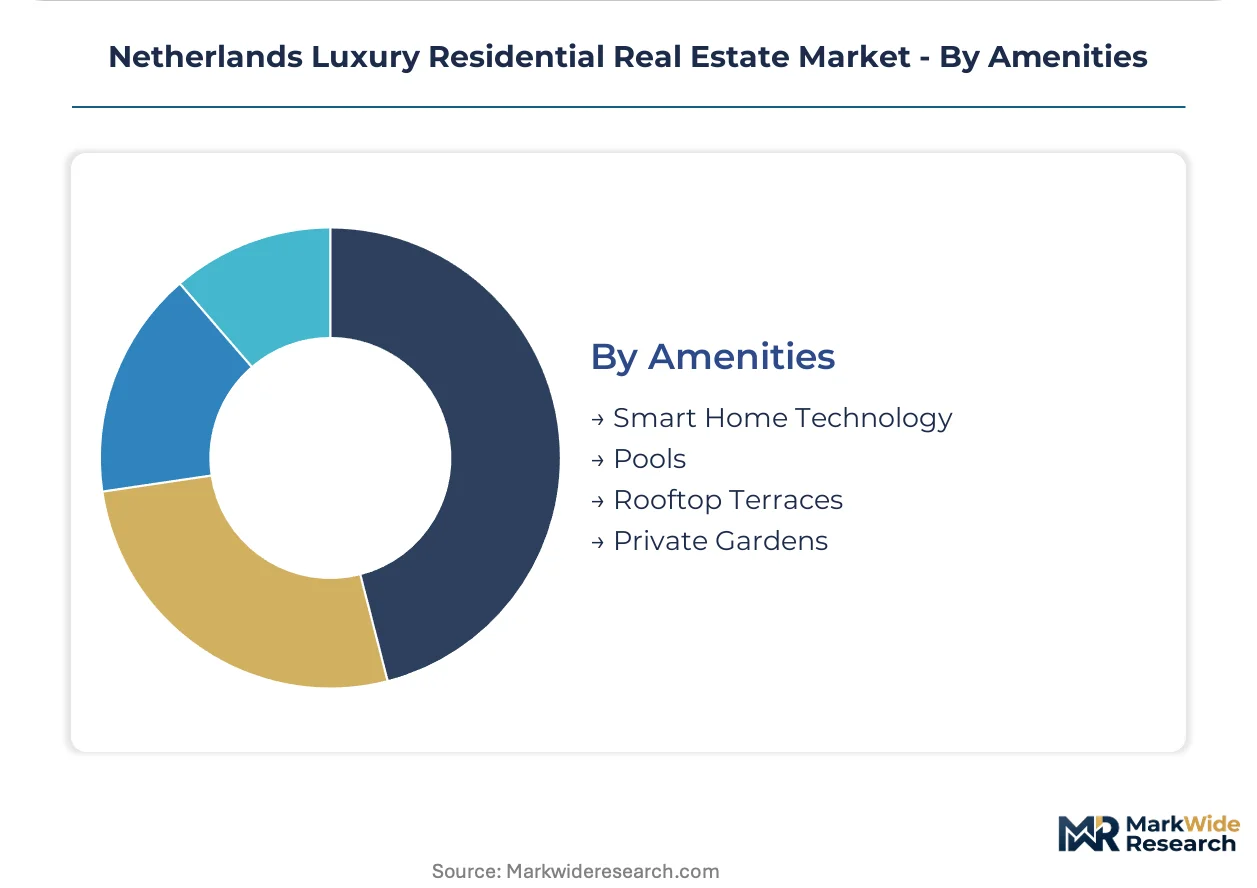
Amenities:
Customer type differentiation separates technology-forward expatriate demand from traditional domestic preferences for leisure-focused specifications.
- Smart Home Technology:Automated climate systems with integrated security platforms represent the fastest-growing amenity dimension as Rotterdam and Amsterdam buyers prioritize remote management capabilities.
- Pools:Indoor thermal pools in North Brabant villas satisfy wellness-focused retiree segments in secondary cities.
- Rooftop Terraces:Outdoor space premiums in height-restricted Amsterdam core districts command disproportionate value per square meter.
- Private Gardens:Scarcity value in dense Randstad urban fabric attracts family-oriented expatriate buyers seeking green space proximity.
By installation frequency, private gardens lead. By specification intensity, smart home technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury residential capital flows from Germany, Belgium, and the United Kingdom into Dutch canal-side assets, with Amsterdam and Rotterdam absorbing the majority of cross-border investment directed at heritage properties and new-build sustainable developments.
North Holland
International financial services professionals concentrate demand in Amsterdam's Zuidas corridor and Grachtengordel canal district. The province enforces the Netherlands' most stringent Building Decree thermal transmittance standards. Amsterdam municipal inspectors reject submittals marginally missing U-value thresholds, compressing development timelines for heritage-compatible conversions.
South Holland
Rotterdam's Kop van Zuid attracts technology sector relocations from London and Frankfurt seeking vertical luxury inventory. Municipal height restrictions constrain new penthouse supply, amplifying price premiums for existing stock with automated climate systems. The port city's waterfront regeneration programs channel development toward sustainable high-performance specifications.
North Brabant
Eindhoven and Tilburg present underpenetrated luxury segments with weaker incumbent developer presence. Domestic retiree downsizing demand shifts toward these secondary cities as Amsterdam price thresholds exclude traditional segments. Provincial authorities apply Building Decree standards less stringently than Randstad counterparts, shortening permitting cycles.
Utrecht
Central location advantages position the city as a commuter hub for Amsterdam and The Hague professionals seeking entry-luxury townhouses. DNB macro-prudential mortgage caps shape buyer liquidity across all price tiers. The Utrecht Science Park corridor concentrates demand from academic and research institution employees.
Netherlands Luxury Residential Real Estate Market Competitive Landscape
Player mix skews toward integrated development-holding conglomerates with captive construction arms and specialized sustainable builders. Market structure concentrates around vertically organized entities controlling land acquisition through delivery. Three archetypes dominate: heritage renovation specialists, large-scale sustainable volume developers, and international brokerage networks. Competitive moves center on land banking in protected landscapes and technology licensing for geothermal integration.
Among Dutch integrated developers, BPD and Van Wijnen occupy positions anchoring distinct strategic vectors. BPD represents the waterfront land-banking archetype with Randstad project pipelines. Van Wijnen exemplifies specialized sustainable construction methods exceeding national energy performance requirements. Christie's International Real Estate sits within the international brokerage tier, controlling high-end listing channels for foreign ultra-high-net-worth buyers.
| Leading Market Players |
|---|
| Van Wijnen |
| VORM |
| BPD |
| Van Wanrooji Construction and Development |
| Dura Vermeer |
| Provast |
| VolkerWessels |
| Christie's International Real Estate |
| Heijmans |
| Others |
Supply & Pricing Matrix
Geothermal heat pump networks replacing conventional gas-boiler systems in canal district renovations simultaneously concentrate supply relationships among specialized Dutch HVAC contractors and elevate pricing premiums for heritage-compatible thermal extraction technology. This substitution dynamic fragments procurement options while amplifying cost differentials between compliant premium inventory and stranded legacy assets facing future retrofit obligations.
Pricing Analysis
Next-generation geothermal integration commands substantial premiums over prior-generation gas-boiler specifications and emerging hydrogen-ready alternatives in Amsterdam's Grachtengordel. Pricing stratifies across bespoke architect-led commissioning, ultra-premium certified energy performance, and standardized premium inventory serving volume segments. Price differentiation rests on Building Decree certification tiers and facade preservation complexity. Margins are tightening for conversion projects because triple-glazed heritage-compatible glazing carries material premiums that compress developer returns. Domestic retiree buyers exhibit highest price sensitivity, while international ultra-high-net-worth purchasers demonstrate lowest elasticity for canal-side heritage assets.
Supply Chain Analysis
Extended lead times for triple-glazed heritage-compatible facades and geothermal heat pump components constrain project velocity across Randstad developments. Supply concentrates in Germany, Belgium, and domestic Dutch manufacturers for high-performance glazing systems and subsurface thermal extraction equipment. Raw material dependencies encompass low-iron glass for optical clarity, copper piping for ground-source loops, and reinforced concrete for century-scale structural frameworks. Single-source vulnerability runs through specialized heritage glazing fabricators with limited European capacity. Distribution feeds from manufacturer-direct relationships for bespoke components and regional building supply networks for standardized materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Netherlands luxury residential real estate sits in early-cycle expansion as international expatriate penetration in Amsterdam and Rotterdam remains below saturation thresholds despite accelerating relocation flows from London and Frankfurt financial services sectors.
For Market Incumbents: Consolidate land banking positions in protected North Holland landscapes before nitrogen deposition rulings tighten construction permitting timelines. Acquire specialized geothermal installation capabilities to reduce subcontractor dependency and capture margin pools currently flowing to third-party HVAC specialists. The emerging threat of architect-led direct buyer relationships bypassing traditional development channels demands captive design-build integration. For New Entrants and Emerging Players: Building Decree energy performance certification fast-tracks market access for compliant developers as near-zero-energy mandates filter out undercapitalized competitors. Target Eindhoven and Tilburg in North Brabant province where incumbent developer presence remains weaker and permitting cycles run shorter than Randstad counterparts. Pursue municipal zoning pre-approvals in secondary cities ahead of formal land acquisition to de-risk greenfield villa projects. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized Dutch developers lacking integrated construction arms and captive land pipelines. Long-term viability across the projection horizon favors vertically organized entities controlling acquisition through delivery. The signal to watch is nitrogen deposition ruling implementation velocity, which would accelerate consolidation pressure on peripheral land positions.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Integration Partnership | Secures subsurface thermal extraction capabilities for heritage-compatible renovations in Amsterdam's canal district. |
| Land Banking in Protected Landscapes | Captures scarce greenfield positions in North Holland before municipal density restrictions tighten further. |
| Smart Home Platform Licensing | Differentiates new-build specifications through automated climate systems and integrated security platforms. |
| Architect Relationship Development | Establishes off-market acquisition channels for foreign ultra-high-net-worth buyers seeking bespoke canal-side properties. |
| North Brabant Geographic Expansion | Penetrates underexploited Eindhoven and Tilburg segments with shorter permitting cycles than Randstad corridors. |
Research Methodology
Desk research of municipal zoning records, DNB macro-prudential policy filings, and Building Decree technical specifications preceded structured interviews with development executives, heritage renovation specialists, municipal planning officers, and international brokerage directors. Primary fieldwork combined with secondary validation against Dutch Central Bureau of Statistics housing transaction data, Kadaster property registry extracts, and European Energy Performance Certificate databases. Bottom-up project pipeline enumeration and top-down macroeconomic scenario modeling were triangulated for consistency.
Variance decomposition across property type, buyer origin, pricing tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value build-ups calibrated to historical transaction velocity patterns. Forecast inputs incorporated expatriate relocation flow projections from financial services and technology sectors, nitrogen deposition ruling implementation scenarios, and Building Decree enforcement intensity differentials across provinces.
The analysis sits within stated boundaries; outcomes outside sustained international buyer inflows or accelerated regulatory tightening would require recalibration. Forecasts reflect documented assumptions regarding mortgage liquidity conditions and heritage preservation policy stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market