
 Egypt Manufactured Homes Market | 2026-2036
Egypt Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Manufactured Homes Market Foresight
Buyer concentration among Egypt's government housing authorities is broadening as private developers and commercial resort operators enter the procurement pool. Middle East Caravan leverages its coastal project portfolio to dominate Red Sea tourism installations. Cretematic Prefabricated Concrete & Steel Structures - S A E anchors large-scale concrete modular production for infrastructure-adjacent housing. ICON competes through steel-frame specialization targeting industrial workforce accommodation.
Manufactured homes are factory-built residential structures assembled from pre-engineered components, typically employing steel framing, insulated wall panels, and integrated utility systems designed for rapid on-site installation. These structures serve Egypt's urgent need for scalable, cost-controlled housing delivery in desert expansion zones and remote employment centers. Single Section units lead volume due to their compatibility with narrow urban infill plots and constrained construction budgets. Multi Section configurations capture margin pools from gated community developers seeking faster project completion cycles. Steel material demand outpaces wood alternatives given Egypt's limited timber supply and the durability requirements of arid-climate deployment.
Egypt's Housing and Building National Research Center sets structural performance benchmarks for prefabricated units, while the New Urban Communities Authority governs land allocation and project approval timelines in satellite cities. The Egyptian Organization for Standardization and Quality aligns local manufacturing with ISO certification requirements to support export eligibility. Stakeholders must monitor how forthcoming building energy codes and green construction mandates reshape material specifications and factory certification thresholds.
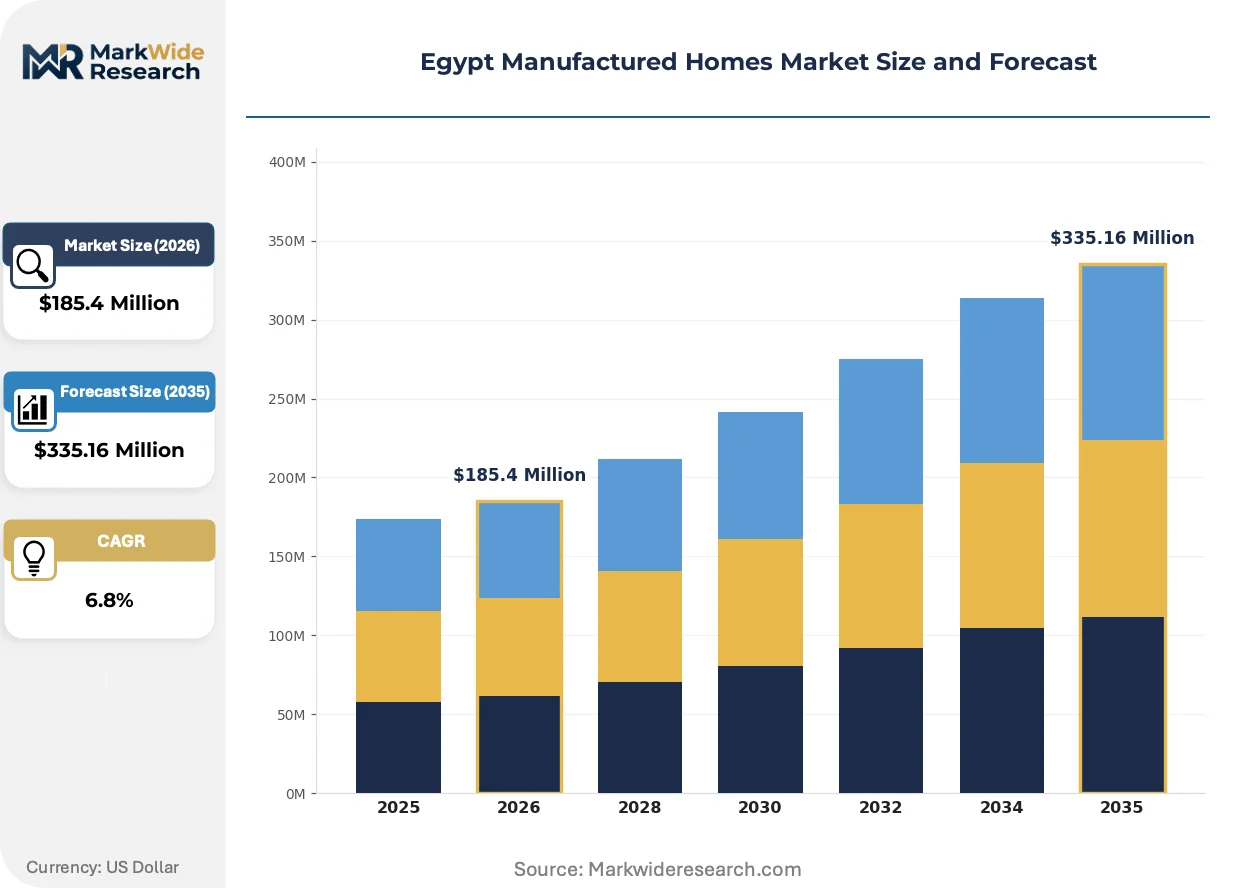
Market Dynamics
Egypt's manufactured homes sector is being fundamentally restructured by the New Urban Communities Authority's accelerated permitting protocols for prefabricated structures, which compress project timelines from years to months in desert satellite cities.
Growth Catalysts
- New Urban Communities Authority Permitting:Streamlined approvals for prefabricated units in the New Administrative City and Suez Canal Economic Zone eliminate traditional construction bottlenecks.
- Suez Canal Economic Zone Workforce Housing:Industrial zone operators require rapid-deployment accommodation for expatriate labor, creating sustained procurement pipelines for steel-frame modular units.
- Steel Framing Material Substitution:Domestic steel production capacity supports cost-competitive framing alternatives to imported timber, aligning with Egypt's import substitution industrial policy.
Market Restraints
- Reinforcement Steel Price Volatility:Fluctuations in Egyptian steel billet pricing directly compress manufacturer margins on fixed-price government contracts.
- Concentrated Coastal Logistics:Red Sea port capacity constraints limit factory-to-site delivery efficiency for tourism resort installations outside Greater Cairo.
- Foundation Engineering Complexity:Desert soil conditions require specialized pile-driving equipment that few local contractors possess, extending site preparation timelines.
Strategic Opportunities
- Upper Egypt Underserved Markets:Sohag, Assiut, and Qena governorates lack established prefabricated housing supply chains despite population displacement pressures.
- Green Building Certification Alignment:Anticipated energy efficiency mandates from the Egyptian Organization for Standardization and Quality will favor insulated panel manufacturers with ISO 14001 credentials.
- Tourism Resort Channel Expansion:Red Sea coastal developers are bypassing traditional general contractors to source directly from modular producers for staff accommodation blocks.
Industry Challenges
- Skilled Welding Labor Scarcity:Certified steel-frame assemblers are concentrated in Alexandria and Cairo, forcing manufacturers to relocate workers to remote project sites.
- Utility Integration Certification Delays:Egyptian Electricity Holding Company inspection backlogs for prefabricated unit electrical connections extend handover timelines by four to eight weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Manufactured Homes Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Section, Multi Section, Tiny Homes, Modular Units Material: Wood, Steel, Concrete, Composite End User: Residential, Commercial, Government, Educational Sales Channel: Direct Sales, Online Retail, Distributors, Showrooms |
| Companies Covered | Middle East Caravan, Cretematic Prefabricated Concrete & Steel Structures - S A E, Industrial Engineering Company for Construction and Development (ICON), Shewekar Design Studio, Al Quds Steel, DTH PREFAB, Rush Projects Egypt "RPE", Dalal Steel Industries, Arabian Construction House Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Manufactured Homes Market Shifts & Advancements
Factory-built housing in Egypt is transitioning from emergency shelter provision to permanent residential infrastructure, driven by quality certification upgrades and buyer sophistication in satellite city developments.
Insulated sandwich panel technology is converging with photovoltaic-integrated roofing systems in manufactured home production. Gated community developers in the New Administrative City are specifying solar-ready modular units to meet anticipated net-zero building requirements. This convergence is compressing the traditional separation between structural fabrication and renewable energy installation, forcing manufacturers to certify electrical integration capabilities that were previously subcontracted.
Egypt's Housing and Building National Research Center is tightening structural performance benchmarks for seismic resistance in prefabricated units. The revised technical specifications will mandate enhanced steel connection detailing for multi-section configurations. Large-scale contractors in Greater Cairo are pre-emptively upgrading factory quality systems to secure eligibility for upcoming government housing tenders.
Buyer purchasing patterns are fragmenting from centralized government procurement toward distributed developer direct sourcing. Private real estate firms in the Suez Canal Economic Zone are negotiating factory gate pricing for volume commitments, bypassing traditional distributor markups. This disintermediation is most pronounced in industrial workforce housing, where project developers possess sufficient technical expertise to specify directly from manufacturers.
Egypt Manufactured Homes Market Segmentation
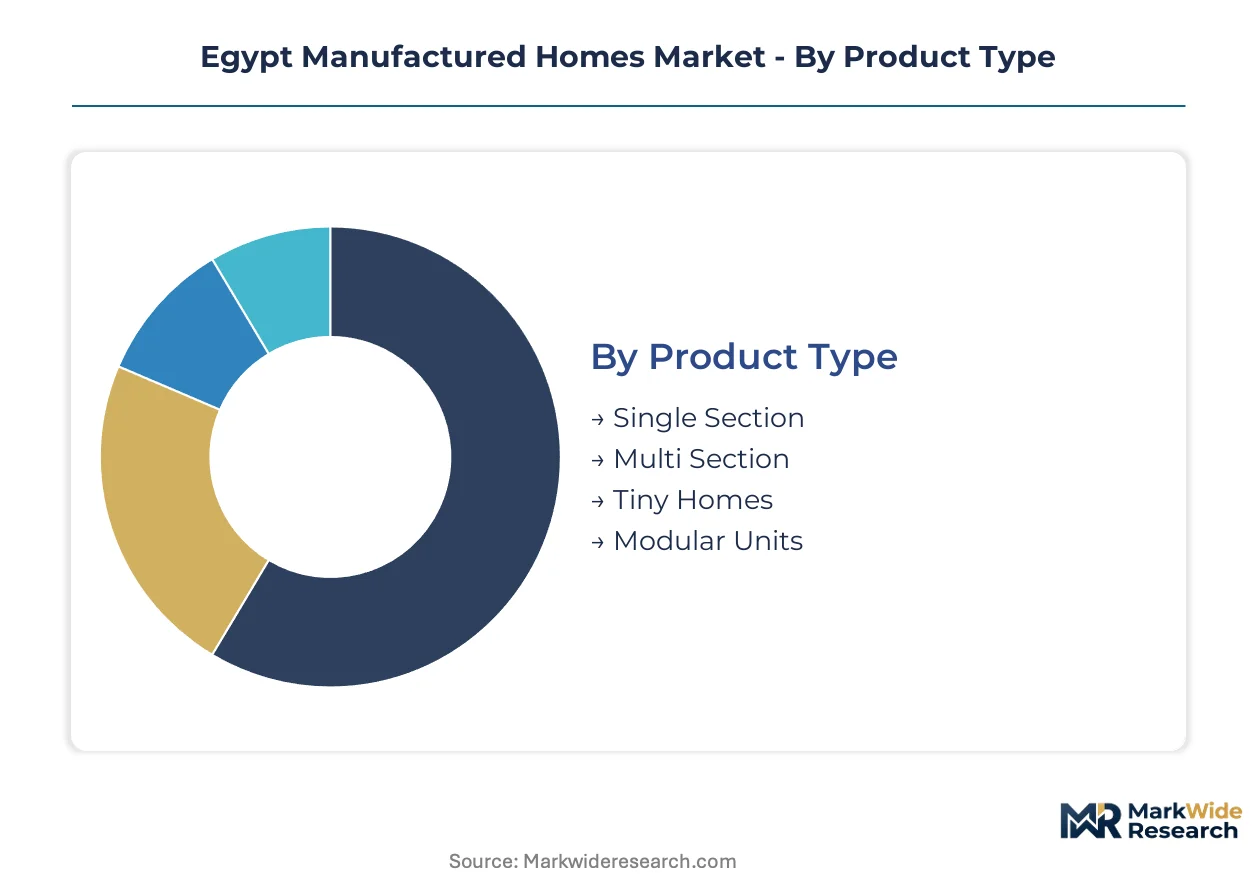
Segmentation in Egypt's manufactured homes market reveals how factory-built housing adapts to divergent site constraints, procurement budgets, and regulatory environments across desert satellite cities and coastal zones. Understanding these divides exposes where margin pools concentrate and which specifications command premium positioning.
Product Type:
Structural configuration determines transport logistics, foundation requirements, and on-site assembly complexity in Egypt's dispersed development corridors.
- Single Section:Factory-built units ship as complete modules requiring minimal on-site joining. Narrow urban infill plots in Greater Cairo's low-income districts absorb these units for their compatibility with constrained construction budgets and tight site access.
- Multi Section:Configurations arrive as separate modules requiring field connection. Gated community developers in the New Administrative City specify these for accelerated project completion cycles that compress holding costs.
- Tiny Homes:Compact footprint structures target remote employment centers and temporary workforce accommodation in the Suez Canal Economic Zone.
- Modular Units:Standardized dimensional systems enable volume manufacturing for repetitive deployment across government housing programs.
Single Section leads on scale; Multi Section leads on momentum.
Material:
Raw material selection reflects Egypt's import substitution priorities and the durability demands of arid-climate deployment.
- Steel:Galvanized framing systems dominate factory output given domestic billet production capacity and resistance to desert corrosion. Industrial zone operators in the Suez Canal Economic Zone specify steel-frame units for workforce housing longevity.
- Concrete:Precast panel construction anchors large-scale infrastructure-adjacent housing. Cretematic Prefabricated Concrete & Steel Structures - S A E specializes in this category for government tenders requiring seismic resilience.
- Wood:Timber framing remains marginal due to Egypt's limited domestic supply and import dependency for treated lumber.
- Composite:Insulated sandwich panels with integrated thermal barriers serve tourism resort developers seeking rapid envelope completion.
Steel commands volume leadership; concrete captures the steepest expansion trajectory in infrastructure-linked projects.
End User:
Buyer type dictates specification stringency, certification requirements, and contract structure in Egypt's bifurcated procurement landscape.
- Residential:Individual and family housing demand concentrates in Greater Cairo's informal settlement upgrading programs and New Urban Communities Authority satellite city allocations.
- Commercial:Tourism resort operators along the Red Sea coast source directly from manufacturers for staff accommodation blocks, bypassing traditional general contractor markups.
- Government:New Urban Communities Authority tenders specify prefabricated units for social housing delivery, with structural performance benchmarks set by the Housing and Building National Research Center.
- Educational:School and university expansion projects in desert new cities generate periodic demand for classroom and dormitory modules.
Government procurement anchors current volume; commercial buyers are gaining share fastest through direct sourcing.
Sales Channel:
Channel structure determines pricing transparency, technical specification depth, and post-sale service allocation across Egypt's manufacturing base.
- Direct Sales:Factory gate contracting enables volume purchasers in the Suez Canal Economic Zone to negotiate pricing without distributor margins. Technical staff from manufacturers handle specification directly.
- Distributors:Regional inventory holders serve dispersed governorates where factory proximity is limited, particularly in Upper Egypt's underserved markets.
- Showrooms:Physical display centers in Greater Cairo allow end-users to evaluate finish quality before purchase, supporting residential segment confidence.
- Online Retail:Digital catalog platforms remain nascent, constrained by the need for site-specific foundation engineering consultation.
Direct Sales leads on transaction value; Distributors extend geographic coverage most aggressively.
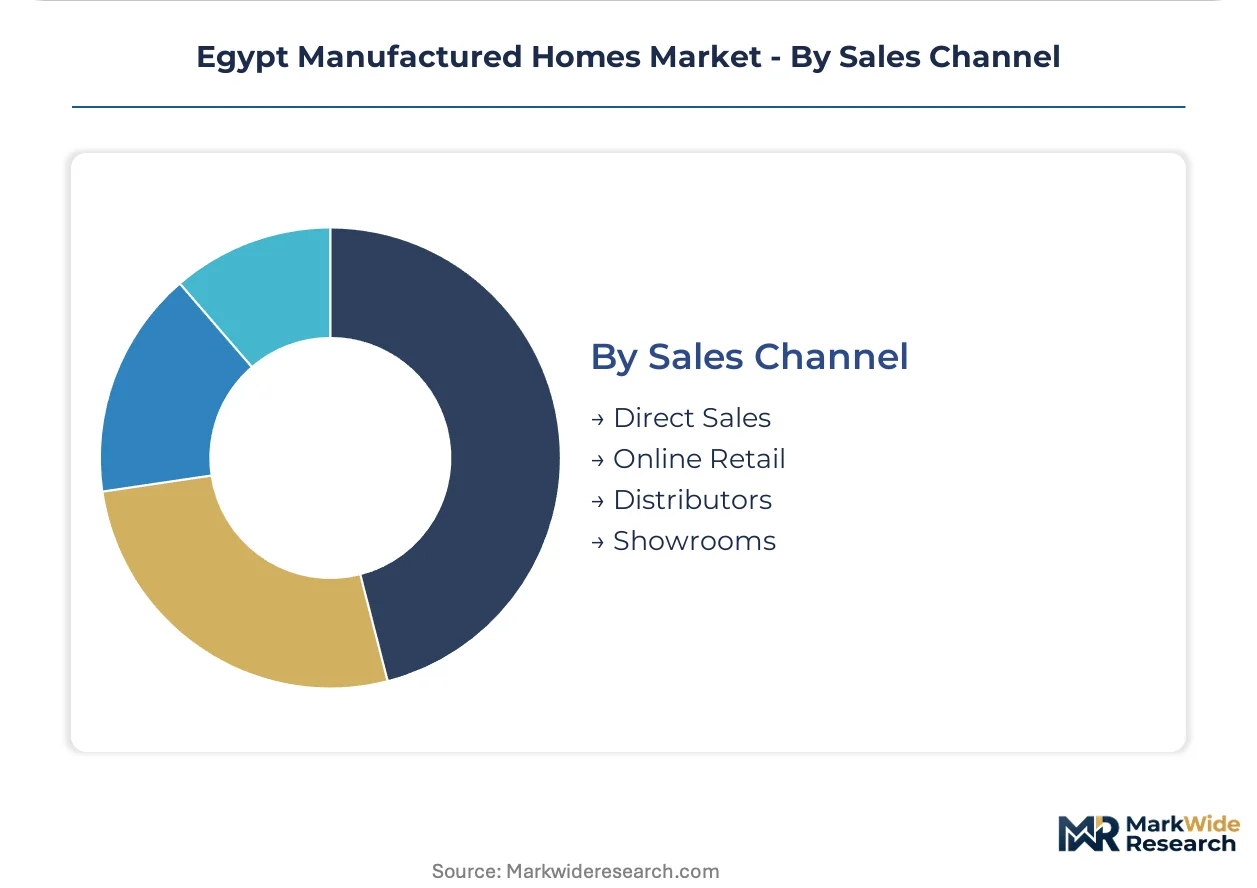
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's manufactured homes sector outpaces Morocco's nascent modular housing programs in deployment velocity, while trailing Saudi Arabia's scale in integrated desert city construction. The analysis examines five sub-regional markets where factory-built housing concentrates.
Greater Cairo
Informal settlement upgrading programs and narrow urban infill plots drive Single Section unit absorption in low-income districts. The New Urban Communities Authority governs land allocation and project approvals in satellite city extensions. Cairo's industrial corridor hosts steel-frame fabricators serving government social housing tenders.
Suez Canal Economic Zone
Industrial zone operators require rapid-deployment workforce accommodation for expatriate labor, sustaining procurement pipelines for steel-frame modular units. The Suez Canal Authority coordinates infrastructure access for factory-to-site logistics. Port Said and Ismailia clusters concentrate manufacturers supplying direct-to-developer contracts.
Red Sea Coast
Tourism resort operators source staff accommodation blocks directly from modular producers, bypassing traditional general contractor markups. The Egyptian General Authority for Tourism Development regulates coastal construction permits. Hurghada and Sharm El-Sheikh anchor manufacturing capacity for hospitality-sector deployments.
New Administrative City
Gated community developers specify Multi Section configurations to compress project completion cycles and reduce holding costs. The New Urban Communities Authority streamlined permitting protocols specifically for prefabricated structures in this zone. East Cairo fabrication parks serve volume contracts from private real estate firms.
Upper Egypt
Sohag, Assiut, and Qena governorates lack established prefabricated housing supply chains despite population displacement pressures. The Ministry of Housing's social housing programs allocate limited modular unit quotas to these regions. Distribution networks remain underdeveloped, constraining manufacturer penetration.
Egypt Manufactured Homes Market Competitive Landscape
Greater Cairo producers anchor one tier; Alexandria and coastal specialists hold differentiated positions in tourism and industrial segments. The vendor base spans steel-frame fabricators, concrete panel specialists, and integrated design-build operators. Three archetypes dominate: steel-structure volume manufacturers, concrete modular engineers, and resort-focused turnkey providers. Capacity expansion and direct-to-developer contracting represent the dominant competitive vectors.
Within the steel-structure tier, Middle East Caravan and Industrial Engineering Company for Construction and Development occupy positions aligned with coastal and industrial workforce housing respectively. Cretematic Prefabricated Concrete & Steel Structures - S A E exemplifies the concrete modular archetype serving infrastructure-adjacent government tenders. These three entities represent the spectrum from tourism-specialized fabrication to large-scale concrete production for seismic-resilient social housing.
| Leading Market Players |
|---|
| Middle East Caravan |
| Cretematic Prefabricated Concrete & Steel Structures - S A E |
| Industrial Engineering Company for Construction and Development (ICON) |
| Shewekar Design Studio |
| Al Quds Steel |
| DTH PREFAB |
| Rush Projects Egypt "RPE" |
| Dalal Steel Industries |
| Arabian Construction House Group |
| Others |
Supply & Pricing Matrix
Backward integration into domestic steel billet production anchors both cost predictability and margin defense for Egyptian manufactured home producers bidding on fixed-price government contracts. This upstream control over framing materials insulates factory gate pricing from import volatility while compressing procurement cycles for Suez Canal Economic Zone developers.
Pricing Analysis
Capacity additions in Greater Cairo's industrial corridor are reshaping price floors for steel-frame modular units as new entrants absorb fixed costs across larger production runs. Project-based transactional pricing dominates government tenders from the New Urban Communities Authority, while direct-to-developer contracts in the Red Sea coast bypass distributor markups entirely. Price differentiation rests on ISO 14001 certification status and seismic performance tier, with green-certified units commanding positioning premiums. Cost compression in economy-tier single-section units is intensifying because reinforcement steel price volatility passes through immediately on thin-margin contracts. Government housing authorities exhibit highest price sensitivity; tourism resort operators demonstrate lowest sensitivity due to accelerated completion value.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale buyer demand from Suez Canal Economic Zone industrial operators, while regional distributors extend coverage into Upper Egypt's underserved governorates. Geographic supply concentration centers on Egypt's domestic steel production, Chinese insulated panel imports, and Turkish composite material suppliers. Raw material dependencies include galvanized steel framing, polyurethane sandwich panels, and photovoltaic-integrated roofing membranes. Single-source vulnerability in certified welding labor pools concentrated in Alexandria and Cairo forces manufacturers to relocate skilled assemblers to remote project sites, extending mobilization timelines. Distribution runs through factory-direct contracting for volume buyers and showroom retail for individual residential purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's manufactured homes sector functions as a stable compounder, with the New Urban Communities Authority's accelerated permitting protocols generating predictable procurement pipelines across satellite city developments.
For Market Incumbents: Anchor market position through captive steel fabrication capacity and pre-emptive seismic certification upgrades ahead of Housing and Building National Research Center benchmark revisions. Defend against direct-sourcing disintermediation by embedding technical specification staff within Suez Canal Economic Zone developer procurement teams. Prioritize welding training center investments to reduce skilled labor scarcity exposure. For New Entrants and Emerging Players: The New Urban Communities Authority's streamlined prefabricated structure approvals in Upper Egypt opens a window for first-mover positioning in Sohag, Assiut, and Qena governorates lacking established supply chains. Target educational sector dormitory modules as the most penetrable application given periodic Ministry of Housing allocations. Pursue factory gate pricing partnerships with industrial zone operators possessing direct specification capability. For Investors and Strategic Acquirers: Roll-up economics work for steel-frame volume manufacturers because buyer concentration among government housing authorities creates predictable offtake visibility for scaled producers. Long-term viability hinges on certification moats and direct-developer relationships rather than distributor networks. Monitor Egyptian Organization for Standardization and Quality energy efficiency mandate timing as inflection indicator for insulated panel manufacturer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Framing | Captive billet supply insulates margins from Egyptian steel price volatility on government tenders. |
| ISO 14001 Certification Investment | Green credentials position manufacturers for anticipated Egyptian Organization for Standardization and Quality efficiency mandates. |
| Direct Developer Contracting | Bypassing distributor markups captures margin pools from Suez Canal Economic Zone industrial housing procurement. |
| Upper Egypt Distribution Expansion | First-mover positioning in Sohag and Assiut exploits Ministry of Housing social housing allocation gaps. |
| Seismic Performance Pre-Certification | Early compliance with Housing and Building National Research Center benchmarks secures eligibility for upcoming government tenders. |
Research Methodology
Direct dialogue with factory operations managers, New Urban Communities Authority procurement officers, Suez Canal Economic Zone developer technical teams, and Egyptian Organization for Standardization and Quality certification auditors grounded demand-side and regulatory intelligence. Secondary validation drew from customs steel import records, Housing and Building National Research Center technical specifications, New Urban Communities Authority project approval databases, and Egyptian Electricity Holding Company connection inspection backlogs. Bottom-up unit deployment estimates across five sub-regional markets triangulated against top-down construction spending allocations.
Segment-level outputs across product type, material, end user, and sales channel dimensions fed into a unified analytical framework spanning the projection horizon. CAGRs were derived from regression-based demand elasticity modeling calibrated to satellite city population absorption targets and industrial zone workforce housing mandates. Key inputs included New Urban Communities Authority land allocation schedules, Suez Canal Authority infrastructure access timelines, and Red Sea coastal tourism development permits.
Revisions become necessary when Egyptian steel billet pricing volatility exceeds historical bands, New Urban Communities Authority permitting protocols shift, or green building certification thresholds advance ahead of anticipated schedules. Forecasts reflect documented assumptions regarding government housing program continuity and industrial zone expatriate labor inflows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
UK Residential Real Estate Market