
 UK Residential Real Estate Market | 2026-2036
UK Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
UK Residential Real Estate Market Insights
First-time buyer concentration is decoupling from traditional mortgage-dependent pathways as shared ownership and institutional rental pathways expand. Barratt Developments leverages its national land bank to sustain volume delivery across England and Wales. Persimmon differentiates through standardized house types that compress construction cycles and reduce cost variability. Greystar anchors the build-to-rent segment with purpose-designed multifamily assets targeting urban professionals.
UK Residential Real Estate encompasses permanent dwelling structures intended for private habitation, typically constructed with load-bearing masonry or timber frames, compliant with Part L thermal efficiency standards and Part B fire safety regulations, serving as primary shelter assets within household wealth portfolios. Apartments and terraced houses capture the fastest structural expansion as urban density policies restrict greenfield sprawl around London, Birmingham, and Manchester. Luxury homes and eco-friendly homes concentrate margin pools where energy performance certificates and net-zero retrofit specifications command pricing premiums over standard new-build stock. Family homes retain volume dominance across suburban corridors but face land scarcity constraints that elevate per-unit development costs.
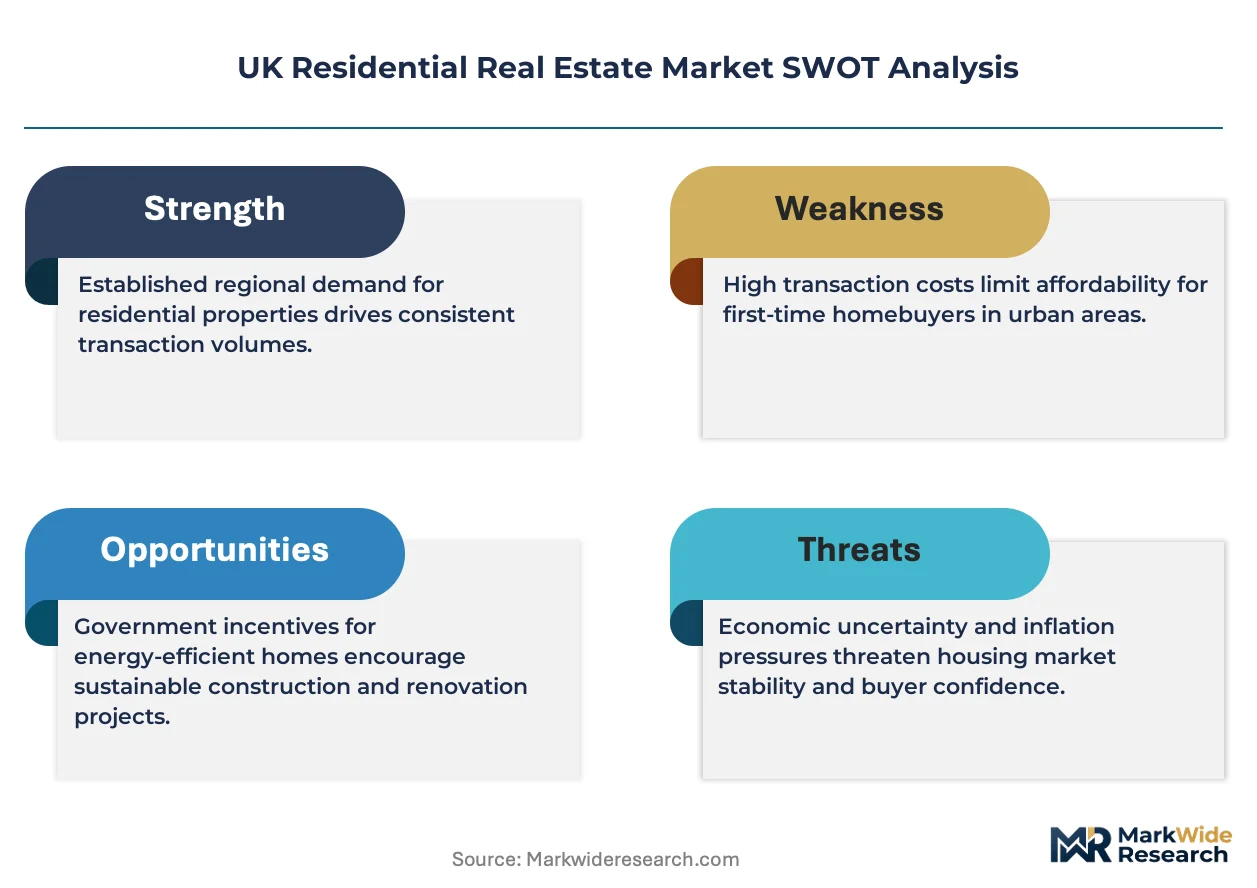
The Building Safety Regulator enforces higher-risk building gateway compliance, while HM Treasury's stamp duty adjustments and Bank of England base rate movements directly modulate transaction liquidity and leverage capacity. Local planning authorities apply National Planning Policy Framework density targets that constrain supply elasticity in high-demand sub-markets. Stakeholders must monitor whether interest rate stabilization restores first-time buyer mortgage access or permanently shifts tenure patterns toward institutional rental and shared ownership structures.
Market Dynamics
The Building Safety Act's gateway compliance regime is fundamentally restructuring development economics across England and Wales, forcing developers to front-load capital commitments before construction begins and compressing returns on higher-risk residential towers.
Growth Catalysts
- Stamp Duty Threshold Adjustments:HM Treasury's fiscal interventions directly modulate first-time buyer transaction velocity, with threshold recalibrations triggering demand surges in sub-£425,000 price brackets across Greater London commuter zones.
- Heat Pump Deployment Mandates:Part L thermal efficiency standards are accelerating fabric-first retrofit specifications, compelling developers to integrate air-source heat pumps and triple-glazing assemblies into new-build designs.
- Build-to-Rent Capital Flows:Institutional investors are channeling capital into purpose-designed multifamily assets, with Greystar and Legal & General deploying patient capital into 500+ unit urban clusters.
Market Restraints
- Land Scarcity Premium:Greenbelt protection around Birmingham, Manchester, and Bristol constrains developable land supply, elevating per-plot acquisition costs by structural multiples compared to continental European markets.
- Construction Input Volatility:Timber frame and structural steel pricing remains exposed to Baltic supply disruptions and energy-intensive manufacturing cost swings, compressing gross development margins unpredictably.
- Planning Permission Delays:Local authority capacity constraints under the National Planning Policy Framework extend determination timelines to 18-24 months, freezing capital deployment and inflating carrying costs.
Strategic Opportunities
- Net-Zero Retrofit Ecosystem:The Future Homes Standard creates regulatory tailwinds for whole-house retrofit providers targeting pre-1919 solid-wall stock across Northern England and the Midlands.
- Shared Ownership Channel Expansion:Housing associations and institutional developers are pioneering staircasing-light structures that reduce deposit barriers for median-income households in high-value sub-markets.
- Modular Fabrication Convergence:Off-site manufacturing techniques combined with digital building information modeling are compressing construction cycles from 24 weeks to 12 weeks for standardized house types.
Industry Challenges
- Building Control Professional Shortage:The Building Safety Regulator's expanded remit has created acute scarcity of qualified building control surveyors, delaying gateway sign-offs and extending project timelines.
- Warranty Provider Capacity Constraints:NHBC and alternative warranty schemes face capacity limitations in underwriting higher-risk buildings over 11 meters, forcing developers toward costly captive insurance structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Residential Real Estate Market |
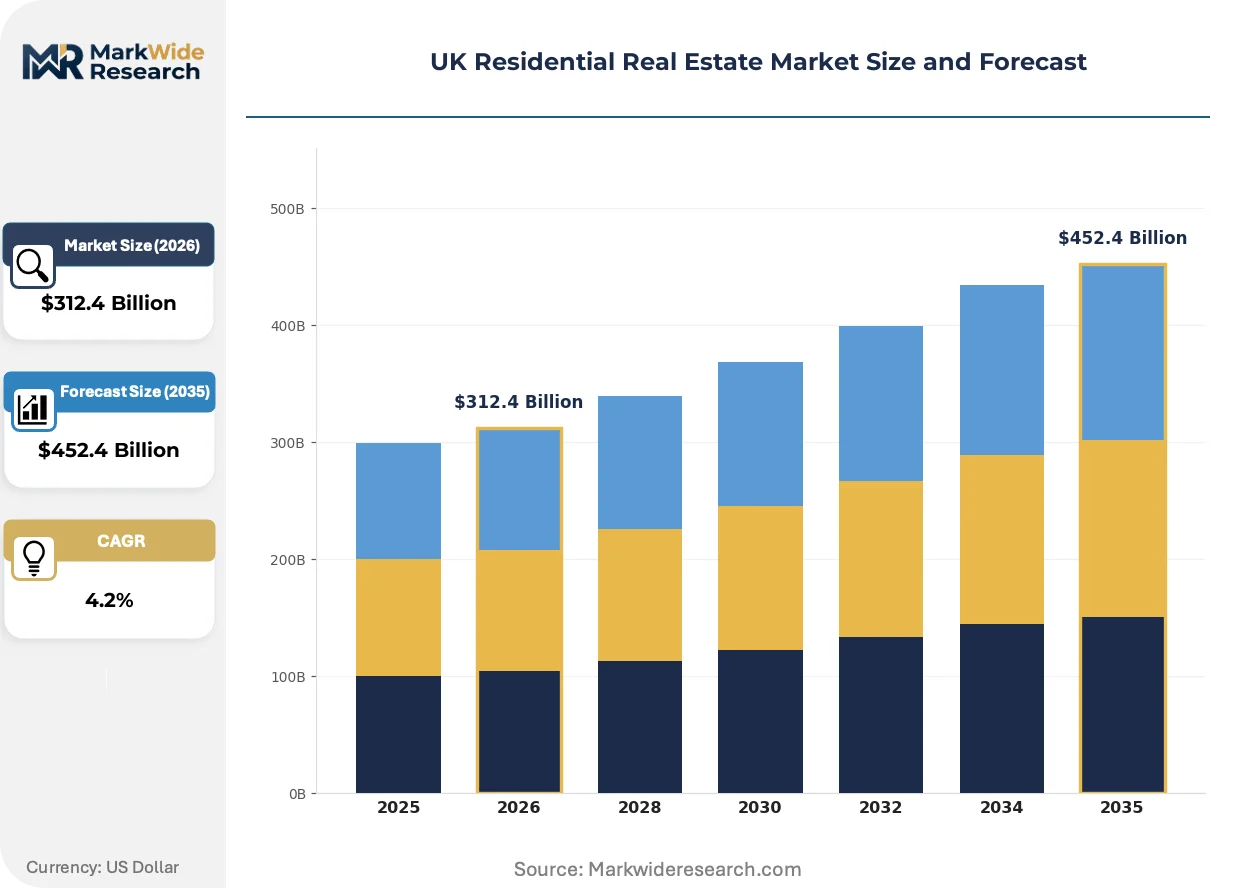
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $452.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Detached House, Semi-Detached House, Terraced House, Apartment Buyer Type: First-Time Buyers, Investors, Downsizers, Upsizers Financing Method: Mortgage, Cash Purchase, Shared Ownership, Help to Buy Market Segment: Luxury Homes, Family Homes, Starter Homes, Eco-Friendly Homes |
| Companies Covered | Barratt Developments, Taylor Wimpey, Persimmon, Vistry Group, Bellway, Grainger, Legal & General, Greystar, Lloyds Living, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Residential Real Estate Market Trends and Innovations
Digital twin technology and embodied carbon accounting are converging to reshape how residential assets are designed, financed, and transacted across the UK development pipeline.
Air-source heat pump systems are electrifying domestic hot water and space heating provision in new-build housing. Volume housebuilders are specifying monobloc units as standard across suburban family home product lines. This transition is compressing gas connection infrastructure requirements and enabling zero-carbon operational performance claims that command green mortgage rate discounts.
The Building Safety Regulator's gateway three compliance requirements are mandating detailed safety case submissions before occupation certificates issue. Developers must now demonstrate structural and fire safety evidence packages that satisfy independent scrutiny. Higher-risk residential buildings across London and Manchester are experiencing extended commissioning periods as safety case preparation consumes additional months.
First-time buyer cohorts are fragmenting across tenure pathways rather than converging on traditional mortgage acquisition. Shared ownership and institutional rental products are capturing households who would have pursued full ownership a decade prior. This behavioral pivot concentrates most acutely in Greater London where deposit requirements exceed eight times median annual earnings for standard new-build stock.
UK Residential Real Estate Market Segmentation
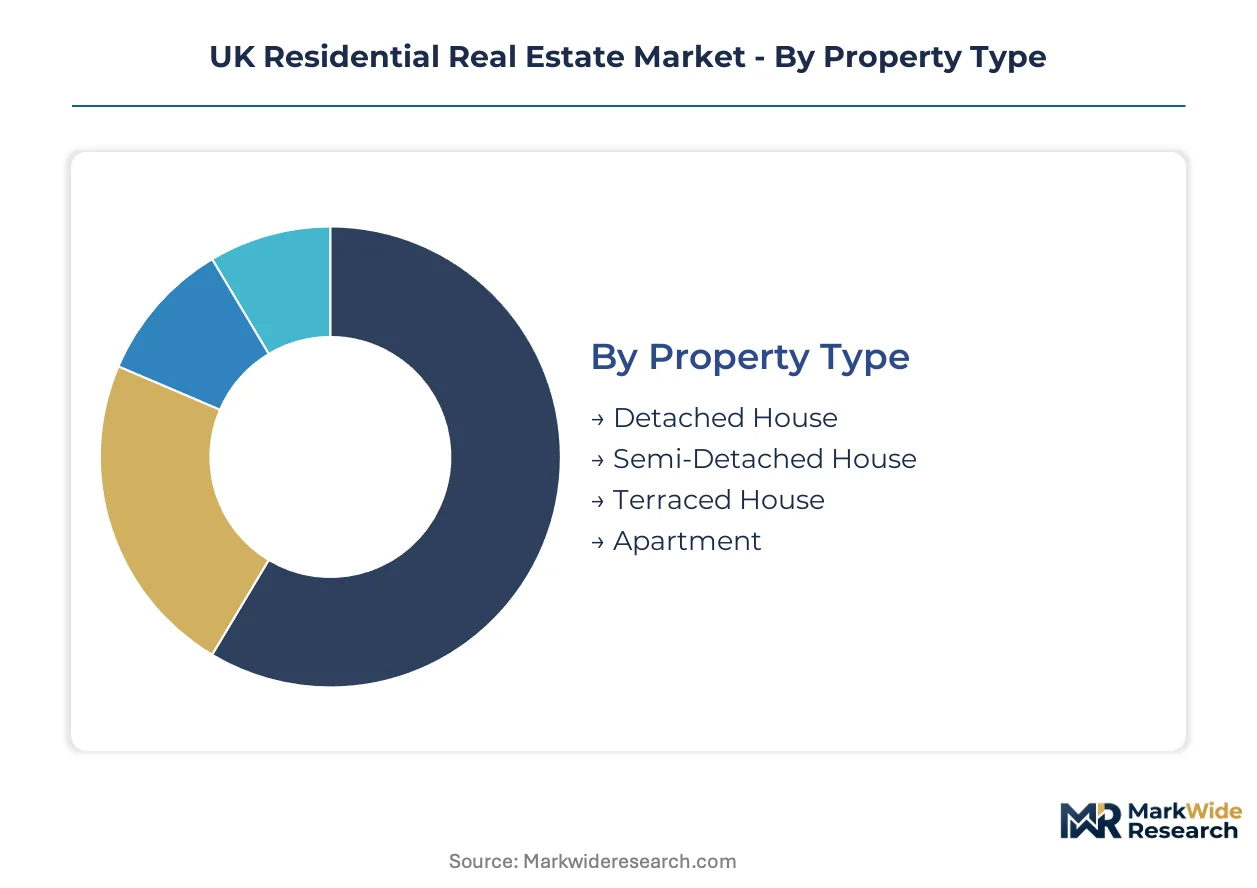
Segmentation in UK residential real estate reveals how capital deployment, tenure preferences, and regulatory compliance intersect across distinct buyer cohorts and property typologies. Understanding these divisions exposes where development returns concentrate and where policy interventions reshape transaction pathways.
Property Type:
Capital intensity escalates sharply with land consumption per unit, creating divergent risk-return profiles across the built-form spectrum.
- Detached House:Standalone dwellings on individual plots command the highest land absorption per unit. Demand concentrates in Surrey, Buckinghamshire, and Hertfordshire commuter belts where remote-work permanence sustains premium absorption despite transport costs.
- Apartment:Vertical density maximizes land value extraction in constrained urban cores. Greater London and Manchester city centers absorb the bulk of institutional build-to-rent deployment, though Building Safety Act compliance costs disproportionately burden towers over 11 meters.
- Semi-Detached House:Paired dwellings balance privacy with plot efficiency. Suburban corridors around Birmingham and Bristol favor this typology for family relocation from apartment stock.
- Terraced House:Continuous street frontages optimize land use in historic urban fabric. Northern England and Midlands regeneration zones repurpose Victorian stock for first-time buyer entry points.
Most installed capacity flows through terraced house and semi-detached segments. Expansion is steepest in apartment typologies as urban density policies harden.
Buyer Type:
Financing access and life-stage positioning determine which cohorts drive marginal transaction velocity in each price bracket.
- First-Time Buyers:Deposit-constrained households increasingly bypass traditional mortgage pathways. Shared ownership and institutional rental products capture this cohort in Greater London where affordability gaps exceed eight times median earnings.
- Investors:Yield-focused purchasers target rental income streams. Build-to-rent institutional capital and individual buy-to-let landlords concentrate in university cities and transport-adjacent sub-markets.
- Downsizers:Empty-nester households release equity from family homes. Coastal retirement clusters and low-maintenance apartment developments in Brighton and Bournemouth absorb this flow.
- Upsizers:Growing families trade space for location. Commuter zone detached stock in Buckinghamshire and Essex captures this mobility as remote-work hybridity extends acceptable journey times.
First-time buyers and investors together dominate transaction volumes. Upsizer activity is climbing fastest as delayed family formation resolves.
Financing Method:
Tenure structure choice increasingly decouples from income qualification alone, reflecting policy design and capital market evolution.
- Mortgage:Traditional amortizing debt remains volume-dominant but faces Bank of England base rate sensitivity. Stress-testing thresholds exclude median-income households from standard new-build stock in high-value sub-markets.
- Shared Ownership:Staircasing structures reduce deposit barriers through partial equity acquisition. Housing associations and institutional developers expand this channel in London and South East corridors.
- Cash Purchase:Unleveraged acquisitions concentrate in equity-rich downsizers and international purchasers. Prime central London and country house markets exhibit highest cash prevalence.
- Help to Buy:Government equity loan scheme targets new-build first-time buyers. Winding down of the program shifts volume toward shared ownership alternatives.
Mortgage-dependent purchases still channel most transaction value. Shared ownership is gaining share fastest as policy support pivots.
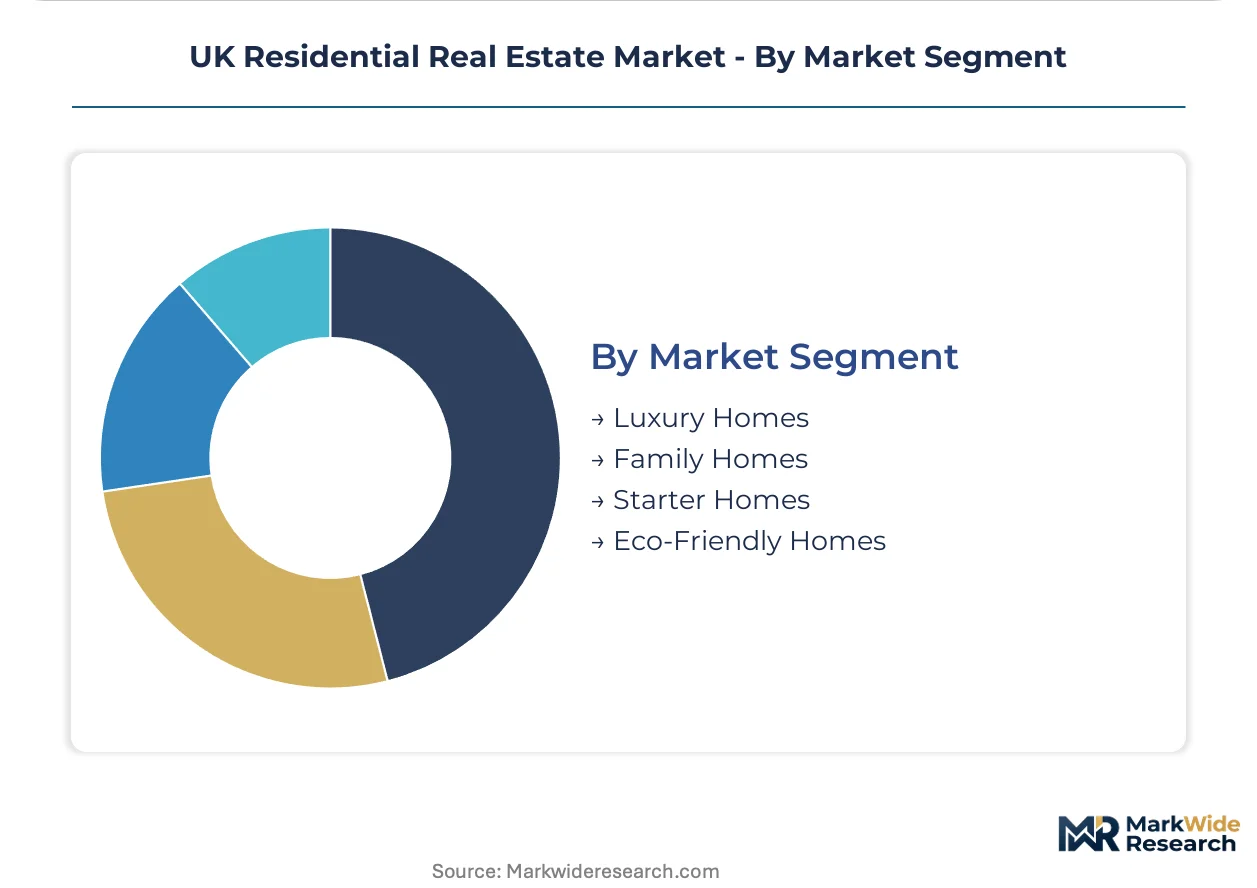
Market Segment:
Price positioning and specification tier create distinct margin pools with divergent exposure to energy regulation and safety compliance.
- Family Homes:Three-to-four-bedroom stock dominates suburban development pipelines. Barratt and Persimmon volume programs concentrate here, with standardized house types compressing construction cycles.
- Luxury Homes:Premium specification assets command scarcity pricing. Super-prime London postcodes and Cotswolds estate markets exhibit lowest price elasticity to interest rate movements.
- Starter Homes:Entry-price new-build targets first-time buyer deposit constraints. Part L thermal efficiency mandates elevate base cost structures, squeezing developer margins.
- Eco-Friendly Homes:Net-zero operational performance claims command green mortgage rate discounts. Air-source heat pump and triple-glazing specifications differentiate this segment as Future Homes Standard tightens.
Family homes absorb the greatest development capital deployment. Eco-friendly specifications are expanding most quickly as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England commands substantially greater development volume than Scotland or Wales, yet regulatory divergence across the three jurisdictions creates distinct compliance cost structures for cross-border operators.
Greater London
Employment density and transport infrastructure sustain premium absorption for apartment stock, with build-to-rent institutional capital concentrating in 500-plus unit urban clusters. The Building Safety Regulator enforces gateway compliance for towers exceeding 11 meters, extending commissioning timelines. Canary Wharf and Stratford City anchor the highest-density residential development pipelines.
South East England
Commuter zone demand from remote-work hybridity sustains detached and semi-detached family home absorption across Surrey and Buckinghamshire. HM Treasury stamp duty threshold adjustments trigger velocity surges in sub-£425,000 brackets. Milton Keynes and Reading corridor developments capture upsizer mobility from London apartment stock.
Midlands
Regeneration zones in Birmingham and Nottingham repurpose Victorian terraced fabric for first-time buyer entry points. Local planning authority capacity constraints under the National Planning Policy Framework extend determination timelines to 18-24 months. Birmingham city center apartment towers absorb institutional rental deployment outside London pricing tiers.
North England
Land scarcity constraints elevate per-unit development costs less severely than in southern markets, enabling volume housebuilder margin preservation. The Future Homes Standard creates retrofit demand targeting pre-1919 solid-wall stock across Manchester and Leeds. Salford Quays and Liverpool Waters anchor waterfront residential renewal clusters.
Scotland
Devolved planning and building standards create regulatory divergence from England and Wales compliance frameworks. Edinburgh and Glasgow city centers concentrate apartment development as urban density policies restrict greenfield expansion. Scottish Government energy efficiency programs accelerate heat pump deployment mandates ahead of Westminster timelines.
UK Residential Real Estate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across development, rental management, and land assembly functions. The vendor base clusters around three strategic archetypes: national volume housebuilders with standardized product lines, institutional build-to-rent operators with patient capital structures, and housing associations delivering affordable tenure pathways. Consolidation pressure intensifies as land scarcity elevates acquisition costs and regulatory compliance demands scale-driven administrative capacity. Geographic expansion and portfolio diversification toward rental income streams represent dominant competitive moves.
Among national volume housebuilders, Barratt Developments and Persimmon occupy positions defined by land bank scale and construction cycle compression through standardized house types. Taylor Wimpey represents the tier balancing regional diversification with suburban family home concentration. Within institutional rental, Greystar anchors the build-to-rent segment with purpose-designed multifamily assets. These named entities exemplify how capital deployment strategies segment across tenure models rather than converging on single pathways.
| Leading Market Players |
|---|
| Barratt Developments |
| Taylor Wimpey |
| Persimmon |
| Vistry Group |
| Bellway |
| Grainger |
| Legal & General |
| Greystar |
| Lloyds Living |
| Others |
Pricing and Supply Chain Analysis
Premium-mid-economy pricing differentiation between luxury eco-friendly homes and standard family housing manifests in both construction cost structures and supplier tiering across the UK development pipeline. Energy performance certificate tiers and net-zero retrofit specifications command material premiums that ripple through procurement decisions for air-source heat pumps and triple-glazing assemblies.
Pricing Analysis
Capacity additions in modular fabrication facilities are reshaping price floors for standardized house types across England and Wales. Project-based transactional pricing dominates new-build development, with price differentiation driven by energy efficiency certification tier and geographic delivery cost to constrained greenbelt-adjacent sites. Cost compression in starter home segments is intensifying because Part L thermal efficiency mandates elevate base specifications. First-time buyers exhibit highest price sensitivity, while cash-rich downsizers in prime central London show lowest elasticity to interest rate movements.
Supply Chain Analysis
Direct-to-developer channels handle volume housebuilder procurement for timber frame and structural steel inputs. Supply concentrates in UK domestic production for load-bearing masonry, with Baltic region timber and Chinese manufactured glazing systems feeding component dependencies. Single-source vulnerability around structural steel pricing from energy-intensive manufacturing creates exposure to energy cost swings. Distribution runs through regional builder merchant networks that aggregate materials for site delivery across suburban development corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in eco-friendly specification tiers where Future Homes Standard compliance commands green mortgage rate discounts and construction cost premiums simultaneously.
For Market Incumbents: Anchor land bank positions in Greater London commuter zones where stamp duty threshold adjustments trigger demand velocity surges. Defensive consolidation through backward integration into modular fabrication capacity mitigates construction input volatility from Baltic supply disruptions. Building Safety Regulator gateway compliance costs threaten smaller competitors lacking scale-driven administrative capacity. For New Entrants and Emerging Players: Digital twin technology for embodied carbon accounting offers a technology-first wedge into the net-zero retrofit ecosystem targeting pre-1919 solid-wall stock across Northern England. White-space targets include shared ownership channel expansion in high-value sub-markets where deposit barriers exclude median-income households from standard mortgage pathways. Housing association partnerships provide the most penetrable go-to-market angle for staircasing-light product structures. For Investors and Strategic Acquirers: Consolidation pressure builds where Building Safety Act compliance demands scale-driven administrative capacity that mid-tier developers cannot sustain. Long-term viability favors institutional build-to-rent operators with patient capital structures capturing tenure pattern shifts away from traditional ownership. Acquisition target archetypes include regional volume housebuilders with standardized product lines and underutilized land banks. The signal to watch is Bank of England base rate stabilization restoring first-time buyer mortgage access versus permanent tenure pattern displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Scale-Up | Off-site manufacturing compresses construction cycles from 24 weeks to 12 weeks for Barratt and Persimmon standardized house types. |
| Net-Zero Retrofit Ecosystem Entry | Whole-house retrofit providers target pre-1919 solid-wall stock across Manchester and Leeds under Future Homes Standard tailwinds. |
| Shared Ownership Channel Expansion | Housing associations pioneer staircasing-light structures reducing deposit barriers in London sub-markets exceeding eight times median earnings. |
| Build-to-Rent Portfolio Buildout | Greystar and Legal & General deploy patient capital into 500-plus unit urban clusters capturing institutional rental demand. |
| Land Bank Strategic Acquisition | Greenbelt protection around Birmingham and Bristol constrains developable supply, elevating per-plot acquisition premiums structurally. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from development directors at national volume housebuilders, land acquisition managers, local planning authority officers, building control surveyors, and institutional rental portfolio managers. Secondary validation drew from HM Treasury policy releases, Bank of England base rate decision records, Building Safety Regulator gateway guidance, National Planning Policy Framework density targets, and NHBC warranty underwriting data. Bottom-up segment sizing triangulated against top-down market value estimates across the analysis window.
Segment-weighting approaches modeled property type, buyer cohort, financing method, and market tier dimensions throughout the forecast period. CAGRs derived from regression analysis against macroeconomic drivers including employment density, transport infrastructure investment, and regulatory compliance cost trajectories. Industry-specific inputs encompassed land scarcity indices for greenbelt-protected corridors and construction input price volatility from Baltic timber and structural steel markets.
The model holds under stable interest rate and regulatory implementation trajectories; deviation in Bank of England base rate movements or Building Safety Regulator enforcement intensity would shift transaction velocity and development margin assumptions. Forecasts reflect documented assumptions regarding tenure pattern evolution and shared ownership channel penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market