
 Urban Design Market | 2026-2036
Urban Design Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Design Market Insights
EPA stormwater management rules is broadening the cost-of-entry calculus for firms bidding on federally funded infrastructure. Gensler leverages its coast-to-coast studio network to anchor large-scale mixed-use commissions. Sweco competes through integrated engineering-design bundling across Northern European public tenders. Sasaki Associates specializes in landscape urbanism frameworks that navigate complex watershed remediation requirements.
Urban design encompasses the multidisciplinary planning and aesthetic organization of built environments, integrating land-use zoning, transportation networks, green infrastructure systems, and public realm geometry to shape human settlement patterns. The discipline employs geospatial analytics, parametric modeling, and bioclimatic simulations to optimize density, mobility efficiency, and ecological performance across metropolitan scales. Public spaces and transit-oriented developments command the deepest municipal budget allocations, reflecting persistent infrastructure backlogs in legacy cities. Sustainable planning and smart city integration represent the fastest-expanding design approach categories, as climate adaptation mandates harden procurement criteria across OECD jurisdictions. Tactical urbanism occupies a niche but growing margin pool, serving cash-constrained municipalities seeking phased implementation pathways.
FERC coordinates with EPA on energy corridor siting that shapes brownfield redevelopment feasibility, while EU Green Deal building performance standards filter through EMA-aligned national codes to constrain material specifications and carbon intensity thresholds. ISO 37120 sustainable city indicators and the EU AI Act's public infrastructure risk classifications are layering new compliance dimensions onto project deliverables. Stakeholders must monitor which regulatory frameworks achieve procurement lock-in first, as divergent standards between North American and European jurisdictions threaten to fragment design methodology exportability.
Market Dynamics
Climate adaptation mandates are compressing design timelines while fragmenting procurement criteria across jurisdictions. Municipal buyers now bundle resilience specifications with digital infrastructure requirements, forcing firms to retool capability stacks mid-project.
Growth Catalysts
- EU Green Deal building performance standards:These binding thresholds for carbon intensity and material specifications are creating mandatory upgrade cycles across existing municipal portfolios.
- Transit-oriented development concentration:Southeast Asian municipal agencies are channeling federal infrastructure grants into dense mixed-use corridors around mass transit nodes.
- Parametric modeling adoption:Bioclimatic simulation tools now sit at the core of competitive bidding for watershed remediation and stormwater management contracts.
Market Restraints
- Specialized talent scarcity:The shallow pool of practitioners combining geospatial analytics with landscape urbanism training constrains project throughput.
- Input cost volatility:Low-carbon concrete and certified timber specifications face supply bottlenecks from limited certified producers in Northern Europe.
- Regulatory fragmentation:Divergent ISO 37120 implementations across OECD jurisdictions force redundant compliance documentation for multi-national firms.
Strategic Opportunities
- India smart city mission corridors:Federal infrastructure grants in these designated zones are accelerating project pipelines with pre-cleared environmental clearances.
- Digital twin convergence:Integration of real-time sensor networks with parametric design platforms opens predictive maintenance revenue streams.
- Tactical urbanism channel expansion:Cash-constrained municipalities are adopting phased implementation pathways as an alternative to capital-intensive full-build delivery.
Industry Challenges
- Bioclimatic simulation expertise gaps:Firms struggle to staff projects requiring simultaneous fluency in parametric tools and watershed ecology.
- Legacy CAD system integration:Municipal clients operate incompatible software stacks that complicate data handoffs and revision control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Design Market |
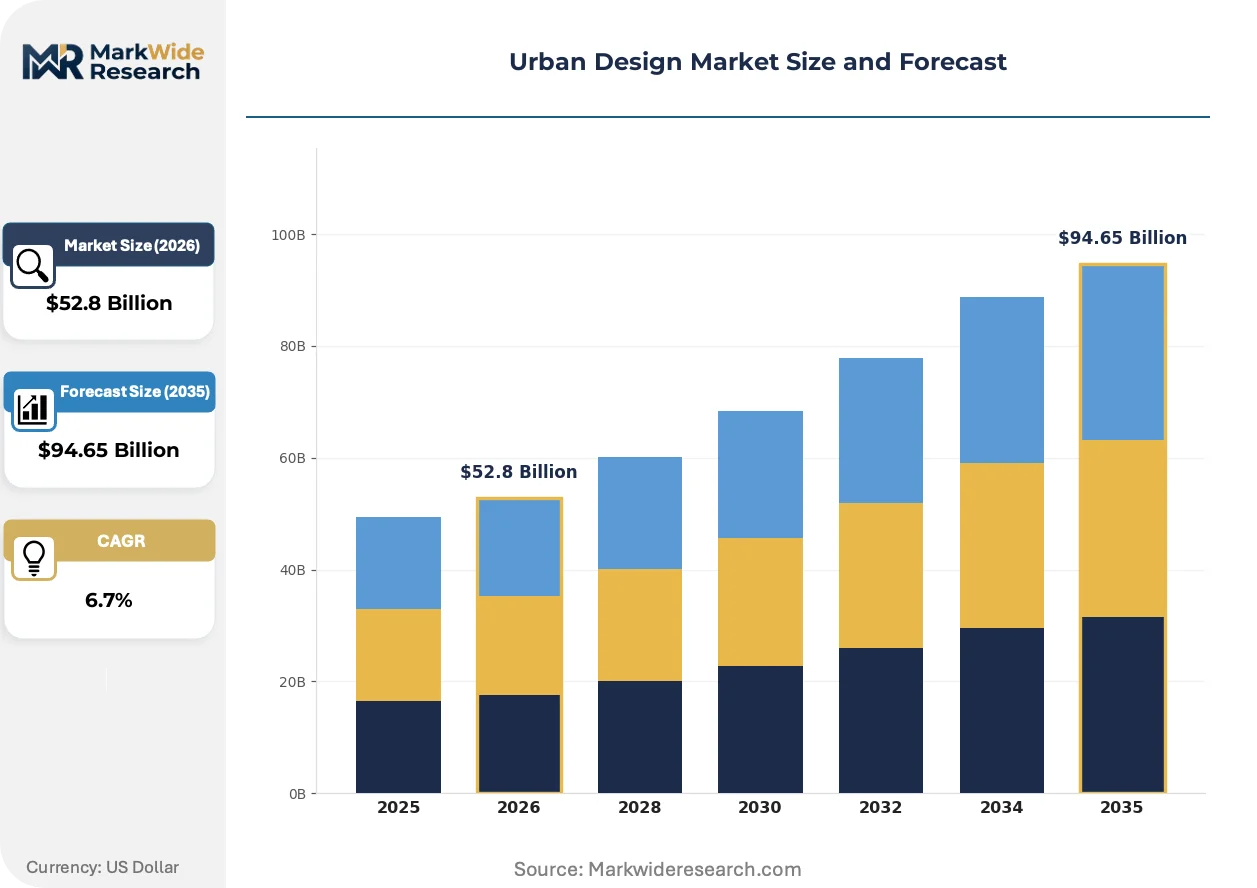
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $94.65 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Public Spaces, Residential Complexes, Commercial Districts, Transit-Oriented Developments, Mixed-Use Zones Design Approach: Smart City Integration, Sustainable Planning, Historical Preservation, Landscape Urbanism, Tactical Urbanism Stakeholder Type: Municipal Agencies, Urban Planners, Community Organizations, Private Developers, Real Estate Consultants Implementation Scale: Neighborhood Level, Citywide Programs, Waterfront Revitalization, Infrastructure Upgrades, Brownfield Redevelopment |
| Companies Covered | SWA, Sweco, Gensler, RMJM, West8, Sasaki Associates, Foster + Partners, Atkins, HOK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Design Market Trends and Innovations
Generative design workflows are compressing the schematic phase while expanding the range of formally complex geometries that clients now expect as standard deliverables.
Machine learning-powered generative design platforms are decentralizing the optimization of density and mobility efficiency calculations that previously required centralized supercomputing resources. Mid-size municipal agencies in the Netherlands and Denmark are adopting these tools at procurement scale. This capability diffusion is decentralizing competitive advantage away from firms with captive computational infrastructure toward those with algorithmic fluency.
EPA stormwater management rules are tightening post-construction runoff standards for federally funded infrastructure, forcing design firms to embed green infrastructure earlier in schematic phases. Engineering-design bundling now dominates Northern European public tenders as a direct response. Firms without integrated hydrology capabilities are exiting this procurement channel entirely.
Performance-based specifications are displacing prescriptive design standards in municipal procurement documents. Dutch and Singaporean agencies now contract for outcomes—flood resilience metrics, mobility efficiency targets—rather than dimensional compliance. This behavioral pivot rewards firms with simulation-validated design histories and penalizes those reliant on pattern-book repetition.
Urban Design Market Segmentation
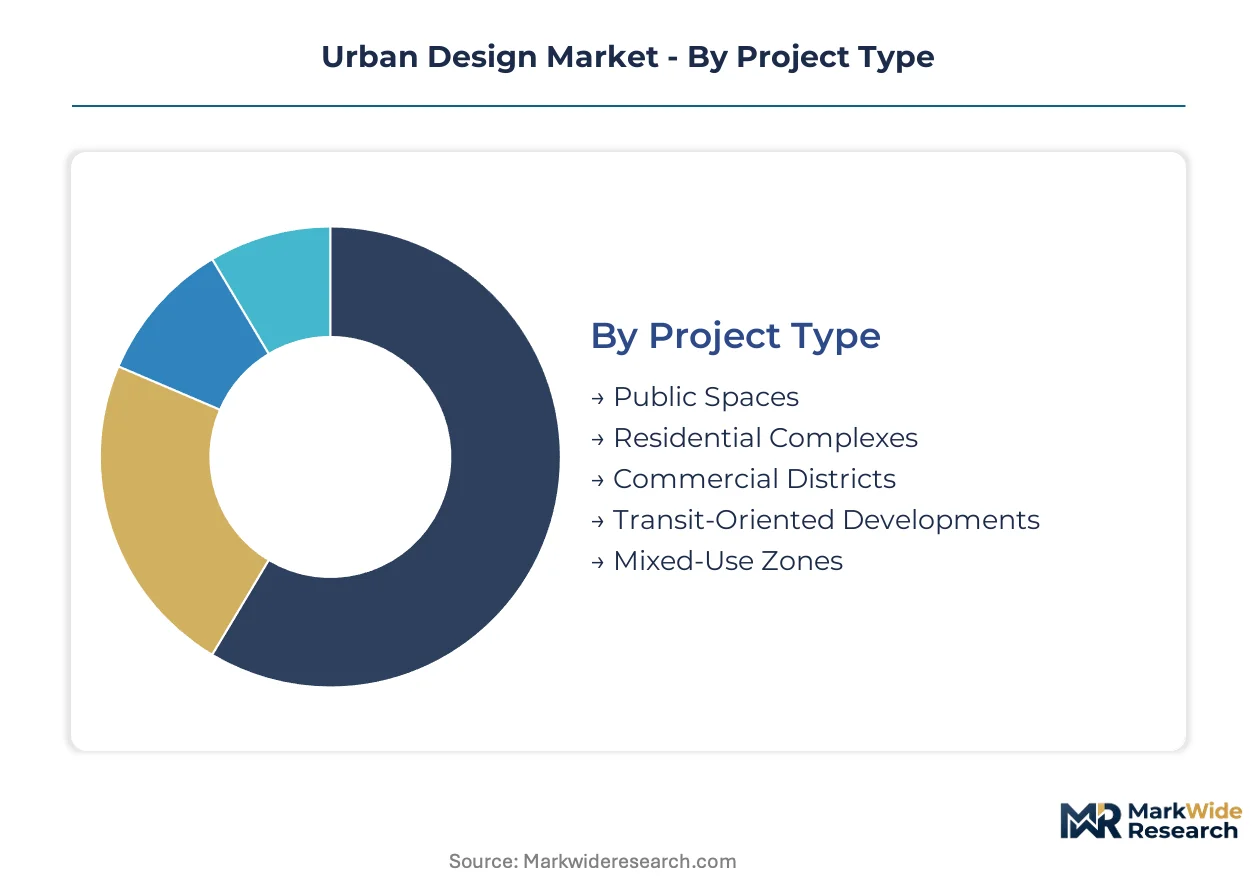
Urban design procurement fragments across project typology, methodological approach, and governance structure. Each segmentation axis reveals distinct capability requirements and margin profiles that shape firm positioning strategies.
Project Type:
Scale and funding mechanisms differentiate these categories, with public realm investments commanding the largest municipal capital allocations.
- Public Spaces:Parks, plazas, and streetscapes absorb the deepest municipal budget pools, driven by legacy infrastructure backlogs in legacy cities. EPA stormwater management rules now mandate green infrastructure integration earlier in schematic phases, compressing design timelines.
- Transit-Oriented Developments:Dense mixed-use corridors around mass transit nodes concentrate federal infrastructure grants in Southeast Asian municipal agencies. Singapore and Bangkok agencies bundle resilience specifications with digital infrastructure requirements, forcing firms to retool capability stacks mid-project.
- Residential Complexes:EU Green Deal building performance standards filter through EMA-aligned national codes to constrain material specifications and carbon intensity thresholds for housing developments.
- Commercial Districts:Performance-based specifications now displace prescriptive standards, with Dutch agencies contracting for flood resilience metrics rather than dimensional compliance.
- Mixed-Use Zones:Gensler leverages coast-to-coast studio networks to anchor large-scale commissions in this category, where engineering-design bundling dominates procurement.
Public spaces lead on scale; transit-oriented developments lead on momentum.
Design Approach:
Methodological differentiation increasingly determines competitive access, as climate adaptation mandates harden procurement criteria across OECD jurisdictions.
- Sustainable Planning:Bioclimatic simulation tools sit at the core of competitive bidding for watershed remediation contracts. Firms without integrated hydrology capabilities are exiting Northern European public tenders entirely.
- Smart City Integration:Digital twin convergence opens predictive maintenance revenue streams through real-time sensor network integration with parametric design platforms.
- Landscape Urbanism:Sasaki Associates specializes in frameworks navigating complex watershed remediation requirements, where machine learning-powered generative design platforms now decentralize optimization calculations.
- Tactical Urbanism:Cash-constrained municipalities adopt phased implementation pathways as alternatives to capital-intensive full-build delivery, creating niche margin expansion.
- Historical Preservation:ISO 37120 sustainable city indicators and EU AI Act risk classifications layer compliance dimensions onto heritage-sensitive project deliverables.
Sustainable planning dominates current procurement volume; smart city integration shows the steepest expansion trajectory.
Stakeholder Type:
Buyer sophistication and procurement authority vary sharply across these actors, with public-sector mandates driving compliance-heavy engagements.
- Municipal Agencies:Southeast Asian agencies scale transit-oriented developments as primary growth buyers, channeling federal infrastructure grants into dense corridors.
- Private Developers:India's smart city mission corridors accelerate project pipelines with pre-cleared environmental clearances, attracting speculative capital.
- Urban Planners:Specialized talent scarcity constrains throughput—practitioners combining geospatial analytics with landscape urbanism training remain shallow.
- Community Organizations:Grassroots advocacy increasingly shapes preliminary design charrettes, particularly in brownfield redevelopment feasibility studies.
- Real Estate Consultants:Advisory roles expand as FERC coordinates with EPA on energy corridor siting that shapes redevelopment economics.
Municipal agencies anchor contract value; private developers are gaining share fastest in emerging corridors.
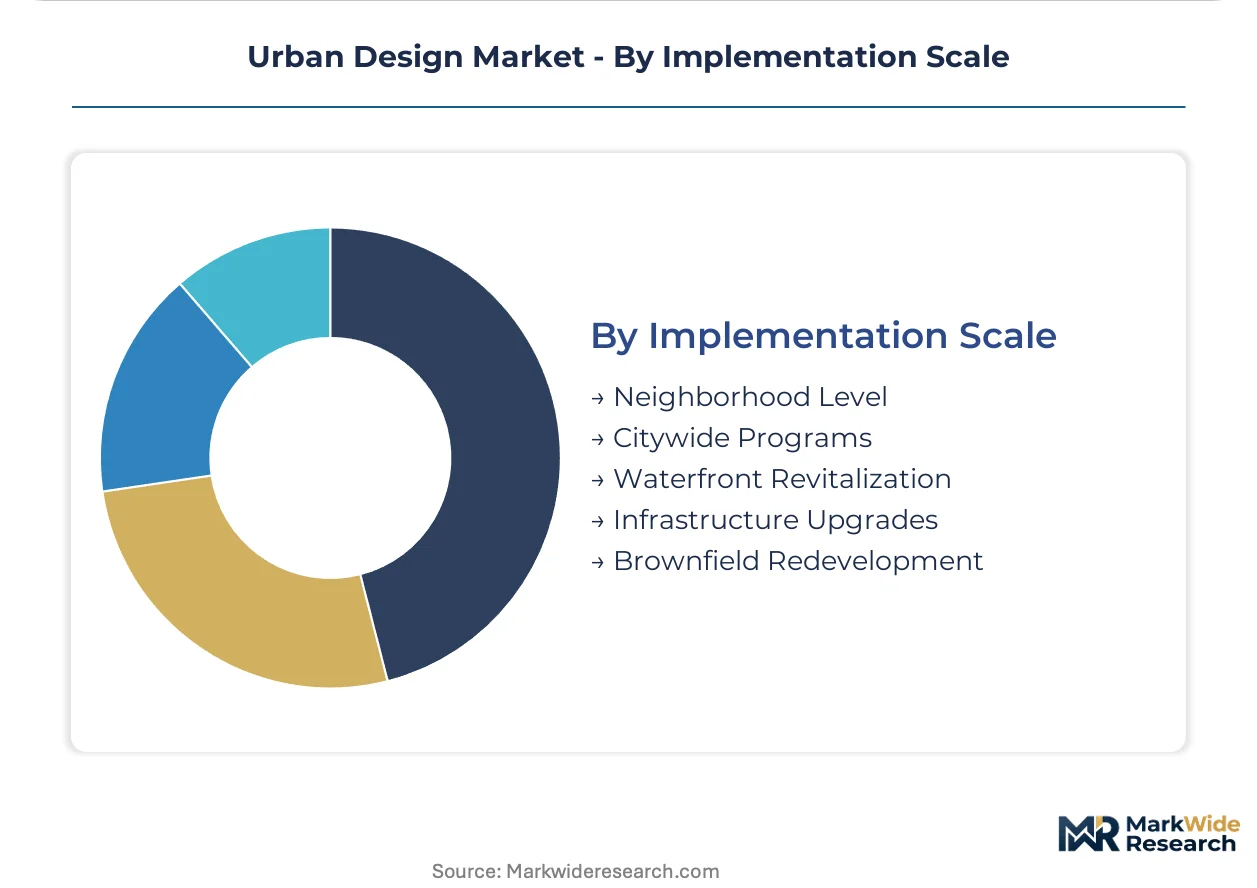
Implementation Scale:
Geographic scope determines regulatory complexity and stakeholder coordination intensity, with waterfront and brownfield projects facing layered approval requirements.
- Citywide Programs:Comprehensive master planning engagements require simultaneous fluency in parametric tools and watershed ecology that firms struggle to staff.
- Waterfront Revitalization:EPA stormwater rules tighten post-construction runoff standards, forcing earlier green infrastructure embedding in schematic phases.
- Brownfield Redevelopment:FERC coordination with EPA on energy corridor siting directly shapes feasibility calculations for contaminated site conversion.
- Neighborhood Level:Tactical urbanism pilots serve cash-constrained municipalities seeking phased implementation pathways with lower capital barriers.
- Infrastructure Upgrades:Legacy CAD system integration challenges complicate data handoffs and revision control across municipal software stacks.
Citywide programs capture the largest fee pools; waterfront revitalization climbs the fastest on climate adaptation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Practitioners combining geospatial analytics with landscape urbanism training concentrate in specific metropolitan clusters where federal infrastructure grants and climate adaptation mandates converge. These talent pools anchor procurement gravity across distinct national regulatory environments.
United States
EPA stormwater management rules tighten post-construction runoff standards for federally funded infrastructure. FERC coordinates with EPA on energy corridor siting that shapes brownfield redevelopment feasibility in legacy industrial cities. Gensler leverages its coast-to-coast studio network to anchor large-scale mixed-use commissions in coastal metropolitan areas.
Netherlands
Machine learning-powered generative design platforms decentralize optimization calculations for density and mobility efficiency. Dutch agencies now contract for flood resilience outcomes rather than dimensional compliance through performance-based specifications. Mid-size municipal agencies in Randstad cities adopt these tools at procurement scale.
Singapore
Southeast Asian municipal agencies channel federal infrastructure grants into dense mixed-use corridors around mass transit nodes. Singapore agencies bundle resilience specifications with digital infrastructure requirements, forcing firms to retool capability stacks mid-project. The city-state's smart city mission corridors accelerate project pipelines with pre-cleared environmental clearances.
India
Federal infrastructure grants in designated smart city mission corridors accelerate project pipelines with pre-cleared environmental clearances. BIS-aligned building codes constrain material specifications for transit-oriented developments. Speculative capital concentrates in Maharashtra and Gujarat where municipal agencies scale dense mixed-use corridors around mass transit nodes.
Germany
EU Green Deal building performance standards filter through EMA-aligned national codes to constrain material specifications and carbon intensity thresholds. Engineering-design bundling dominates Northern European public tenders as a direct response to compliance complexity. Berlin-Brandenburg and North Rhine-Westphalia municipal agencies drive procurement volume for integrated hydrology capabilities.
Urban Design Market Competitive Landscape
The competitive structure tilts toward integrated engineering-design bundlers with captive computational infrastructure. Mid-size specialists and global multidisciplinary networks coexist in a tiered configuration where algorithmic fluency displaces captive supercomputing as the primary differentiator. Three archetypes dominate: coast-to-coast studio networks, Northern European integrated bundlers, and landscape urbanism specialists. Geographic expansion through studio acquisition and backward integration into parametric tool development represent the dominant competitive moves.
Within the integrated bundler tier, Sweco exemplifies the Northern European model of engineering-design convergence for public tenders. Gensler anchors the coast-to-coast studio network archetype with distributed presence across metropolitan markets. Sasaki Associates occupies a position within the landscape urbanism specialist tier, navigating complex watershed remediation requirements through bioclimatic simulation frameworks.
| Leading Market Players |
|---|
| SWA |
| Sweco |
| Gensler |
| RMJM |
| West8 |
| Sasaki Associates |
| Foster + Partners |
| Atkins |
| HOK |
| Others |
Pricing and Supply Chain Analysis
Machine learning-powered generative design platforms are compressing schematic-phase labor costs while simultaneously concentrating procurement power among firms with captive algorithmic infrastructure. This technology shift squeezes mid-tier practitioners unable to retool capability stacks mid-project, reshaping both fee structures and supplier consolidation dynamics across municipal and private buyer segments.
Pricing Analysis
Engineering-design bundling versus unbundled architectural services splits the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade, with EU Green Deal compliance and ISO 37120 indicator validation commanding top-tier premiums. Price differentiation hinges on bioclimatic simulation depth and digital twin integration maturity. Cost compression in the standard tier is intensifying because municipal buyers now mandate parametric tool fluency as baseline procurement criteria. Cash-constrained municipalities exhibit highest price sensitivity, while Singapore and Dutch agencies with federal infrastructure grant backing show lowest.
Supply Chain Analysis
Direct-to-municipal-agency channels handle hyperscale transit-oriented development demand in Southeast Asia, while intermediary consortiums dominate Northern European public tenders. Certified low-carbon concrete and engineered timber supply concentrates in Germany, Sweden, and Austria. Geospatial analytics software and parametric modeling platforms draw from US, Netherlands, and Singapore development clusters. Single-source vulnerability in certified timber specifications threatens project throughput where FSC and PEFC chain-of-custody documentation is mandatory. Distribution runs through integrated engineering-design bundlers in Northern Europe and coast-to-coast studio networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Urban Design Market functions as a stable compounder anchored by persistent infrastructure backlogs in legacy cities and hardening climate adaptation mandates across OECD jurisdictions. Municipal procurement volume renews predictably through regulatory upgrade cycles rather than discretionary capital allocation.
For Market Incumbents: Hedge against algorithmic capability diffusion by acquiring mid-size parametric tool developers before machine learning platforms fully decentralize competitive advantage. Sweco's integrated engineering-design bundling model in Northern Europe offers a template for defending procurement access as EPA stormwater rules and EU Green Deal standards harden compliance thresholds. Backward integration into bioclimatic simulation software development protects margin pools in watershed remediation contracts.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in tactical urbanism services opens white-space for algorithmic-fluent boutiques serving cash-constrained municipalities. India's smart city mission corridors with pre-cleared environmental clearances offer the most penetrable geography for speculative capital entry. Target neighborhood-level implementation scale where legacy CAD system integration challenges disadvantage incumbents. Lead with phased implementation pathway expertise as the go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for landscape urbanism specialists because shallow talent pools combining geospatial analytics with watershed ecology training constrain organic growth for standalone firms. The five-to-ten year viability window favors acquiring practitioners with simulation-validated design histories as performance-based specifications displace prescriptive standards. Target firms with demonstrated EU Green Deal compliance project portfolios. Watch for FERC-EPA coordination on energy corridor siting as the inflection signal for brownfield redevelopment feasibility premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Tool Development Acquisition | Captures algorithmic fluency as EPA stormwater rules compress design timelines. |
| Bioclimatic Simulation Capability Buildout | Secures competitive access to Dutch and Singaporean municipal procurement channels. |
| EU Green Deal Compliance Certification | Unlocks Northern European public tender participation as EMA-aligned codes harden. |
| Digital Twin Platform Integration | Opens predictive maintenance revenue streams through real-time sensor convergence. |
| Tactical Urbanism Service Line Launch | Captures niche margin expansion from cash-constrained municipalities seeking phased delivery. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down design firm capacity tracking forms the analytical core. Primary interviews with urban planning directors, municipal engineering leads, landscape architecture principals, and federal infrastructure grant administrators combined with secondary validation against EPA regulatory filings, EU Green Deal implementation databases, ISO 37120 indicator repositories, and smart city mission corridor project registries. This triangulation anchors volume estimates across transit-oriented development, public space, and watershed remediation segments.
Historical trendline analysis of federal infrastructure grant allocation patterns and municipal capital expenditure cycles informed the projection framework. Segmentation dimensions modeled include project typology, design approach methodology, implementation scale, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed procurement pipeline data. Forecast inputs incorporate bioclimatic simulation adoption rates and digital twin convergence milestones without year-specific anchoring.
Caveats apply where FERC-EPA coordination shifts on energy corridor siting or where EU AI Act public infrastructure risk classifications materially alter compliance cost structures. Forecasts reflect base-case assumptions around regulatory implementation pacing and certified material supply availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Ireland Facility Management Market
Real Estate
Saudi Arabia Residential Real Estate Market
Real Estate
Qatar Luxury Residential Real Estate Market
Real Estate
Denmark Facility Management Market
Real Estate
Relocation Management Service Market
Real Estate
Norway Facility Management Market
Real Estate
Japan Condominiums and Apartments Market
Real Estate
Europe Real Estate Brokerage Market
Real Estate
North America Hard Facility Management Market
Real Estate
India Residential Construction Market
Real Estate
Serbia Facility Management Market
Real Estate
Sweden Luxury Residential Real Estate Market
Real Estate
Property Management Software Market
Real Estate
Europe Self Storage Market
Real Estate
Malaysia Facility Management Market
Real Estate
Europe Luxury Residential Real Estate Market