
 India Residential Real Estate Market | 2026-2036
India Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
India Residential Real Estate Market Foresight
Aftermarket property management revenue is tilting toward developer-retained service models as builders seek recurring income beyond unit sales. DLF Ltd anchors this shift through captive facility management arms across its NCR portfolio. Godrej Properties differentiates by embedding smart-home infrastructure during construction, locking in long-term service contracts. Sobha Ltd sustains premium positioning through backward integration into interior fit-outs and glazing manufacturing.
India residential real estate encompasses finished dwelling units delivered through reinforced concrete frame construction, typically spanning 450–4,500 square feet across mid-rise and high-rise configurations, designed for permanent habitation or rental yield. The segment serves household shelter needs while functioning as the primary wealth-accumulation vehicle for Indian families. Apartments dominate volume in Mumbai, Bengaluru, and Hyderabad where land scarcity forces vertical development and FSI norms constrain horizontal expansion. The affordable and mid-range price tiers absorb the bulk of first-time buyer flows, while luxury inventory concentrates in gated enclaves along peripheral expressways where land assembly costs justify premium positioning.
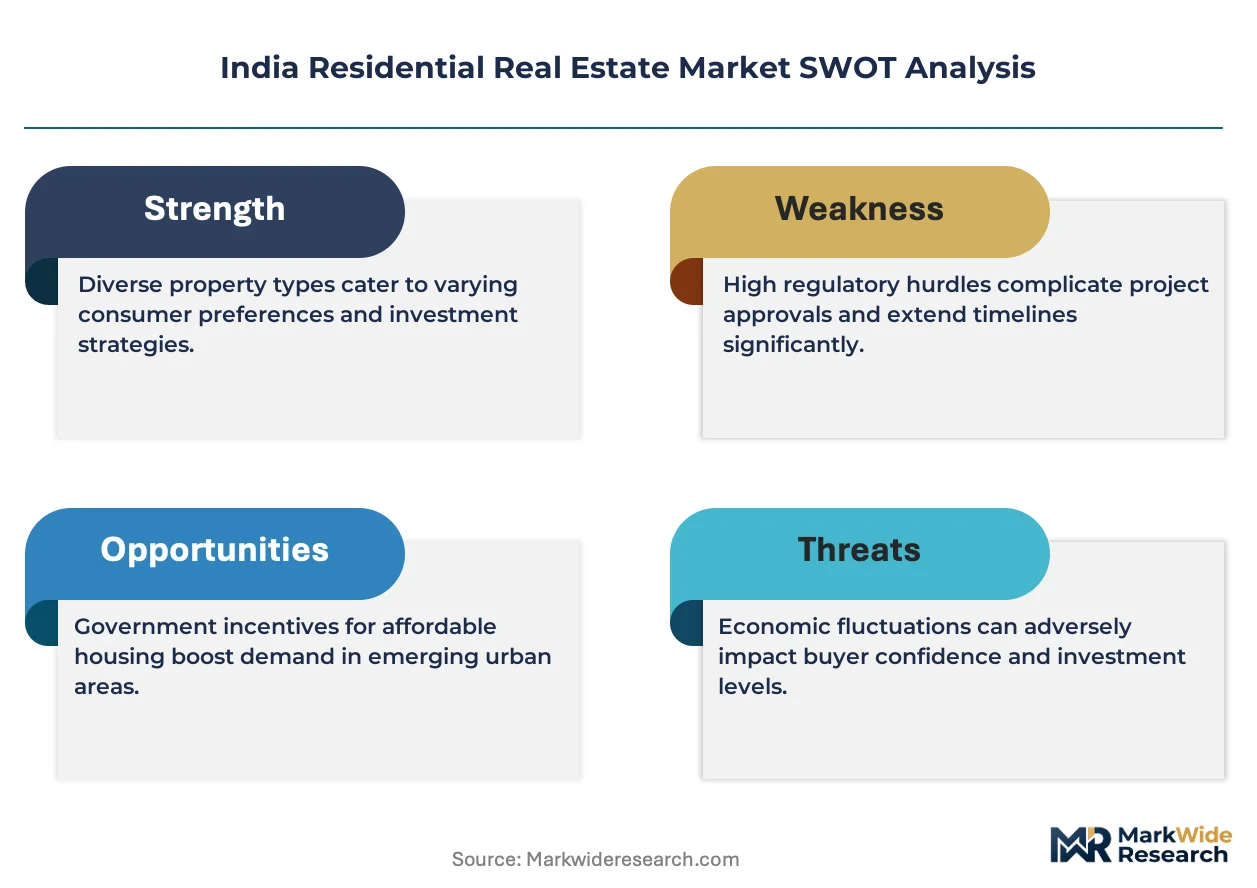
RBI monetary policy, RERA registration mandates, and state-level stamp-duty adjustments collectively govern transaction velocity and developer liquidity across Indian markets. RERA's escrow requirements have forced capital discipline, weeding out speculative launches and concentrating supply among compliant developers with balance-sheet depth. Stakeholders must track how state-level rental-housing policies and municipal development plan revisions redistribute buildable rights across suburban nodes.
Market Dynamics
The RBI's repo rate transmission mechanism now dominates developer cash-flow planning, compressing project launch cycles and forcing inventory turnover acceleration across Maharashtra, Karnataka, and Telangana.
Growth Catalysts
- PLI scheme for construction materials:Domestic manufacturing incentives for cement and steel are reducing input cost volatility for developers in Gujarat and Rajasthan.
- Mumbai-Pune corridor infrastructure density:Metro rail expansion and expressway connectivity are validating premium land banking strategies along this node.
- RERA escrow mandates:Buyer protection frameworks are restoring transaction confidence and channeling first-time purchaser flows toward registered developers.
Market Restraints
- Steel and cement price volatility:Input cost swings of 15-20% within single quarters are eroding project-level margins for mid-tier developers.
- Urban land assembly bottlenecks:Fragmented land ownership patterns in Bengaluru and Hyderabad are extending pre-construction timelines by 18-24 months.
- Affordable housing finance gaps:Formal credit access for informal-income borrowers remains constrained by collateral documentation requirements.
Strategic Opportunities
- Tier-2 city expansion:Indore, Kochi, and Chandigarh are exhibiting demand velocity previously concentrated in Mumbai and Delhi-NCR.
- Green building certification tailwinds:GRIHA and IGBC rating mandates for government leases are creating premium capture potential.
- Co-living format penetration:Young professional migration patterns are validating institutional rental models in Pune and Gurugram.
Industry Challenges
- Skilled construction labor scarcity:Migrant worker return patterns post-pandemic are destabilizing project timelines in NCR and Mumbai.
- Legacy project completion liability:Stalled developments from pre-RERA era are trapping developer capital and diluting brand equity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Residential Real Estate Market |
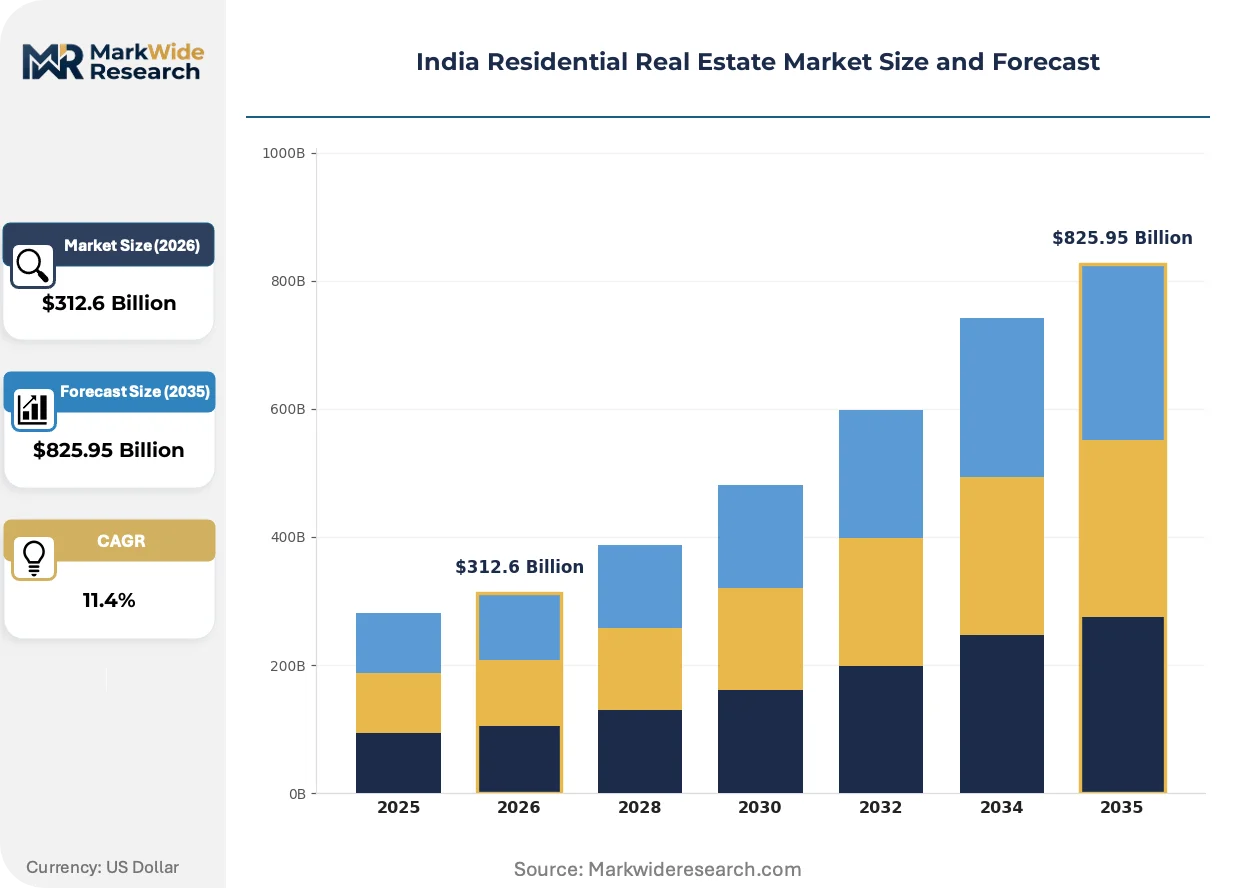
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Multi-Family Units, Apartments, Villas Price Tier: Luxury, Mid-Range, Affordable, Economical Financing Type: Home Loans, Cash Purchases, Leasing, Developer Financing Buyer Profile: First-Time Buyers, Investors, Retirees, Young Professionals |
| Companies Covered | Prestige Estates Projects, Sobha Ltd, DLF Ltd, L&T Realty, Brigade Enterprises, Macrotech Developers, Godrej Properties, Anant Raj, Oberoi Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Residential Real Estate Market Shifts & Advancements
Technology adoption is compressing traditional construction timelines while regulatory digitization and buyer behavior shifts are restructuring how residential inventory reaches end-users across Indian metropolitan markets.
Modular prefabrication is collapsing conventional cast-in-situ construction cycles. Leading developers in Mumbai and Hyderabad are deploying factory-produced bathroom pods and wall panels, cutting on-site labor dependency by half. This technology is collapsing the 36-month standard project duration toward 24-month execution windows.
RERA's digital compliance infrastructure is mandating real-time project disclosure and escrow transparency. Developers must now upload construction progress photographs and fund utilization statements on state portals quarterly. Maharashtra and Karnataka implementations are most stringent, forcing smaller developers toward joint-venture structures with balance-sheet-strong partners.
Institutional channel partners are capturing an expanding share of primary sales volume. Digital brokerage platforms and banking co-marketing arrangements are displacing traditional site-office walk-ins as the dominant lead source. This pattern is most pronounced in Bengaluru, where technology-sector buyers prefer virtual site tours and mortgage pre-approval integration before physical visits.
India Residential Real Estate Market Segmentation
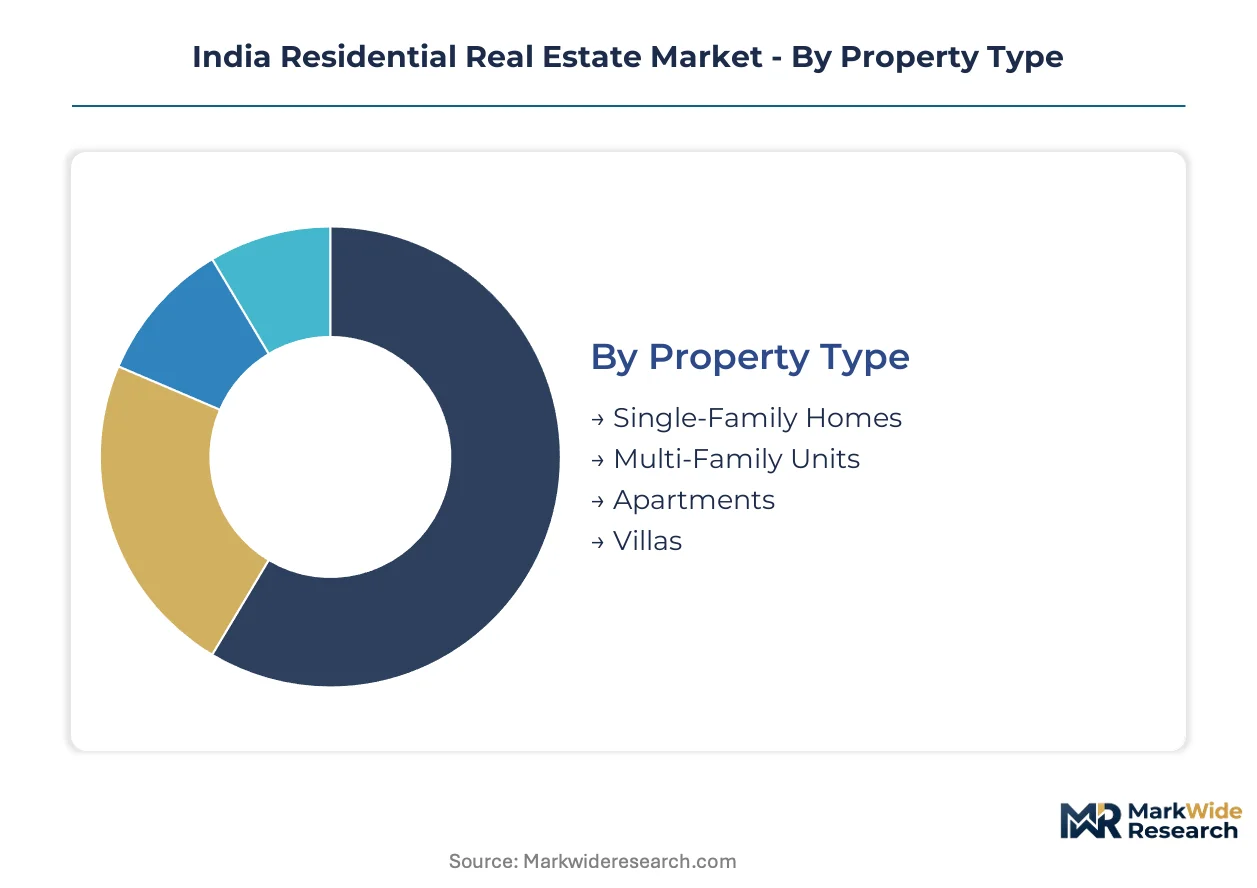
Segmentation in Indian residential real estate reveals how construction economics, buyer demographics, and financing access intersect to create distinct market pockets. Developers calibrate product mix across these dimensions to match local land costs with purchasing power.
Property Type:
Mature vertical formats dominate established metros while emerging configurations gain traction in peripheral nodes where land economics permit experimentation.
- Apartments:Reinforced concrete frame structures spanning 450–4,500 square feet with shared amenities and maintenance pools. Mumbai, Bengaluru, and Hyderabad absorb the bulk of apartment demand where FSI norms constrain horizontal expansion and metro connectivity validates vertical living premiums.
- Multi-Family Units:Low-rise configurations with 2–8 dwelling units per structure, typically 600–1,800 square feet per unit with limited common facilities. Pune and Gurugram exhibit accelerating uptake among young professional cohorts seeking space efficiency with lower maintenance burdens than high-rise alternatives.
- Single-Family Homes:Independent dwellings on owned land parcels, prevalent in Tier-2 cities and suburban fringes of Hyderabad and Chennai where plot availability sustains horizontal development.
- Villas:Gated enclave configurations with private land titles and bespoke construction, concentrated along peripheral expressways in the Mumbai-Pune corridor and Delhi-NCR where land assembly costs justify premium positioning.
Apartments handle the majority of throughput; multi-family units are expanding most quickly in share as young professionals prioritize location over space.
Price Tier:
Cost stratification follows construction input intensity and location premiums, with each tier serving distinct wealth-accumulation and shelter-need profiles.
- Affordable:Units priced within formal housing finance eligibility thresholds, typically sub-600 square feet configurations in peripheral locations. First-time buyer flows concentrate here, though collateral documentation requirements constrain informal-income borrower access.
- Mid-Range:800–1,500 square feet units in established suburbs with metro or expressway connectivity. This tier absorbs the bulk of salaried professional demand in Bengaluru and Hyderabad where technology-sector income growth supports mortgage eligibility.
- Luxury:Premium specifications with branded amenities, smart-home infrastructure, and gated security. Mumbai's south and central districts plus Gurugram's Golf Course Road corridor sustain this tier through concentrated high-net-worth household density.
- Economical:Basic finish specifications with minimal amenities, often in early-stage infrastructure locations. Demand concentrates in industrial satellite towns around Pune and Chennai where manufacturing workforce housing needs outpace formal supply.
Mid-range inventory dominates transaction velocity; affordable units are climbing the fastest on share as RERA compliance channels first-time buyers toward registered developers.
Financing Type:
Credit access patterns shape developer cash-flow structures and buyer entry thresholds across Indian markets.
- Home Loans:Institutional mortgage products from banks and housing finance companies, with eligibility tied to formal income documentation and CIBIL scores. RBI repo rate transmission directly affects affordability, compressing or expanding eligible buyer pools quarterly.
- Cash Purchases:Full upfront payment without leverage, prevalent in investor transactions and luxury tier acquisitions where stamp-duty optimization and negotiation leverage motivate liquidity deployment.
- Leasing:Rental arrangements with institutional or individual landlords, growing in Pune and Gurugram among young professionals prioritizing mobility over ownership.
- Developer Financing:Subvention schemes and construction-linked payment plans offered directly by builders, particularly in pre-RERA legacy markets where formal credit access remains constrained.
Home loans channel the majority of transaction value; leasing is gaining share fastest as co-living formats institutionalize rental housing.
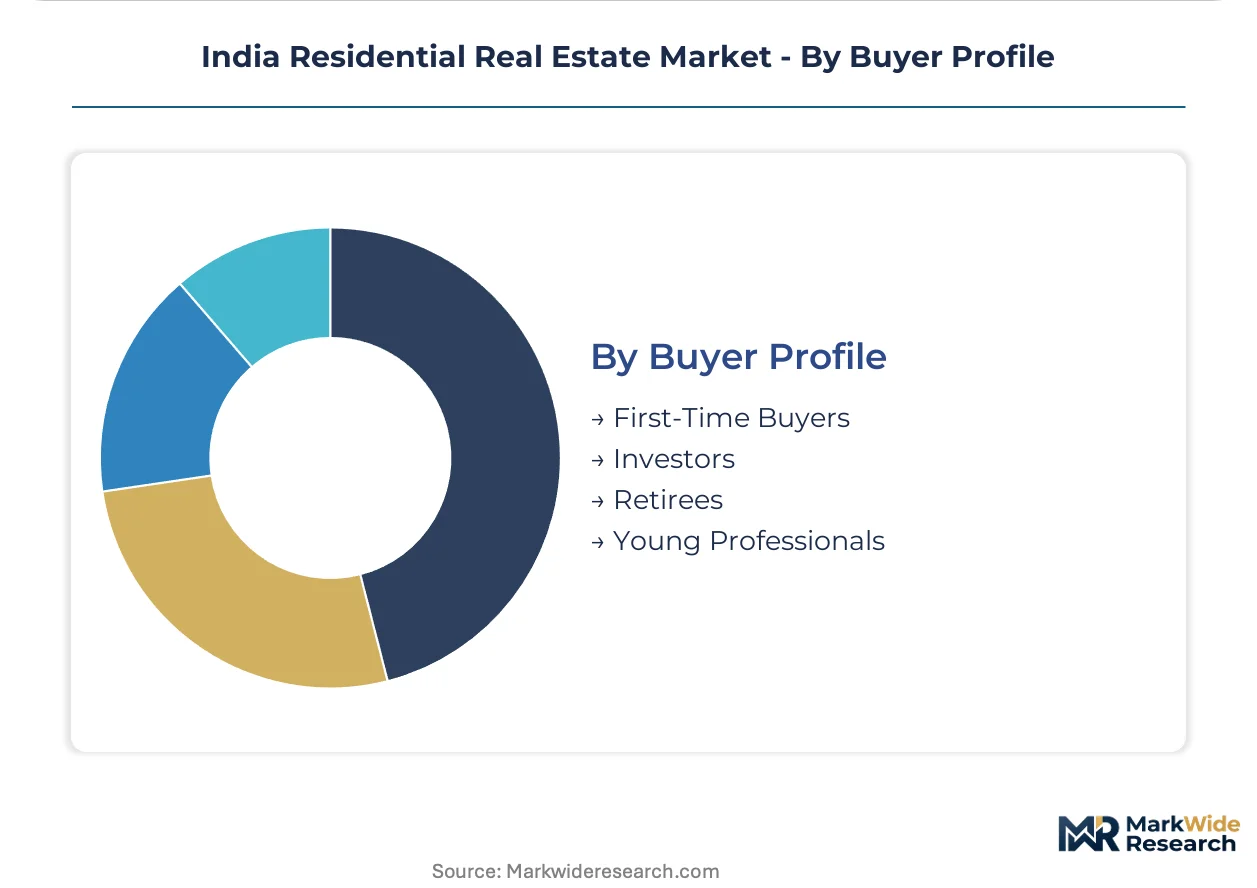
Buyer Profile:
Purchasing motivation and financial capacity stratify demand into segments with distinct product preferences and location trade-offs.
- First-Time Buyers:Households entering ownership for primary residence, typically salaried employees in technology and financial services. RERA escrow mandates and affordable housing finance gaps define their search constraints.
- Young Professionals:Early-career individuals aged 25–35 prioritizing commute proximity and amenity access over space. This cohort drives compact apartment demand in Mumbai's western suburbs and Bengaluru's Whitefield corridor.
- Investors:Acquisition for rental yield or capital appreciation, concentrated in completed inventory with established rental markets. Cash purchase prevalence and stamp-duty considerations shape their transaction timing.
- Retirees:Downsizing households seeking maintenance-light configurations with healthcare proximity. Demand concentrates in Pune and Chennai where climate and established medical infrastructure support aging-in-place preferences.
First-time buyers represent the largest transaction volume; young professionals are expanding fastest as migration to technology hubs accelerates household formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states. Maharashtra and Karnataka buyers absorb premium pricing with limited volume contraction, while Rajasthan and Madhya Pradesh markets exhibit acute price sensitivity where modest increases trigger significant demand destruction.
Maharashtra
The Mumbai-Pune corridor sustains the nation's highest per-square-foot pricing through concentrated employment density and metro rail expansion. RBI repo rate transmission directly affects affordability in Mumbai's western suburbs where salaried professional demand concentrates. Thane and Navi Mumbai sub-markets absorb spillover demand as central Mumbai land scarcity intensifies vertical development.
Karnataka
Bengaluru's technology sector income growth validates premium apartment pricing across Whitefield and Electronic City corridors. RERA registration mandates have concentrated supply among compliant developers with balance-sheet depth. Peripheral nodes along the Bangalore-Mysore Infrastructure Corridor are capturing manufacturing workforce housing demand as industrial clusters expand.
Telangana
Hyderabad's pharmaceutical and IT corridor expansion drives mid-range apartment absorption in Gachibowli and HITEC City sub-markets. State-level stamp-duty adjustments periodically accelerate transaction velocity among first-time buyers. The Outer Ring Road corridor is emerging as a villa development cluster where land assembly costs justify gated enclave premiums.
Gujarat
Ahmedabad and Surat markets exhibit pronounced price elasticity where affordable housing finance gaps constrain informal-income borrower participation. PLI scheme incentives for domestic cement and steel manufacturing are reducing input cost volatility for local developers. The Delhi-Mumbai Industrial Corridor node at Dholera is attracting land banking strategies from balance-sheet-strong builders.
Tamil Nadu
Chennai's manufacturing satellite towns around Sriperumbudur absorb economical-tier demand from automotive workforce housing needs. Fragmented land ownership patterns in core city areas extend pre-construction timelines compared to greenfield peripheral locations. The Chennai-Bengaluru Industrial Corridor is validating premium land banking as expressway connectivity improves.
India Residential Real Estate Market Competitive Landscape
Capability concentration sits with integrated developers possessing captive construction arms; scale advantage sits with diversified conglomerates with balance-sheet depth to absorb land banking cycles. The market structure exhibits tiered consolidation where RERA compliance has forced capital discipline and weeded out speculative launches. Three archetypes dominate: backward-integrated specialists controlling interior fit-outs and glazing manufacturing; diversified conglomerates leveraging group financial services for homebuyer financing; and technology-forward developers embedding smart-home infrastructure during construction. Competitive moves center on joint-venture structures for land assembly and captive facility management arms for recurring revenue beyond unit sales.
Among established developers with NCR and southern India presence, DLF Ltd, Sobha Ltd, and Godrej Properties exemplify distinct strategic archetypes. DLF Ltd occupies a position representing the diversified conglomerate model with captive facility management capabilities across its portfolio. Sobha Ltd exemplifies backward integration into manufacturing inputs, controlling interior fit-outs and glazing production. Godrej Properties represents the technology-forward tier, embedding smart-home infrastructure during construction to lock in long-term service relationships. These three anchors illustrate how developer strategies diverge across integration depth, geographic concentration, and revenue model composition.
| Leading Market Players |
|---|
| Prestige Estates Projects |
| Sobha Ltd |
| DLF Ltd |
| L&T Realty |
| Brigade Enterprises |
| Macrotech Developers |
| Godrej Properties |
| Anant Raj |
| Oberoi Realty |
| Others |
Supply & Pricing Matrix
The Delhi-Mumbai Industrial Corridor freight lanes transmit steel and cement cost volatility directly into developer pricing power, concentrating margin pressure on mid-tier builders while enabling premium capture by balance-sheet-strong players with captive logistics arrangements.
Pricing Analysis
Aftermarket property management contracts now drive lifetime value capture as developers shift from unit-sales to recurring-revenue models. Pricing stratifies across luxury, mid-range, affordable, and economical tiers based on location premiums and amenity bundling. Cost compression in affordable housing is intensifying because steel and cement input swings erode thin margins. First-time buyers exhibit acute price sensitivity while luxury investors absorb premiums with limited volume contraction.
Supply Chain Analysis
Upstream cement and steel feedstock sourcing centers on India, China, and select Middle East suppliers. Domestic manufacturing draws from limestone, iron ore, and energy inputs, with PLI scheme incentives reducing import dependency. Tariff exposure on specialty construction chemicals creates vulnerability for smart-home infrastructure developers. Distribution runs through developer-procurement teams, captive manufacturing arms, and third-party logistics networks serving metropolitan construction nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India residential real estate sits in early-cycle expansion as RERA compliance channels first-time buyer flows toward registered developers with balance-sheet depth.
For Market Incumbents: Harden land banking positions along the Mumbai-Pune corridor and Bengaluru's peripheral nodes before infrastructure completion validates premiums. Deepen backward integration into interior fit-outs and glazing manufacturing to defend margins against steel price volatility. Lock in captive facility management contracts across existing portfolios to secure recurring revenue beyond unit sales.
For New Entrants and Emerging Players: Tier-2 city penetration in Indore, Kochi, and Chandigarh offers white-space expansion with demand velocity previously concentrated in Mumbai and Delhi-NCR. Target co-living format development in Pune and Gurugram where young professional migration patterns validate institutional rental models. Partner with digital brokerage platforms for virtual site tour integration to reduce customer acquisition costs.
For Investors and Strategic Acquirers: Technology-forward developers embedding smart-home infrastructure during construction represent the priority acquisition archetype for long-term viability across a five-to-ten-year window. Monitor RBI repo rate transmission as the inflection indicator for home loan affordability compression and eligible buyer pool expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Land Assembly | Fragmented ownership in Bengaluru and Hyderabad forces partnership structures with balance-sheet-strong developers. |
| Captive Facility Management Arm | DLF's recurring revenue model demonstrates how developer-retained services capture aftermarket value. |
| Smart-Home Infrastructure Embedding | Godrej Properties locks in long-term service contracts through technology integration during construction. |
| Backward Integration Manufacturing | Sobha's interior fit-out and glazing control insulates margins from input cost volatility. |
| Tier-2 City Geographic Expansion | Indore, Kochi, and Chandigarh exhibit demand velocity previously concentrated in established metros. |
Research Methodology
A spread of perspectives from developer project heads, RBI monetary policy researchers, state RERA compliance officers, and mortgage lending executives converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against RERA registration databases, RBI monetary policy circulars, state stamp-duty notifications, and municipal development plan revisions. Bottom-up project pipeline enumeration triangulated against top-down state-level housing demand estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include property type, price tier, financing mechanism, and buyer demographic profile. CAGRs were derived from trend extrapolation moderated by regulatory inflection points. Forecast inputs incorporated RBI repo rate trajectory assumptions and state-level rental housing policy evolution.
Practitioners should monitor steel and cement price volatility, RBI monetary policy adjustments, and state-level stamp-duty revisions for early signals requiring forecast reassessment. Cross-checking against RERA quarterly disclosure data and state housing board registration statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
France Manufactured Homes Market