
 Property Management Service Market | 2026-2036
Property Management Service Market Size, Share, and Industry Trends Forecast 2026-2036
Property Management Service Market Insights
Institutional investors and REITs are rotating toward full-service property management as their preferred operating model, displacing fragmented owner-operator structures. Greystar leverages its vertical scale across multifamily assets to capture recurring fee income. FirstService Residential anchors its position through geographic density in high-barrier coastal markets. Avenue5 Residential specializes in technology-enabled operating platforms that reduce per-unit service costs.
Property management services encompass the operational oversight, maintenance coordination, tenant relations, and financial administration of real estate assets on behalf of owners. Core functions include lease administration, rent collection, vendor procurement, and capital planning for physical infrastructure preservation. Residential services lead by managed unit count, though commercial and industrial segments command higher fee margins per square foot. The percentage-of-rent pricing model dominates institutional contracts, while flat-fee structures persist among individual owner clients. Cloud-based property management software represents the fastest-expanding technology layer, displacing on-premise legacy systems.
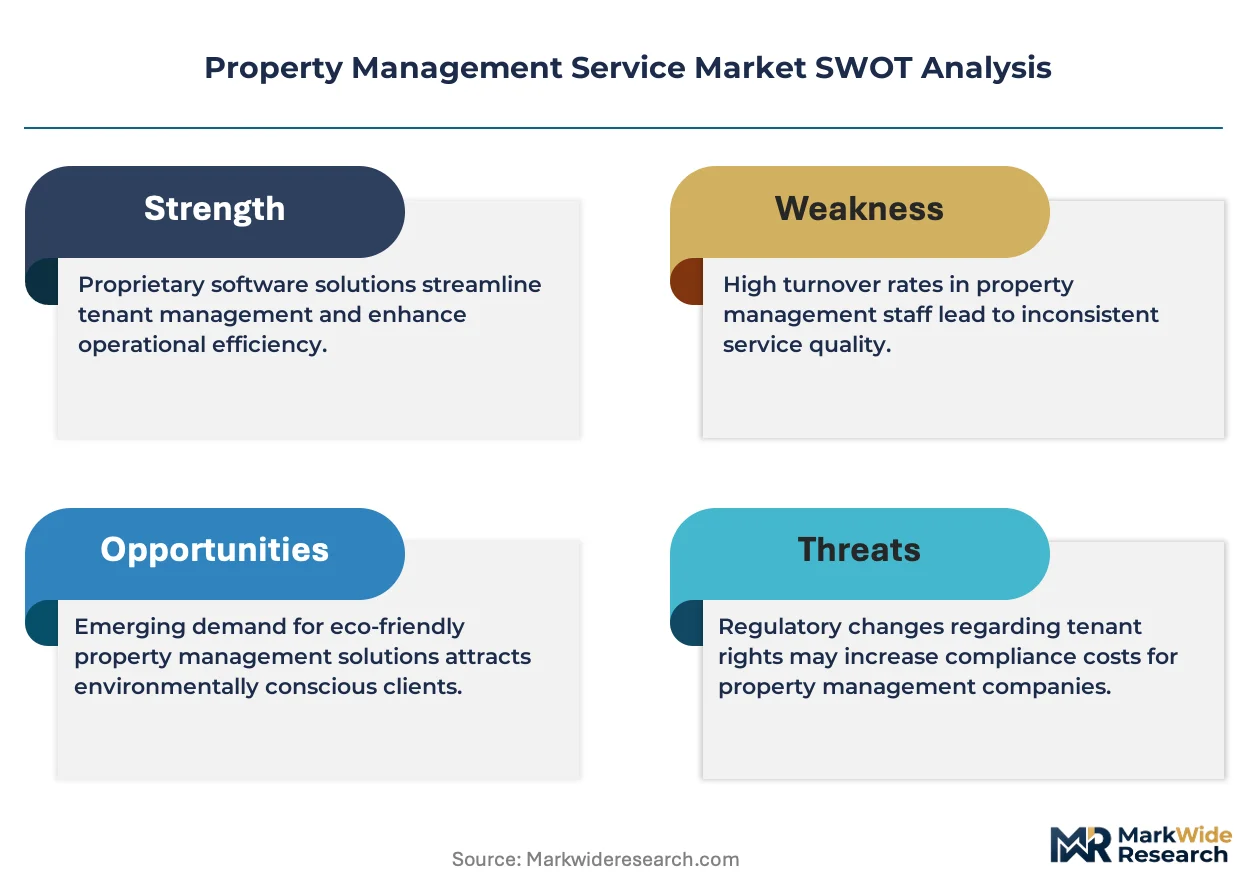
The US Department of Housing and Urban Development shapes fair housing compliance requirements that govern tenant screening and lease administration practices. State-level landlord-tenant statutes in California, Texas, and Florida create fragmented regulatory terrain that demands localized operational expertise. Stakeholders must monitor evolving rent-control ballot measures and building decarbonization mandates that threaten to compress net operating income and reshape service fee structures.
Market Dynamics
Institutional capital rotation into build-to-rent multifamily assets is compressing fee tolerance while demanding full-stack operational capabilities, forcing property managers to absorb capital planning and smart infrastructure oversight previously retained by asset owners.
Growth Catalysts
- HUD Fair Housing Act enforcement expansion:Complex compliance requirements drive outsourcing of tenant screening and lease administration to specialized managers with dedicated legal infrastructure.
- Smart building IoT convergence:Sensor networks for predictive maintenance and energy optimization create recurring technology service revenue streams atop traditional management fees.
- Sun Belt metropolitan cluster expansion:Phoenix, Austin, and Tampa absorb domestic migration flows, concentrating new multifamily supply requiring professionalized operational oversight.
Market Restraints
- Labor cost volatility in maintenance trades:HVAC technician and certified electrician wage inflation compresses net margins on full-service contracts with fixed fee escalators.
- Supply concentration in cloud software platforms:Three dominant vendors control property management SaaS infrastructure, creating subscription cost pressure and integration lock-in.
- Technical limitation in legacy system interoperability:On-premise accounting and access control systems resist API connectivity, fragmenting operational data across incompatible platforms.
Strategic Opportunities
- India commercial office stock professionalization:REIT-structured office assets in Bangalore and Mumbai lack mature management infrastructure, creating greenfield contract potential for platform-equipped operators.
- EU CSRD sustainability reporting mandates:Mandatory building-level carbon disclosure creates demand for energy auditing and ESG data aggregation services as add-on offerings.
- Technology convergence of AI leasing assistants with virtual touring:Automated tenant qualification and remote property showings reduce per-lease labor hours while accelerating occupancy velocity.
Industry Challenges
- Certified property manager talent scarcity:State-level broker licensing requirements and specialized CPM credentialing create pipeline bottlenecks for scaling operations into new markets.
- Legacy accounting system migration complexity:Decades of tenant ledger data trapped in depreciated on-premise software resists clean extraction to cloud-native platforms, delaying technology ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Property Management Service Market |
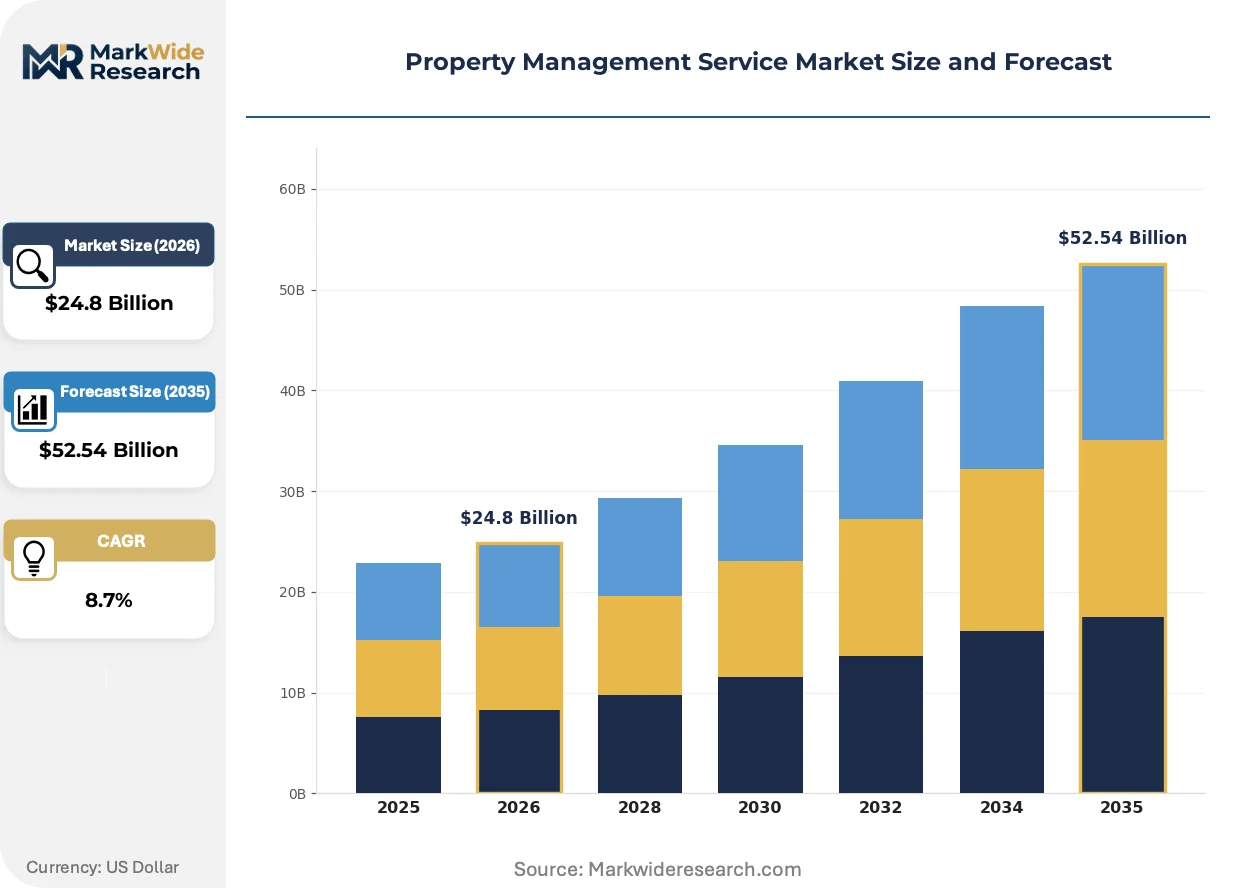
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Industrial, Retail Pricing Model: Flat Fee, Percentage of Rent, Hybrid, Commission-based Client Type: Individual Owners, Corporations, Investors, REITs Technology: Property Management Software, Mobile Apps, IoT Solutions, Cloud Services |
| Companies Covered | Greystar, Asset Living, RPM Living, FirstService Residential, FPI Management, Lincoln Property Company, Avenue5 Residential, Willow Bridge Property Company, Yardi Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Property Management Service Market Trends and Innovations
Digital infrastructure is collapsing the traditional separation between physical asset oversight and financial administration, embedding property managers into capital allocation decisions previously reserved for institutional asset allocators.
Cloud-native property management platforms are supplanting server-based legacy systems that required on-site IT maintenance and resisted remote access. Mid-market multifamily operators with 500-5,000 units under management are migrating fastest, driven by distributed workforce requirements and investor reporting demands. This technology shift compresses back-office headcount per unit while enabling real-time performance benchmarking across portfolios.
Building decarbonization mandates emerging from California's Title 24 energy code and New York City Local Law 97 are forcing capital planning integration into standard service contracts. Property managers must now model retrofit timelines and utility incentive capture alongside traditional operating budgets. The commercial office segment faces the steepest compliance burden, with managers absorbing engineering assessment costs to retain institutional clients.
Tenant qualification workflows are fragmenting across specialized point solutions rather than consolidating into single-vendor suites. Automated income verification services, AI-powered chatbot screening, and third-party guarantor platforms now operate as modular add-ons to core management software. This unbundling is most pronounced in high-turnover student housing and workforce housing submarkets, where speed-to-lease outweighs operational simplicity.
Property Management Service Market Segmentation
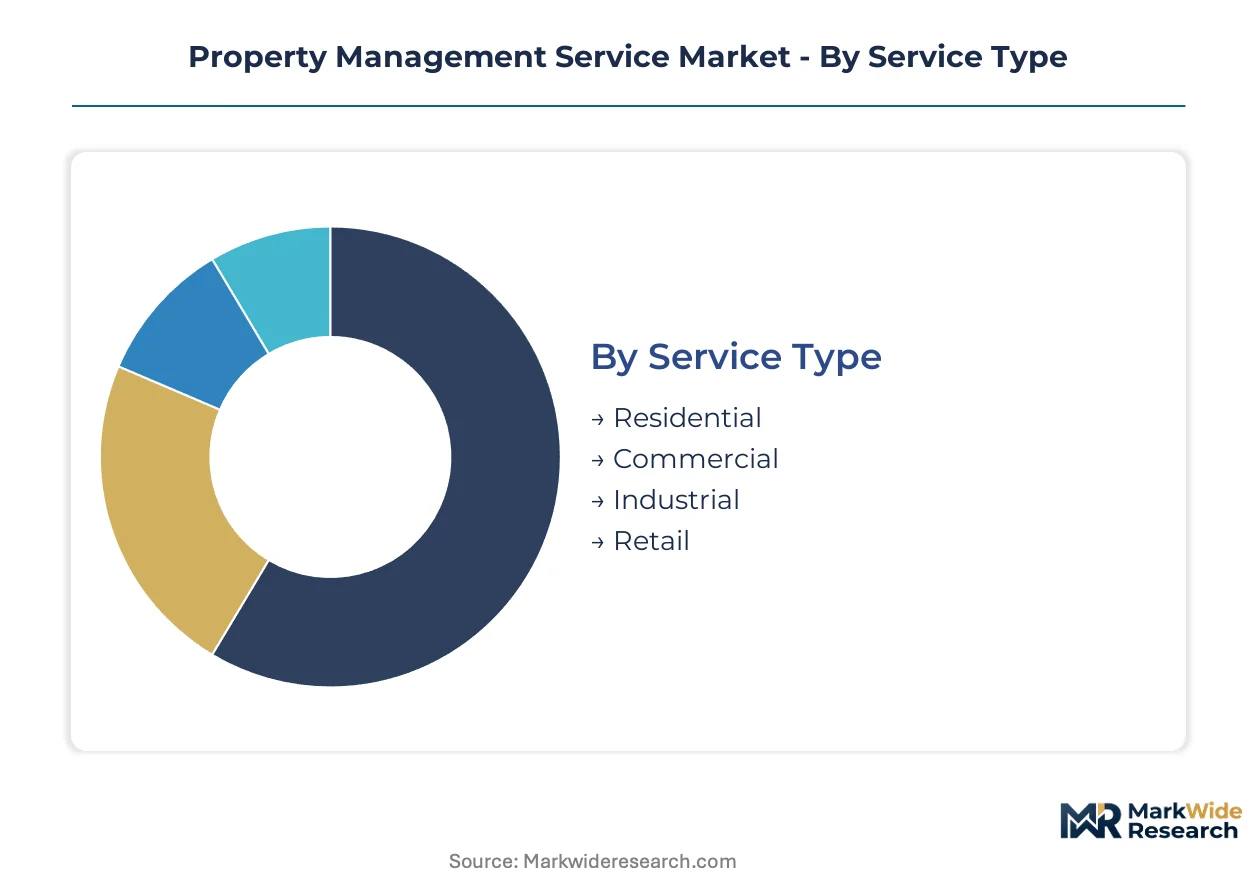
Segmentation in property management services reveals divergent margin structures across asset classes and client sophistication tiers. Service providers configure operational capabilities and pricing architectures around specific combinations of building type, ownership structure, and technology integration depth.
Service Type:
Margin pools concentrate disproportionately in commercial and industrial segments where per-square-foot fee rates exceed residential multiples, though residential commands absolute unit volume.
- Residential:Multifamily apartment complexes and single-family rental portfolios generate recurring monthly management fees scaled to unit counts. Sun Belt metropolitan clusters including Phoenix, Austin, and Tampa absorb domestic migration flows, concentrating new supply requiring professionalized oversight.
- Commercial:Office buildings, medical facilities, and mixed-use developments demand specialized lease administration and capital planning services. Building decarbonization mandates from California's Title 24 energy code and New York City Local Law 97 force retrofit timeline modeling into standard contracts, elevating technical service value.
- Industrial:Warehouses, distribution centers, and manufacturing facilities require environmental compliance monitoring and specialized vendor networks.
- Retail:Shopping centers and strip malls face tenant mix optimization challenges amid e-commerce displacement pressures.
Residential holds installed capacity. Commercial is rotating up the share rankings.
Pricing Model:
Client sophistication determines pricing architecture, with institutional contracts gravitating toward performance-linked structures while individual owners prefer cost certainty.
- Flat Fee:Fixed monthly charges for defined service bundles appeal to cost-sensitive individual owners and small portfolios. The structure sacrifices upside participation but eliminates revenue volatility during vacancy cycles.
- Percentage of Rent:Fee scales with collected rental income, aligning manager incentives with owner returns. Institutional REIT contracts favor this model for its transparency in investor reporting and its natural hedge against occupancy fluctuations.
- Hybrid:Base fee plus performance bonuses for occupancy targets or expense reductions captures value from operational excellence.
- Commission-based:Transaction fees for tenant placement and lease renewals dominate in high-turnover submarkets.
Percentage of Rent anchors institutional contracts. Hybrid structures are climbing fastest in mid-market operator adoption.
Client Type:
Ownership concentration shapes service bundling depth, with scaled investors demanding integrated capabilities that fragmented individual owners procure separately.
- Individual Owners:Small landlords with under 50 units typically purchase à la carte services and resist technology platform fees. Localized operational expertise and personal relationship continuity drive vendor selection.
- Corporations:Corporate real estate departments managing owned facilities require integrated facilities management spanning maintenance, security, and space planning.
- Investors:Private equity and institutional capital pools prioritize reporting granularity and benchmarked performance metrics across dispersed portfolios.
- REITs:Publicly traded real estate investment trusts mandate Sarbanes-Oxley-compliant financial controls and real-time investor dashboard access.
REITs command premium service tiers. Individual Owners represent the largest addressable population by count.
Technology:
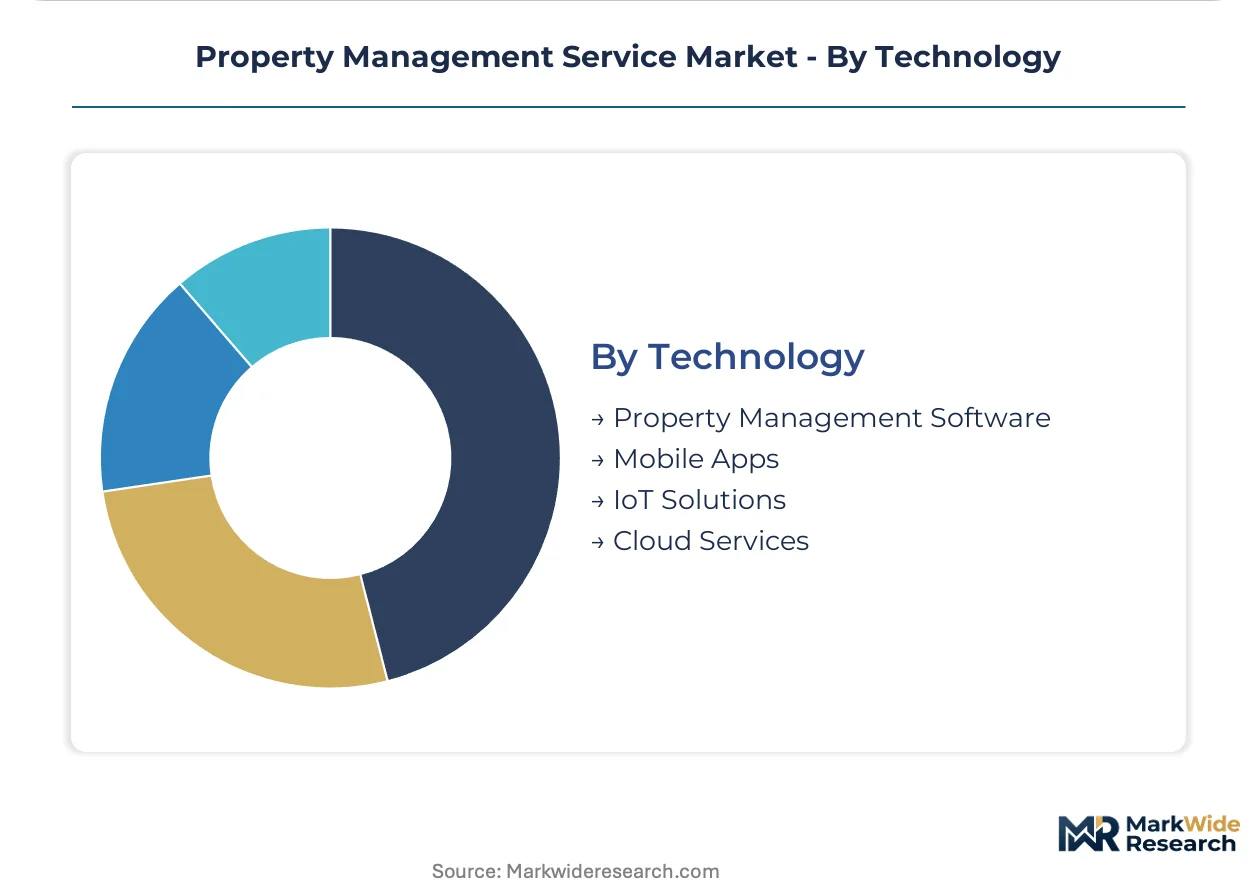
Technology stack choices segment providers by capital intensity and recurring revenue composition, with cloud-native platforms displacing legacy infrastructure.
- Property Management Software:Core platforms for lease administration, accounting, and maintenance ticketing now operate exclusively through cloud delivery. Mid-market operators with 500-5,000 units are migrating fastest, driven by distributed workforce requirements.
- Mobile Apps:Tenant-facing applications for rent payment, maintenance requests, and community engagement reduce call center volume. Student housing and workforce housing submarkets show highest adoption where digital-native tenant demographics dominate.
- IoT Solutions:Sensor networks for predictive maintenance and energy optimization create technology service revenue streams atop traditional management fees.
- Cloud Services:Data hosting and cybersecurity infrastructure underpins remote operational capabilities across all service tiers.
Property Management Software holds functional centrality. IoT Solutions are expanding most quickly as decarbonization mandates accelerate sensor deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles Basin logistics corridor underwrites North American property management concentration, channeling institutional capital into adjacent multifamily and industrial assets requiring professionalized oversight.
United States
Domestic migration into Sun Belt metropolitan clusters concentrates new multifamily supply in Phoenix, Austin, and Tampa. HUD Fair Housing Act enforcement expansion drives outsourcing of tenant screening to specialized managers with dedicated legal infrastructure. Dallas-Fort Worth absorbs the largest share of build-to-rent institutional investment, forcing property managers to integrate capital planning into standard service contracts.
Canada
Toronto and Vancouver multifamily REITs professionalize operating platforms to satisfy institutional investor reporting requirements. The country's national housing regulator maintains rent-control frameworks that compress fee tolerance while demanding compliance infrastructure. Calgary's downtown office-to-residential conversion pipeline creates specialized asset repositioning service demand.
Germany
Berlin's rental market regulation through the Mietendeckel framework, despite constitutional challenges, established precedent for municipal intervention in property management fee structures. Munich and Frankfurt commercial office stock faces EU CSRD sustainability reporting mandates requiring energy auditing services. The Rhine-Ruhr industrial corridor generates logistics facility management demand from e-commerce fulfillment expansion.
United Kingdom
London's Build to Rent sector institutionalizes professional management as standard for institutional capital deployment. The UK's national housing regulator enforces building safety standards post-Grenfell, elevating technical compliance service value. Manchester and Birmingham city-center residential towers concentrate technology-enabled operating platform adoption.
India
Bangalore and Mumbai REIT-structured office assets lack mature management infrastructure, creating greenfield contract potential. The country's national real estate regulator mandates project-level escrow and disclosure standards that professionalize owner-manager relationships. Hyderabad's HITEC City corridor concentrates commercial office stock requiring integrated facilities management.
Property Management Service Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational agility dimensions. The market exhibits tiered concentration, with vertically integrated multifamily operators commanding institutional contracts while regional specialists retain individual owner relationships. Three archetypes dominate: scale-driven full-service platforms, technology-enabled cost optimizers, and geographically dense coastal specialists. Competitive moves center on portfolio acquisition to achieve market density and technology licensing to embed recurring software revenue.
Within the scale-driven tier, Greystar and Lincoln Property Company exemplify vertical integration across development, investment, and management functions. FirstService Residential anchors the geographically dense archetype through coastal market concentration. Avenue5 Residential occupies a position representing technology-enabled operating platform specialization. These three patterns illustrate how capital structure and capability focus determine contract access across institutional, corporate, and individual owner segments.
| Leading Market Players |
|---|
| Greystar |
| Asset Living |
| RPM Living |
| FirstService Residential |
| FPI Management |
| Lincoln Property Company |
| Avenue5 Residential |
| Willow Bridge Property Company |
| Yardi Systems |
| Others |
Pricing and Supply Chain Analysis
Scale economies in cloud-native platform deployment compress per-unit service delivery costs while concentrating vendor power among three dominant SaaS infrastructure providers. This concentration elevates subscription pricing leverage and fragments operational data across incompatible legacy systems, forcing mid-market operators into costly migration cycles.
Pricing Analysis
Volume-discount tiering structures separate institutional REIT contracts from individual owner arrangements, with percentage-of-rent models dominating scaled portfolios and flat-fee structures persisting among sub-50-unit landlords. Price differentiation rests on technology integration depth and geographic market density, with Sun Belt metropolitan clusters absorbing compressed fee tolerance amid build-to-rent capital inflows. Margins are tightening due to labor cost volatility in HVAC and certified electrical trades. Individual owners exhibit highest price sensitivity, while REITs prioritize reporting transparency over absolute fee minimization.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach and Los Angeles Basin channel smart building sensor hardware and HVAC equipment into domestic installation networks. Component supply draws from Mexico for proximity manufacturing, China for IoT sensor fabrication, and Germany for precision control systems. Single-source vulnerability concentrates in cloud software platforms resisting API interoperability with legacy accounting systems. Distribution runs through vertically integrated national operators and regional specialist networks serving fragmented individual owner segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property management incumbents face substitution pressure from self-service technology platforms that disintermediate traditional operational oversight, requiring defensive capability investments to retain contract access.
For Market Incumbents: Consolidate geographic density in high-barrier coastal markets where regulatory complexity defends against platform disintermediation. Absorb capital planning and smart infrastructure oversight functions previously retained by asset owners, embedding managers into allocation decisions. Backward integration into proprietary technology platforms reduces per-unit service costs and creates recurring software revenue streams.
For New Entrants and Emerging Players: CPM credential fast-tracks unlock scaling pathways into Sun Belt metropolitan clusters where certified manager scarcity constrains incumbent expansion. Target India commercial office stock in Bangalore and Mumbai where REIT-structured assets lack mature management infrastructure. Lead with technology-enabled operating platforms that reduce per-unit labor hours through AI leasing assistants and virtual touring capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-equipped operators with cloud-native infrastructure and IoT integration capabilities over legacy server-dependent competitors. Long-term viability hinges on decarbonization mandate compliance infrastructure and ESG data aggregation service offerings. Monitor EU CSRD sustainability reporting enforcement as inflection indicator for energy auditing service demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Acquisition | Cloud-native infrastructure displaces legacy systems across mid-market operator portfolios. |
| Geographic Market Consolidation | Sun Belt metropolitan density captures build-to-rent institutional capital inflows. |
| Certified Talent Pipeline Investment | CPM credentialing programs alleviate scaling constraints in fragmented state licensing environments. |
| Smart Building IoT Integration | Sensor networks generate recurring technology service revenue atop traditional management fees. |
| Decarbonization Compliance Services | California Title 24 and New York Local Law 97 mandate retrofit timeline modeling into standard contracts. |
Research Methodology
A spread of perspectives from property management executives, REIT portfolio directors, facilities maintenance contractors, and cloud software platform engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from HUD regulatory filings, state landlord-tenant statute databases, and multifamily REIT SEC disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing across service type, pricing model, and client sophistication tiers.
Segmentation dimensions modeled include asset class, ownership structure, technology integration depth, and geographic market cluster over the projection horizon. CAGRs derived from historical fee income trajectories and forward supply absorption patterns in Sun Belt metropolitan areas. Forecast inputs incorporated domestic migration flow data and institutional capital deployment velocity into build-to-rent multifamily assets.
Underlying assumptions cover sustained HUD Fair Housing Act enforcement expansion and smart building IoT adoption curves, with deviation risk concentrated in rent-control ballot measure outcomes and cloud vendor consolidation dynamics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
United States Property Management Market
Property Management
Europe Self Storage Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
Spain Warehousing Market
Property Management
Residential Property Management Market
Property Management
Qatar Flexible Office Space Market
Property Management
Hungary Warehousing Sector Market
Property Management
South Korea Self-Storage Market
Property Management
Real Estate Management Software Market
Property Management
Real Estate (Property) Management Market
Property Management
US Property Management Software Market
Property Management
Property Management Software Market