
 Period Patch Market | 2026-2036
Period Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Period Patch Market Analytics
Transdermal cannabinoid and herbal delivery systems is tilting period patch formulation away from simple adhesive heat wraps toward multi-layer active-release platforms. Procter & Gamble leverages its mass retail infrastructure to sustain shelf dominance across North American pharmacy chains. Rael specializes in organic cotton substrates and K-beauty positioning, anchoring its appeal among Asian-American millennials. Sirona competes through aggressive digital marketing on Instagram and TikTok, controlling direct-to-consumer conversion in India's tier-one cities.
A period patch is a topical adhesive device engineered with a layered composite of hydrogel or fabric substrate, active ingredient reservoir, and controlled-release membrane designed to deliver analgesic, anti-inflammatory, or thermoregulatory agents through the skin during menstruation. Manufacturing employs precision coating lines to achieve consistent active loading between 50-200 mg per 10 cm² patch surface, with peel adhesion measured at 300-600 g/25mm to balance secure placement against sensitive abdominal skin removal. Disposable patches lead volume due to convenience-driven repeat purchase behavior, while organic patches command the strongest margin pools as consumers scrutinize ingredient transparency. Transdermal delivery technology is displacing simple heat patches in premium positioning, though herbal infusion formats retain loyalty among users seeking non-synthetic relief pathways.
FDA 510(k) clearance requirements govern active-ingredient patches marketed with drug claims in the United States, while the EU Medical Device Regulation and REACH chemical safety standards shape formulation compliance across European markets. Japan's PMDA maintains distinct documentation thresholds for thermal versus pharmacological patch classifications, creating divergent registration pathways for exporters. Stakeholders must monitor evolving classification boundaries between cosmetic wellness devices and regulated medical products as national health authorities recalibrate oversight frameworks.
Market Dynamics
Transdermal delivery architecture is virtualizing period patch formulation from passive heat wraps toward active-release platforms with pharmacological reservoirs, forcing manufacturers to recalibrate coating precision and membrane permeability specifications.
Growth Catalysts
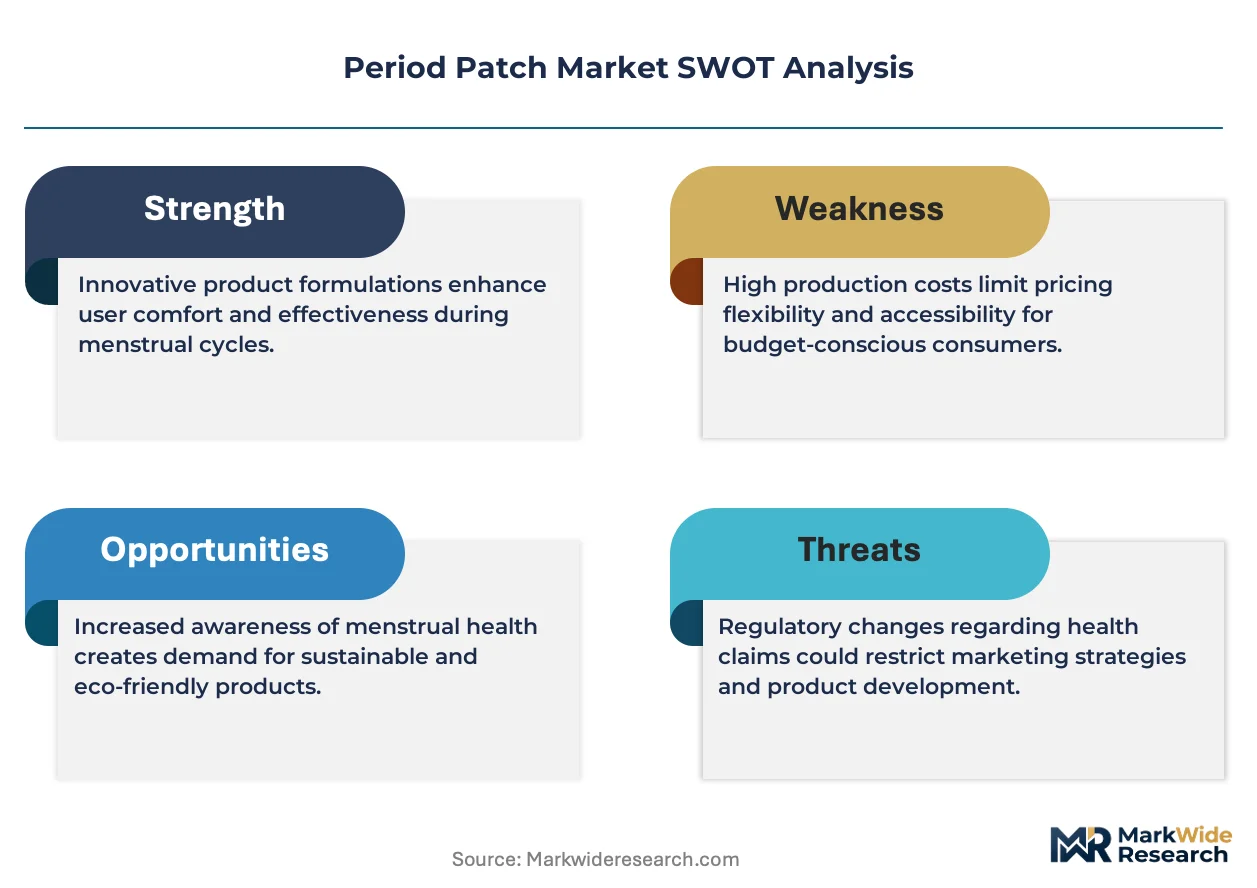
- EU MDR Reclassification:The Medical Device Regulation's tightened documentation for adhesive patches with active ingredients is accelerating investment in clinical validation infrastructure among European manufacturers.
- Menstrual Wellness Spending Concentration:Women aged 18-45 in developed economies are directing discretionary health budgets toward non-pharmaceutical pain management, expanding direct-to-consumer subscription channels.
- Hydrogel Reservoir Technology:Precision coating lines achieving 50-200 mg active loading per 10 cm² surface are enabling consistent transdermal flux rates that meet pharmacological efficacy thresholds.
Market Restraints
- Active Pharmaceutical Ingredient Volatility:Cannabinoid and herbal extract supply chains face agricultural yield fluctuations and extraction capacity bottlenecks that compress formulation margins.
- Regulatory Classification Friction:FDA 510(k) clearance requirements for drug-claim patches create 18-24 month approval timelines that deter rapid product iteration compared to cosmetic wellness devices.
- Adhesion Performance Trade-offs:Peel adhesion specifications of 300-600 g/25mm must balance secure abdominal placement against pain-free removal from sensitive skin, limiting substrate material options.
Strategic Opportunities
- India Tier-One City Penetration:Instagram and TikTok-native digital marketing is converting urban millennial consumers to subscription-based patch delivery models with minimal retail infrastructure investment.
- Organic Cotton Certification Tailwinds:REACH chemical safety standards and consumer ingredient transparency demands are creating margin pools for GOTS-certified substrate manufacturers.
- Pharmacy Chain Integration:Mass retail infrastructure in North American pharmacy chains offers shelf dominance for patches positioned between analgesic pharmaceuticals and feminine hygiene aisles.
Industry Challenges
- Formulation Chemist Scarcity:Transdermal permeation enhancement expertise sits concentrated among pharmaceutical specialists, creating recruitment bottlenecks for wellness-device manufacturers.
- Multi-Jurisdiction Registration Complexity:Divergent PMDA thermal versus pharmacological classification thresholds in Japan force exporters to maintain parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Period Patch Market |
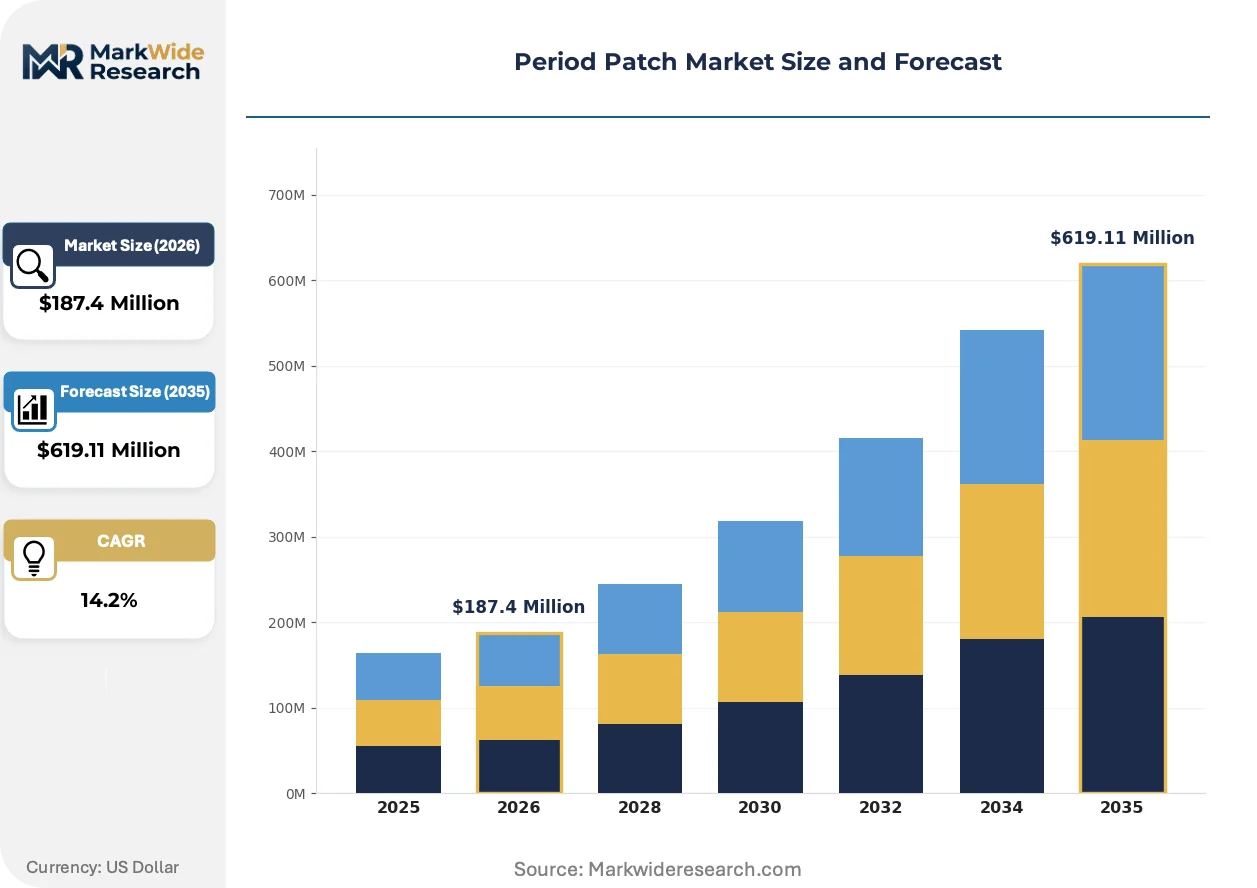
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Patches, Reusable Patches, Organic Patches, Standard Patches Technology: Transdermal Delivery, Heat Patches, Herbal Infusion, Cooling Technology End User: Teenagers, Adults, Athletes, Healthcare Providers Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Procter & Gamble, BeYou, Rael, Cora, The Good Patch, Sirona, TheraPatch, Patchology, Livia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Period Patch Market Evolving Landscape
Multi-layer active-release platforms are compressing the competitive distance between wellness devices and regulated medical products, reshaping how manufacturers position efficacy claims and clinical evidence requirements.
Micro-needle array technology is virtualizing period patch delivery from passive diffusion to active stratum corneum disruption. K-beauty positioned brands are adopting these platforms for faster onset times among Asian-American millennial demographics. The structural consequence is virtualizing the boundary between cosmetic wellness and pharmacological device categories, forcing regulatory strategy to precede product development.
Japan's PMDA maintains distinct thermal versus pharmacological patch classifications that create divergent registration pathways for exporters. Manufacturers targeting the Japanese market must submit separate documentation bundles depending on active ingredient claims and intended mechanism of action. Premium positioning segments are responding by bifurcating product lines into regulated medical and cosmetic wellness variants with identical substrates but differentiated labeling.
Subscription-based direct-to-consumer replenishment is displacing pharmacy impulse purchases among urban professional women. Digital-native brands are capturing lifetime value through automated monthly shipments while legacy retail-dependent competitors face channel margin compression. This pattern concentrates in United States metropolitan markets where menstrual wellness app integration drives patch replenishment timing.
Period Patch Market Segmentation
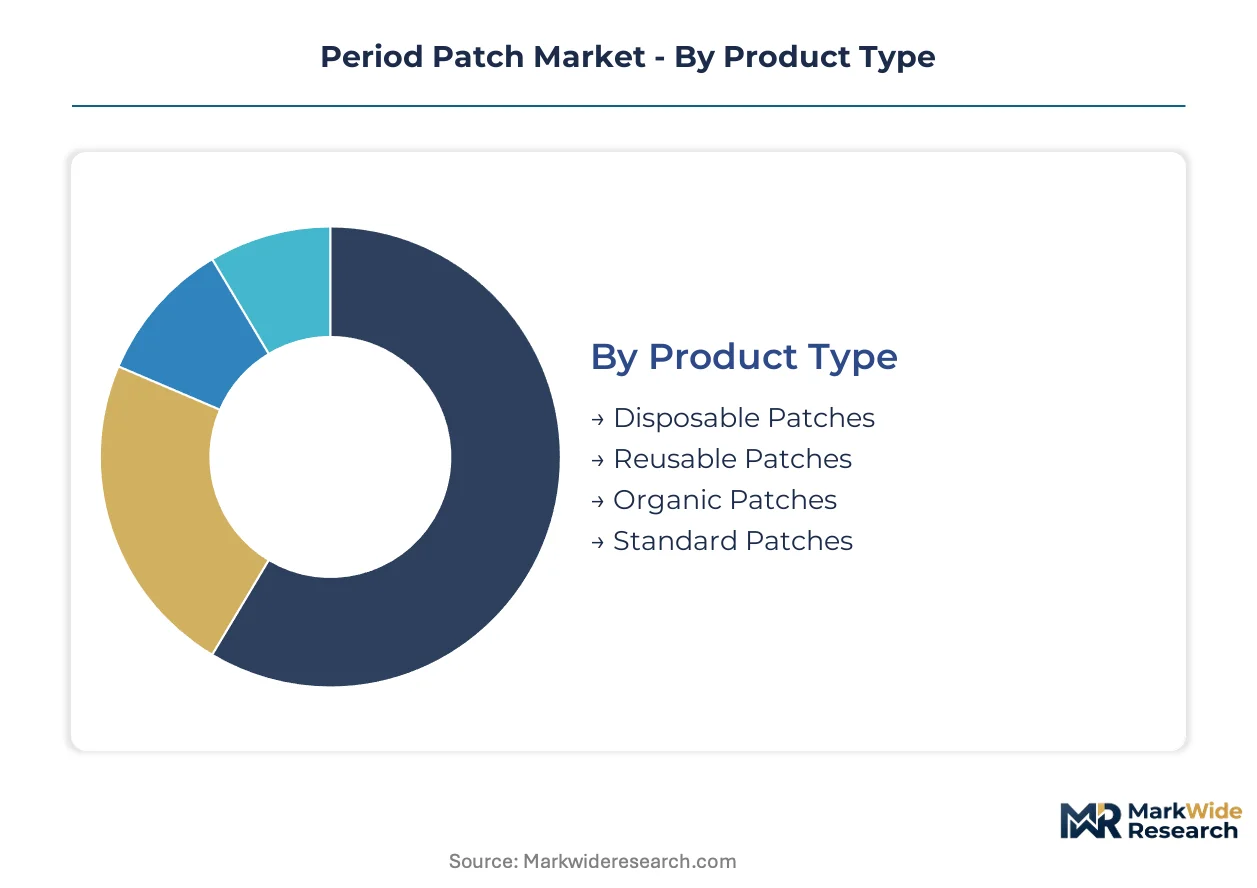
Period patch segmentation reveals divergent margin structures across material choices, delivery mechanisms, and channel economics. Manufacturers optimize portfolio mix by calibrating regulatory burden against subscription lifetime value within each segment cluster.
Product Type:
Cost tier stratification separates convenience-driven disposables from certified-organic premium positioning with divergent margin profiles.
- Disposable Patches:Single-use hydrogel or fabric substrates with 50-200 mg active loading per 10 cm² surface dominate pharmacy impulse purchases. Demand concentrates in United States metropolitan markets where subscription fatigue has not yet displaced convenience-driven replenishment cycles.
- Organic Patches:GOTS-certified cotton substrates with REACH-compliant adhesive formulations command strongest margin pools as ingredient transparency scrutiny intensifies. German and Japanese consumers drive premium positioning through direct-to-consumer channels that bypass mass retail margin compression.
- Reusable Patches:Silicone or fabric substrates designed for 20-50 wash cycles target sustainability-motivated athletes and healthcare providers seeking waste reduction credentials.
- Standard Patches:Conventional synthetic substrates with basic analgesic or thermal functionality serve price-sensitive entry segments in emerging markets.
Disposable patches command the established base. The steepest expansion runs through organic certification tiers.
Technology:
Delivery mechanism sophistication determines regulatory pathway complexity and clinical validation requirements across jurisdictions.
- Transdermal Delivery:Multi-layer reservoirs with controlled-release membranes achieve pharmacological flux rates through precision coating lines. FDA 510(k) clearance requirements in the United States and EU MDR documentation obligations create 18-24 month approval timelines that favor established pharmaceutical infrastructure holders.
- Heat Patches:Iron powder oxidation or carbon fiber elements generate 40-50°C surface temperatures for vasodilation. Japan's PMDA maintains distinct thermal classification thresholds that simplify registration compared to pharmacological variants, concentrating exporter attention on Tokyo and Osaka metropolitan distribution.
- Herbal Infusion:Cannabidiol, menthol, or traditional Asian botanical extracts in hydrogel matrices serve consumers seeking non-synthetic relief pathways with lighter regulatory burden.
- Cooling Technology:Evaporative or endothermic chemical reactions targeting inflammation rather than cramping occupies niche positioning among athletic recovery applications.
Heat patches retain volume leadership across pharmacy chains. Transdermal platforms are climbing the fastest as efficacy claims harden into clinical evidence requirements.
End User:
Demographic and professional application segments diverge sharply in purchase frequency, price sensitivity, and channel preference.
- Adults:Women aged 18-45 in developed economies direct discretionary health budgets toward subscription-based replenishment with menstrual wellness app integration. United States urban professional concentrations in New York, Los Angeles, and Chicago anchor direct-to-consumer conversion rates.
- Teenagers:First-time users with lower brand loyalty and higher parental purchase influence concentrate in pharmacy and supermarket channels where impulse visibility drives trial.
- Athletes:Performance-oriented users prioritize cooling technology and reusable formats with sweat-resistant adhesion specifications for training continuity.
- Healthcare Providers:Clinical recommendation channels in Germany and Japan drive institutional procurement of transdermal variants with documented efficacy profiles.
Adult subscription segments capture highest lifetime value. Teenage trial conversion offers the steepest volume expansion pathway.
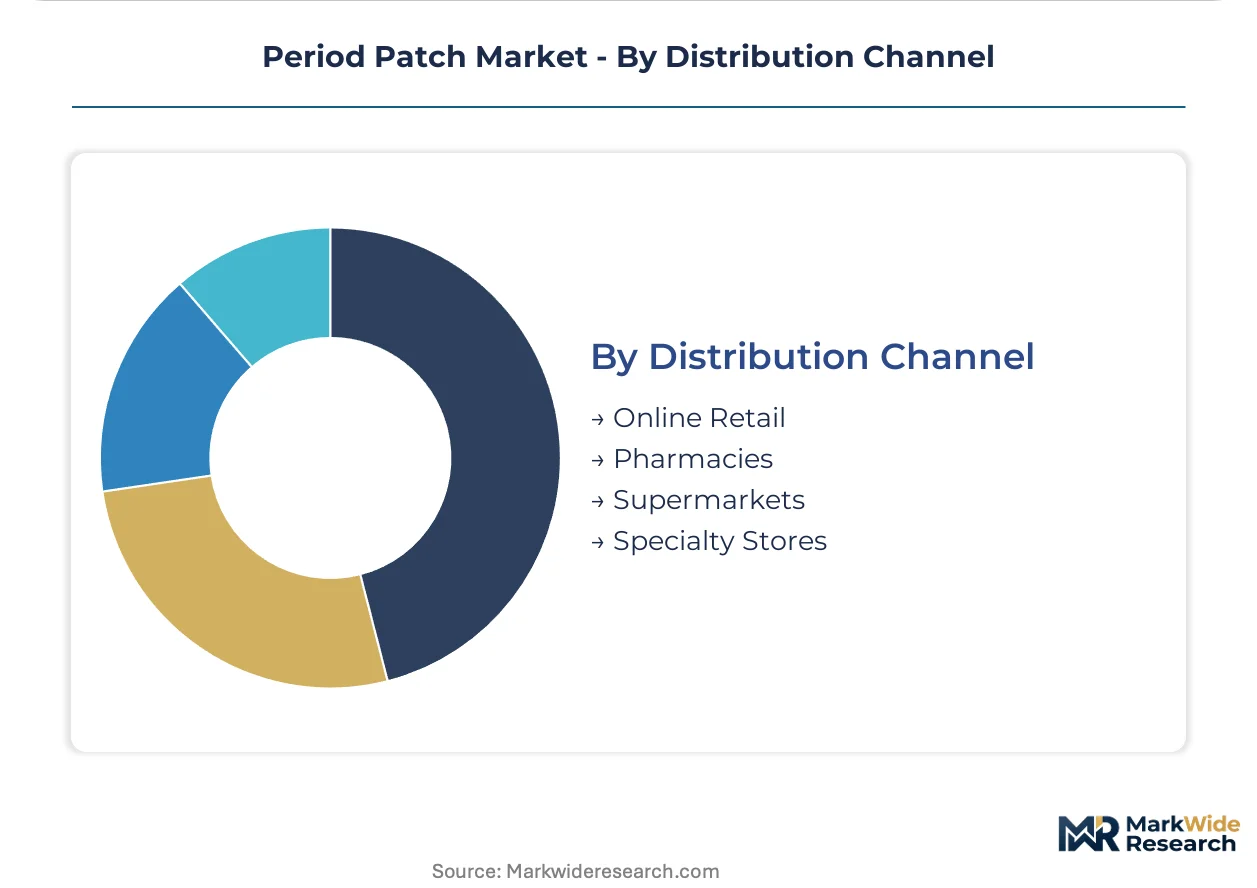
Distribution Channel:
Channel configuration determines margin retention, customer data ownership, and regulatory compliance burden intensity.
- Online Retail:Direct-to-consumer platforms with automated replenishment algorithms capture full margin and behavioral data. Instagram and TikTok-native marketing converts urban Indian millennials in Mumbai, Delhi, and Bangalore with minimal retail infrastructure investment.
- Pharmacies:CVS, Walgreens, and Shoppers Drug Mart shelf positioning between analgesics and feminine hygiene drives impulse discovery. Procter & Gamble leverages mass retail infrastructure to sustain North American dominance.
- Supermarkets:Mass-market placement targets price-sensitive convenience purchasers with lower engagement and subscription conversion potential.
- Specialty Stores:K-beauty retailers and organic wellness boutiques in Seoul, Los Angeles, and New York serve ingredient-transparency-motivated segments with premium positioning.
Pharmacy channels command the established base. Online retail is expanding most quickly as subscription economics displace impulse purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban professional women aged 18-45 in developed economies concentrate menstrual wellness spending through direct-to-consumer channels, with regulatory frameworks in major markets determining product classification pathways.
United States
FDA 510(k) clearance requirements govern active-ingredient patches marketed with drug claims, creating 18-24 month approval timelines that favor established pharmaceutical infrastructure holders. New York, Los Angeles, and Chicago metropolitan areas anchor subscription-based direct-to-consumer conversion rates. Procter & Gamble leverages mass retail infrastructure across CVS and Walgreens pharmacy chains to sustain shelf dominance.
Germany
EU Medical Device Regulation tightened documentation requirements for adhesive patches with active ingredients, accelerating investment in clinical validation infrastructure among European manufacturers. REACH chemical safety standards shape formulation compliance for organic cotton substrate certification. Berlin and Hamburg concentrate direct-to-consumer premium positioning that bypasses mass retail margin compression.
Japan
PMDA maintains distinct thermal versus pharmacological patch classifications, creating divergent registration pathways for exporters targeting Tokyo and Osaka metropolitan distribution. Thermal classification thresholds simplify registration compared to pharmacological variants. Premium positioning segments bifurcate product lines into regulated medical and cosmetic wellness variants with identical substrates but differentiated labeling.
India
Instagram and TikTok-native digital marketing converts urban millennial consumers in Mumbai, Delhi, and Bangalore to subscription-based patch delivery models. Sirona competes through aggressive social media campaigns controlling direct-to-consumer conversion in tier-one cities. Minimal retail infrastructure investment requirements enable rapid market penetration for digital-native brands.
South Korea
K-beauty positioning anchors appeal among Asian-American millennials seeking organic cotton substrates with ingredient transparency. Seoul-based specialty retailers serve transparency-motivated segments with premium positioning. Micro-needle array technology adoption for faster onset times concentrates among brands targeting this demographic cluster.
Period Patch Market Competitive Landscape
Channel-controlling players compete with product-specialist players across pharmacy, supermarket, and direct-to-consumer platforms. The vendor base stratifies into mass retail infrastructure holders, digital-native subscription specialists, and regional K-beauty positioned brands. Three archetypes dominate: legacy FMCG conglomerates with shelf dominance, organic-certified substrate specialists, and social media-native direct-to-consumer converters. Competitive moves center on pharmacy chain integration partnerships and automated replenishment algorithm deployment.
Within the mass retail infrastructure tier, Procter & Gamble exemplifies channel control through North American pharmacy chain shelf positioning. Among digital-native specialists, Sirona occupies a position exemplifying social media-driven direct-to-consumer conversion in emerging market tier-one cities. On the K-beauty and organic substrate vector, Rael represents the archetype of certified-organic positioning targeting ingredient-transparency-motivated demographics.
| Leading Market Players |
|---|
| Procter & Gamble |
| BeYou |
| Rael |
| Cora |
| The Good Patch |
| Sirona |
| TheraPatch |
| Patchology |
| Livia |
| Others |
Value Network & Pricing Analysis
Chinese hydrogel substrate manufacturers supply 60-70 percent of precision coating lines to period patch formulators, concentrating margin capture upstream while brand holders downstream compete on subscription lifetime value and certification tier positioning.
Pricing Analysis
Cost-plus contracts with cannabidiol and herbal extract indexation dominate active-ingredient procurement, exposing formulators to agricultural yield volatility. Three-tier pricing structure across premium organic certification, standard transdermal efficacy, and economy heat-patch tiers separates GOTS-certified substrates from synthetic alternatives. Cost compression in standard heat-patch tiers is intensifying because iron powder oxidation chemistry faces commodity input pressure. Teenage trial segments through pharmacy channels exhibit highest price sensitivity, while adult subscription segments in metropolitan United States markets tolerate premium positioning.
Supply Chain Analysis
Export-control regimes limiting micro-needle array technology flows from South Korea and Japan constrain advanced delivery platform access for non-Asian manufacturers. Active pharmaceutical ingredient concentration centers on India and China for herbal extracts, with German and Japanese suppliers dominating precision membrane substrates. Formulation rests on cannabidiol agricultural supply, hydrogel polymer feedstocks, and certified organic cotton substrates. Single-source vulnerability runs through Chinese coating equipment manufacturers. Distribution runs through direct-to-consumer platforms capturing full margin, pharmacy chains demanding slotting fees, and specialty retailers extracting premium positioning rents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Period patch economics increasingly favor service-attach models where automated subscription replenishment algorithms generate recurring revenue expanding faster than one-time hardware margins.
For Market Incumbents: Pre-empt digital-native challengers by acquiring direct-to-consumer subscription infrastructure in India's tier-one cities before Sirona consolidates Instagram and TikTok conversion dominance. Backward integration into GOTS-certified organic cotton substrate production defends margin pools as REACH chemical safety standards tighten. FDA 510(k) clearance investment creates regulatory moats against cosmetic wellness device competitors seeking drug-claim positioning. For New Entrants and Emerging Players: Establish a beachhead in teenage pharmacy channel segments where parental purchase influence and lower brand loyalty enable rapid trial conversion. India's tier-one cities offer the most penetrable geography given minimal retail infrastructure requirements and social media-native marketing efficiency. Position through K-beauty adjacent specialty retailers in Seoul and Los Angeles targeting Asian-American millennial ingredient transparency demands. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital-native subscription specialists possessing automated replenishment algorithms but lacking transdermal formulation expertise. Five-to-ten year viability hinges on regulatory classification boundaries between cosmetic wellness and medical devices hardening in favor of clinically validated platforms. Watch FDA 510(k) clearance timelines for micro-needle array technologies as inflection indicator for premium positioning consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Validation Investment | European manufacturers accelerating documentation infrastructure capture premium positioning as reclassification tightens. |
| Direct-to-Consumer Subscription Launch | Digital-native brands in Mumbai and Delhi bypass pharmacy margin compression through Instagram conversion funnels. |
| GOTS-Certified Substrate Backward Integration | Organic cotton certification control defends strongest margin pools against REACH chemical safety standard compliance costs. |
| Micro-Needle Array Platform Development | South Korean technology licensing enables faster onset claims among K-beauty positioned Asian-American millennial segments. |
| Pharmacy Chain Shelf Positioning | CVS and Walgreens analgesic-aisle placement sustains impulse discovery against supermarket price competition. |
Research Methodology
Operator-level perspectives from transdermal formulation chemists, GOTS certification auditors, pharmacy category buyers, and direct-to-consumer subscription platform operators anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, REACH chemical safety registration data, and social media engagement analytics. Bottom-up patch volume estimates triangulated against top-down menstrual wellness spending data across the analysis window.
Scenario-bracketing across regulatory classification uncertainty, cannabidiol supply volatility, and subscription churn rate variation shaped the analytical framework. Segmentation dimensions modeled include product type tier, delivery mechanism technology, end-user demographic, and distribution channel economics. CAGRs derived from fitted growth curves applied to validated base-year estimates, with transdermal flux rate efficacy thresholds and organic certification penetration rates serving as industry-specific forecast inputs.
Stress conditions across EU MDR documentation timeline extensions, herbal extract agricultural yield shortfalls, and TikTok advertising cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway stability and direct-to-consumer channel share trajectories. Material shifts in FDA classification boundaries between cosmetic wellness and medical devices would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market