
 Dry Cleaning Solvent for Clothes Market | 2026-2036
Dry Cleaning Solvent for Clothes Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Cleaning Solvent for Clothes Market Insights
Commercial laundry chains is consolidating procurement volumes across metropolitan markets. Dow Chemical leverages its integrated chlor-alkali platform to sustain feedstock cost advantages in perchloroethylene production. SEITZ GmbH Chemische Fabrik anchors its position through specialized solvent formulations tailored to European textile care standards. Chevron Phillips Chemical Company competes on hydrocarbon solvent purity grades for machine-based cleaning systems.
Dry cleaning solvent for clothes comprises volatile organic compounds formulated to dissolve oils, greases, and particulate soils from fabrics without water immersion, with perchloroethylene historically dominating due to its low flammability and high solvency power around 121 degrees Celsius boiling point. The solvent type dimension shows perchloroethylene retaining volume leadership in legacy installations while green solvents capture fastest growth as regulatory pressure intensifies. Application method segmentation reveals machine-based cleaning as the mature margin pool, whereas spot cleaning formulations command premium positioning in residential and on-premise textile care channels.
The EPA regulates perchloroethylene emissions under the National Emission Standards for Hazardous Air Pollutants, while the EU REACH framework restricts chlorinated solvent classifications and the EU F-Gas Regulation shapes alternative solvent approval pathways. ECHA's substance evaluation protocols force reformulation investments that favor hydrocarbon and silicone-based chemistry migrations. Stakeholders must monitor regulatory amendment timelines to time capital redeployment between solvent chemistries and cleaning equipment platforms.
Market Dynamics
The EPA's phased perchloroethylene emission restrictions are forcing wholesale solvent chemistry migration across installed machine bases, with capital redeployment timing now dictating competitive survival rather than operational efficiency alone.
Growth Catalysts
- Machine replacement cycles:Legacy perchloroethylene equipment in Germany, Japan, and the United States is reaching end-of-life, triggering solvent procurement decisions that favor hydrocarbon and silicone alternatives.
- REACH substance evaluations:ECHA's reformulation mandates under EU chemical classification protocols are accelerating hydrocarbon chemistry investments among European textile care operators.
- Urban garment care clustering:Metropolitan dry cleaning density in Tokyo, New York, and Frankfurt is consolidating procurement volumes and standardizing solvent specifications across multi-site operators.
Market Restraints
- Feedstock cost volatility:Chlor-alkali platform economics tie perchloroethylene margins to chlorine and caustic soda price swings that resist hedging.
- Equipment capital intensity:Hydrocarbon and silicone solvent machines require fire suppression systems and modified distillation units that triple installation costs versus legacy perchloroethylene equivalents.
- Technical solvency gaps:Green alternatives lack the 121-degree Celsius boiling point efficiency for heavy grease removal that perchloroethylene delivers.
Strategic Opportunities
- Spot cleaning formulations:Residential and on-premise textile care channels command premium positioning for portable solvent products outside machine-based infrastructure.
- EU F-Gas Regulation pathways:Alternative solvent approval frameworks are opening accelerated certification timelines for silicone-based chemistry entrants.
- Commercial laundry consolidation:Multi-site procurement standardization creates volume anchor contracts for solvent suppliers with formulation flexibility.
Industry Challenges
- Reformulation timeline compression:ECHA substance evaluation deadlines force simultaneous R&D and regulatory submission investments that strain mid-size chemical producers.
- Legacy equipment integration:Hydrocarbon solvent retrofits into existing perchloroethylene machines require distillation column modifications and solvent recovery system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Cleaning Solvent for Clothes Market |
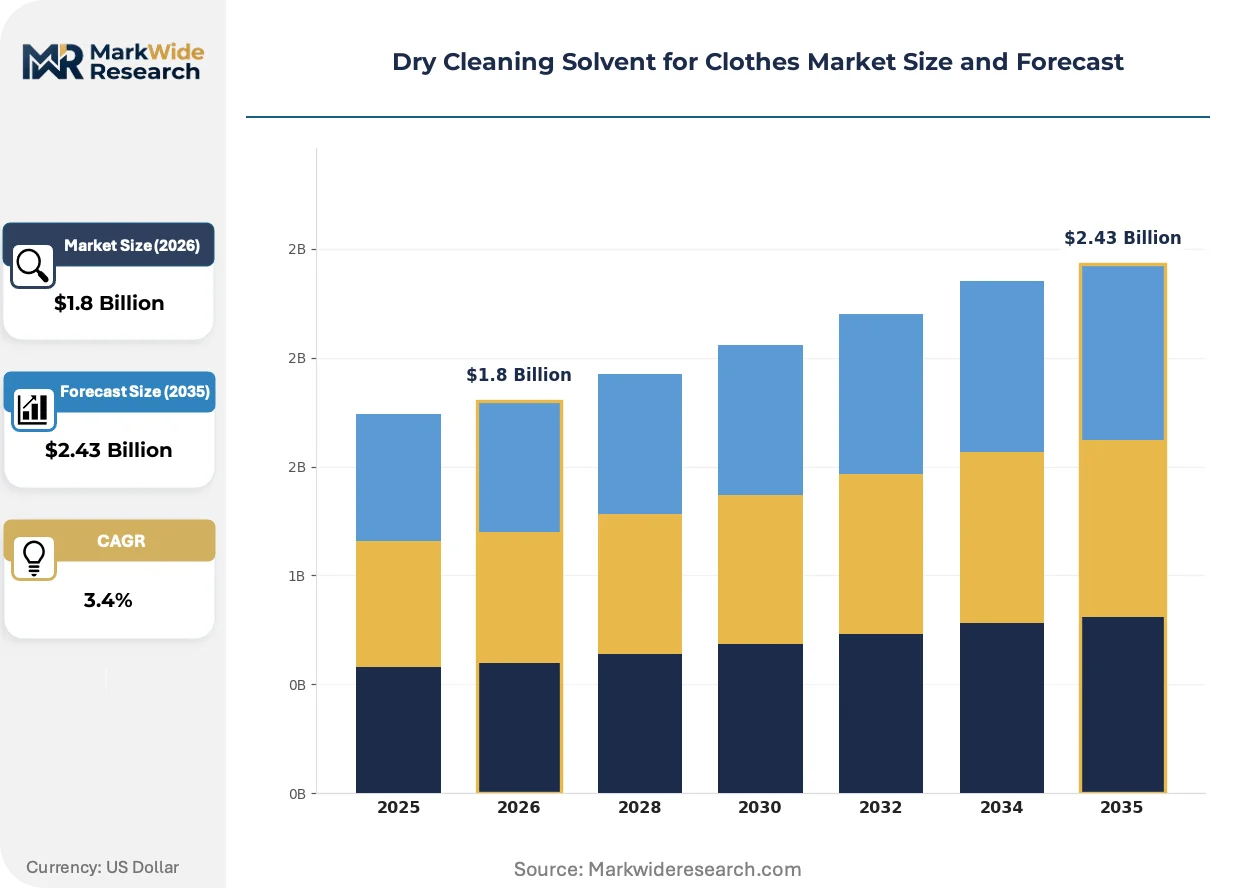
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solvent Type: Perchloroethylene, Hydrocarbon Solvent, Green Solvent, Others Application Method: Machine-Based, Hand-Wash, Spot Cleaning, Others End User: Commercial Laundry, Residential Users, Textile Cleaners, Others Packaging Type: Drum, Bottle, Bulk Container, Bag |
| Companies Covered | Dow Chemical, Occidental Chemical, Chevron Phillips Chemical Company, Shell Chemical Company, Caled Chemical, SEITZ GmbH Chemische Fabrik, Ineos Chlor Americas, Tech Chem, GreenEarth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Cleaning Solvent for Clothes Market Trends and Innovations
Closed-loop solvent recovery systems are displacing open-batch operations as the dominant technical architecture, with machine design now prioritizing emission containment over throughput maximization.
Silicone-based decamethylcyclopentasiloxane (D5) formulations are modularizing machine-based cleaning infrastructure by enabling lower-temperature distillation cycles that reduce energy consumption. Metropolitan commercial laundries in Germany are piloting these systems to preempt REACH compliance deadlines. The technology is modularizing supplier relationships as equipment OEMs and solvent producers form captive partnerships around integrated platform offerings.
EPA National Emission Standards for Hazardous Air Pollutants amendments are tightening perchloroethylene exposure limits for dry cleaning workers and adjacent residential zones. The industrial consequence is accelerated machine retirement timelines that compress the replacement window from ten years to five. Small independent operators in the United States are responding through cooperative purchasing agreements that aggregate procurement volumes for hydrocarbon system conversions.
Buyer concentration among commercial laundry chains is compressing supplier negotiation cycles and unbundling after-sales solvent replenishment from equipment purchase contracts. Volume-based pricing agreements are displacing spot procurement in metropolitan garment care clusters. This pattern is most visible across Japan's Kanto region, where multi-site operators now centralize solvent specification decisions at headquarters level rather than granting local autonomy.
Dry Cleaning Solvent for Clothes Market Segmentation
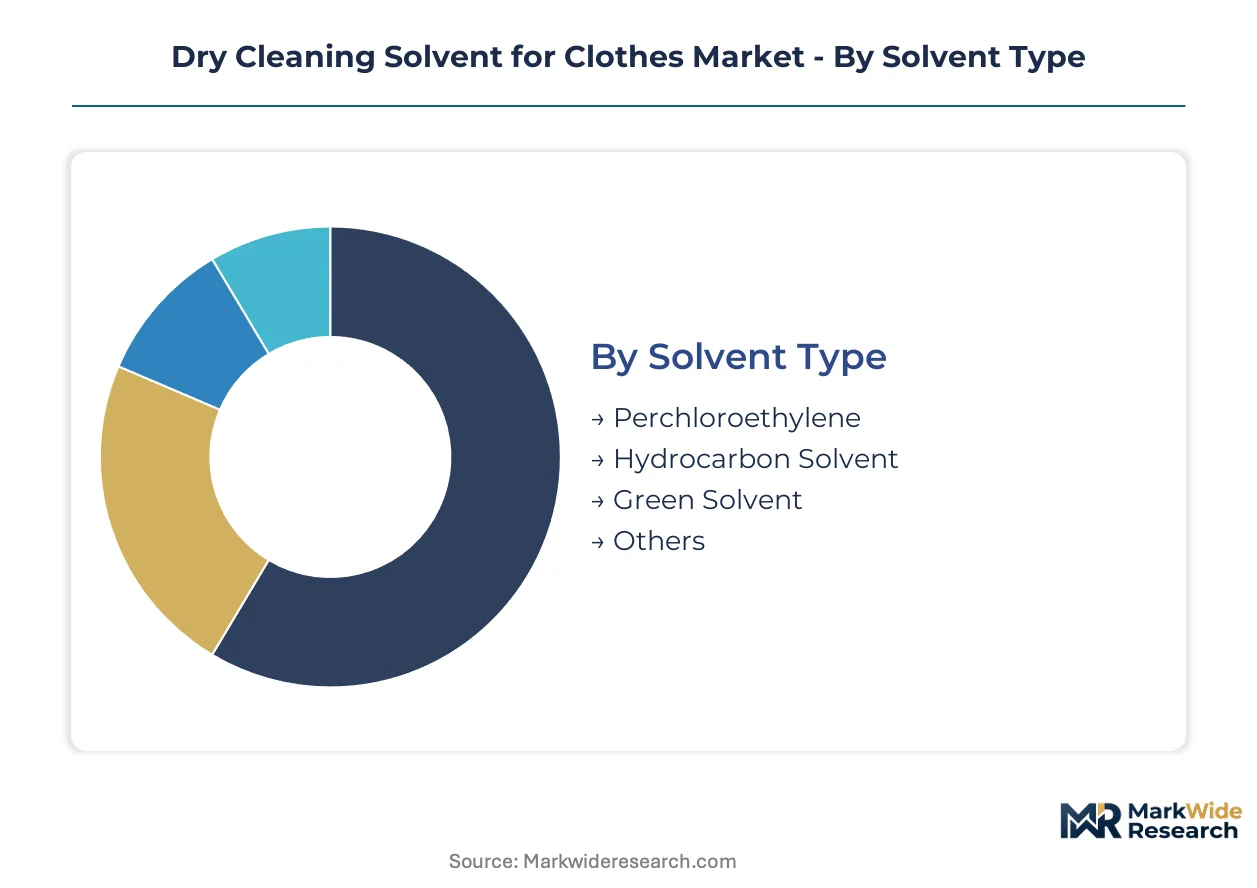
Dry cleaning solvent procurement decisions diverge sharply across user types and regulatory exposure zones. Solvent chemistry approvals, equipment compatibility, and end-use concentration patterns create distinct segment economics that suppliers must navigate separately.
Solvent Type:
EPA National Emission Standards for Hazardous Air Pollutants governs perchloroethylene classifications, while EU REACH substance evaluations drive hydrocarbon and silicone chemistry certifications.
- Perchloroethylene:Chlorinated hydrocarbon with 121 degrees Celsius boiling point delivers unmatched grease solvency for heavy soil removal. Commercial laundries in Japan and the United States retain this chemistry in legacy machine installations despite tightening exposure limits.
- Hydrocarbon Solvent:Petroleum-derived formulations with higher flash points require fire suppression systems but satisfy EPA and ECHA emission thresholds. German textile care operators are migrating to these solvents ahead of REACH compliance deadlines.
- Green Solvent:Bio-based and silicone formulations including decamethylcyclopentasiloxane (D5) target low-temperature distillation cycles.
- Others:Glycol ether and modified alcohol blends serve niche spot cleaning applications outside machine infrastructure.
Perchloroethylene sits at the top of the volume ranking, with green solvent climbing the fastest.
Application Method:
Capital intensity and throughput requirements separate machine-based infrastructure from portable formulations.
- Machine-Based:Closed-loop distillation systems dominate commercial throughput, with solvent recovery rates now prioritized over speed. Metropolitan laundry chains in Frankfurt and Tokyo standardize on this method for multi-site procurement.
- Spot Cleaning:Aerosol and pump-spray formulations command premium positioning in residential and on-premise textile care channels where equipment investment is prohibitive.
- Hand-Wash:Small-batch immersion methods persist in artisanal garment care settings with specialized fabric handling.
- Others:Ultrasonic and immersion technologies serve technical textile applications outside mainstream dry cleaning.
Machine-based cleaning holds the largest installed base, while spot cleaning gains share fastest in premium residential segments.
End User:
Procurement scale and specification authority concentrate differently across customer types.
- Commercial Laundry:Multi-site operators in urban garment care clusters centralize solvent decisions at headquarters level, aggregating volume for hydrocarbon system conversions. Kanto region chains exemplify this consolidation pattern.
- Textile Cleaners:Specialized operators handling delicate fabrics and couture garments require solvent flexibility for fiber-specific treatments.
- Residential Users:Spot cleaning products serve this dispersed segment through retail and direct channels with minimal technical support.
- Others:Institutional users including hotels and hospitals operate captive facilities with standardized procurement.
Commercial laundry anchors procurement volumes, with textile cleaners expanding most quickly in premium service tiers.
Packaging Type:
Logistics economics and handling safety requirements shape container specifications across the value chain.
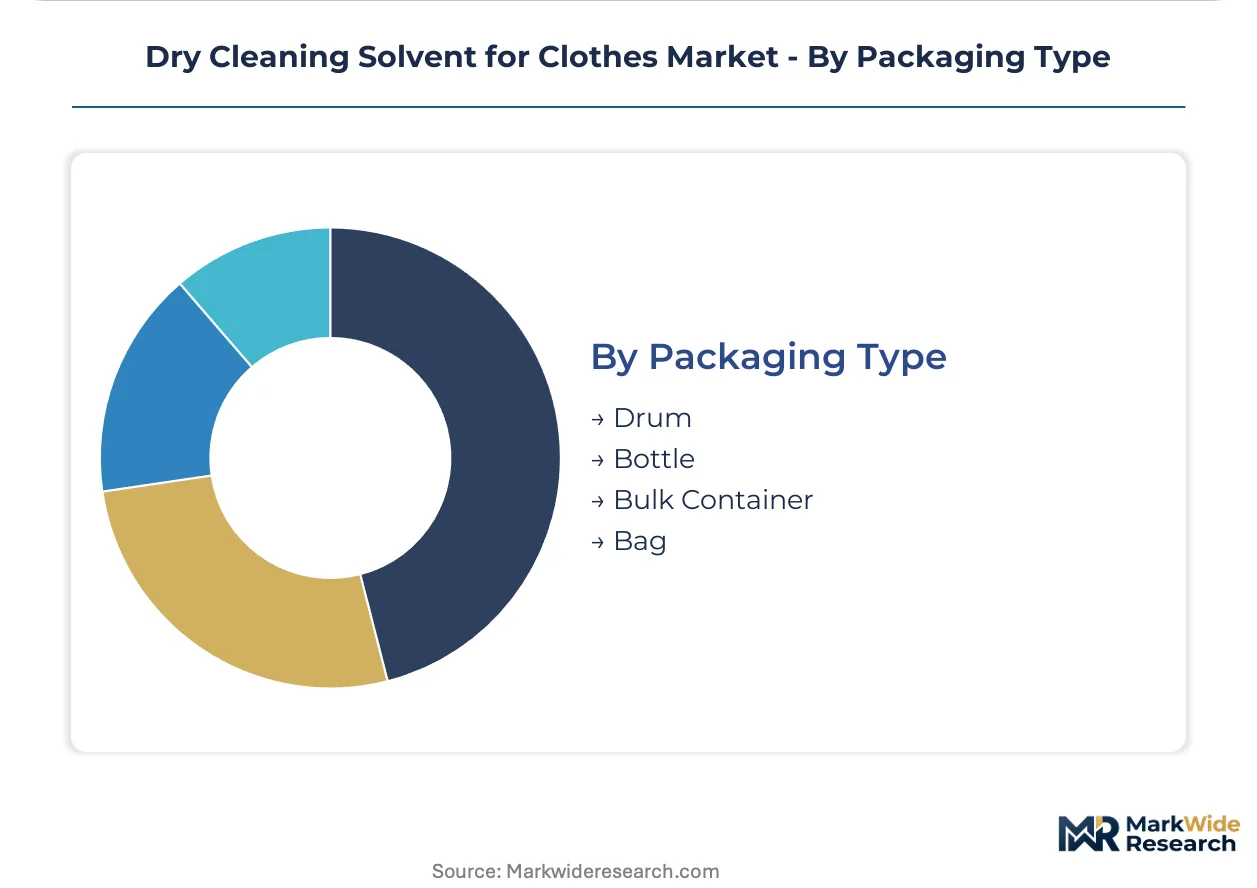
- Drum:Steel and polyethylene drums dominate commercial replenishment cycles, with UN certification required for hydrocarbon solvent transport. German distributors favor this format for metropolitan route delivery.
- Bulk Container:Intermediate bulk containers and tanker deliveries serve high-volume laundry chains with dedicated storage infrastructure, compressing per-unit logistics costs.
- Bottle:Retail-format containers target residential spot cleaning applications with child-resistant closures and labeling compliance.
- Bag:Flexible intermediate bulk containers serve limited niche applications in textile processing facilities.
Drum packaging leads commercial shipments, with bulk container adoption rising fastest among consolidating laundry chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan garment care clusters in Tokyo, New York, and Frankfurt drive procurement concentration for dry cleaning solvents. Regulatory pressure from EPA and ECHA is compressing replacement timelines across these urban markets. Capital redeployment now favors hydrocarbon and silicone chemistry conversions.
United States
Commercial laundry chains in the New York metropolitan area are consolidating solvent procurement volumes ahead of EPA National Emission Standards for Hazardous Air Pollutants deadlines. The phased perchloroethylene restrictions are forcing five-year machine replacement cycles versus historical ten-year horizons. Small independent operators in urban garment care clusters are forming cooperative purchasing agreements to aggregate conversion capital.
Germany
Textile care operators across the Frankfurt-Rhine-Main region are migrating to hydrocarbon solvents ahead of ECHA REACH substance evaluation deadlines. The EU F-Gas Regulation is opening accelerated certification pathways for silicone-based chemistry entrants. SEITZ GmbH Chemische Fabrik anchors specialized solvent formulation supply from its base in the Stuttgart industrial corridor.
Japan
Kanto region multi-site operators now centralize solvent specification decisions at headquarters level rather than granting local outlet autonomy. METI chemical handling standards shape equipment certification requirements for hydrocarbon system installations. Tokyo's dense metropolitan dry cleaning infrastructure is standardizing on closed-loop solvent recovery architectures.
China
Urban garment care clusters in Shanghai and Beijing are expanding solvent procurement as post-pandemic garment care volumes rebound. MEE air quality standards are beginning to constrain chlorinated solvent emissions in coastal manufacturing zones. Dow Chemical leverages integrated chlor-alkali platform economics to sustain feedstock cost advantages for perchloroethylene production serving Asian markets.
Dry Cleaning Solvent for Clothes Market Competitive Landscape
Capacity expansion dominates the current landscape as solvent suppliers position for hydrocarbon and silicone chemistry migrations. The vendor base organizes around three tiers: integrated petrochemical majors with chlor-alkali platforms, European specialty chemical formulators with REACH certification expertise, and regional distributors with metropolitan route density. Strategic archetypes include feedstock-integrated producers, regulatory compliance specialists, and logistics-anchored distributors. M&A activity and captive equipment-solvent partnerships represent the dominant competitive vectors reshaping supplier relationships.
Among integrated petrochemical majors, Dow Chemical and Chevron Phillips Chemical Company exemplify the feedstock-integrated archetype with chlor-alkali and hydrocarbon purification capabilities respectively. SEITZ GmbH Chemische Fabrik represents the European specialty formulator tier with REACH-aligned certification infrastructure. These three anchors illustrate how competitive positioning now depends on regulatory timing alignment rather than solvency performance alone.
| Leading Market Players |
|---|
| Dow Chemical |
| Occidental Chemical |
| Chevron Phillips Chemical Company |
| Shell Chemical Company |
| Caled Chemical |
| SEITZ GmbH Chemische Fabrik |
| Ineos Chlor Americas |
| Tech Chem |
| GreenEarth |
| Others |
Pricing and Supply Chain Analysis
Specialized solvent formulation chemists concentrated in Germany's Stuttgart industrial corridor anchor labor-cost differentials that widen pricing spreads between REACH-certified premium grades and commodity hydrocarbon alternatives. EPA compliance investments in the United States compress margins for perchloroethylene producers while Japanese METI-certified silicone formulations command sustained premiums.
Pricing Analysis
Input-cost pass-through from chlor-alkali platform economics governs perchloroethylene contract structures, with Dow Chemical's integrated feedstock position enabling sharper spot-market responses than merchant producers. Three-tier pricing structure across premium silicone, standard hydrocarbon, and economy perchloroethylene levels reflects certification grade and volume scale differentiation. Pricing pressure stems from ECHA reformulation deadlines forcing simultaneous R&D and regulatory submission investments. Commercial laundry chains exhibit lowest price sensitivity due to consolidated procurement volumes, while independent operators in urban garment care clusters face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with chlor-alkali platform operators in the United States and China for perchloroethylene feedstock, with German specialty formulators anchoring European hydrocarbon solvent supply. Raw material dependencies include chlorine gas, caustic soda, and petroleum distillate fractions. Regulatory restriction risk concentrates in REACH substance evaluation timelines that compress reformulation windows. Distribution runs through drum-based metropolitan route delivery for commercial laundries, with bulk container adoption rising among consolidating multi-site operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA emission restrictions in the United States accelerate capital redeployment toward ECHA-aligned European formulations, exploiting regulatory timing differentials between jurisdictions.
For Market Incumbents: Cement feedstock-integrated positions through captive chlor-alkali capacity additions in Gulf Coast production corridors. Defend against silicone chemistry substitution by accelerating hydrocarbon solvent purity investments ahead of EU F-Gas Regulation certification deadlines. Prioritize after-sales solvent replenishment contracts to unbundle from equipment purchase negotiations.
For New Entrants and Emerging Players: Silicone-based decamethylcyclopentasiloxane modularization technology offers a technology-first wedge into metropolitan German textile care clusters ahead of REACH compliance deadlines. Target spot cleaning formulations for residential channels where equipment investment barriers exclude incumbent machine-based suppliers. Pursue cooperative purchasing agreement partnerships with small independent operators to aggregate conversion capital.
For Investors and Strategic Acquirers: Integrated petrochemical majors are the most active acquirer in this space, seeking REACH certification infrastructure to accelerate hydrocarbon chemistry migrations. Long-term viability hinges on regulatory timing alignment rather than solvency performance alone. Monitor ECHA substance evaluation amendment timelines as the critical inflection signal for capital redeployment between solvent chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Dow Chemical's captive chlorine supply secures cost advantages against merchant perchloroethylene producers. |
| REACH Certification Infrastructure Investment | SEITZ GmbH's specialized formulation capabilities anchor European hydrocarbon solvent approval pathways. |
| Silicone Chemistry Joint Venture | Equipment OEMs and solvent producers form captive partnerships around integrated D5 platform offerings. |
| Cooperative Purchasing Agreement Formation | Small independent operators in New York aggregate conversion capital for hydrocarbon system replacements. |
| Spot Cleaning Formulation Launch | Premium residential channels command portable solvent products outside machine-based infrastructure constraints. |
Research Methodology
Multiple input streams — primary interviews with solvent plant managers, commercial laundry procurement leads, and textile care technical directors, alongside secondary validation through EPA emission filings, ECHA substance evaluation databases, and customs trade records — were reconciled through bottom-up and top-down triangulation. The analysis combined field-level intelligence from equipment OEMs and distribution channel partners with regulatory documentation and industry association reports.
Data-stream reconciliation across solvent type, application method, end user category, and packaging format dimensions generated volume and value outputs throughout the forecast period. CAGRs were derived from equipment replacement cycle modeling and regulatory deadline impact assessment. Forecast inputs incorporated METI chemical handling standards, EU F-Gas Regulation amendment timelines, and metropolitan garment care cluster density metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA evaluation deadline shifts, chlor-alkali feedstock price volatility, and silicone chemistry certification pathway accelerations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market