
 Dye Sublimation Printing Market | 2026-2036
Dye Sublimation Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Dye Sublimation Printing Market Analysis
Modular printer configurations is decoupling hardware from ink supply commitments, forcing buyers to evaluate total cost per print rather than upfront equipment price. Seiko Epson Corporation leverages its MicroPiezo printhead ecosystem to lock in recurring ink revenue streams. Mimaki Engineering Co., Ltd. anchors its competitive stance through deep specialization in wide-format textile systems with integrated color management. HP Inc. competes by extending cloud-based workflow software that reduces operator training burdens in commercial print shops.
Dye sublimation printing transfers solid dye particles onto polyester substrates through controlled heat and pressure, typically operating at 175-230°C to achieve gas-phase bonding without liquid intermediate stages. The process delivers permanent, full-bleed color saturation for fabrics, rigid panels, and promotional goods requiring wash-fast, scratch-resistant finishes. Printers and ink categories command the dominant share of equipment spending, while transfer films represent the fastest-expanding segment as thin-film coating technologies improve yield rates. Digital printing technology leads in unit installations, though continuous feed systems capture disproportionate margin pools in high-volume textile manufacturing.
EPA oversight of volatile organic compound emissions shapes ink formulation requirements in the United States, while REACH chemical restrictions in Europe constrain certain disperse dye chemistries. China's MEE enforces wastewater discharge standards that affect dye sublimation wastewater treatment investments in concentrated production zones. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations that threaten water-repellent finishing chemistries commonly paired with dye sublimated textiles.
Market Dynamics
Modular printer architectures are decoupling hardware from ink supply commitments, forcing buyers to evaluate total cost per print rather than upfront equipment price and reshaping vendor revenue models toward recurring consumables.
Growth Catalysts
- On-demand production models:Sports apparel brands are expanding short-run manufacturing capabilities, eliminating minimum order quantity constraints and reducing finished goods inventory exposure.
- REACH chemical compliance:Europe's tightening ink formulation requirements are accelerating R&D investment in compliant disperse dye chemistries, creating first-mover advantages for certified suppliers.
- Zhejiang manufacturing corridor:China's concentrated textile production infrastructure enables integrated dye sublimation workflows from fabric preparation through finishing.
Market Restraints
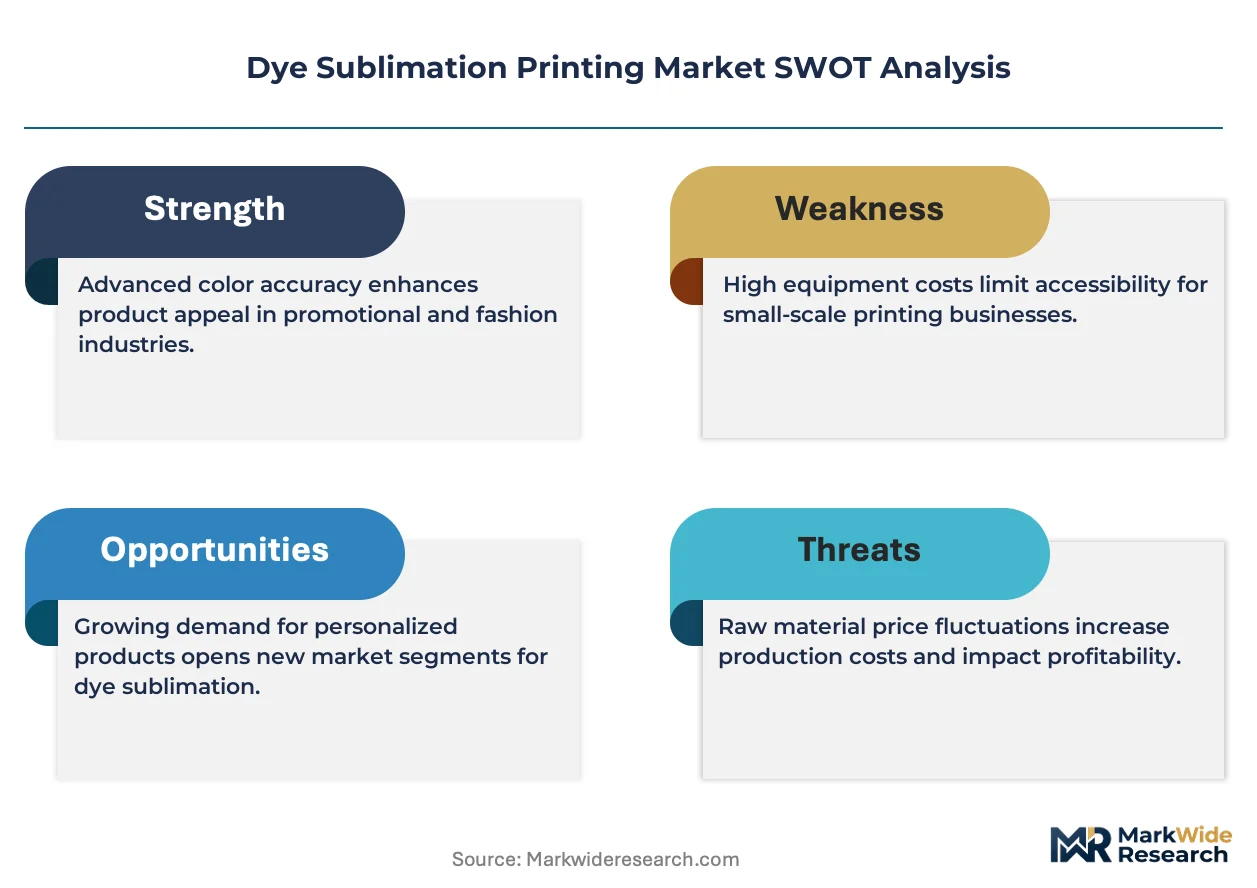
- PET substrate cost volatility:Polyester price swings tied to crude oil derivatives compress margin predictability for print service providers locked into fixed-price contracts.
- Printhead supply concentration:Precision piezoelectric components depend on a limited supplier base concentrated in Japan and Germany, creating procurement bottlenecks during demand surges.
- Water-repellent finishing restrictions:Evolving PFAS regulations threaten chemistries commonly paired with dye sublimated textiles, forcing reformulation investments.
Strategic Opportunities
- India textile digitization:The country's PLI scheme incentives for technical textiles create entry points for dye sublimation equipment in underpenetrated garment manufacturing clusters.
- Cloud workflow convergence:Integration of color management software with enterprise resource planning systems enables remote job routing and reduces operator skill barriers.
- Transfer film innovation:Thin-film coating technology improvements are expanding yield rates and opening rigid substrate applications beyond traditional fabric markets.
Industry Challenges
- Colorimetric expertise scarcity:Qualified operators capable of ICC profile management and substrate-specific calibration remain difficult to recruit in commercial print shops.
- Legacy screen printing integration:Hybrid workflows combining digital and analog methods require capital-intensive workflow software and create production scheduling complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dye Sublimation Printing Market |
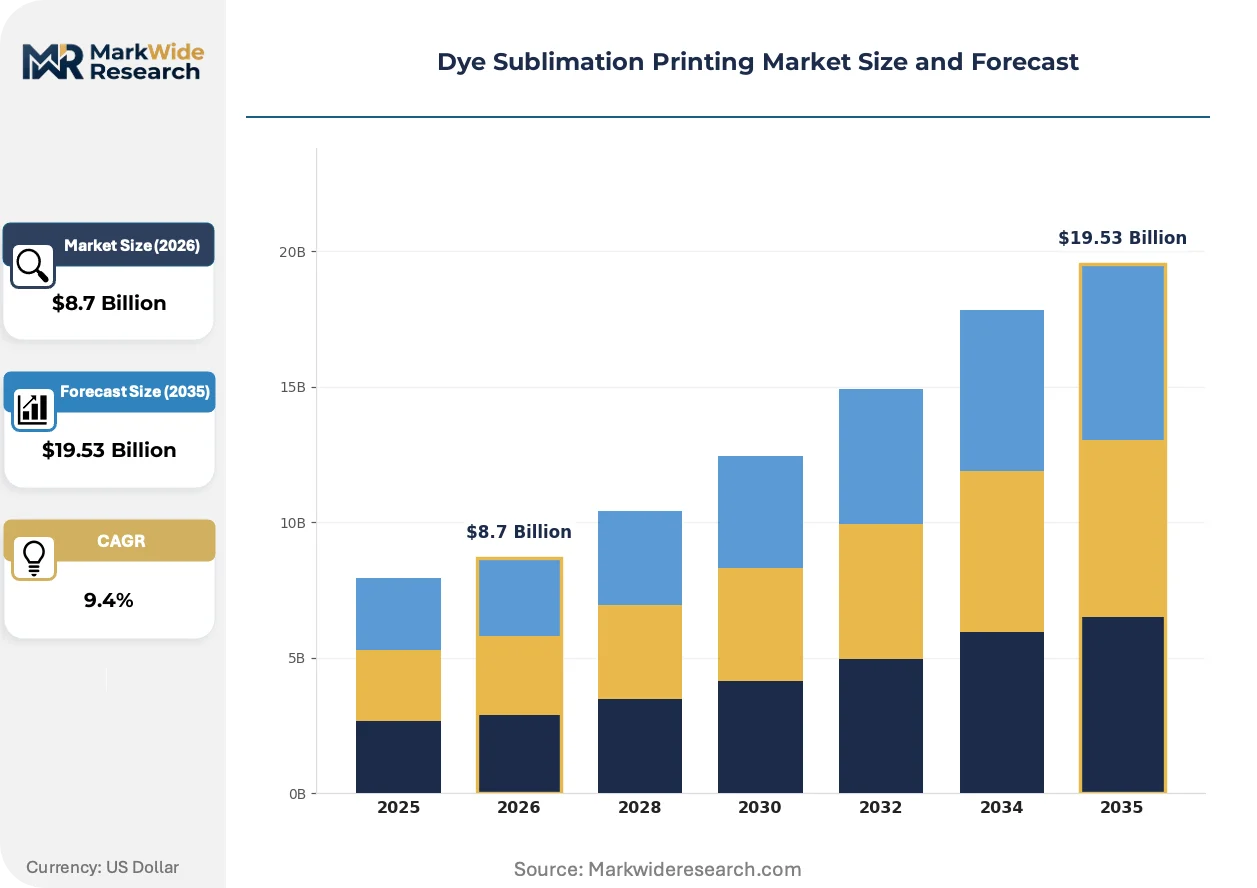
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Transfer Paper, Ink, Printers, Transfer Films Application: Textiles, Promotional Materials, Apparel, Home Décor End User: Retailers, Manufacturers, E-commerce, Print Shops Technology: Digital Printing, Wide Format Printing, Continuous Feed, Single-Use |
| Companies Covered | Mimaki Engineering Co., Ltd., Seiko Epson Corporation, Sinotec Digital Co., Ltd., Fujifilm Holdings Corporation, Roland DG Corporation, ColorJet India Limited, Canon Inc., HP Inc., MeiTu Digital Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dye Sublimation Printing Market Emerging Trajectories
Digital workflow integration is compressing pre-press timelines and enabling same-day production cycles that analog methods cannot match, fundamentally altering how print buyers evaluate supplier capabilities.
Single-pass inkjet arrays are absorbing wide-format textile production volumes previously dominated by rotary screen equipment. Large-format soft signage manufacturers in Germany and the United States are adopting these systems at accelerating rates. The technology is absorbing margin pools in high-volume polyester flag and banner applications by reducing labor content per square meter.
REACH authorization requirements for disperse dyes containing certain aromatic amines are forcing reformulation of legacy ink portfolios. European textile finishers face compliance deadlines that compress qualification timelines for new chemical suppliers. The sportswear segment is responding fastest, with brands mandating certified ink chains from Zhejiang suppliers.
Short-run procurement patterns are fragmenting order volumes across more print service providers, weakening volume-based pricing leverage for large buyers. Brand licensors and promotional product distributors are disintermediating traditional wholesale channels by connecting directly with regional print shops. This behavioral shift is most visible in North American custom apparel markets where e-commerce platforms aggregate micro-orders for same-day fulfillment.
Dye Sublimation Printing Market Segmentation
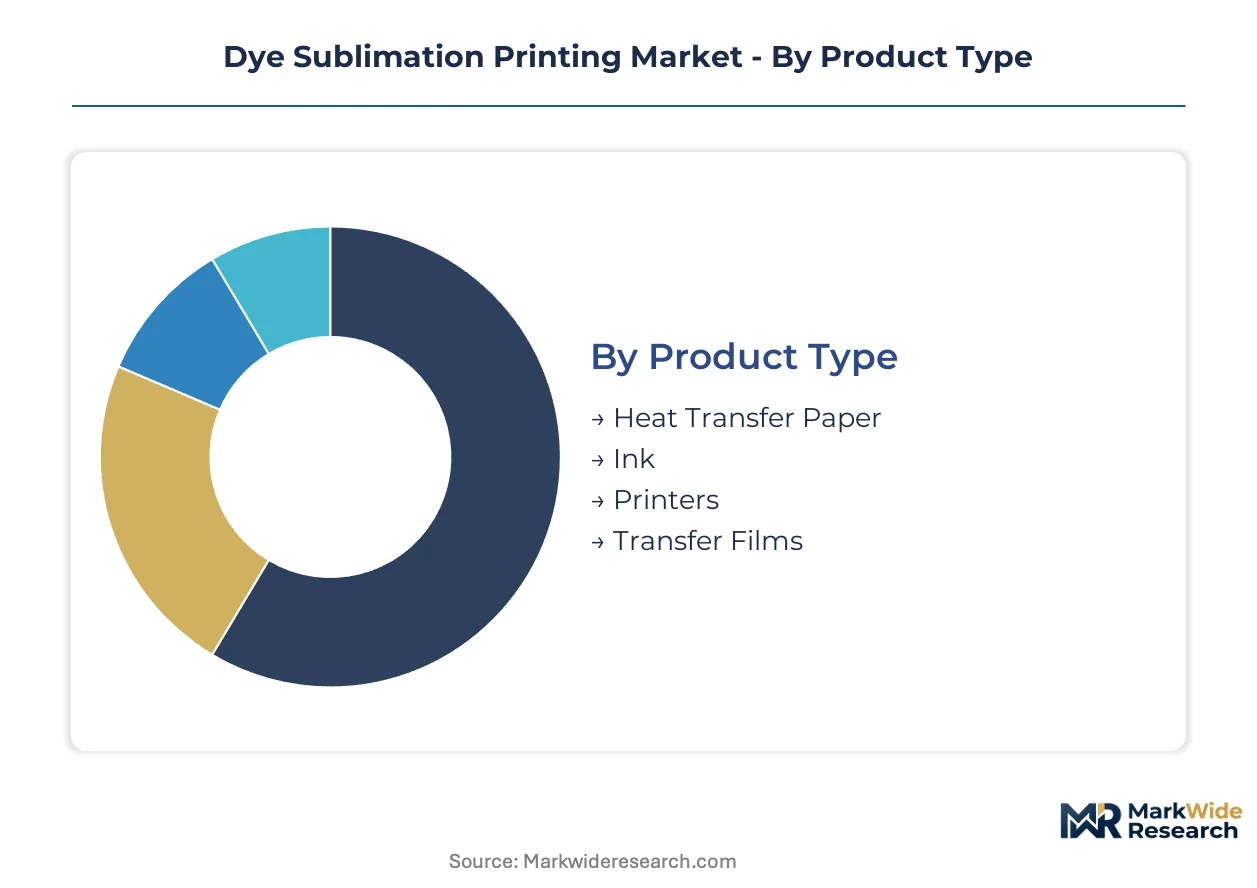
Dye sublimation printing segments fragment across equipment configuration, substrate compatibility, and buyer operational scale. Each category demands distinct procurement criteria, from total cost-per-print economics for high-volume textile manufacturers to upfront capital constraints facing commercial print shops.
Product Type:
Buyers in this category differentiate primarily by recurring consumables spend versus capital equipment outlay, with print service providers prioritizing ink yield rates and equipment buyers fixating on printhead durability warranties.
- Printers:Hardware configurations span desktop units for promotional goods through industrial continuous-feed systems for textile roll-to-roll production. Demand concentrates in China's Zhejiang corridor where integrated fabric-to-finish workflows require synchronized equipment procurement.
- Ink:Water-based disperse dye formulations dominate polyester applications, with viscosity and particle size distribution determining gas-phase transfer efficiency at 175-230°C bonding temperatures. REACH-compliant chemistries from certified European suppliers command procurement priority as regulatory deadlines compress qualification timelines.
- Heat Transfer Paper:Coated substrates with controlled release layers enable clean dye separation during thermal transfer cycles.
- Transfer Films:Thin-film coating improvements are expanding yield rates and opening rigid panel applications beyond traditional fabric markets.
Printers lead volumes today; transfer films are gaining share fastest.
Application:
Application selection tracks end-use durability requirements and wash-fastness specifications, with apparel buyers demanding certified colorfastness ratings that promotional material buyers rarely specify.
- Apparel:Sports and activewear segments drive premium disperse dye consumption for polyester-rich fabrics requiring abrasion resistance and repeated thermal cycling. On-demand production models from brands like Nike and Adidas are eliminating minimum order quantity constraints across North American and European supply chains.
- Textiles:Soft signage and interior fabric applications absorb wide-format production capacity, with flag and banner manufacturers in Germany adopting single-pass inkjet arrays previously dominated by rotary screen equipment.
- Promotional Materials:Mugs, phone cases, and rigid substrates utilize hard-surface transfer films with lower barrier-to-entry equipment requirements.
- Home Décor:Cushion covers and drapery panels demand larger repeat patterns and color consistency across extended print runs.
Textiles lead volumes today; apparel is climbing the fastest.
End User:
End-user procurement behavior splits between inventory-risk-bearing manufacturers and asset-light intermediaries, with e-commerce platforms disintermediating traditional wholesale channels through direct regional print shop aggregation.
- Print Shops:Commercial service providers face acute colorimetric expertise scarcity, with ICC profile management and substrate-specific calibration capabilities difficult to recruit. Cloud-based workflow software from HP and competitors reduces operator training burdens and enables remote job routing.
- E-commerce:Platform aggregators connect brand licensors directly with regional fulfillment networks, fragmenting order volumes across more service providers and weakening volume-based pricing leverage for traditional distributors.
- Manufacturers:Vertically integrated textile producers in Zhejiang capture margin through captive dye sublimation finishing.
- Retailers:Custom apparel micro-orders for same-day fulfillment drive North American demand concentration.
Print shops lead volumes today; e-commerce is expanding most quickly.
Technology:
Technology adoption correlates with production volume thresholds and labor cost structures, with high-wage economies accelerating single-pass automation and developing markets retaining digital batch workflows.
- Digital Printing:Piezoelectric inkjet systems with MicroPiezo printhead architectures dominate unit installations, enabling variable data printing and short-run economics that analog methods cannot match. Seiko Epson's ecosystem locks in recurring ink revenue through proprietary cartridge designs.
- Continuous Feed:Roll-to-roll systems capture disproportionate margin pools in high-volume polyester manufacturing, with Japan- and Germany-sourced precision piezoelectric components creating supply concentration risks during demand surges.
- Wide Format Printing:Mimaki Engineering anchors competitive positioning through integrated color management specialization for textile applications.
- Single-Use:Disposable transfer media configurations serve promotional goods and event marketing with minimal capital requirements.
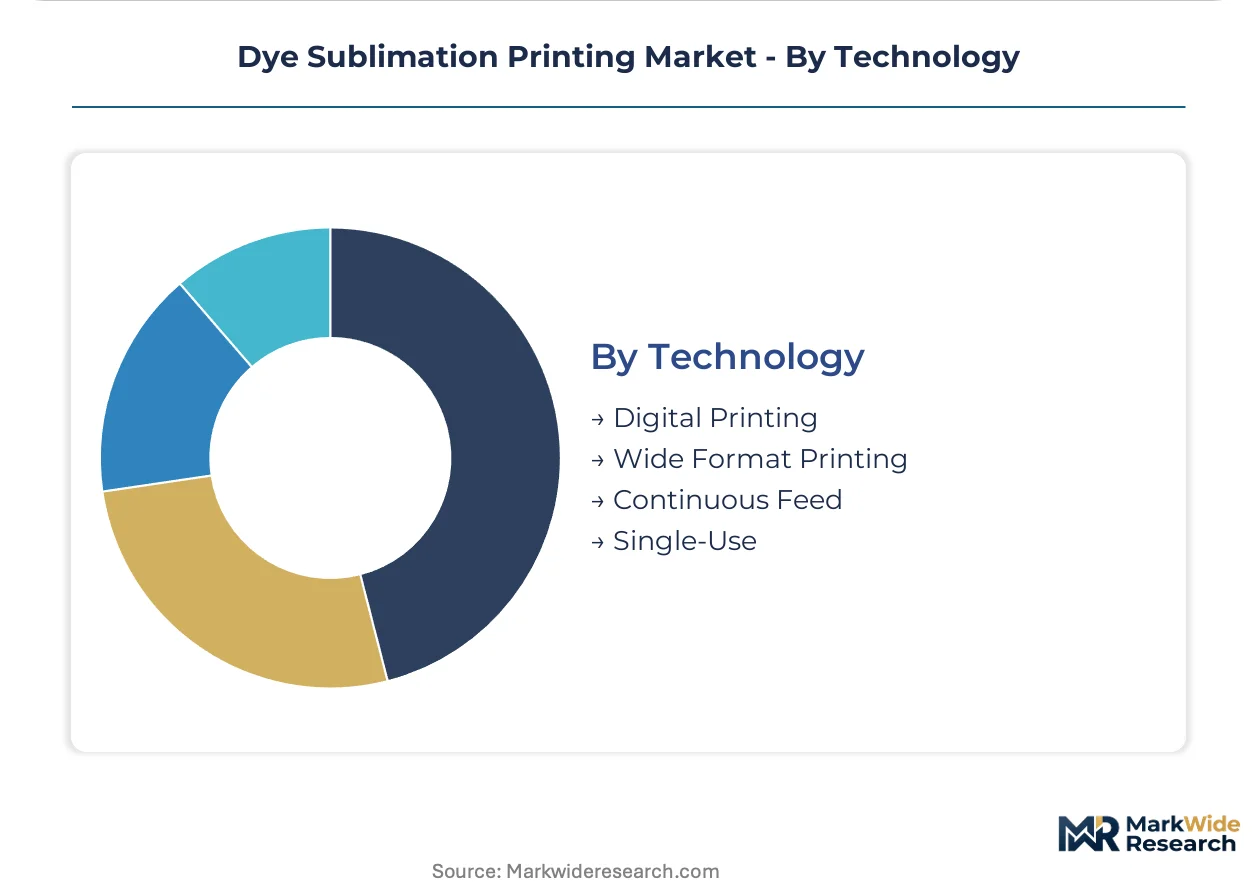
Digital printing leads volumes today; continuous feed is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dye sublimation printing originated in Japanese precision manufacturing during the 1980s, where thermal transfer technologies first achieved commercial viability for polyester textiles. The industry's geographic footprint now spans concentrated production corridors across three continents.
China
Zhejiang province hosts the world's densest cluster of integrated dye sublimation workflows, from fabric preparation through finishing. MEE wastewater discharge standards force treatment investments in Shaoxing and Jinhua manufacturing zones. Hangzhou-based equipment vendors supply continuous-feed systems to captive textile finishers.
United States
Custom apparel micro-orders drive demand concentration in North Carolina's textile corridor and Los Angeles basin print shops. EPA volatile organic compound regulations shape ink formulation requirements for domestic production. E-commerce aggregators in Texas and Florida connect brand licensors directly with regional fulfillment networks.
Germany
Large-format soft signage manufacturers in North Rhine-Westphalia adopt single-pass inkjet arrays for polyester flag production. ECHA REACH authorization requirements compress qualification timelines for compliant disperse dye suppliers. Stuttgart-area equipment distributors serve Central European technical textile finishers.
India
PLI scheme incentives for technical textiles create entry points in underpenetrated garment clusters across Maharashtra and Gujarat. BIS standards govern equipment safety certifications for imported printing systems. Tiruppur's knitwear manufacturers pilot dye sublimation finishing for polyester-rich activewear exports.
Japan
Precision piezoelectric printhead supply concentrates in Tokyo-Osaka manufacturing belts, creating procurement bottlenecks during demand surges. METI industrial policy supports next-generation thermal transfer R&D consortia. Kyoto-based component fabricators supply MicroPiezo architectures to global printer OEMs.
Dye Sublimation Printing Market Vendor Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive printhead technologies. Market concentration remains moderate, with tier-one players commanding premium pricing through proprietary consumables ecosystems while regional specialists compete on equipment flexibility. Three archetypes dominate: printhead-integrated conglomerates, wide-format textile specialists, and cloud-software-anchored workflow providers. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Among Japan-based diversified manufacturers, Seiko Epson Corporation and Mimaki Engineering Co., Ltd. exemplify contrasting strategic positions. Seiko Epson occupies the printhead-integrated archetype through its MicroPiezo ecosystem. Mimaki Engineering anchors the wide-format textile specialist tier with integrated color management positioning. HP Inc. represents the cloud-software vector among US-based technology conglomerates.
| Leading Market Players |
|---|
| Mimaki Engineering Co., Ltd. |
| Seiko Epson Corporation |
| Sinotec Digital Co., Ltd. |
| Fujifilm Holdings Corporation |
| Roland DG Corporation |
| ColorJet India Limited |
| Canon Inc. |
| HP Inc. |
| MeiTu Digital Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Single-pass inkjet adoption is compressing cost-per-square-meter economics while concentrating procurement power among buyers with capital for continuous-feed systems. This technology transition simultaneously reshapes vendor revenue models toward recurring consumables and fragments price-setting authority across equipment, ink, and transfer media suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume commitment. Premium tiers command REACH-compliant ink bundles with color management software, while economy tiers compete on hardware depreciation schedules. Cost compression in entry-level equipment is intensifying because Chinese manufacturers are flooding desktop promotional-goods segments. Commercial print shops show highest price sensitivity due to fixed-price contract exposure, whereas Zhejiang textile manufacturers absorb premium pricing for yield guarantees.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for technical textiles are redirecting equipment procurement toward local assembly partners. Precision piezoelectric printhead supply draws from Japan and Germany, with water-based disperse dye formulations anchored in European REACH-certified facilities. Single-source vulnerability concentrates in MicroPiezo architecture supply during demand surges. Distribution runs through Hangzhou-based equipment vendors serving captive textile finishers and Stuttgart-area distributors supplying Central European technical textile producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as sportswear brands mandate certified ink chains, elevating compliance investments into competitive moats. This demand shift toward premium specifications signals late-cycle margin defense for incumbents with established certification infrastructure.
For Market Incumbents: Deploy consumables-lock ecosystems to counter modular printer architectures that threaten recurring revenue streams. Seiko Epson's MicroPiezo cartridge designs exemplify this lever. Add capacity in Zhejiang to capture integrated workflow demand from textile manufacturers. Defend against Chinese equipment entrants through color management software bundling that raises switching costs. For New Entrants and Emerging Players: Regional print shops lacking ICC profile expertise represent the most penetrable buyer archetype. Cloud-based workflow solutions reduce operator training barriers for this segment. Target India's underpenetrated garment clusters in Maharashtra and Gujarat where PLI incentives lower entry friction. Lead with transfer film innovation for rigid substrate applications beyond traditional fabric markets. For Investors and Strategic Acquirers: Roll-up economics work for regional print shop networks because e-commerce aggregation is fragmenting order volumes across dispersed service providers. Acquire platforms with established brand-licensor relationships and same-day fulfillment infrastructure. Watch REACH authorization timelines for disperse dyes as inflection indicators for compliant supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Formulation | Captures margin pools threatened by REACH-compliant chemistry shortages in European supply chains. |
| Cloud Workflow Platform Integration | HP's software-anchored model reduces operator recruitment burdens for commercial print shops. |
| Single-Pass Inkjet Capacity Expansion | Mimaki Engineering absorbs wide-format textile volumes previously dominated by rotary screen equipment. |
| Transfer Film Technology Licensing | Thin-film coating improvements open rigid panel applications beyond traditional polyester fabric markets. |
| Joint Venture in Zhejiang Manufacturing Corridor | Shaoxing and Jinhua zones enable integrated fabric-to-finish workflows with captive finishing capacity. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged print shop operators, textile finishing plant managers, ink formulation chemists, and equipment procurement leads at sportswear brands. Secondary validation drew from EPA VOC emission filings, ECHA REACH authorization databases, China MEE wastewater discharge records, and customs data tracking dye sublimation equipment imports. Bottom-up equipment installation counts were triangulated against top-down consumables spend estimates across the analysis window.
Segment-weighting approaches modeled printer configurations, ink chemistries, transfer media types, and end-user operational scales throughout the forecast period. CAGRs were derived from installed base projections and yield-per-machine assumptions. Industry-specific inputs included polyester price volatility indices, printhead supply lead times from Japanese component fabricators, and e-commerce order fragmentation rates in North American custom apparel channels.
Underlying measurement precision varies by segment; printer hardware and ink volumes carry tighter precision than emerging transfer film applications. Forecasts reflect documented assumptions about regulatory compliance timelines and raw material cost trajectories. Risks of revision stem from PFAS restriction expansions, crude oil derivative price swings affecting PET substrates, and piezoelectric component supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market