
 Middle East and Africa Footwear Sole Material Market | 2026-2036
Middle East and Africa Footwear Sole Material Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Footwear Sole Material Market Foresight
Modular sole systems with interchangeable cushioning layers and replaceable outsole units is broadening buyer choice across price tiers. SABIC leverages its Jubail petrochemical complex to supply high-performance thermoplastic elastomers for premium athletic soles. Borouge anchors the UAE's polymer value chain with differentiated polyethylene grades that compete on durability metrics in safety footwear applications.
Footwear sole material encompasses the elastomeric and polymeric compounds engineered for abrasion resistance, energy return, and ground contact performance, typically formulated from rubber, ethylene-vinyl acetate, polyurethane, or thermoplastic compounds processed through injection molding or compression curing. These materials must achieve Shore A hardness between 40 and 70 while maintaining flex fatigue resistance exceeding 100,000 cycles for commercial viability. Rubber dominates safety footwear applications where oil resistance and electrical hazard ratings command premium positioning, while EVA concentrates in athletic segments where density reduction drives performance claims. Polyurethane captures margin pools in fashion footwear through direct attach molding that eliminates adhesive costs.
Saudi Arabia's SFDA and the UAE's MOHAP enforce product safety standards that restrict phthalate content in children's footwear soles, while Egypt's national standards body mandates slip resistance testing for occupational safety categories. REACH-aligned substance restrictions from European trading partners are forcing reformulation across export-oriented Moroccan and Tunisian tanneries. Stakeholders must monitor polymer feedstock cost volatility from Gulf petrochemical expansions and decide between regional compounding investments or import dependency for specialized grades.
Market Dynamics
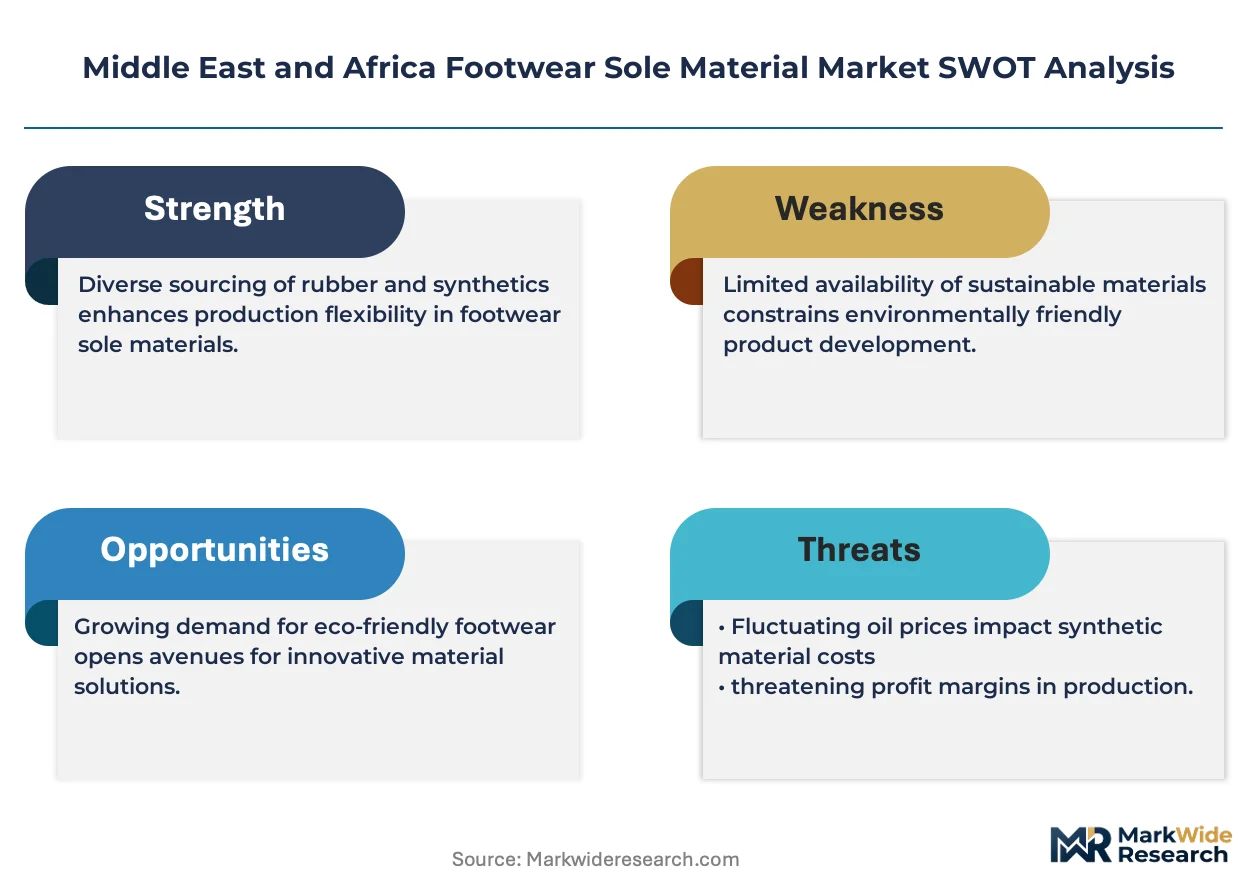
Gulf petrochemical capacity expansions are compressing regional feedstock costs while REACH-aligned substance restrictions from European trading partners force simultaneous reformulation across Moroccan and Tunisian export corridors.
Growth Catalysts
- REACH-aligned chemical restrictions:European trading partner mandates are accelerating phthalate-free compound development across North African tanneries serving premium export contracts.
- Modular sole architecture:Interchangeable cushioning layers and replaceable outsole units are broadening buyer choice across athletic and safety footwear price tiers.
- Saudi specialty polymer output:Jubail complex expansions are supplying high-performance thermoplastic elastomers for premium athletic sole applications regionally.
Market Restraints
- Crude oil derivative volatility:Ethylene and propylene feedstock costs fluctuate with Gulf petrochemical output cycles, compressing compounder margins unpredictably.
- Technical hardness-flex tradeoff:Achieving Shore A 40-70 ratings while maintaining 100,000+ flex fatigue cycles requires expensive additive packages that price out economy segments.
- Import dependency for specialized grades:Regional compounding capacity concentrates in standard EVA and rubber, forcing premium polyurethane and TPU sourcing from European or Asian suppliers.
Strategic Opportunities
- Nigerian manufacturing corridor:Lagos-to-Kano infrastructure investments are drawing footwear assembly operations that create captive demand for regional sole material supply.
- Safety footwear electrification standards:Egypt's national standards body mandates for slip resistance and electrical hazard ratings are opening certified compound premiumization paths.
- Direct attach molding convergence:Polyurethane injection systems are eliminating adhesive costs in fashion footwear, enabling margin capture through process integration.
Industry Challenges
- Formulation chemistry expertise scarcity:Compounding facilities across the Gulf and North Africa lack depth in thermoplastic elastomer rheology and additive synergies for performance grades.
- Multi-jurisdiction certification timelines:Simultaneous SFDA, MOHAP, and Egyptian standards compliance creates 18-24 month product launch cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Footwear Sole Material Market |
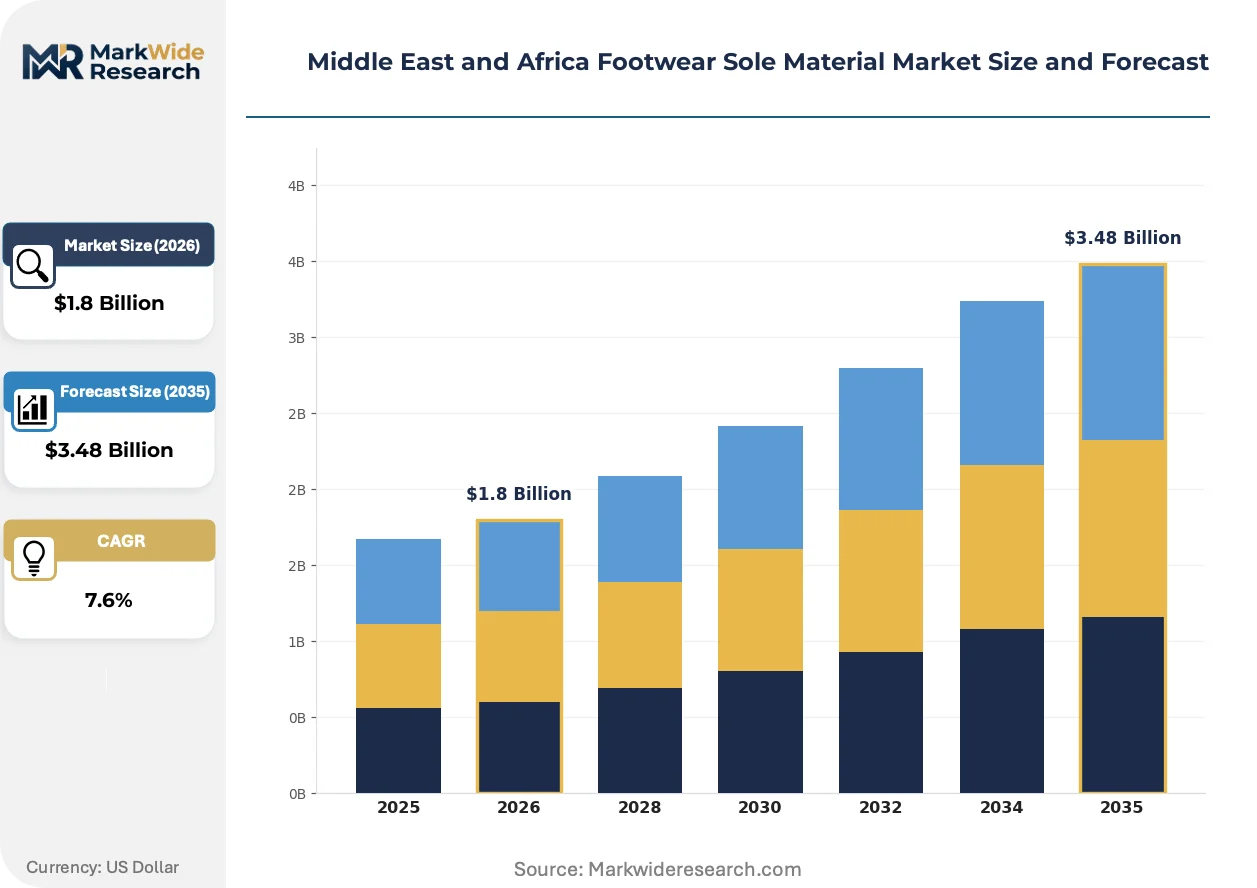
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, EVA, Polyurethane, Thermoplastic Application: Casual Footwear, Athletic Footwear, Safety Footwear, Fashion Footwear Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets Customer Type: Men, Women, Children, Unisex |
| Companies Covered | QAPCO, EQUATE, SABIC, Yansab, Saudi Kayan, Borouge, Sipchem, Petkim Petrokimya Holding A.Ş., Petro Rabigh, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Footwear Sole Material Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are converging to reshape compound specifications, processing methods, and supply chain configurations across Middle Eastern and African manufacturing nodes.
Distributed thermoplastic elastomer compounding is decentralizing production geography for premium athletic soles. Small-batch compounders in Dubai Industrial City and Jeddah are adopting twin-screw extrusion systems that previously required European or Asian centralization. Regional footwear brands are sourcing customized hardness and rebound specifications with 72-hour turnaround rather than 6-week import lead times.
REACH substance restrictions are forcing reformulation across Moroccan and Tunisian tanneries supplying European distributors. Phthalate-free plasticizer systems and bio-based polyol feedstocks are displacing conventional petroleum-derived compounds in children's and occupational footwear categories. Export-oriented manufacturers are absorbing 15-20% raw material cost premiums to maintain market access.
Athletic footwear procurement is compressing supplier qualification cycles as Gulf retailers demand seasonal collection responsiveness. Direct relationships between Riyadh and Dubai retail chains and compounders are displacing traditional distributor intermediaries. Saudi Arabia's domestic consumption surge is driving preference for regional sole material sourcing that supports "Made in GCC" labeling claims.
Middle East and Africa Footwear Sole Material Market Segmentation
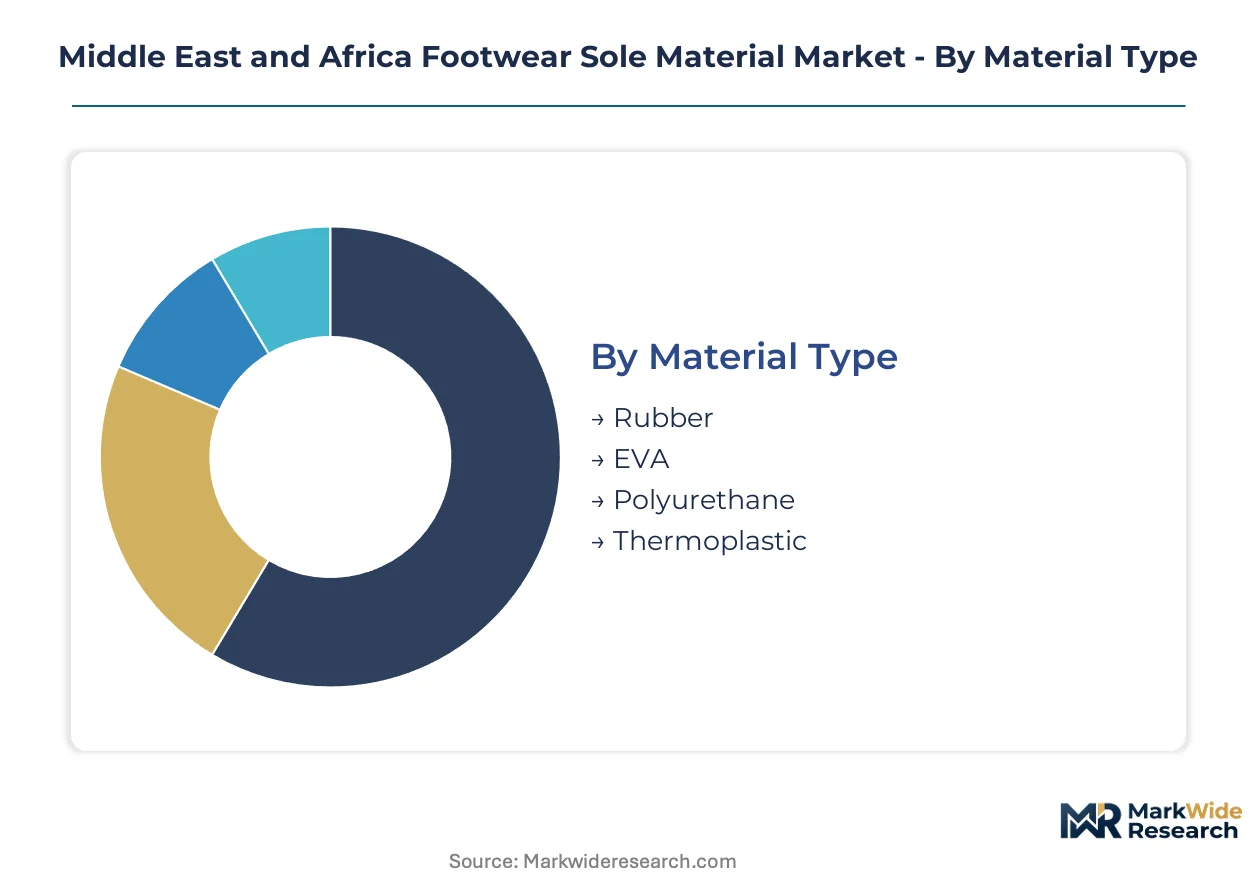
Footwear sole material procurement across the Middle East and Africa follows distinct technical and commercial logics that vary sharply by end-use durability requirements and buyer price sensitivity. Compound specifications diverge meaningfully between oil-resistant safety grades and density-optimized athletic formulations, creating separate supply channels and margin structures.
Material Type:
Performance specifications and Shore A hardness targets drive material selection more than unit cost for premium applications, while economy segments prioritize feedstock availability from Gulf petrochemical complexes.
- Rubber:Natural and synthetic rubber compounds deliver Shore A 60-70 hardness with superior oil resistance and electrical hazard insulation. Demand concentrates in Saudi Arabian and UAE safety footwear manufacturing where SABIC's butadiene derivatives supply regional compounders serving oil & gas sector procurement.
- EVA:Ethylene-vinyl acetate copolymers achieve density reductions below 0.25 g/cm³ for energy return optimization in running and training footwear. Athletic footwear adoption across Gulf Cooperation Council states is accelerating EVA volume, with Borouge's polyethylene value chain feeding regional foam expansion operations.
- Polyurethane:Direct attach molding systems eliminate adhesive layers through reactive injection processes, capturing margin in fashion footwear categories.
- Thermoplastic:TPU and TPE compounds enable small-batch customization with 72-hour turnaround for Dubai and Jeddah-based footwear brands demanding seasonal responsiveness.
Rubber leads on scale through safety footwear's regulatory-mandated durability requirements; thermoplastic leads on momentum through distributed compounding investments shortening lead times.
Application:
End-use durability standards and certification complexity create tiered pricing structures that separate commodity replacement soles from premium performance systems.
- Casual Footwear:EVA and rubber blends dominate everyday wear applications where comfort priorities meet moderate abrasion resistance targets of 50,000 flex cycles.
- Athletic Footwear:Multi-density midsole constructions combine compression-molded EVA bases with TPU energy return plates. Gulf retailer direct sourcing from compounders is displacing distributor intermediaries as Riyadh and Dubai chains demand collection responsiveness for seasonal launches.
- Safety Footwear:Oil-resistant nitrile rubber and polyurethane systems must achieve Egypt's national standards body mandates for slip resistance and electrical hazard ratings, opening certified compound premiumization paths.
- Fashion Footwear:Polyurethane direct attach molding eliminates adhesive costs while enabling design flexibility through single-unit cavity tooling.
Safety footwear leads on scale through occupational mandate penetration; athletic footwear leads on momentum through Gulf consumption surges and domestic sourcing preferences.
Distribution Channel:
Buyer relationship depth and technical consultation requirements determine channel viability, with specification-heavy safety and athletic segments favoring assisted purchase environments.
- Online Retail:Standard EVA replacement soles and aftermarket cushioning inserts move through e-commerce platforms serving price-sensitive individual consumers.
- Specialty Stores:Technical consultation for hardness specification and flex fatigue matching drives safety and athletic footwear sole material sales through professional fitting services.
- Department Stores:Fashion footwear categories with seasonal collection turnover rely on department store volume commitments to justify compounder minimum order quantities.
- Supermarkets:Economy casual footwear with basic rubber or EVA constructions targets impulse purchase and immediate-need replacement segments.
Specialty stores lead on scale through specification complexity; online retail leads on momentum through aftermarket expansion and direct-to-consumer brand building.
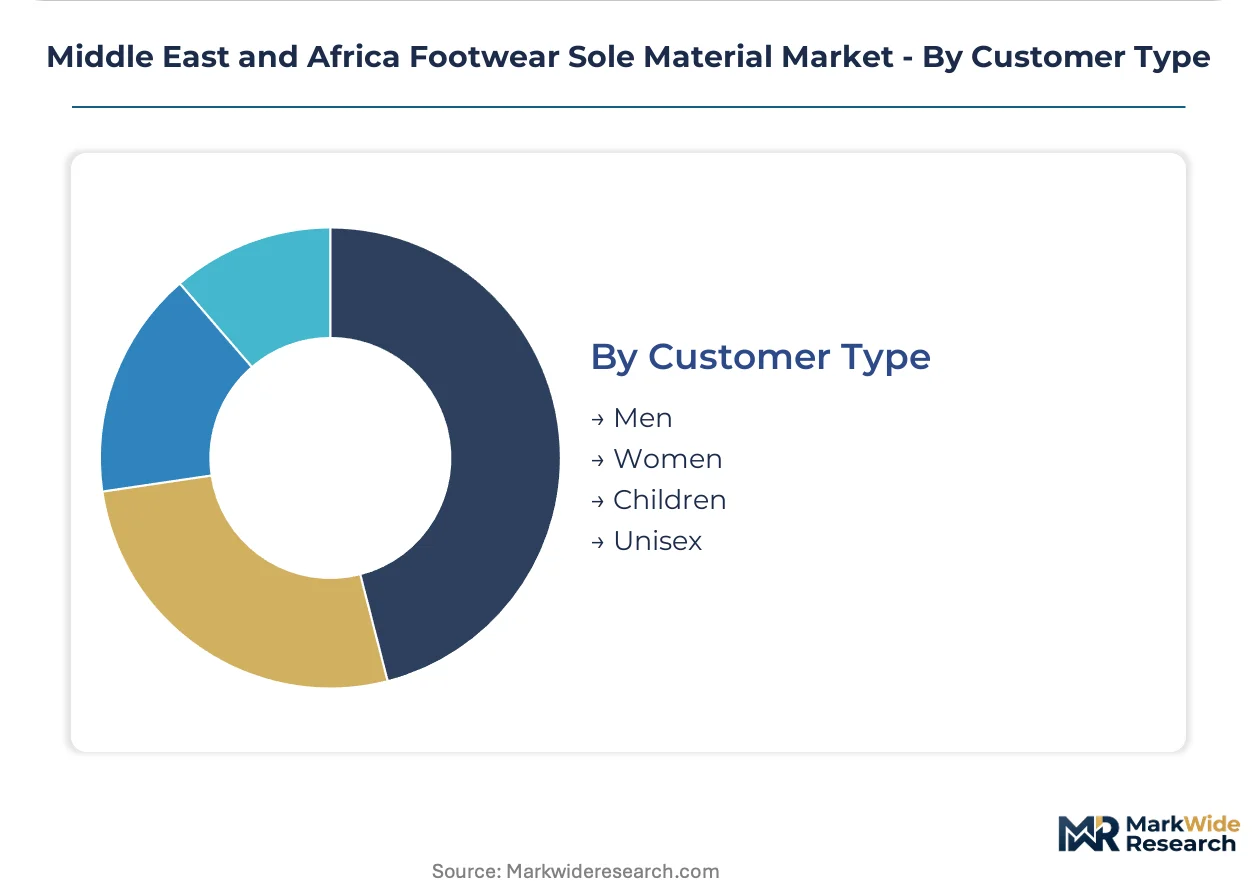
Customer Type:
Demographic-specific durability requirements and regulatory exposure create divergent compound performance thresholds across gender and age segments.
- Men:Industrial safety footwear with oil-resistant rubber soles dominates male-oriented procurement, particularly in Saudi Arabian and UAE oil & gas employment clusters.
- Women:Fashion and athletic categories drive polyurethane and EVA demand where density reduction and direct attach molding enable design differentiation.
- Children:SFDA and MOHAP phthalate content restrictions mandate reformulated plasticizer systems, with export-oriented manufacturers absorbing raw material cost premiums to maintain European market access.
- Unisex:Casual athletic and safety crossover styles standardize on mid-range EVA compounds with 45-55 Shore A ratings.
Men's safety applications lead on scale through industrial employment concentration; children's reformulated compounds lead on momentum through regulatory harmonization pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Footwear sole material manufacturing in the Middle East and Africa traces its industrial lineage to Gulf petrochemical buildouts of the 1970s-1980s, when Saudi Arabia and Kuwait established the region's first ethylene crackers to supply downstream polymer operations. Today, that feedstock advantage anchors specialized compounding for athletic and safety footwear across four distinct national markets.
Saudi Arabia
SABIC's Jubail complex supplies high-performance thermoplastic elastomers to domestic compounders serving the kingdom's surging athletic footwear consumption. The Saudi Food and Drug Authority enforces phthalate content limits in children's footwear soles, forcing reformulation across export-oriented manufacturers. Riyadh-based footwear brands are sourcing customized hardness specifications with 72-hour turnaround from new Jeddah compounders.
United Arab Emirates
Borouge anchors the UAE's polymer value chain with differentiated polyethylene grades competing on durability metrics in safety footwear applications. The Ministry of Health and Prevention restricts hazardous substance migration in children's sole materials, aligning product standards with European trading partner requirements. Dubai Industrial City has attracted small-batch thermoplastic elastomer compounders adopting twin-screw extrusion systems for premium athletic sole production.
Egypt
The national standards body mandates slip resistance testing and electrical hazard ratings for occupational safety footwear, opening certified compound premiumization paths for domestic manufacturers. Cairo-based tanneries serving European distributors are absorbing raw material cost premiums to maintain REACH-aligned market access. The Suez Canal Economic Zone is positioning for footwear assembly investment that would create captive demand for regional sole material supply.
Nigeria
The Lagos-to-Kano manufacturing corridor is drawing footwear assembly operations that create captive demand for regional sole material supply as domestic consumption rises. The country's national standards body is developing occupational safety footwear specifications that would mirror Egyptian and South African regulatory frameworks. Kano's emerging industrial clusters are attracting compounding investment targeting price-sensitive EVA formulations for mass-market casual footwear.
South Africa
Industrial safety footwear procurement from mining and manufacturing sectors drives nitrile rubber compound demand with oil resistance and electrical hazard insulation properties. The South African Bureau of Standards enforces durability testing protocols that exceed regional minimums, creating a premium tier for certified suppliers. Gauteng province's manufacturing belt concentrates domestic compounding capacity serving Southern African Development Community export markets.
Middle East and Africa Footwear Sole Material Market Competitive Landscape
The competitive structure tilts toward petrochemical-integrated compounders with captive feedstock access. Regional market concentration is moderate, with SABIC and Borouge commanding upstream polymer supply while downstream compounding fragments across specialized athletic and safety footwear formulators. Three archetypes dominate: Gulf-based integrated petrochemical suppliers, North African export-oriented compounders, and emerging Nigerian assemblers building captive sole material capacity. Capacity expansion and strategic partnerships with European technology licensors represent the dominant competitive moves.
Among Gulf-based integrated suppliers, SABIC, Borouge, and QAPCO exemplify the feedstock-advantaged archetype with Jubail and Ruwais complex positions. These entities occupy positions that downstream compounders depend upon for standard EVA and rubber grades, while specialized polyurethane and TPU sourcing remains concentrated with European or Asian technology partners. EQUATE and Petkim Petrokimya Holding A.Ş. represent the mid-tier compounding segment, serving regional footwear manufacturers with formulation services that bridge commodity polymer supply and performance-grade specifications.
| Leading Market Players |
|---|
| QAPCO |
| EQUATE |
| SABIC |
| Yansab |
| Saudi Kayan |
| Borouge |
| Sipchem |
| Petkim Petrokimya Holding A.Ş. |
| Petro Rabigh |
| Others |
Supply & Pricing Matrix
REACH-aligned phthalate restrictions from European trading partners are forcing North African tanneries to absorb reformulation costs, compelling compounders to recalibrate pricing models while Gulf petrochemical expansions create feedstock cost advantages for regional suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified safety compounds from uncertified alternatives and commodity EVA grades. Price differentiation rests on certification tier and volume scale, with Egyptian electrical hazard-rated compounds commanding premiums over standard occupational grades. Cost compression in economy EVA segments is intensifying because Borouge's polyethylene value chain expansion is flooding regional markets with standard-grade feedstock. Safety footwear procurement shows least price sensitivity due to regulatory mandate rigidity, while mass-market casual segments exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from Gulf retailers are mandating multi-supplier qualification for thermoplastic elastomer grades, fragmenting order books across Jeddah and Dubai compounders. Geographic supply concentration centers on Saudi Arabia's Jubail complex, the UAE's Ruwais facilities, and Egypt's Suez Canal Economic Zone. Raw material dependencies draw from SABIC's butadiene derivatives, Borouge's polyethylene grades, and imported polyurethane systems. Single-source vulnerability persists for specialized TPU grades tethered to European technology licensors. Distribution runs through direct relationships between Riyadh and Dubai retail chains and regional compounders, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Footwear Sole Material Market functions as a geographic-arbitrage play where Gulf petrochemical feedstock costs undercut European compounder pricing by double-digit margins, while North African export corridors face REACH compliance premiums that regional suppliers can avoid.
For Market Incumbents: Cement feedstock-advantaged positions through backward integration into SABIC's specialty polymer output and Borouge's differentiated polyethylene grades. Expand Jeddah and Dubai Industrial City compounding capacity to capture 72-hour turnaround demand from Riyadh retail chains. Defend against modular sole architecture disruptors by locking in multi-year supply agreements with athletic footwear brands seeking collection responsiveness. For New Entrants and Emerging Players: Capture the Nigerian Lagos-to-Kano manufacturing corridor where footwear assembly investment is creating captive sole material demand without established supplier relationships. Target Kano's emerging industrial clusters with price-sensitive EVA formulations for mass-market casual footwear. Enter through technical partnership with Egyptian standards body certification pathways to bypass 18-24 month compliance timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with small-batch thermoplastic elastomer compounders in Dubai Industrial City and Jeddah that have secured twin-screw extrusion technology from European licensors. Five-to-ten year viability favors entities with distributed compounding capabilities and direct retail chain relationships over centralized import-dependent models. Watch for inflection in Nigerian national standards body occupational safety specifications that would mirror Egyptian frameworks and trigger certified compound demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Supply | SABIC's Jubail complex expansions enable captive thermoplastic elastomer feedstock for premium athletic sole production. |
| Long-term Supply Agreement with Retail Chains | Direct relationships with Riyadh and Dubai chains displace distributor intermediaries and secure volume commitments. |
| Joint Venture with European Technology Licensor | TPU and specialized polyurethane formulation expertise transfers to regional compounders through technology partnerships. |
| Geographic Expansion into Nigerian Manufacturing Corridor | Lagos-to-Kano infrastructure investments create first-mover advantage in underserved West African footwear assembly. |
| Green Manufacturing Transition to Bio-based Polyols | REACH-aligned bio-based feedstocks maintain European market access for Moroccan and Tunisian export-oriented tanneries. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with compounder plant managers, footwear brand procurement leads, Gulf petrochemical technical directors, and Egyptian standards body officials with secondary validation from customs and trade data, SABIC and Borouge technical disclosures, and SEC filings from integrated petrochemical suppliers. Bottom-up volume modeling from individual facility capacities and top-down demand aggregation from end-use consumption patterns were cross-referenced for triangulation.
Comparable-period anchoring linked projection assumptions to historical feedstock cost cycles, regional capacity utilization rates, and certification timeline patterns across the analysis window. Segmentation dimensions modeled included material type, application category, distribution channel structure, and customer demographic with regional production hub differentiation. CAGRs were derived from slope analysis of normalized growth trajectories against petrochemical capacity expansion schedules and footwear consumption indices. Forecast inputs incorporated REACH regulatory harmonization pressures and modular sole architecture adoption curves.
Feedstock cost volatility from Gulf petrochemical output cycles, regulatory timeline delays from multi-jurisdiction certification requirements, and Nigerian manufacturing corridor infrastructure execution are the dominant revision risks. Deviation in SABIC specialty polymer expansion schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Uniform Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
North America Garment Steamers Market