
 Textile Transfer Paper Market | 2026-2036
Textile Transfer Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Transfer Paper Market Outlook
East Asian coating mills is repositioning global supply chains for textile transfer paper as brands demand shorter lead times. Felix Schoeller Group anchors European premium-grade output through its German manufacturing base. Sappi Limited leverages South African pulp integration to sustain cost-advantaged feedstock security. MINSEO CO., LTD. competes in Asian markets with specialized sublimation coatings.
Textile transfer paper consists of coated substrates engineered to release dyes or pigments onto fabric under controlled heat and pressure, typically operating at 180-220 degrees Celsius with dwell times of 15-30 seconds for optimal image fidelity. Its primary commercial purpose is enabling on-demand decoration of garments and soft goods without minimum order constraints inherent to direct screen printing. Sublimation transfer paper dominates technical margins due to polyester sportswear proliferation, while inkjet transfer paper captures fastest volume growth as desktop digital printers penetrate small decorator shops. Heat transfer paper retains largest share in cotton-apparel channels where pigment compatibility requirements limit substitute technologies.
EPA oversees volatile organic compound emissions from coating operations in US production facilities, while REACH restricts perfluorinated chemicals in European import paper. ECHA substance evaluations are forcing reformulation of release coatings across multiple supplier portfolios. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border fulfillment channels.
Market Dynamics
Digital print workflows are compressing order minimums across apparel decoration, forcing transfer paper suppliers to reconfigure coating lines for rapid SKU turnover rather than long production runs.
Growth Catalysts
- REACH chemical reformulation mandates:European coating facilities are accelerating investment in fluorine-free release layers, creating first-mover advantages for compliant suppliers in cross-border fulfillment channels.
- Polyester sportswear proliferation:Athletic apparel brands in Vietnam's export processing zones are scaling sublimation transfer capacity to serve direct-to-garment fulfillment models.
- Desktop digital printer penetration:Small decorator shops across North America and Western Europe are adopting inkjet transfer systems that bypass traditional screen-printing setup costs.
Market Restraints
- Pulp cost volatility:South African and Brazilian pulp supply disruptions are squeezing margins for uncoated base paper converters dependent on spot market feedstock.
- Coating chemical concentration:Specialty silicone and fluoropolymer release agents are supplied by a narrow tier of German and Japanese chemical firms, creating single-source vulnerability.
- Cotton-apparel pigment incompatibility:Sublimation dyes bond poorly with natural fibers, limiting addressable market share in cotton-dominant fashion segments where direct-to-film alternatives face technical constraints.
Strategic Opportunities
- India's PLI scheme for technical textiles:Domestic coating capacity investments are attracting transfer paper producers seeking tariff-advantaged supply to South Asian garment exporters.
- Recycled PET substrate development:Convergence of rPET fiber recycling with coating chemistry is enabling closed-loop transfer paper for circular apparel claims.
- Direct-to-film workflow adoption:Custom print shops are bypassing traditional transfer paper entirely, creating white-space demand for hybrid coating systems compatible with both legacy and film-based heat pressing.
Industry Challenges
- Color chemist talent scarcity:Formulation expertise for sublimation dye compatibility is concentrated among retiring specialists in European coating mills, constraining new product development timelines.
- ECHA substance evaluation lag:Pending regulatory determinations on perfluorinated compound alternatives are freezing capex decisions for coating line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Transfer Paper Market |
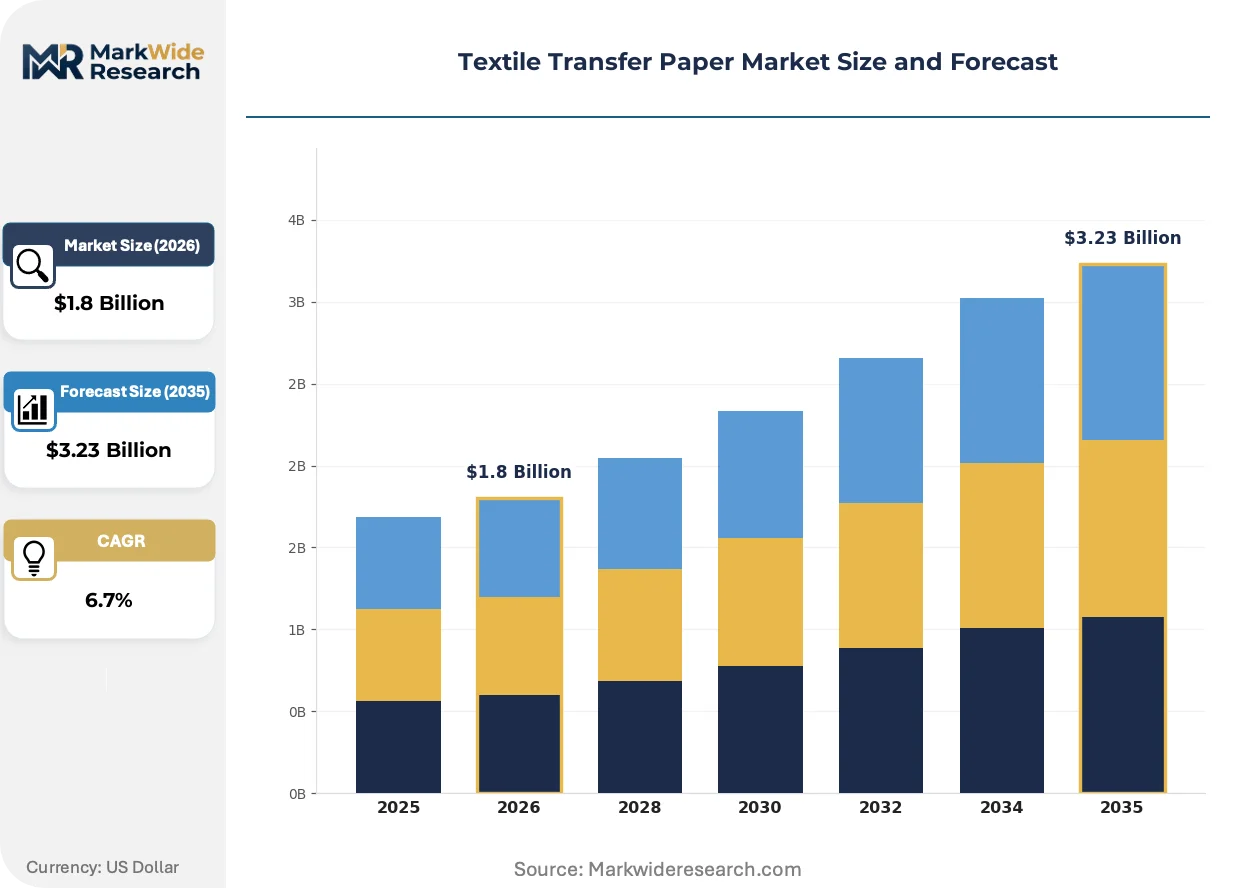
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Transfer Paper, Inkjet Transfer Paper, Sublimation Transfer Paper, Laser Transfer Paper Application: Apparel Decoration, Home Textiles, Promotional Items, Signage Technology: Digital Printing, Offset Printing, Screen Printing, Flexographic Printing End User: Manufacturers, Retailers, Online Platforms, Individual Consumers |
| Companies Covered | MINSEO CO., LTD., CANAPA Inc., Sappi Limited, Sino Coat Inc., Surya Coats Private Limited, Felix Schoeller Group, Guyenne Papier S.A.S., CHEEVER Specialty Paper & Film, Beaver Paper Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Transfer Paper Market Strategic Shifts
Heat press automation and AI-driven color profiling are compressing the skill threshold for commercial-grade textile decoration, democratizing access previously gated by technical expertise.
Water-based pigment inkjet transfer systems are overtaking solvent-based alternatives in small-batch cotton decoration. Print shops in Germany and the United States are retrofitting desktop units with these formulations to eliminate ventilation infrastructure. The shift is overtaking the historical volume advantage of plastisol screen transfers in orders below fifty units.
EPA volatile organic compound rules for coating operations are tightening solvent recovery requirements at US manufacturing facilities. Mills near textile clusters in North Carolina and California are consolidating thermal oxidizer investments to maintain operating permits. Heat transfer paper producers serving domestic fulfillment networks face the steepest compliance cost escalation.
Brand procurement teams are unbundling decoration services from garment manufacturing, contracting directly with regional print shops for localized fulfillment. Sportswear labels in Italy and Portugal are bypassing traditional wholesale distributors to source transfer-decorated blanks from micro-factories near retail endpoints. This pattern concentrates order fragmentation pressure on coating suppliers capable of sub-500-meter roll production.
Textile Transfer Paper Market Segmentation
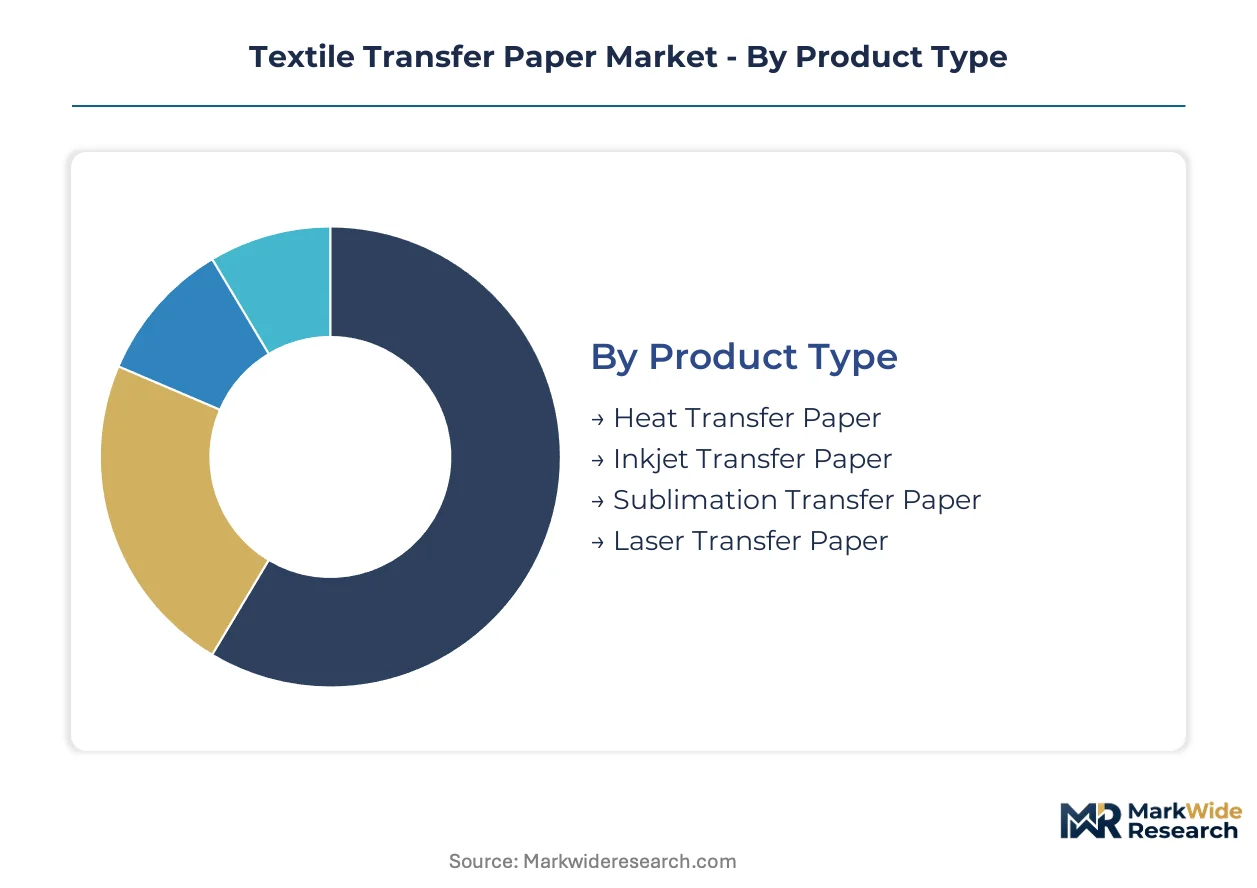
Transfer paper segmentation reveals how coating chemistry and print mechanism compatibility dictate supplier investment priorities. Each dimension—product type, application, technology, and end user—carries distinct margin profiles and capital requirements that reshape competitive positioning across the value chain.
Product Type:
Capital intensity peaks with sublimation coating lines requiring precision temperature control and specialized release chemistry, while inkjet formulations demand flexible SKU management for rapid formulation turnover.
- Sublimation Transfer Paper:Polyester-compatible coatings engineered for disperse dye gasification at 200 degrees Celsius. Vietnam's export garment zones concentrate demand as athletic brands relocate direct-to-garment fulfillment capacity from screen-printing operations.
- Inkjet Transfer Paper:Microporous coatings optimized for water-based pigment absorption and controlled release onto cotton substrates. Small decorator shops across Germany and the United States are driving volume as desktop printer adoption eliminates traditional setup costs.
- Heat Transfer Paper:Silicone release layers compatible with plastisol and solvent-based inks for natural fiber decoration.
- Laser Transfer Paper:Polymer coatings formulated for toner adhesion and heat-activated transfer in low-volume commercial environments.
Sublimation transfer paper absorbs the bulk of installed capacity; inkjet transfer paper is expanding most quickly.
Application:
Application segmentation tracks how end-use durability requirements and order fragmentation patterns redistribute coating demand across customer tiers.
- Apparel Decoration:Performance-grade coatings withstand repeated industrial washing cycles. Brand procurement teams in Italy and Portugal are unbundling decoration from manufacturing, contracting micro-factories for localized fulfillment.
- Home Textiles:Heavyweight base papers support large-format transfer for curtain and upholstery applications.
- Promotional Items:Cost-optimized formulations prioritize throughput over wash durability for single-use branded merchandise.
- Signage:UV-resistant coatings enable outdoor textile displays with extended color fastness requirements.
Apparel decoration commands the deepest coating expertise investment; promotional items are gaining share fastest as order minimums compress.
Technology:
Technology segmentation reflects the divergence between digital workflow flexibility and conventional print economies of scale.
- Digital Printing:On-demand inkjet and laser systems eliminate screen-making lead times. EPA volatile organic compound rules are accelerating water-based pigment adoption in US print shops.
- Screen Printing:Traditional mesh-based stencil methods retain cost advantages above 500-unit order thresholds.
- Offset Printing:Lithographic transfer for high-volume commercial decoration with standardized designs.
- Flexographic Printing:Rotary relief printing for continuous-roll textile decoration in industrial settings.
Digital printing infrastructure attracts the majority of new equipment spending; screen printing retains the largest installed base.
End User:
End user segmentation captures how procurement scale and technical sophistication reshape supplier service models.
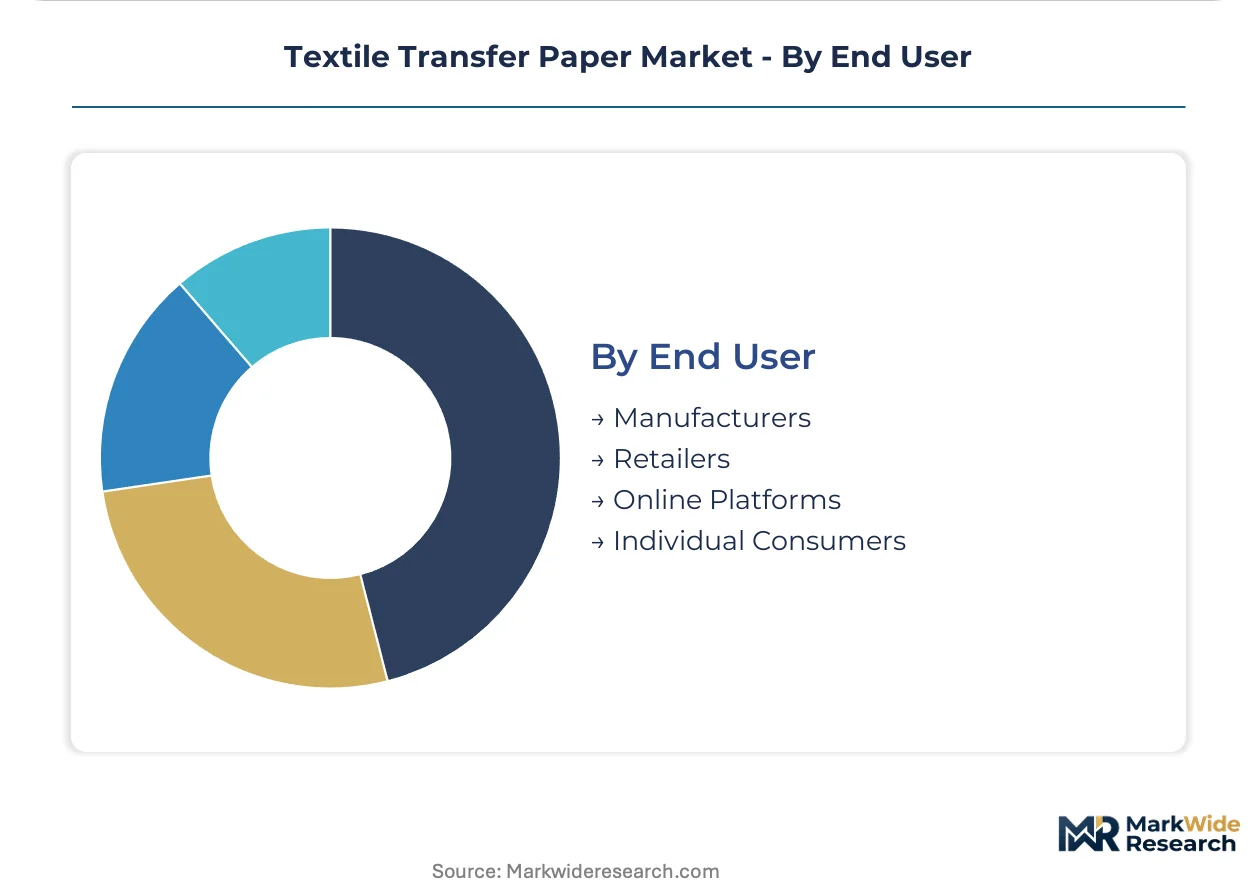
- Manufacturers:Vertically integrated garment producers operating captive decoration lines. REACH compliance mandates are forcing reformulation of European release coatings across their supplier portfolios.
- Retailers:Private-label brands sourcing decorated blanks through contracted print networks.
- Online Platforms:Digital-native fulfillment operations aggregating micro-batch orders from dispersed creators.
- Individual Consumers:Hobbyist decorators using desktop heat press systems for personalized projects.
Manufacturers represent the highest volume concentration; online platforms are climbing the fastest as direct-to-consumer models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African pulp integration anchors cost-advantaged feedstock security for coating mills serving export garment zones. German chemical expertise sustains premium-grade release layer formulation. Vietnamese manufacturing clusters absorb relocated screen-printing capacity from coastal China.
United States
EPA volatile organic compound rules tighten solvent recovery requirements at North Carolina and California coating facilities. Desktop digital printer penetration drives inkjet transfer paper demand among small decorator shops. Micro-factories near retail endpoints in Portland and Austin contract directly with sportswear labels for localized fulfillment.
Germany
ECHA substance evaluations force reformulation of perfluorinated release coatings across supplier portfolios. Felix Schoeller Group maintains premium-grade output through its domestic manufacturing base. Print shops in Bavaria and Baden-Württemberg retrofit desktop units with water-based pigment systems to eliminate ventilation infrastructure.
Vietnam
Export processing zones scale sublimation transfer capacity for athletic apparel brands adopting direct-to-garment fulfillment. BIS-equivalent technical textile standards attract coating facility investment from regional suppliers. Ho Chi Minh City and Binh Duong Province concentrate relocated screen-printing operations from Dongguan and Shenzhen.
India
PLI scheme incentives for technical textiles attract domestic coating capacity investment from transfer paper producers. Maharashtra and Gujarat garment exporters demand tariff-advantaged supply for South Asian fulfillment networks. Tiruppur and Surat industrial clusters integrate digital decoration workflows for cotton-apparel export orders.
China
Dual carbon goals accelerate coating line energy efficiency mandates in Yangtze River Delta manufacturing hubs. Sino Coat Inc. and Zhejiang-based competitors reposition supply chains for shorter lead time demands. Dongguan and Shenzhen micro-factories bypass traditional wholesale distributors to serve brand procurement teams directly.
Textile Transfer Paper Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized sublimation and hybrid coating niches. The vendor base concentrates among European premium-grade specialists, Asian volume producers, and North American regional converters. Three archetypes dominate: pulp-integrated paper mills with captive feedstock security, coating specialists with proprietary release chemistry, and regional converters serving fragmented decorator shop demand. Competitive moves center on fluorine-free formulation R&D and sub-500-meter roll production capability for micro-factory fulfillment.
Within the premium-grade tier, Felix Schoeller Group exemplifies European coating expertise anchored in German manufacturing. Sappi Limited represents pulp-integrated production with South African feedstock control. MINSEO CO., LTD. occupies the Asian specialist position competing on sublimation coating technology. These three entities illustrate how geographic feedstock advantages and regulatory compliance capabilities segment competitive positioning across the value chain.
| Leading Market Players |
|---|
| MINSEO CO., LTD. |
| CANAPA Inc. |
| Sappi Limited |
| Sino Coat Inc. |
| Surya Coats Private Limited |
| Felix Schoeller Group |
| Guyenne Papier S.A.S. |
| CHEEVER Specialty Paper & Film |
| Beaver Paper Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap coating specialists across Germany and Japan maintain pricing discipline through captive formulation expertise, resisting margin erosion even as pulp feedstock volatility squeezes converters dependent on spot-market sourcing. Their ownership structure insulates pricing power from quarterly earnings pressure, allowing sustained R&D investment in fluorine-free release chemistry demanded by REACH-compliant buyers.
Pricing Analysis
Warranty-backed coating performance guarantees separate premium-grade suppliers from unbundled commodity tiers. Felix Schoeller Group bundles technical service with sublimation formulations, commanding price premiums against standard-grade Asian imports. REACH compliance certification and sub-500-meter roll flexibility drive differentiation. Price erosion runs through heat transfer paper segments as cotton-apparel decorators face direct-to-film substitution. Small decorator shops in North America exhibit highest price sensitivity; athletic brands in Vietnam's export zones prioritize performance consistency over unit cost.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are redirecting coating facility investment toward Maharashtra and Gujarat production hubs. Base paper supply draws from South African pulp integration, German specialty paper mills, and Chinese Yangtze River Delta converters. Silicone and fluoropolymer release agents rest on narrow German and Japanese chemical firm supply. Single-source vulnerability in release chemistry creates structural exposure. Distribution runs through regional converters serving fragmented decorator shop networks rather than direct mill-to-brand relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH-compliant coating capacity as ECHA substance evaluations strand non-compliant inventory, forcing smaller converters toward acquisition or exit.
For Market Incumbents: Anchor fluorine-free formulation R&D ahead of pending ECHA determinations to capture stranded demand from non-compliant competitors. Pursue backward integration into South African or Brazilian pulp supply to neutralize feedstock volatility squeezing margin at uncoated base paper converters. Defend against direct-to-film substitution by developing hybrid coating systems compatible with legacy and film-based workflows. For New Entrants and Emerging Players: Begin with recycled PET substrate development targeting circular apparel claims where established players lack dedicated capacity. India's PLI scheme offers tariff-advantaged entry into South Asian garment export supply chains with lower compliance burden than European markets. Position through micro-factory fulfillment partnerships requiring sub-500-meter roll production that scale-protected incumbents disfavor. For Investors and Strategic Acquirers: Distressed-cycle entries favor coating specialists with captive release chemistry expertise in Germany and Japan where color chemist talent scarcity constrains new product development timelines. Five-to-ten-year viability hinges on fluorine-free formulation portfolios achieving commercial scale before regulatory deadlines harden. Watch ECHA substance evaluation timelines as inflection signal for capex commitment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating R&D Investment | REACH compliance mandates in Europe accelerate reformulation timelines for release layer suppliers. |
| Backward Integration into Pulp Supply | South African feedstock control insulates margin from spot market volatility affecting converters. |
| Hybrid Coating System Development | Direct-to-film workflow adoption creates white-space demand bridging legacy and emerging technologies. |
| Micro-Factory Fulfillment Partnership | Brand procurement unbundling concentrates order fragmentation on sub-500-meter roll capability. |
| Recycled PET Substrate Commercialization | Circular apparel claims converge rPET fiber recycling with coating chemistry for closed-loop positioning. |
Study Parameters
Multi-period observation of coating line capacity utilization, REACH compliance investment flows, and digital printer installation rates anchored the trend analysis, supplemented by interviews with coating mill technical directors, garment export procurement managers, and specialty chemical formulation leads. Secondary validation drew from customs trade data, ECHA substance evaluation dockets, EPA enforcement and compliance records, and SEC filings of pulp-integrated paper producers. Bottom-up demand modeling across decorator shop tiers triangulated against top-down coating capacity estimates.
Segment-weighting applied differential growth assumptions across sublimation, inkjet, and heat transfer paper categories, with technology adoption curves and regulatory compliance timelines as primary variance drivers. Product type, application durability requirements, print technology, and end-user procurement scale formed the core segmentation dimensions. CAGRs derived from installed base replacement cycles, capacity expansion announcements, and import-export flow analysis across the projection horizon.
Pulp supply disruption severity, ECHA regulatory timeline acceleration, and direct-to-film substitution velocity are the dominant revision risks to demand forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market