
 South America Cotton Market | 2026-2036
South America Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
South America Cotton Market Analytics
Synthetic fiber substitution is shifting product economics across South American textiles as polyester price volatility pushes spinners back toward natural fiber blends. Bom Futuro Group leverages its integrated farming-to-ginning footprint across Brazil's cerrado to capture margin at multiple stages. SLC Agrícola anchors its operations in precision agriculture platforms that optimize input application across massive landholdings. Cargill competes through its grain-and-fiber logistics network, extending storage and export terminal access to inland producers who lack direct port connectivity.
Cotton comprises the seed-hair fibers of Gossypium species, with staple length ranging from short (below 25mm) to extra-long (above 35mm) and cellulose content exceeding 88%, serving primarily as the foundational raw material for spun yarns and woven textiles. Raw cotton occupies the dominant value position due to Brazil's status as a top-five global exporter, while cotton yarn segments sustain higher per-unit margins through proximity to Andean textile clusters in Peru and Colombia. Organic cotton represents the fastest-expanding quality grade category as European apparel brands tighten their fiber sourcing standards and Brazilian certifiers build audit capacity.
Brazil's MAPA and ANVISA frameworks govern phytosanitary approvals and pesticide residue limits, directly conditioning which seed technologies and crop protection chemistries reach commercial scale across the cerrado and pampas. Argentina's SENASA regulations on genetically modified organism traceability create parallel compliance requirements for cross-border seed shipments and lint exports. Stakeholders must monitor how EU Green Deal due diligence rules on deforestation-free supply chains will reshape access conditions for South American lint entering European spinning mills.
Market Dynamics
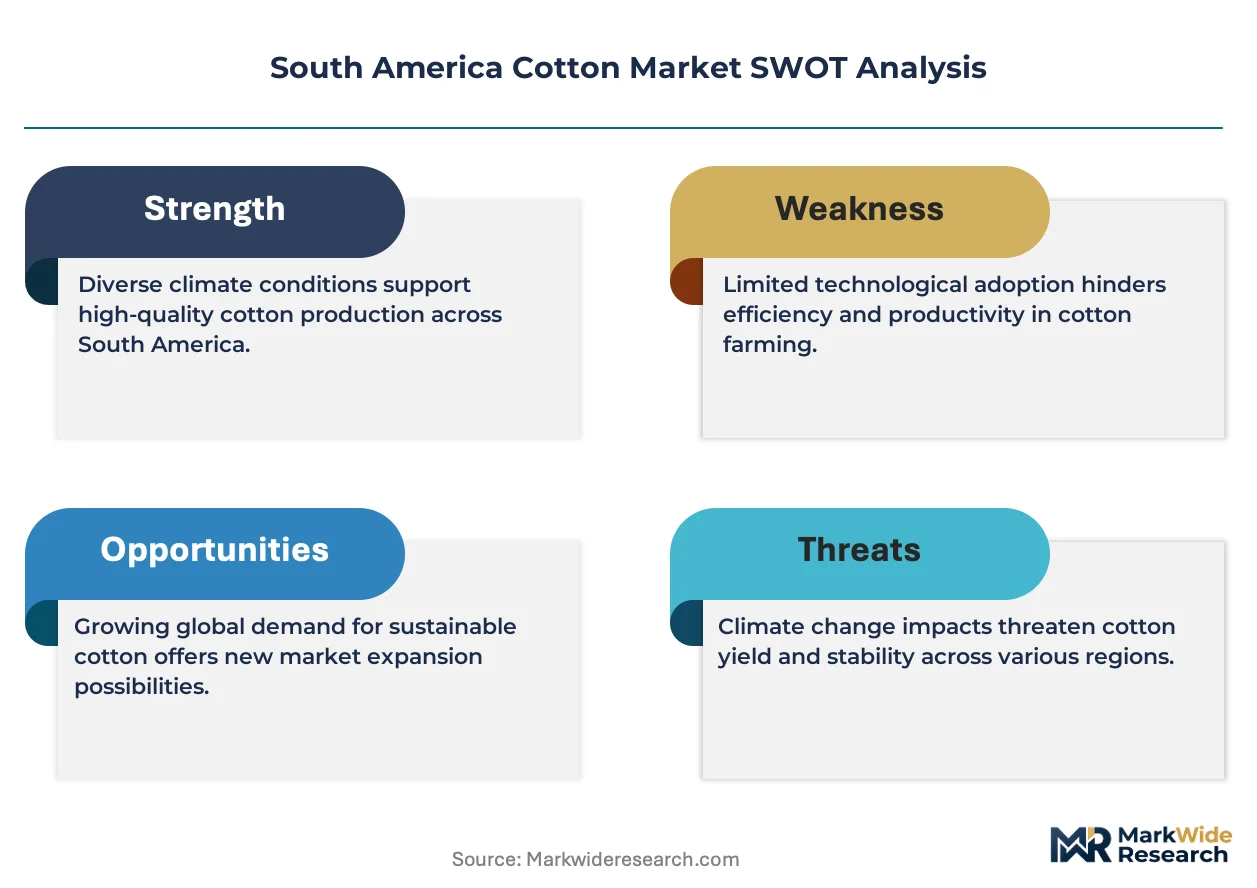
MAPA certification requirements for genetically improved seed varieties are redirecting planting decisions across Brazil's cerrado, concentrating output in Mato Grosso while marginalizing smaller holdings that cannot absorb compliance costs.
Growth Catalysts
- Genetically improved seed varieties:Higher-yielding cultivars certified under Brazil's MAPA framework are lifting lint output per hectare across mechanized farms in Mato Grosso and Bahia.
- Denim and knitwear manufacturing:Textile mills in Brazil and Argentina are expanding cotton sourcing to supply regional apparel production clusters serving domestic and export markets.
- EU Green Deal traceability mandates:European apparel brands are tightening fiber sourcing standards, pulling certified organic and deforestation-free South American lint into premium supply chains.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings compress margins for mechanized farming operations dependent on diesel-powered equipment across Brazil's interior.
- Supply concentration risk:Continental output dominance by Mato Grosso state creates geographic vulnerability to localized weather shocks and logistics bottlenecks.
- Synthetic fiber substitution:Polyester price volatility occasionally pushes spinners toward natural blends, but sustained low petrochemical costs threaten cotton's share in basic yarn grades.
Strategic Opportunities
- Organic certification capacity:Brazilian certifiers building audit infrastructure can capture premium positioning as EU due diligence rules harden market access requirements.
- Andean textile cluster proximity:Peru and Colombia's spinning mills offer yarn segment margin expansion for lint exporters with established cross-border logistics.
- Precision agriculture convergence:Integration of variable-rate input application with satellite imagery enables yield optimization across SLC Agrícola-scale landholdings.
Industry Challenges
- ANVISA residue compliance timelines:Pesticide approval delays and shifting maximum residue limits create inventory risk for growers with committed export contracts.
- Cross-border seed traceability:Argentina's SENASA GMO documentation requirements add administrative burden to Brazilian-Argentine seed shipments and lint re-exports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Cotton Market |
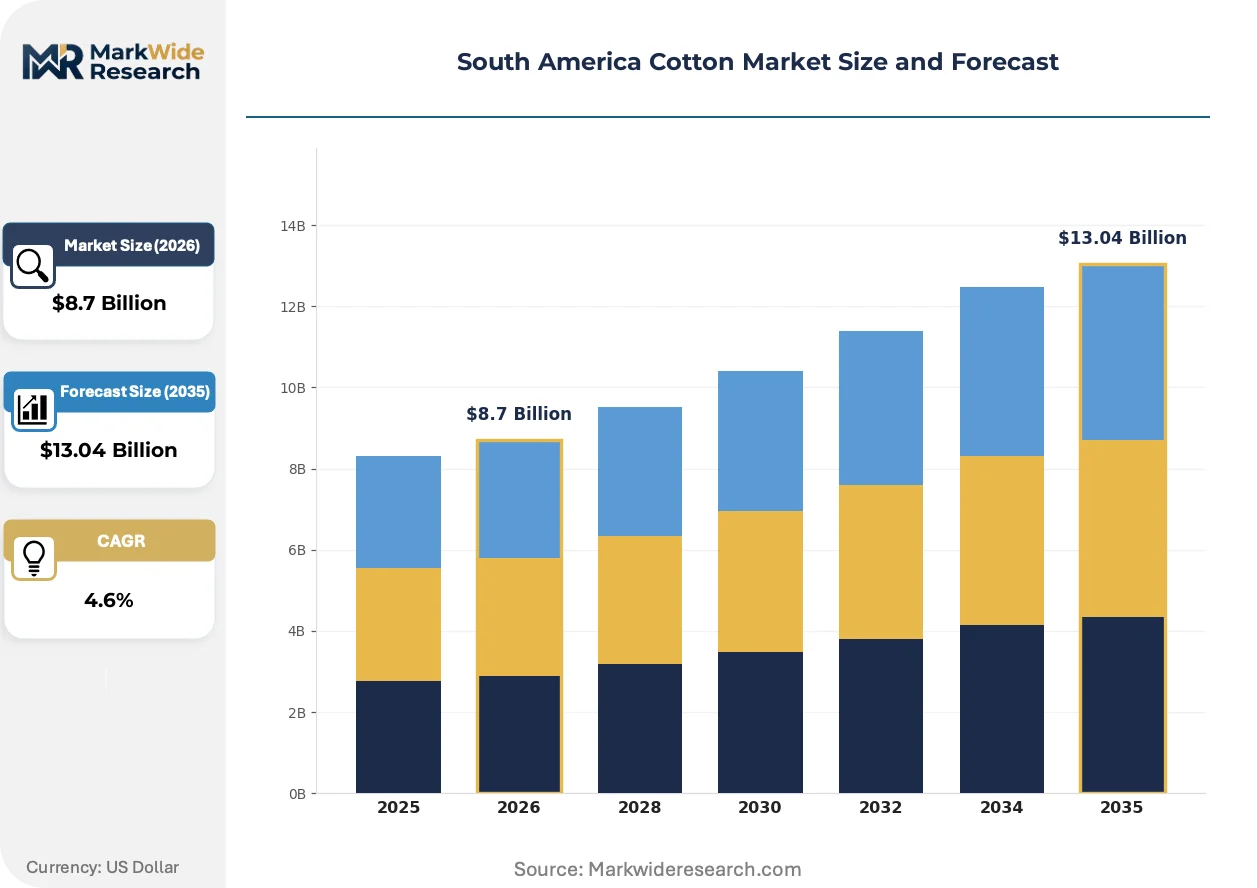
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cotton, Cotton Yarn, Cotton Fabric, Cotton Seed End User: Textile Manufacturers, Apparel Brands, Agricultural Producers, Wholesalers Distribution Channel: Direct Sales, Online Retail, Distributors, Exporters Quality Grade: Upland Cotton, Pima Cotton, Egyptian Cotton, Organic Cotton |
| Companies Covered | Bom Futuro Group, SLC Agrícola, Cargill, Bayer AG, BASF SE, Louis Dreyfus Company, ADM, Vicunha Textil SA, Coteminas SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Cotton Market Evolving Landscape
Technology adoption and regulatory tightening are reshaping how South American cotton moves from field to spinner, with certification and mechanization acting as the primary vectors of competitive differentiation.
Variable-rate precision agriculture platforms are expanding into large-scale farming operations across Brazil's cerrado, enabling real-time input optimization based on soil mapping and yield monitoring. SLC Agrícola and similar operators are deploying these systems across massive contiguous landholdings to compress per-hectare production costs. The technology is expanding into mid-scale holdings through shared-service models, threatening to widen the productivity gap between capital-intensive and traditional farms.
Brazil's MAPA and ANVISA frameworks are tightening phytosanitary and residue standards, conditioning which seed technologies and crop protection chemistries achieve commercial scale. These rules directly filter the cultivar options available to growers in Mato Grosso and Bahia, favoring multinationals with established regulatory submission capabilities. Exporters are responding by building internal compliance teams to manage documentation for EU Green Deal due diligence requirements.
European apparel brands are unbundling fiber sourcing from traditional commodity channels, establishing direct relationships with certified Brazilian growers to secure deforestation-free supply chains. This procurement model shift bypasses established trading houses for premium grades, concentrating volume commitments among holders of recognized sustainability certifications. The pattern is most visible in contracts for organic and BCI-certified lint entering Portuguese and Italian spinning mills.
South America Cotton Market Segmentation
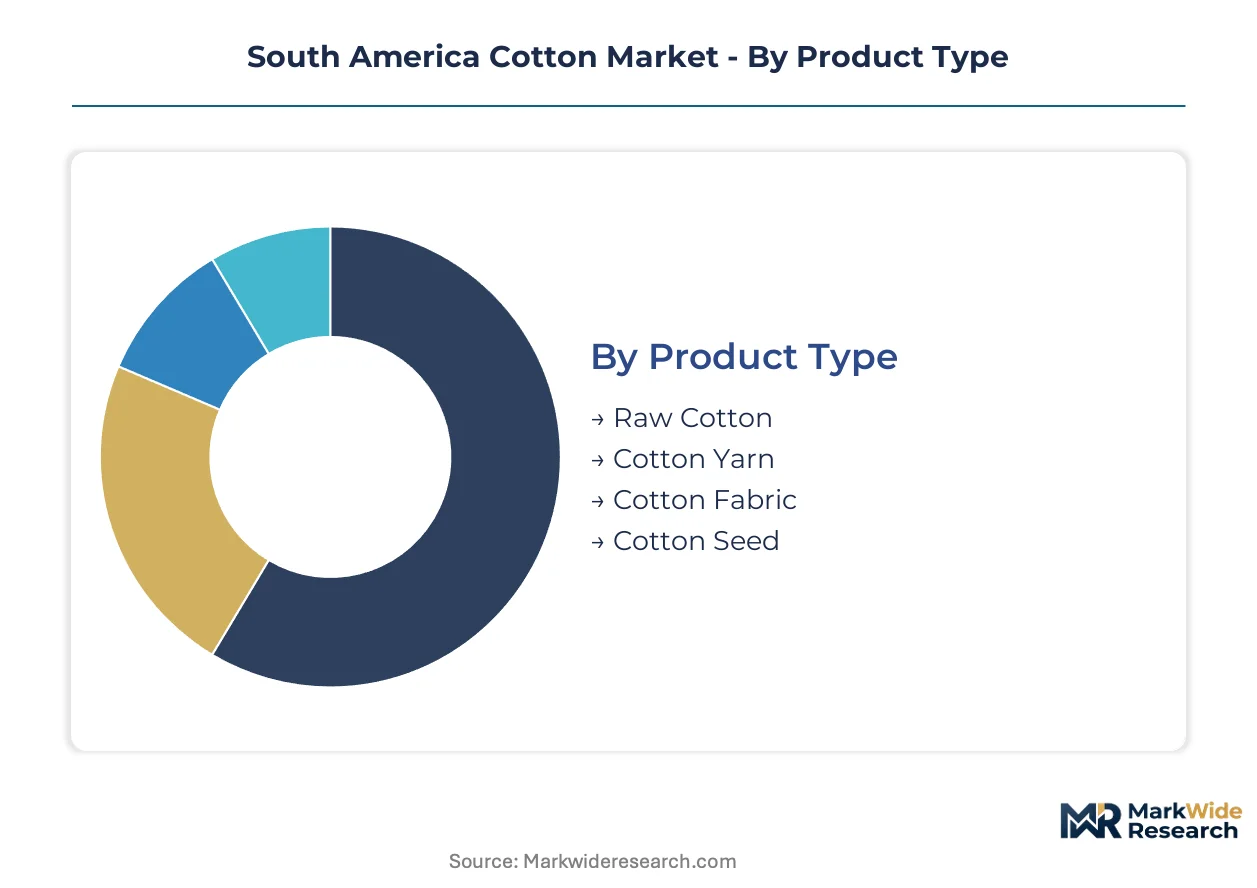
Cotton flows through South American supply chains along four distinct axes that reshape procurement economics. Product type determines margin capture, end user dictates certification requirements, distribution channel governs geographic reach, and quality grade controls premium access to European spinning mills.
Product Type:
Buyers prioritize product type based on where they sit in the value chain and their capital intensity for downstream processing.
- Raw Cotton:Seed-hair fibers of Gossypium species with staple length from short (below 25mm) to extra-long (above 35mm) and cellulose content exceeding 88%. Lint from Brazil's Mato Grosso state dominates continental exports to Portuguese and Italian mills, though ANVISA residue compliance timelines create inventory risk for growers with committed contracts.
- Cotton Yarn:Spun fibers serving as intermediate input for weaving and knitting operations. Peru's Andean textile clusters and Colombia's spinning mills sustain higher per-unit margins for yarn exporters with established cross-border logistics from Brazilian ginning facilities.
- Cotton Fabric:Woven or knitted textile substrates ready for garment assembly. Denim producers in Argentina's Pampas region source fabric from domestic mills serving regional apparel brands.
- Cotton Seed:Byproduct of ginning operations crushed for oil and meal. Crushers in Brazil's interior states process seed into feedstock for livestock operations and biodiesel refineries.
Raw cotton leads on scale; organic-certified yarn leads on momentum.
End User:
End user segmentation reflects divergent procurement power and sustainability mandate intensity across the value chain.
- Textile Manufacturers:Spinning and weaving mills converting lint into yarn and fabric. Brazil's denim and knitwear producers in São Paulo state are expanding cotton sourcing to supply regional apparel clusters.
- Apparel Brands:Finished garment producers and private-label retailers. European apparel brands are tightening fiber sourcing standards, pulling certified organic South American lint into premium supply chains through direct grower relationships.
- Agricultural Producers:Farming operations purchasing seed and inputs for cultivation. MAPA certification requirements for genetically improved varieties are redirecting planting decisions toward higher-yielding cultivars.
- Wholesalers:Trading houses aggregating lint from multiple ginning operations for export resale. Established trading houses face volume concentration as brands bypass intermediaries for premium certified grades.
Textile manufacturers anchor volume throughput; apparel brands drive certification premiums.
Distribution Channel:
Channel selection hinges on shipment scale, documentation complexity, and destination market access requirements.
- Direct Sales:Grower-to-mill contracts bypassing intermediaries. Large-scale mechanized farms in Mato Grosso negotiate directly with Portuguese and Italian spinning mills for deforestation-free supply chains.
- Online Retail:Digital platforms for seed and input procurement. Precision agriculture providers deploy shared-service models through web-based interfaces to mid-scale holdings.
- Distributors:Regional aggregators managing logistics for inland producers. Distributor networks extend storage and transport access to growers lacking direct port connectivity.
- Exporters:Specialized trading operations handling cross-border documentation. Exporters manage EU Green Deal due diligence paperwork and ANVISA residue certification for European market entry.
Direct sales capture the steepest expansion trajectory; distributors retain infrastructure leverage in interior states.
Quality Grade:
Quality grade determines end-market access and price tier positioning, with certification status increasingly decisive.
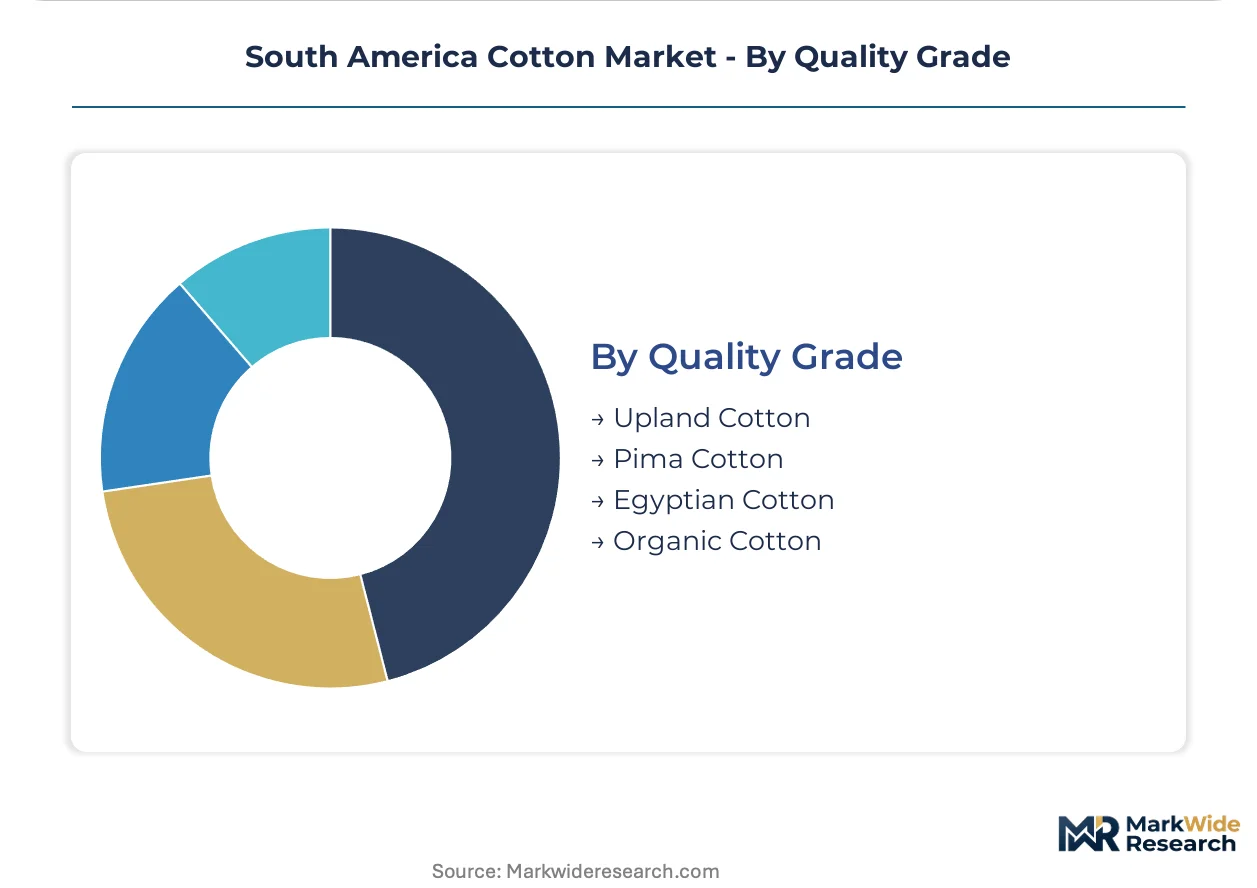
- Upland Cotton:Short to medium staple fiber (25-32mm) comprising the bulk of commercial production. Mechanized farms across Brazil's Cerrado dominate upland output for standard yarn grades.
- Pima Cotton:Extra-long staple variety (35mm+) commanding textile mill premiums. Peru's coastal valleys sustain Pima cultivation for export to high-end spinning operations.
- Egyptian Cotton:Giza-type extra-long staple historically imported for luxury textile blends. Egyptian cotton enters South American mills through re-export channels for premium fabric production.
- Organic Cotton:Cultivar grown without synthetic pesticides or fertilizers under third-party certification. Brazilian certifiers building audit capacity capture premium positioning as EU due diligence rules harden market access requirements.
Upland cotton leads on scale; organic cotton leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso's mechanized farming belt dominates continental lint output, concentrating export capacity in Brazil's interior while Andean spinning clusters in Peru and Colombia pull premium yarn segments northward.
Brazil
Denim manufacturers in São Paulo state are expanding cotton sourcing to supply regional apparel clusters. ANVISA residue limits and MAPA seed certification requirements filter which cultivars reach commercial scale across the cerrado. Large-scale operations in Mato Grosso anchor mechanized production for Portuguese and Italian mill contracts.
Argentina
Pampas-region denim producers source fabric from domestic mills serving regional apparel brands. SENASA GMO traceability rules add administrative burden to cross-border seed shipments and lint re-exports. Buenos Aires province ginning facilities process output for Mercosur textile manufacturers.
Peru
Andean textile clusters sustain higher per-unit margins for yarn exporters with established cross-border logistics. Coastal valley Pima cultivation supplies extra-long staple fiber to high-end spinning operations. Lima-based spinning mills convert imported Brazilian lint into premium yarn grades for export.
Colombia
Medellín and Bogotá spinning mills drive demand for certified lint entering regional supply chains. The country's national agricultural regulator enforces phytosanitary standards on imported seed varieties. Antioquia department textile parks are expanding cotton fabric production for domestic apparel brands.
South America Cotton Market Competitive Landscape
Global majors compete with regional champions across logistics networks and certification infrastructure, creating a tiered structure where scale-driven operators face specialized mid-cap growers. Trading houses with grain-and-fiber networks anchor the middle tier alongside integrated farming-to-ginning groups. Three archetypes dominate: multinational agribusiness conglomerates with export terminal access, domestic integrated operators controlling contiguous landholdings, and precision agriculture specialists deploying variable-rate platforms. Capacity consolidation and direct-to-mill contracting represent the dominant competitive moves reshaping procurement relationships.
Among Brazil-based integrated operators, Bom Futuro Group and SLC Agrícola exemplify the farming-to-ginning archetype, capturing margin across multiple production stages. Cargill occupies a position bridging multinational logistics scale with regional export infrastructure, extending storage and terminal access to interior producers lacking direct port connectivity.
| Leading Market Players |
|---|
| Bom Futuro Group |
| SLC Agrícola |
| Cargill |
| Bayer AG |
| BASF SE |
| Louis Dreyfus Company |
| ADM |
| Vicunha Textil SA |
| Coteminas SA |
| Others |
Value Network & Pricing Analysis
EU Green Deal traceability mandates gate both qualified supply and premium-tier pricing access, restricting deforestation-free lint to certified Brazilian growers while pushing standard-grade cotton toward commodity discounting. This bifurcation concentrates margin capture among holders of recognized sustainability certifications.
Pricing Analysis
Input-cost pass-through from fertilizer and diesel price swings compresses margins for mechanized farming operations across Brazil's interior. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with organic and BCI-certified lint commanding textile mill premiums. Cost compression in standard grades is intensifying because polyester substitution threatens cotton's share in basic yarn blends. Smallholder operations exhibit highest price sensitivity due to limited working capital buffers, while integrated farming-to-ginning groups absorb volatility through captive supply of processing capacity.
Supply Chain Analysis
Certification and qualification gating through MAPA seed approval and ANVISA residue compliance filters which cultivars reach commercial scale across Brazil's cerrado. Supply concentrates in Brazil, Argentina, and Peru, with Mato Grosso state anchoring mechanized output for export markets. The chain draws from genetically improved seed varieties, synthetic fertilizers, and diesel-powered equipment as core inputs. Single-source vulnerability runs through Mato Grosso's dominance of continental lint production, exposing buyers to localized weather shocks. Distribution runs through direct grower-to-mill contracts for premium grades and distributor networks for interior producers lacking port connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Green Deal due diligence rules driving demand for certified organic and deforestation-free supply chains.
For Market Incumbents: Deepen backward integration into ginning and logistics infrastructure to defend margin position against synthetic fiber substitution. SLC Agrícola-scale operators should expand precision agriculture platforms to compress per-hectare costs while building internal compliance teams for ANVISA residue documentation. Certification investment represents the critical lever for accessing premium European spinning mill contracts. For New Entrants and Emerging Players: Variable-rate precision agriculture platforms offer a technology-first wedge into mid-scale holdings through shared-service models. White-space targets include organic certification audit services and cross-border logistics coordination for Andean textile clusters in Peru and Colombia. The most penetrable segment is certified organic lint procurement, where established trading houses face displacement as brands bypass intermediaries. For Investors and Strategic Acquirers: Roll-up economics work for integrated farming-to-ginning operators because certification requirements and scale advantages are consolidating volume among capital-intensive players. Long-term viability centers on 5-10 year positioning around EU due diligence rule expansion and precision agriculture convergence. Target acquisition archetype: mid-scale Brazilian holdings with contiguous land and MAPA-certified seed adoption. The signal to watch is EU enforcement action on deforestation-free supply chain documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Capacity Buildout | Brazilian certifiers capturing premium positioning as EU Green Deal rules harden market access requirements. |
| Precision Agriculture Platform Deployment | SLC Agrícola-scale operators optimizing input application through satellite imagery and soil mapping integration. |
| Direct-to-Mill Contracting Expansion | Bom Futuro Group and similar integrated operators bypassing trading houses for deforestation-free supply chains. |
| Cross-Border Logistics Investment | Peru and Colombia spinning mills driving margin expansion for lint exporters with established Andean corridor access. |
| Backward Integration into Ginning | Large-scale mechanized farms capturing margin across multiple production stages while controlling quality documentation. |
Research Methodology
Bottom-up textile manufacturer demand modeling reconciled against top-down lint production tracking forms the analytical core of this study. Primary interviews with ginning operation managers, spinning mill procurement directors, MAPA regulatory officials, and European apparel brand sustainability leads combined with secondary validation from customs trade data, ANVISA phytosanitary filings, and EU Green Deal implementation guidance. This approach triangulates consumption patterns against certified acreage and export terminal throughput.
Historical trendline analysis of lint output, certified organic adoption rates, and mechanized farming expansion established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include product type, quality grade, end-user category, and distribution channel complexity. CAGRs derived from regression analysis of planted area, yield per hectare improvements, and premium-grade price differentials incorporate genetically improved seed adoption curves and EU due diligence compliance timelines as industry-specific forecast inputs.
The model holds under stable EU Green Deal enforcement intensity and continued MAPA certification pathway access; deviation in pesticide approval timelines or synthetic fiber cost collapses would shift volume and value trajectories. Forecasts reflect documented assumptions regarding certification adoption rates and mechanization investment cycles. A model refresh is warranted upon material change in EU deforestation-free supply chain verification requirements or ANVISA residue limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market