
 PVC Coated Fabrics Market | 2026-2036
PVC Coated Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Coated Fabrics Market Outlook
REACH registration deadlines for PVC plasticizers is unwinding competitive access across European supply chains. SRF Limited leverages backward integration into polyester yarn and PVC resin to control input costs across Asian production bases. Seaman Corporation anchors its position through military-specification product lines that dominate North American defense and emergency response procurement. Trelleborg AB differentiates via advanced polymer compounding capabilities that extend service life in marine and offshore environments.
PVC coated fabrics are textile substrates laminated with polyvinyl chloride layers, typically achieving 0.3–1.5 mm total thickness through calendering or knife-over-roll coating processes, engineered for waterproofing, UV resistance, and mechanical durability in exposed applications. Tarpaulins and canopies lead product type revenue due to recurring replacement cycles in logistics and event infrastructure, while marine-grade upholstery commands premium positioning through specialized saltwater and mildew-resistant formulations. Automotive applications within transportation end users represent the fastest-expanding demand pool as OEMs specify lighter-weight interior trim materials to support efficiency targets.
EMA and ECHA frameworks in Europe restrict phthalate plasticizer formulations, while EPA and OSHA standards in the United States govern vinyl chloride emissions and workplace exposure limits during coating operations. India's BIS certification mandates mechanical performance testing for tarpaulin exports, creating compliance barriers for uncertified regional mills. Stakeholders must monitor evolving chemical substitution pathways and certification reciprocity agreements that will determine which coating technologies retain market access across major economies.
Market Dynamics
REACH compliance deadlines for phthalate-based plasticizers are forcing European fabricators to reformulate coating chemistries, while Asian producers exploit backward integration into polyester and PVC resin to capture cost advantages in export markets.
Growth Catalysts
- Infrastructure buildouts:India's National Highways Authority and China's provincial transport bureaus are procuring weather-resistant tarpaulin systems for logistics corridors and temporary shelter networks.
- REACH substitution mandates:ECHA's progressive restrictions on orthophthalates are accelerating adoption of bio-based and terephthalate plasticizer alternatives in European coating operations.
- Automotive lightweighting:OEM interior trim specifications are specifying PVC-coated textiles to replace heavier vinyl sheet and leather substrates in seat and panel applications.
Market Restraints
- Petrochemical input volatility:Crude-derived PVC resin and plasticizer costs swing with naphtha and ethylene pricing, compressing margin predictability for independent coaters lacking captive resin supply.
- Substitution pressure:Thermoplastic polyurethane and silicone-coated fabrics are penetrating marine and medical segments where hydrolysis resistance and biocompatibility requirements exceed PVC performance ceilings.
- European regulatory friction:EMA and ECHA frameworks impose extended toxicological assessment timelines for new plasticizer chemistries, delaying product registration and market entry.
Strategic Opportunities
- Defense procurement specialization:NATO-aligned military shelter and tactical vehicle programs specify flame-retardant coated fabrics with documented supply chain security, creating premium contracting channels.
- Recycling infrastructure gaps:Mechanical and chemical recycling pathways for post-industrial PVC coated textile waste remain underdeveloped across North American and European collection networks.
- PLI scheme leverage:India's production-linked incentive programs for technical textiles subsidize capital investment in coating lines serving export-oriented tarpaulin and geotextile segments.
Industry Challenges
- Formulation chemistry expertise:Shortages of polymer scientists and coating process engineers with REACH-compliant plasticizer knowledge constrain European producer technical staffing.
- Multi-jurisdiction certification burden:Simultaneous BIS, ISO, and customer-specific factory audits create compliance timeline congestion for Asian exporters serving diversified markets.
- Legacy equipment retrofit costs:Knife-over-roll and calendering lines require capital-intensive ventilation and emission control upgrades to meet OSHA vinyl chloride exposure limits in US facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Coated Fabrics Market |
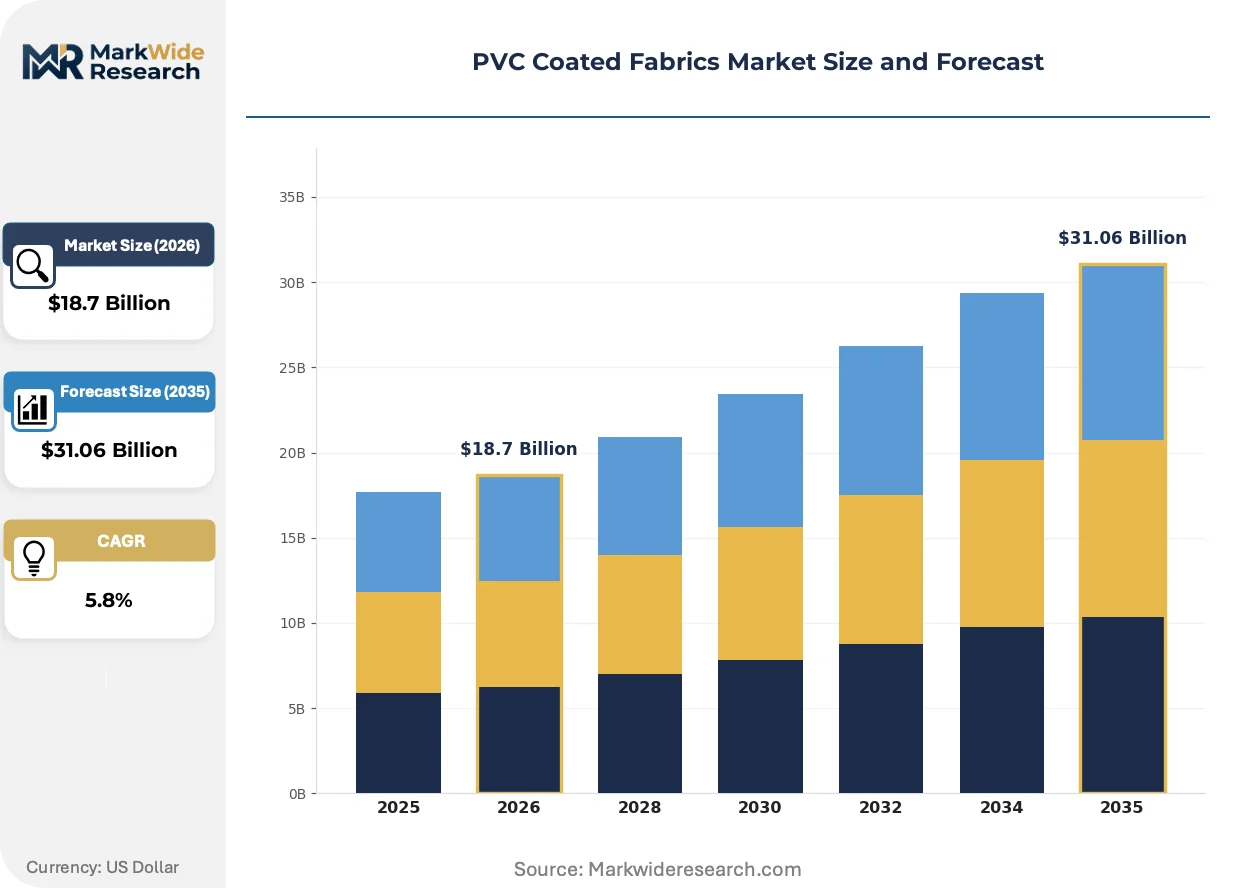
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tarpaulins, Banners, Canopies, Upholstery Application: Automotive, Construction, Marine, Agriculture End User: Transportation, Industrial, Retail, Recreation Fabric Grade: Standard, Heavy Duty, Light Weight, Weather Resistant |
| Companies Covered | SRF Limited, Seaman Corporation, Sioen Industries NV, Trelleborg AB, OMNOVA Solutions Inc., Serge Ferrari Group SAS, Freudenberg Performance Materials International SE & Co. KG, Valmiera Glass Group, Koninklijke Ten Cate NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Coated Fabrics Market Strategic Shifts
Coating technology evolution is bifurcating around sustainability credentials and performance specialization, with regulatory chemistry restrictions and end-use durability requirements pulling development in divergent directions.
Water-based PVC dispersion coating is displacing solvent-borne systems in European architectural membrane production. German and Dutch fabricators are converting calendering lines to aqueous formulations to eliminate MEK and toluene emissions. This transition is compressing the addressable market for conventional high-VOC coating equipment while expanding demand for infrared drying and forced-air curing infrastructure.
ECHA's 2025-2027 REACH authorization sunset dates for DINP and DIDP plasticizers are compelling reformulation investments across continental coating operations. Compounders are validating terephthalate, citrate, and bio-ester alternatives through accelerated weathering and migration testing protocols. Marine upholstery and inflatable boat segments face the steepest compliance ramps given saltwater immersion and prolonged UV exposure performance thresholds.
Fleet operators and event infrastructure managers are compressing replacement cycles for commercial tarpaulin assets through predictive wear monitoring and modular panel replacement programs. Logistics contractors in Germany and the Netherlands are shifting from full-cover replacement to sectional refurbishment contracts. This behavioral shift is visible most acutely in European road freight and outdoor event rental channels where asset utilization tracking justifies intervention-before-failure service models.
PVC Coated Fabrics Market Segmentation
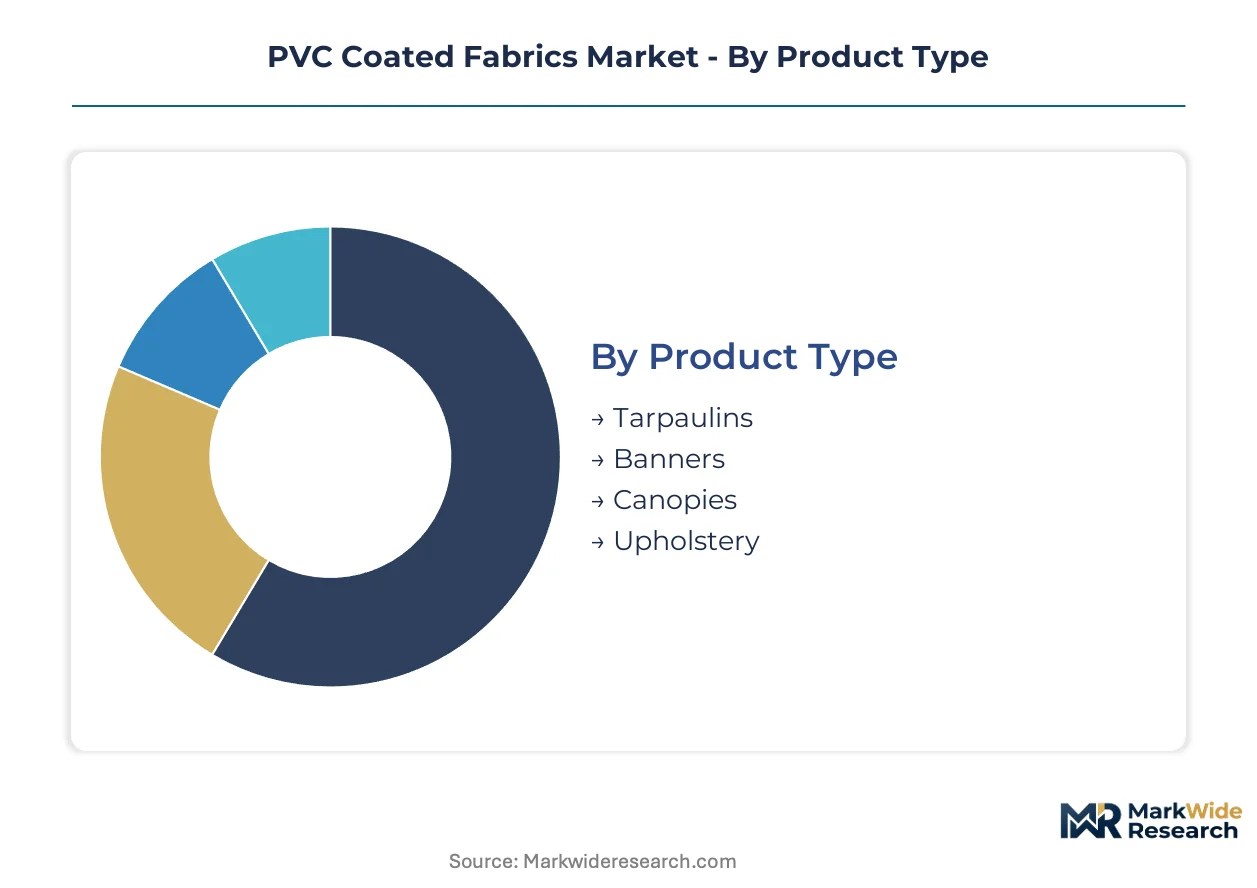
PVC coated fabrics serve divergent performance requirements across protective coverings, structural membranes, and interior finishes. Segmentation reveals which specifications command premium positioning versus commodity volume, and where substitute materials threaten incumbent technologies.
Product Type:
Tarpaulins and canopies face intensifying substitution pressure from polyethylene woven laminates in logistics applications, while marine upholstery defends its position through saltwater resistance specifications that thermoplastic polyurethane struggles to match at equivalent cost.
- Tarpaulins:Woven polyester or nylon substrates receive 0.5–1.2 mm PVC coatings through calendering lines, achieving 300–600 gsm fabric weights for truck covers and warehouse dividers. Indian logistics corridors and Chinese provincial transport bureaus are standardizing modular replacement programs that compress full-cover procurement cycles. Tarpaulins retain volume leadership; canopies hold the steepest expansion curve.
- Canopies:Architectural membrane structures employ knife-over-roll coated polyester with enhanced UV stabilizer packages for 10–15 year service life in event infrastructure and temporary shelter networks. German and Dutch rental operators are shifting from ownership to refurbishment-service contracts.
- Banners:Frontlit and backlit display substrates use lighter 200–400 gsm constructions with optimized ink adhesion layers for digital printing. Retail and event signage demand concentrates in urban commercial corridors.
- Upholstery:Marine and automotive seating applications specify mildew-resistant biocide packages and flame-retardant additives meeting NATO shelter specifications and OEM interior trim standards.
Replacement-cycle compression in logistics and event infrastructure is elevating service-contract revenue over discrete product sales.
Application:
Cost tier stratification separates military-specification marine fabrics from commodity construction site coverings, with automotive interior applications capturing margin through lightweighting compliance value.
- Automotive:Seat covers, door panels, and headliners specify 0.4–0.8 mm coated textiles replacing heavier vinyl sheet and leather substrates to meet OEM efficiency targets. North American and European passenger vehicle programs are expanding technical textile procurement for interior trim. Automotive applications gain share fastest; construction maintains volume dominance.
- Construction:Weather-resistant membranes for scaffolding enclosures and concrete curing blankets use heavy-duty 500–800 gsm grades with reinforced hems and grommet patterns. India's National Highways Authority infrastructure buildouts are accelerating tarpaulin deployment for logistics corridor shelter.
- Marine:Inflatable boats, fender covers, and deck upholstery require specialized plasticizer formulations resisting hydrolysis in saltwater immersion environments. ECHA's phthalate restrictions are forcing compound reformulation investments.
- Agriculture:Greenhouse cladding and grain storage covers balance light transmission with durability, competing against polyethylene film on cost in emerging markets.
Construction absorbs the highest tonnage; automotive climbs the fastest.
End User:
Customer type determines specification stringency, with defense and industrial procurement mandating documented supply chain security while retail channels prioritize cost and color consistency.
- Transportation:Fleet operators in road freight, rail, and shipping specify standardized cover dimensions with predictive wear monitoring integration. German logistics contractors are piloting RFID-embedded fabrics for asset tracking.
- Industrial:Manufacturing facilities and warehousing operations demand flame-retardant grades meeting OSHA workplace exposure standards during installation and maintenance.
- Retail:Point-of-sale displays and seasonal outdoor fixtures drive shorter-run, higher-SKU production with rapid color-matching requirements.
- Recreation:Camping, boating, and event rental segments combine seasonal demand volatility with performance expectations for repeated deployment cycles.
Industrial procurement anchors volume; transportation segments expand most quickly through fleet standardization.
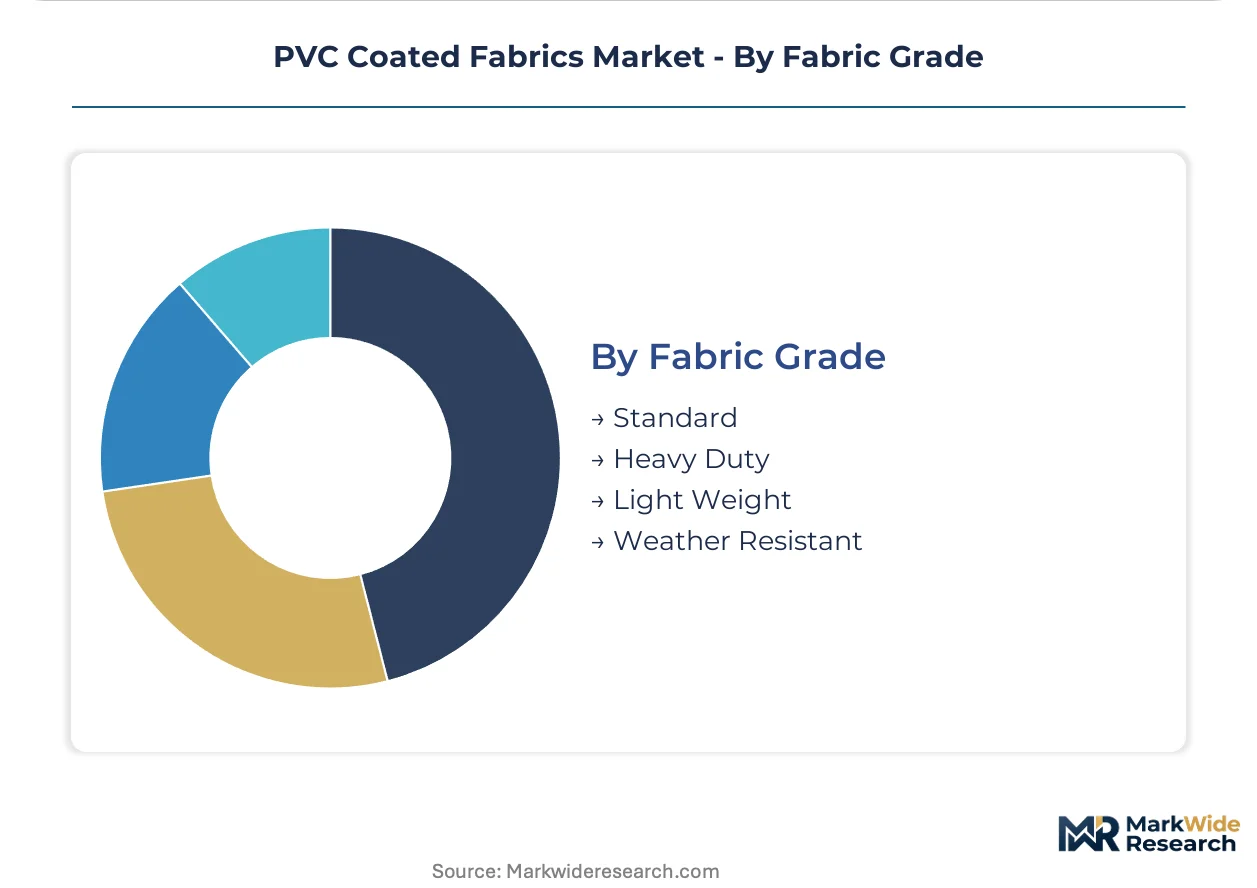
Fabric Grade:
Performance tier alignment matches specification investment to exposure severity, with weather-resistant grades capturing premium positioning in extended-service applications.
- Heavy Duty:Reinforced constructions with ripstop weave patterns and double-coated surfaces achieve 800+ gsm weights for military shelters and offshore platform coverings. NATO-aligned defense programs specify documented supply chain security.
- Weather Resistant:Enhanced UV stabilizer and fungicide packages extend service life in tropical and marine environments where standard grades degrade within 18–24 months.
- Standard:General-purpose 300–500 gsm grades serve cost-sensitive construction and agriculture applications with 3–5 year replacement expectations.
- Light Weight:Reduced coating thicknesses below 0.4 mm prioritize packability and handling efficiency in recreational and temporary signage uses.
Heavy duty grades command premium positioning; weather resistant specifications climb fastest as replacement-cycle extension becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for technical textiles and China's infrastructure buildouts are redirecting production capacity toward export-oriented coating operations. Germany and the Netherlands face ECHA-mandated reformulation deadlines that compress margins for phthalate-dependent fabricators.
China
Provincial transport bureaus in Jiangsu and Zhejiang are procuring weather-resistant tarpaulin systems for logistics corridor expansion. MIIT's dual carbon goals pressure coating lines toward aqueous dispersion technologies. The Yangtze River Delta concentrates calendering capacity serving automotive interior programs for domestic OEMs.
India
National Highways Authority infrastructure tenders drive heavy-duty tarpaulin deployment across logistics shelter networks. BIS certification mandates for export-grade mechanical performance testing filter uncertified regional mills from international procurement. Gujarat and Maharashtra host backward-integrated polyester yarn and PVC resin operations that control input costs for Asian production bases.
Germany
REACH authorization sunset dates for DINP and DIDP plasticizers force compound reformulation investments across continental coating operations. ECHA's extended toxicological assessment timelines delay new chemistry registrations. The Ruhr industrial corridor witnesses conversion of solvent-borne lines to water-based PVC dispersion systems for architectural membrane production.
United States
OSHA vinyl chloride exposure limits during coating operations necessitate capital-intensive ventilation upgrades for legacy knife-over-roll equipment. Defense procurement programs specify flame-retardant coated fabrics with documented supply chain security. The Southeast automotive belt expands technical textile sourcing for interior trim lightweighting compliance.
Netherlands
Dutch rental operators pioneer modular panel replacement contracts that compress full-cover procurement cycles in event infrastructure. EMA frameworks restrict phthalate plasticizer formulations in marine upholstery segments. The Port of Rotterdam cluster serves North Sea offshore platform covering demand with specialized saltwater-resistant grades.
PVC Coated Fabrics Market Competitive Environment
Listed leaders compete with private specialists across capital access and reformulation agility. The vendor base stratifies between scale-driven resin-integrated producers and specification-focused defense contractors. Three archetypes dominate: backward-integrated Asian fabricators controlling polyester and PVC inputs; European compounders pivoting aqueous coating technologies; and military-specification anchors serving NATO procurement channels. Competitive moves concentrate on capacity expansion in India and China plus technology licensing for REACH-compliant plasticizer alternatives.
Among the named set, SRF Limited exemplifies the backward-integrated archetype through its polyester yarn and PVC resin operations. Seaman Corporation anchors the defense-specialist tier with documented supply chain security positioning. Trelleborg AB occupies the advanced polymer compounding segment serving marine and offshore durability requirements.
| Leading Market Players |
|---|
| SRF Limited |
| Seaman Corporation |
| Sioen Industries NV |
| Trelleborg AB |
| OMNOVA Solutions Inc. |
| Serge Ferrari Group SAS |
| Freudenberg Performance Materials International SE & Co. KG |
| Valmiera Glass Group |
| Koninklijke Ten Cate NV |
| Others |
Value Chain & Pricing Dynamics
REACH authorization timelines for phthalate plasticizers gate both European supply qualification and the price premium commanded by compliant formulations, compressing margins for fabricators caught mid-reformulation while rewarding early movers with certified alternative chemistries.
Pricing Analysis
Certification level creates the primary spread between heavy-duty military-spec grades and commodity construction tarpaulins. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification status, REACH compliance documentation, and volume contract scale. Pricing pressure stems from polyethylene woven laminates undercutting logistics-grade PVC tarpaulins in emerging markets. Fleet operators and construction procurement teams exhibit highest price sensitivity, while defense shelter programs tolerate premium positioning for documented supply chain security.
Supply Chain Analysis
Inventory lead times stretch 8–14 weeks for specialty plasticizer formulations subject to ECHA toxicological review. Supply concentrates in China, India, and Germany, with the Yangtze River Delta and Gujarat corridor hosting backward-integrated polyester yarn and PVC resin operations. Raw material dependencies center on naphtha-derived PVC resin, orthophthalate and terephthalate plasticizers, and UV stabilizer packages. Single-source vulnerability runs through European specialty compounders lacking captive resin supply. Distribution runs through direct mill relationships with large fleet operators and industrial distributors serving fragmented construction and agriculture accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure procurement cycles are entering an upswing phase as India's National Highways Authority and China's provincial transport bureaus accelerate logistics corridor deployment, creating volume absorption capacity for compliant coating operations.
For Market Incumbents: Consolidate formulation chemistry expertise around REACH-compliant plasticizer alternatives before ECHA sunset deadlines eliminate phthalate-dependent competitors. Acquire distressed European coating assets with aqueous dispersion line conversions already completed. Thermoplastic polyurethane substitution in marine upholstery represents the most acute technology threat requiring defensive R&D allocation. For New Entrants and Emerging Players: BIS certification fast-tracks for Indian export-grade tarpaulin production unlock access to National Highways Authority tenders and European logistics contractor procurement. Target modular panel replacement service contracts in German and Dutch event infrastructure where incumbent rental operators lack technical textile coating capabilities. Pursue PLI scheme subsidies for technical textile capital investment in Gujarat and Maharashtra production corridors. For Investors and Strategic Acquirers: ECHA's 2025–2027 REACH authorization sunset reshapes the acquisition landscape toward compounders with validated bio-ester and terephthalate plasticizer portfolios. Over a 5–10 year horizon, viability hinges on aqueous coating technology maturation and recycling infrastructure development. Monitor BIS certification reciprocity negotiations as the signal for Indian export capacity absorption into European procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester and PVC Resin | SRF Limited's captive yarn and resin operations neutralize petrochemical input volatility for Asian export bases. |
| REACH-Compliant Plasticizer Reformulation | ECHA sunset deadlines force compound investments that filter uncertified European fabricators from NATO defense procurement. |
| Aqueous Dispersion Coating Conversion | German and Dutch calendering line upgrades eliminate MEK emissions while meeting MIIT dual carbon goals in China. |
| Modular Panel Replacement Service Contracts | Dutch rental operators compress full-cover procurement cycles through predictive wear monitoring and sectional refurbishment programs. |
| Defense Procurement Supply Chain Security Documentation | Seaman Corporation's military-specification positioning anchors NATO shelter and tactical vehicle premium contracting channels. |
Study Parameters
The analysis maps tarpaulin, canopy, marine upholstery, and automotive interior segments, each validated through coating line engineers, logistics procurement managers, defense shelter program officers, and technical textile distributors. Primary interviews with polymer scientists, plant managers at integrated resin operations, and fleet maintenance directors combined with secondary validation from customs trade data, BIS certification registries, ECHA authorization databases, and SEC filings from listed coating specialists. Bottom-up capacity and utilization estimates triangulated against top-down end-use demand modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, application end-use, fabric grade tier, and regional production hub dimensions. CAGRs derived from segment-level growth drivers including infrastructure procurement intensity, automotive lightweighting compliance, and regulatory substitution mandates. Forecast inputs incorporated REACH compliance timeline assumptions, PLI scheme subsidy absorption rates, and aqueous coating technology penetration curves.
Underlying assumptions cover ECHA authorization sunset adherence, BIS certification reciprocity expansion, and naphtha price corridor stability, with deviation risk concentrated in petrochemical input volatility and thermoplastic polyurethane substitution acceleration in marine segments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market