
 Global Sulfur Dye Market | 2026-2036
Global Sulfur Dye Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sulfur Dye Market Intelligence
Manufacturing capacity for conventional sulfur dye powders in China is consolidating due to stricter environmental enforcement. This shift benefits multinational producers like Archroma, which specializes in sustainable dyeing solutions. DyStar Group leverages its global distribution network to supply a broad portfolio of colorants to major textile hubs. Meanwhile, Atul Ltd sustains its market position through large-scale production facilities in India, serving both domestic and export markets.
Sulfur dyes are synthetic colorants rendered water-soluble through a reduction process involving sodium sulfide, enabling them to dye cellulosic fibers. Their primary industrial purpose is coloring cotton, particularly for denim and other heavy fabrics, due to their cost-effectiveness and good wash fastness. The market for powder forms remains dominant by volume, though liquid variants are gaining traction due to easier handling and reduced environmental impact. Within applications, the textiles segment, specifically for garment manufacturing, accounts for the vast majority of consumption.
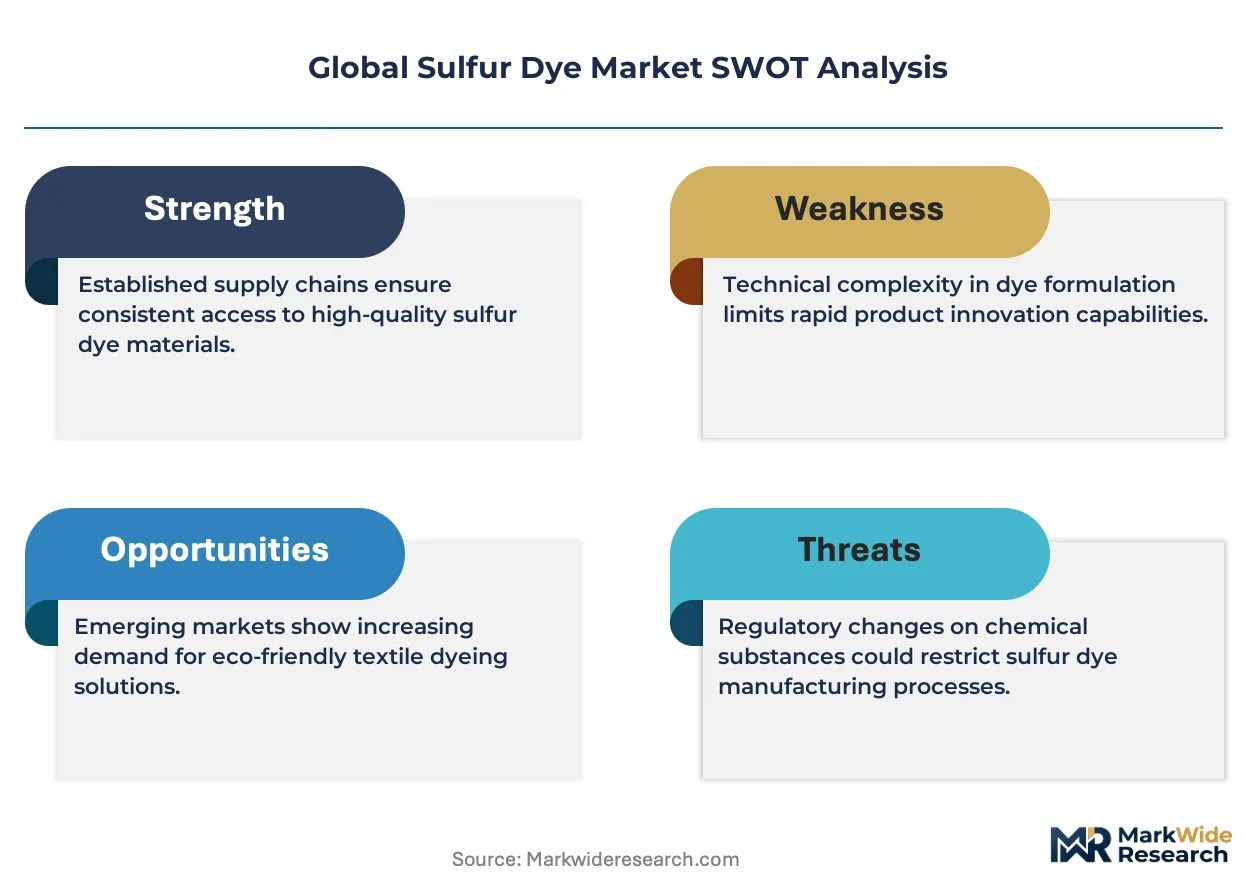
Regulatory frameworks significantly influence product formulation and market access for sulfur dyes. The European Union's REACH regulation restricts certain hazardous chemicals, while China's Ministry of Ecology and Environment (MEE) imposes stringent standards on wastewater discharge from dyeing facilities. These rules push manufacturers toward developing eco-friendlier, low-sulfide dye formulations. Navigating this complex environmental compliance landscape while managing raw material costs is the central strategic challenge for all producers.
Market Dynamics
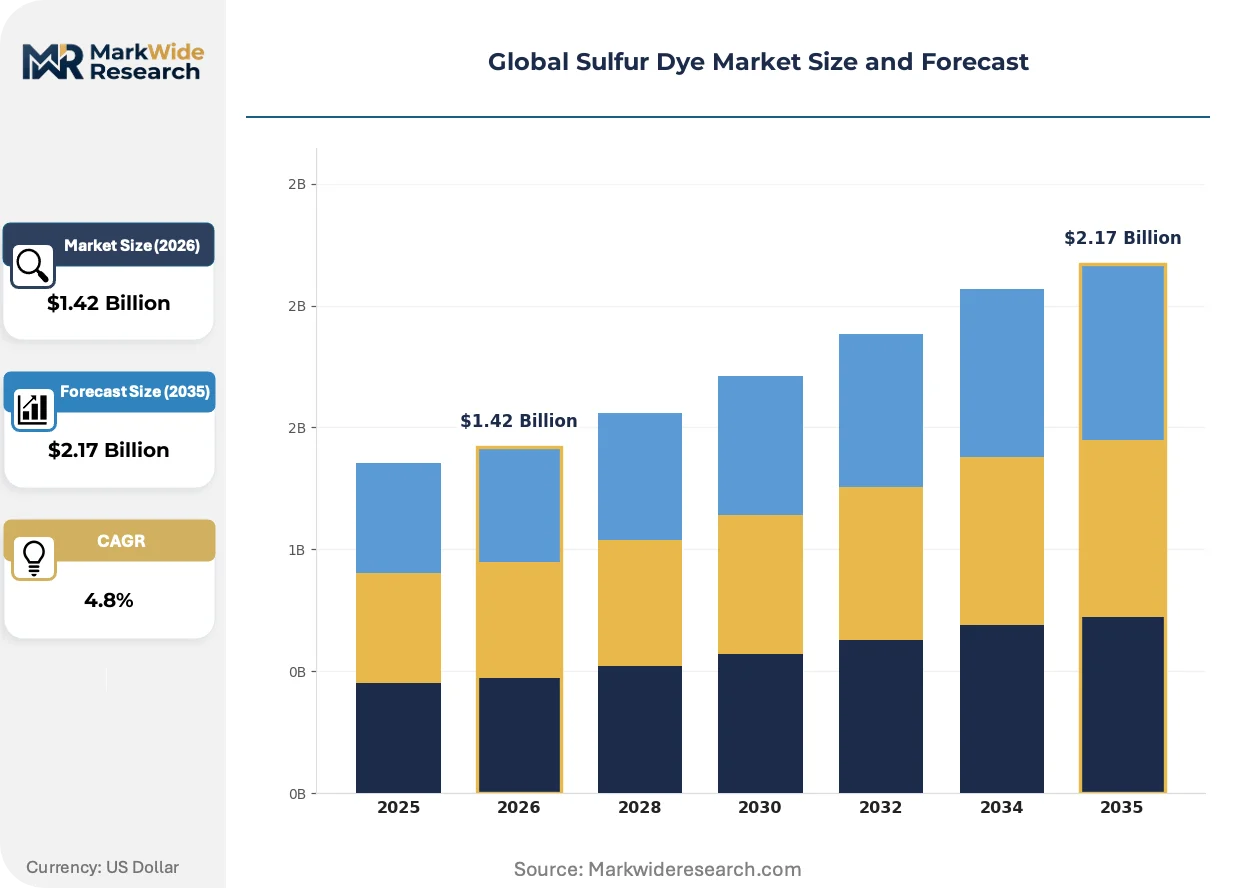
The market's primary dynamic is the conflict between the cost-efficiency of conventional sulfur dyes and the escalating pressure from environmental regulations. Stricter enforcement by bodies like China's MEE is forcing a technological and supply chain recalibration toward cleaner liquid formulations.
Growth Catalysts
- Sustained Denim Demand:The global garment industry's consistent need for coloring cotton denim fabrics provides a stable consumption base, particularly in large textile production centers like India and Bangladesh.
- Pre-Reduced Liquid Dyes:The development of liquid dye formulations improves process efficiency and environmental performance for textile mills by reducing water consumption and simplifying wastewater treatment.
- Supply Chain Consolidation:Stricter environmental rules in China are forcing smaller, less compliant powder dye manufacturers to exit, creating opportunities for larger producers in India and elsewhere to capture market share.
Market Restraints
- Raw Material Price Volatility:The cost of key inputs like sodium sulfide and other chemical intermediates is subject to fluctuations in the broader petrochemical and industrial chemical markets, impacting producer margins.
- Limited Color Range:Sulfur dyes produce a relatively narrow and muted palette of colors, primarily dark shades, which restricts their application compared to more versatile reactive or vat dyes.
- Substitution by Alternative Dyes:For applications requiring bright colors, higher fastness properties, or simpler processing on non-cellulosic fibers, competing dye classes present a significant substitution threat.
Strategic Opportunities
- Sulfide-Free Formulations:Developing and commercializing eco-friendly sulfur dyes with low or zero sulfide content creates a significant opportunity to meet stringent standards like the ZDHC MRSL.
- Expansion in Technical Textiles:Exploring applications beyond apparel, such as in the coloration of paper, cardboard, or specific types of leather, offers a pathway for market diversification.
- Growth in Southeast Asian Hubs:Targeting emerging textile manufacturing centers in Vietnam and Indonesia provides an avenue for growth as these nations expand their garment export operations.
Industry Challenges
- Complex Regulatory Compliance:Manufacturers face the operational challenge of developing dye formulations that can simultaneously meet the divergent chemical restriction lists of the EU's REACH regulation and other national standards.
- Wastewater Treatment Investment:The high capital cost for textile mills to install and operate advanced effluent treatment plants capable of handling sulfur dye wastewater remains a significant barrier to adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sulfur Dye Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Paste, Flake, Liquid Application: Textiles, Leather Coloring, Paper Industry, Printing Inks End User Industry: Garment Manufacturers, Footwear Producers, Upholstery Makers, Craft Workshops Packaging Type: Bag, Drum, Plastic Container, Bulk Tank |
| Companies Covered | Sinochem Tianjin Co., Ltd., Archroma, Nippon Kayaku Co., Ltd., Atul Ltd, Qingdao Sanhuan Colorchem Co., Ltd., Venus Dye Chem, DyStar Group, Apco Dye Chem Pvt. Ltd., Balaji Dye Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sulfur Dye Market Strategic Shifts & Innovations
A fundamental shift toward sustainable chemistry is redefining product development and procurement within the sulfur dye market. This evolution is driven by regulatory mandates and brand-level sustainability commitments, prioritizing environmental performance alongside cost and color fastness.
Pre-reduced liquid sulfur dyes are advanced formulations that eliminate the need for on-site chemical reduction. Denim manufacturers and industrial-scale textile mills are steadily adopting these products to enhance workplace safety and achieve greater process control. This technology is unifying environmental compliance with operational efficiency, creating a new performance benchmark for high-volume cotton dyeing.
The European Union's REACH regulation continues to restrict the use of certain chemicals, influencing dye formulation globally. Its impact forces manufacturers to reformulate products to ensure market access into Europe, often leading to the phase-out of older, less-compliant chemistries. The textile segment, especially exporters in India and Turkey, is most affected, actively seeking REACH-compliant colorant suppliers.
Major apparel brands are increasingly specifying dye inputs that conform to the ZDHC Manufacturing Restricted Substances List (MRSL). This demand-side pressure alters the supplier selection criteria for textile mills, moving beyond simple price-per-kilogram to a total cost of compliance. This behavioral shift is most visible in supply chains catering to North American and European retailers, particularly for denim and casualwear.
Global Sulfur Dye Market Segmentation
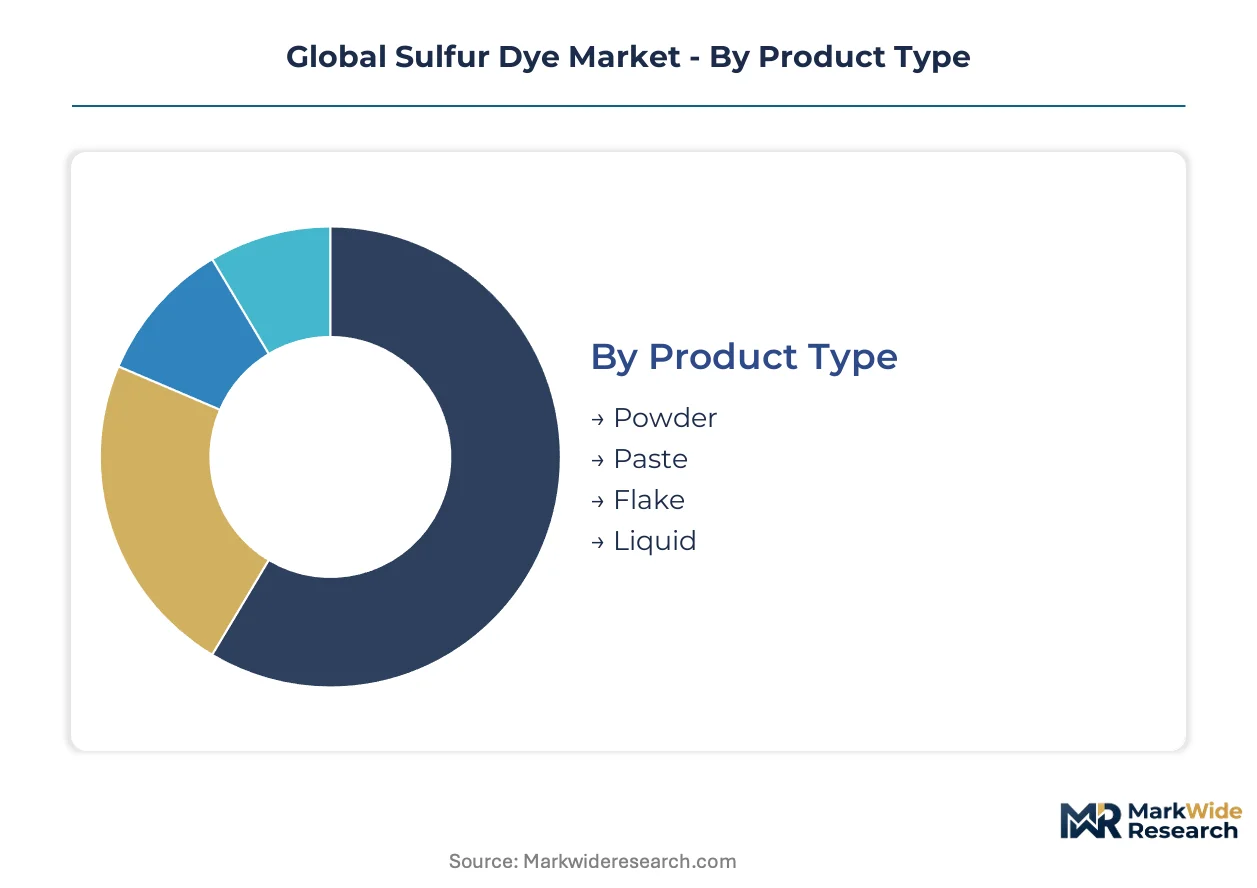
Segmentation offers a granular view of the Global Sulfur Dye Market, detailing how different product forms, applications, end-user industries, and packaging types contribute to its overall structure. This analysis highlights the specific demand drivers and operational considerations within each segment, providing clarity on market dynamics.
Product Type:
The sulfur dye market exhibits a clear division between high-volume, cost-effective powder forms and increasingly adopted liquid variants offering enhanced process efficiency.
- Powder:This traditional form of sulfur dye is a solid particulate product, requiring on-site reduction with sodium sulfide before application. Demand for powder forms remains dominant by volume, particularly in textile production centers like India, due to its cost-effectiveness for large-scale operations.
- Liquid:These pre-reduced, ready-to-use formulations eliminate the need for chemical reduction at the textile mill, improving safety and process control. Adoption of liquid dyes is gaining traction among denim manufacturers in Europe and North America, driven by environmental performance and operational efficiency benefits.
- Paste:A semi-solid form of sulfur dye, paste variants offer intermediate handling characteristics between powder and liquid, often favored for specific dyeing processes in smaller textile units.
- Flake:This solid form of sulfur dye is less common than powder but provides a denser, less dusty alternative for bulk handling in some industrial settings.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquid.
Application:
Different applications leverage sulfur dyes for distinct properties, ranging from robust coloration in textiles to specialized uses in paper and leather.
- Textiles:Sulfur dyes are primarily used for coloring cellulosic fibers, with significant application in cotton fabrics, especially denim. The global garment industry's sustained need for durable, cost-effective denim coloration in countries such as Bangladesh and Vietnam drives this segment.
- Leather Coloring:These dyes provide deep, consistent shades for various leather products, offering good lightfastness and resistance to rubbing. Demand stems from tanneries producing leather for footwear and accessories in regions with established leather industries like Italy.
- Paper Industry:Sulfur dyes are employed for coloring paper and cardboard products, particularly where deep, dark shades are required for packaging or specialty papers. This application is driven by manufacturers seeking economical coloration solutions for industrial paper goods.
- Printing Inks:A smaller but specialized application involves using sulfur dyes in certain printing ink formulations, particularly for textile printing or specific industrial marking inks.
The largest volume of sulfur dye consumption is observed in Textiles, while Printing Inks represent a niche but expanding application.
End User Industry:
End-user industries dictate product specifications and procurement volumes, with large-scale manufacturing driving the bulk of demand for sulfur dyes.
- Garment Manufacturers:This industry segment constitutes the vast majority of sulfur dye consumption, primarily for coloring cotton denim used in jeans, jackets, and other apparel. Major garment production hubs in India, China, and Southeast Asia are significant consumers.
- Footwear Producers:Sulfur dyes are utilized in the coloration of canvas and leather components for shoes, providing durable and cost-effective color. This segment includes manufacturers creating casual and work footwear.
- Upholstery Makers:Manufacturers of upholstered furniture and automotive interiors use sulfur dyes for coloring heavy cotton or blended fabrics requiring good fastness properties. Demand is stable from established furniture production regions.
- Craft Workshops:Smaller-scale producers and artisans use sulfur dyes for specialty dyeing projects, valuing their unique color palette and ease of use in controlled environments.
Significant demand originates from Garment Manufacturers, with specialized requirements met by Footwear Producers.
Packaging Type:
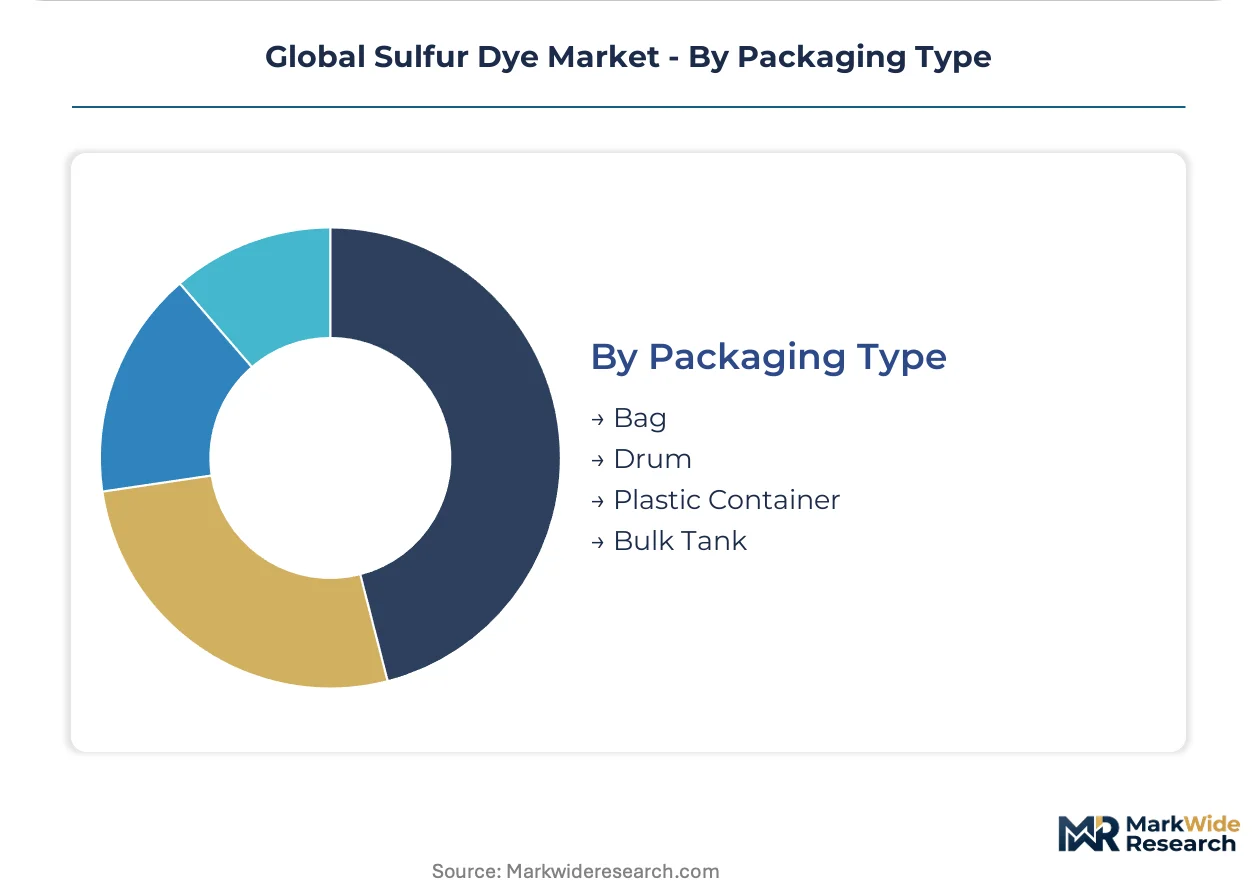
Packaging configurations are primarily driven by the scale of industrial use and the physical form of the sulfur dye, impacting logistics and handling efficiency.
- Bulk Tank:Large industrial users, particularly those consuming liquid sulfur dyes, employ bulk tanks for efficient storage and direct integration into automated dyeing processes. This packaging reduces handling costs and environmental exposure.
- Bag:Powdered sulfur dyes are commonly packaged in bags, typically for smaller to medium-scale industrial users or for export. These bags facilitate manual handling and batch processing in textile mills.
- Drum:Both liquid and powdered sulfur dyes can be supplied in drums, offering a robust packaging solution for transport and storage, particularly for international shipments or medium-volume consumption.
- Plastic Container:Smaller volumes of liquid or paste sulfur dyes are often supplied in plastic containers, suitable for craft workshops or specialized industrial applications requiring precise dosing.
Industrial clients with high consumption rates primarily utilize Bulk Tank packaging, whereas smaller batch users often prefer Bag formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global sulfur dye market finds significant demand in regions with robust textile manufacturing and chemical production capabilities. These areas benefit from established supply chains for key raw materials like sodium sulfide. Such concentrations enable efficient production and distribution of various dye formulations.
India
India's extensive textile manufacturing sector drives substantial demand for sulfur dyes, especially for cost-effective denim coloration. The country's PLI scheme supports domestic textile production, further stabilizing dye consumption. Textile clusters in Gujarat and Tamil Nadu continuously process large volumes of cotton fabrics, requiring steady dye supplies.
China
Chinese textile mills historically consumed significant volumes of sulfur dyes for various fabrics. China's MEE enforces stringent environmental standards, pushing dye manufacturers towards cleaner production methods. Major textile hubs within the Yangtze River Delta are recalibrating operations to meet these evolving regulatory requirements.
Bangladesh
The flourishing garment export industry in Bangladesh creates a consistent need for sulfur dyes, particularly for denim and other cotton apparel. National environmental policies are increasingly focusing on sustainable practices within textile processing. Manufacturing zones around Dhaka and Chittagong are expanding their capacities for dyeing and finishing operations.
Vietnam
Emerging textile manufacturing centers in Vietnam are increasing their consumption of sulfur dyes for export-oriented garment production. Vietnam's environmental protection laws guide industrial development, influencing dye procurement choices. Textile and garment production facilities near Ho Chi Minh City are attracting new investments and expanding operations.
Germany
Germany's advanced textile sector and chemical industry drive demand for high-performance and eco-friendly sulfur dye formulations. The EU's REACH regulation significantly influences product development and compliance for all chemical suppliers. Chemical producers in Baden-Württemberg and North Rhine-Westphalia specialize in sustainable dyeing innovations.
Global Sulfur Dye Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue sustainable dyeing solutions and specialized formulations. The market structure exhibits consolidation among larger multinational entities and fragmentation among regional and local suppliers. Multinational specialists focus on advanced liquid dye technologies, while large-scale regional players maintain cost leadership in powder forms. Companies pursue capacity expansion in strategic textile hubs and diversify their product portfolios to meet evolving regulatory demands.
Within the multinational specialist tier, Archroma and DyStar Group exemplify global reach and a focus on sustainable chemical solutions. Archroma, a Swiss-based entity, represents innovation in eco-friendly dyeing processes for the textile industry. DyStar Group, with its global distribution network, occupies a position as a comprehensive colorant supplier to major textile production hubs. Atul Ltd, an Indian chemical conglomerate, anchors the large-scale regional producer segment, serving both domestic and export markets with its extensive manufacturing capabilities.
| Leading Market Players |
|---|
| Sinochem Tianjin Co., Ltd. |
| Archroma |
| Nippon Kayaku Co., Ltd. |
| Atul Ltd |
| Qingdao Sanhuan Colorchem Co., Ltd. |
| Venus Dye Chem |
| DyStar Group |
| Apco Dye Chem Pvt. Ltd. |
| Balaji Dye Chem |
| Others |
Cost & Logistics Intelligence
Major apparel brands' demand for ZDHC MRSL-compliant dye inputs compels manufacturers to invest in advanced formulations. This shift influences pricing structures across the sulfur dye supply chain, favoring cleaner products.
Pricing Analysis
After-sales technical support and formulation assistance are often bundled with premium liquid sulfur dye offerings. The market primarily operates on a contract-based long-term offtake model for large textile mills, while smaller buyers often access commodity spot pricing. Price differentiation stems from certification levels, particularly REACH compliance and ZDHC MRSL adherence, alongside volume scale. Pricing softness affects conventional powder forms due to regulatory pressures, whereas advanced liquid variants command a premium. Garment manufacturers catering to North American and European retailers show lower price sensitivity for compliant products.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of sulfur dyes, particularly for bulk shipments across continents. Global supply concentrates in India and China for powder forms, with specialized liquid formulations originating from European producers like those in Germany. The production of sulfur dyes draws from key inputs such as sodium sulfide and various chemical intermediates. Commodity price volatility for these raw materials represents a structural supply chain risk. Distribution runs through direct sales channels to large textile manufacturers and regional distributors serving smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sulfur dye market presents a consolidation play, driven by stringent environmental regulations like China's MEE standards. These pressures force smaller, less compliant manufacturers to exit, creating opportunities for larger, more agile entities.
For Market Incumbents: Deploy R&D investment into sulfide-free and low-sulfide formulations to meet evolving regulatory demands. Incumbents should expand compliant production capacity in strategic textile hubs like India to counter supply chain disruptions from Chinese consolidation. Diversifying the product portfolio beyond traditional denim to include specialized technical textile applications mitigates the threat from alternative dye classes.
For New Entrants and Emerging Players: Smaller textile units in emerging Southeast Asian hubs, particularly in Vietnam and Indonesia, represent an underserved market. New entrants should target these regions with pre-reduced liquid dye formulations, emphasizing process efficiency and reduced wastewater treatment costs. Developing localized distribution networks and offering comprehensive technical support provides a strong go-to-market angle against established powder dye suppliers.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to capitalize on industry consolidation over the next five to ten years. Investors should target vertically integrated mid-cap specialists possessing robust R&D capabilities in eco-friendly, low-sulfide dye formulations. A key signal to watch is the acceleration of M&A activity among regional producers, indicating intensified competition for compliant manufacturing assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Secures supply for the largest textile production base. |
| Green Manufacturing Transition | Meets global regulatory standards like REACH and ZDHC. |
| Long-term Supply Agreement | Stabilizes raw material costs for key chemical intermediates. |
| Joint Venture for Liquid Dye Production | Accelerates adoption of efficient, eco-friendly formulations. |
| Product Portfolio Diversification | Expands market reach beyond traditional denim applications. |
Research Approach
Document review covered customs data, company annual reports, environmental agency guidelines, and textile industry association publications, complemented by interviews. Primary research involved discussions with textile mill procurement managers, dye manufacturers' R&D directors, chemical intermediate suppliers, and apparel brand sustainability officers. This approach ensured bottom-up and top-down triangulation of market insights.
The analytical model produced market size and growth projections across the analysis window, segmented by product type, application, end-user industry, packaging type, and regional regulatory compliance. Compound annual growth rates were derived from regression analysis of historical data and future growth drivers. Key forecast inputs included textile production volumes, denim consumption trends, and environmental regulation stringency.
Revisions become necessary when significant shifts in raw material prices, new regulatory mandates, or disruptive dyeing technologies materialize. Forecasts reflect assumptions documented at the time of publication. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market