

3-Layer Seam Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
3-Layer Seam Tapes Market Insights
Technical support and specification consulting is repositioning how 3-layer seam tape suppliers engage apparel manufacturers, shifting transactions from commodity orders to engineered partnerships. Bemis Associates leverages deep vertical integration into film extrusion and adhesive formulation to sustain margin control across waterproof tape lines. Toray Industries anchors its position through advanced polyurethane lamination R&D, while HiMEL competes on manufacturing scale in Asia-Pacific supply chains. DingZing Advanced Material specializes in heat-activated solutions for industrial protective equipment, occupying a defensible niche in high-temperature applications.
3-Layer seam tapes are composite adhesive strips constructed from a carrier film, a functional middle layer—typically polyurethane or silicone—and a hot-melt or pressure-sensitive adhesive base, designed to seal stitched seams against water ingress while maintaining breathability in finished garments. The polyurethane lamination technology segment leads value contribution due to its dominance in premium waterproof-breathable outerwear, though silicone coating is gaining traction in extreme-temperature workwear where thermal stability matters. Breathable tape holds the largest share among product types, while reflective tape represents the fastest-growing category as safety regulations tighten across European and North American industrial sectors. Technical apparel and protective clothing applications concentrate margin pools, with sportswear serving as the volume anchor.
REACH in Europe, OSHA workplace safety standards in the United States, and China's GB standards for protective clothing collectively shape material compliance requirements and testing protocols for seam tape suppliers seeking cross-border market access. The EU Green Deal and emerging restrictions on perfluorinated chemicals are forcing reformulation timelines across polyurethane and silicone adhesive systems. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer cleanly to another, complicating product platform strategies and regional pricing architectures.
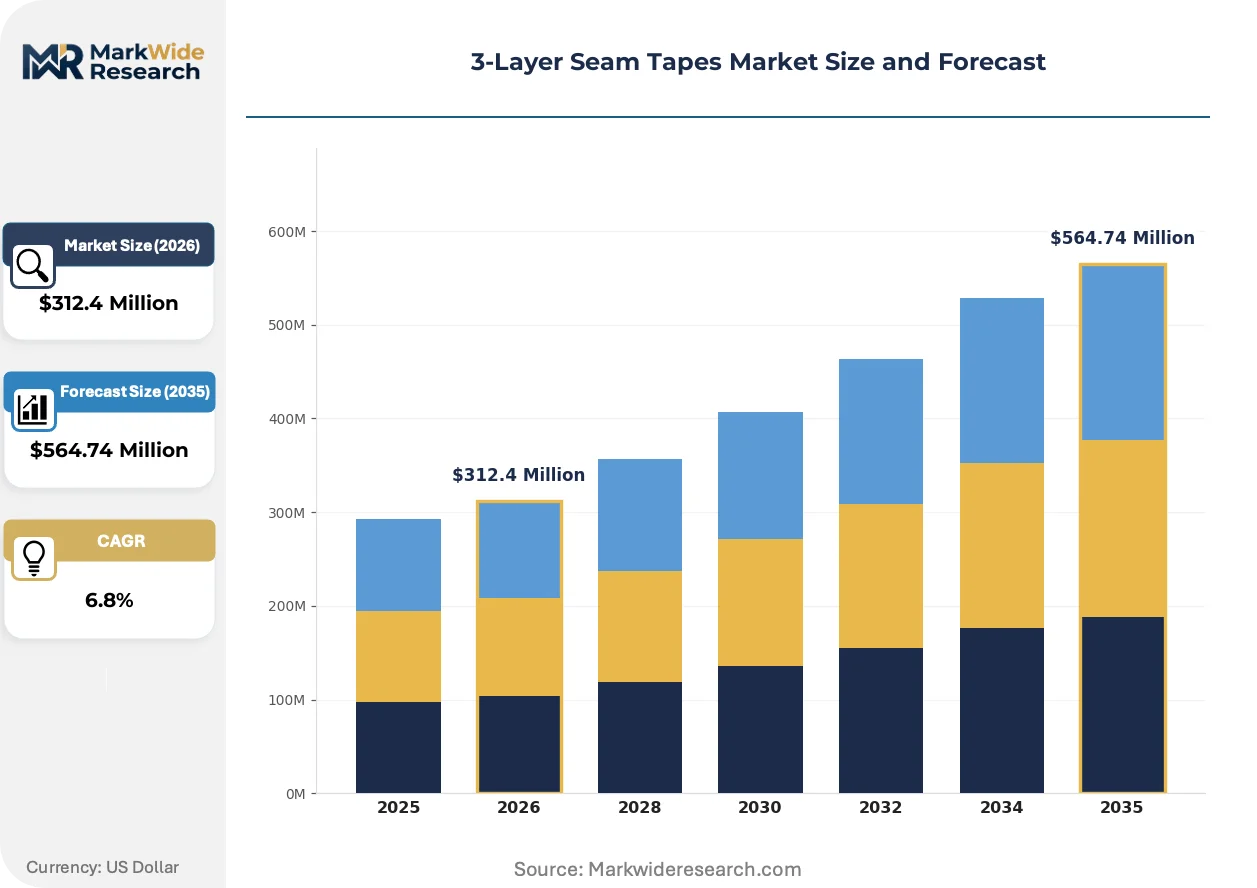
Market Dynamics
REACH compliance deadlines and China's GB standards are compressing reformulation timelines for polyurethane adhesive systems, forcing suppliers to accelerate solvent-free lamination R&D while maintaining seam-seal performance in technical apparel.
Growth Catalysts
- REACH chemical restrictions:European ECHA enforcement against perfluorinated compounds is pulling apparel brands toward certified solvent-free tape systems that satisfy import documentation requirements.
- Industrial protective equipment:Heat-activated polyurethane tapes for high-temperature workwear are expanding addressable demand beyond traditional outdoor apparel into foundry and welding applications.
- German manufacturing concentration:Technical textile clusters around Stuttgart and Munich anchor premium tape consumption for automotive interiors and industrial workwear, creating specification pull-through effects.
Market Restraints
- Polyurethane feedstock volatility:MDI and polyester polyol price swings compress margin predictability for tape converters lacking backward integration into resin production.
- East Asian supply concentration:Heavy reliance on Taiwan and South Korea for carrier film extrusion creates single-source vulnerability during regional logistics disruptions.
- Silicone thermal limitations:Cold-cure silicone adhesives fail to achieve bond strength parity with polyurethane in sub-zero applications, restricting penetration of extreme-climate outerwear.
Strategic Opportunities
- India technical apparel:BIS certification mandates for protective clothing under PLI scheme incentives are opening specification windows for compliant tape suppliers.
- Reflective safety tape:Tightening OSHA visibility standards for US industrial workwear creates incremental demand for combined waterproof-reflective seam sealing.
- Digital specification platforms:Online technical data repositories are compressing buyer research cycles and enabling direct manufacturer-to-brand engagement outside traditional distributor channels.
Industry Challenges
- Adhesive formulation chemist scarcity:Specialized expertise in hot-melt polyurethane reactive systems is concentrating at a handful of European and Japanese suppliers, constraining R&D velocity elsewhere.
- Multi-jurisdiction certification overlap:Divergent testing protocols between REACH, OSHA, and China's GB standards force redundant validation runs that extend product launch timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Layer Seam Tapes Market Trends and Innovations
Digital manufacturing tools and regulatory chemistry shifts are restructuring how 3-layer seam tapes are specified, produced, and validated across technical apparel supply chains.
Hot-melt reactive polyurethane lamination is automating quality consistency in high-speed tape production lines. German automotive textile suppliers are adopting these systems fastest, replacing batch-dependent solvent-based coating. The technology is automating defect detection and reducing manual inspection headcount in continuous-roll manufacturing.
EU Green Deal chemical phase-down schedules are forcing adhesive reformulation across polyurethane and silicone systems. Industrial consequences include accelerated R&D spend and supplier consolidation around labs with in-house polymer synthesis capability. Premium outdoor apparel brands in Scandinavia and the Alps are responding by dual-sourcing from REACH-certified and legacy suppliers during transition periods.
Brand technical teams are conducting direct supplier audits rather than relying on mill certifications for seam-tape performance claims. This bypasses traditional fabric converter gatekeepers and compresses specification cycles from seasonal to continuous review. The pattern is most visible among US and German performance outerwear labels with dedicated materials innovation departments.
3-Layer Seam Tapes Market Segmentation
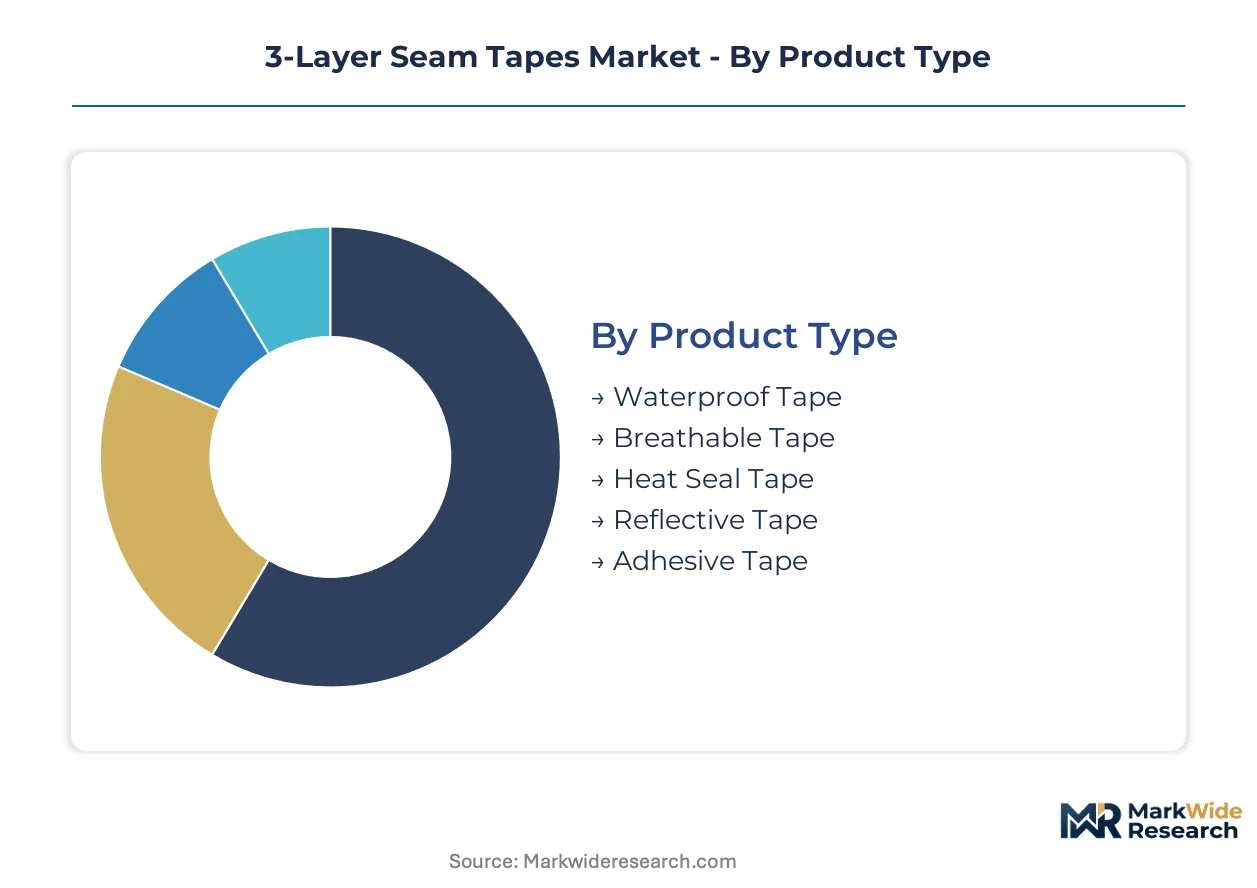
Segmentation in 3-layer seam tapes reveals how material specifications and end-use performance requirements fragment demand across distinct technical tiers. Manufacturers configure tape formulations, adhesive chemistries, and carrier films to match the durability, breathability, and regulatory compliance profiles of specific garment categories.
Product Type:
Replacement cycles vary sharply across product types, with industrial workwear demanding annual re-taping while premium outdoor apparel operates on multi-season durability specifications.
- Breathable Tape:Microporous polyurethane membranes bonded to carrier films allow moisture vapor transmission while blocking liquid water ingress. Technical apparel manufacturers in Germany and the United States specify these for premium waterproof-breathable shells where comfort under exertion drives repurchase intent.
- Reflective Tape:Glass bead or microprismatic layers laminated to seam-sealing substrates combine visibility compliance with waterproofing. Industrial workwear producers in the United States face tightening OSHA visibility mandates that accelerate specification of combined waterproof-reflective systems for highway and railway maintenance crews.
- Waterproof Tape:Non-breathable barrier films with aggressive hot-melt adhesives for cost-sensitive rain gear and disposable protective equipment.
- Heat Seal Tape:Activated by thermal compression during garment finishing, eliminating stitch holes in critical seam junctions for diving suits and dry bags.
- Adhesive Tape:Pressure-sensitive formulations for field repair kits and aftermarket seam reinforcement in outdoor retail channels.
Breathable tape sits at the top of the volume ranking, with reflective tape climbing the fastest.
Technology:
Cost tiers separate technology adoption, with solvent-free polyurethane systems commanding premium positioning against commodity polyethylene alternatives.
- Polyurethane Lamination:Reactive hot-melt or solvent-based coating of aromatic or aliphatic polyurethane onto polyester or polyamide carriers. REACH compliance deadlines in Europe are forcing suppliers toward waterborne and hot-melt reactive systems that eliminate residual isocyanate exposure during garment production.
- Silicone Coating:Platinum-cured or condensation-cure elastomer layers applied to woven or knit substrates. Foundry and welding workwear producers specify these for thermal stability above 200°C where polyurethane degrades, though cold-cure variants struggle with sub-zero bond strength.
- Polyethylene Backing:Extruded low-density films for single-use protective gowns and budget rainwear where breathability is not specified.
- Acrylic Adhesive:Water-based pressure-sensitive systems for temporary seam sealing and repair applications with limited wash durability.
- Film Lamination:Multi-layer coextrusion of functional barriers without separate adhesive coating, reducing production steps for high-volume converters.
Polyurethane lamination dominates the value tier, while silicone coating gains share fastest in heat-stress industrial segments.
Application:
Application segmentation tracks customer maturity, with established outdoor brands driving specification standardization while emerging protective clothing markets generate format experimentation.
- Technical Apparel:Garments engineered for specific performance envelopes including military, emergency services, and professional alpine guides. Scandinavian defense procurement and German police equipment tenders specify seam-tape performance to EN 14360 water-column standards, creating certification barriers for uncertified suppliers.
- Protective Clothing:Chemical, biological, and thermal hazard ensembles for industrial and first-responder use. China's GB 24539 standard for protective clothing against chemical hazards mandates seam-seal integrity testing that favors tape systems with documented permeation resistance.
- Sportswear:Ski, cycling, and running outerwear where brand marketing emphasizes waterproof ratings as consumer-facing specifications.
- Workwear:General industrial uniforms with basic water resistance requirements and shorter replacement cycles.
- Outdoor Gear:Tents, backpacks, and sleeping bag shells where seam geometry complexity favors tape over welded alternatives.
Technical apparel commands the highest specification density, with protective clothing expanding most quickly on regulatory tailwinds.
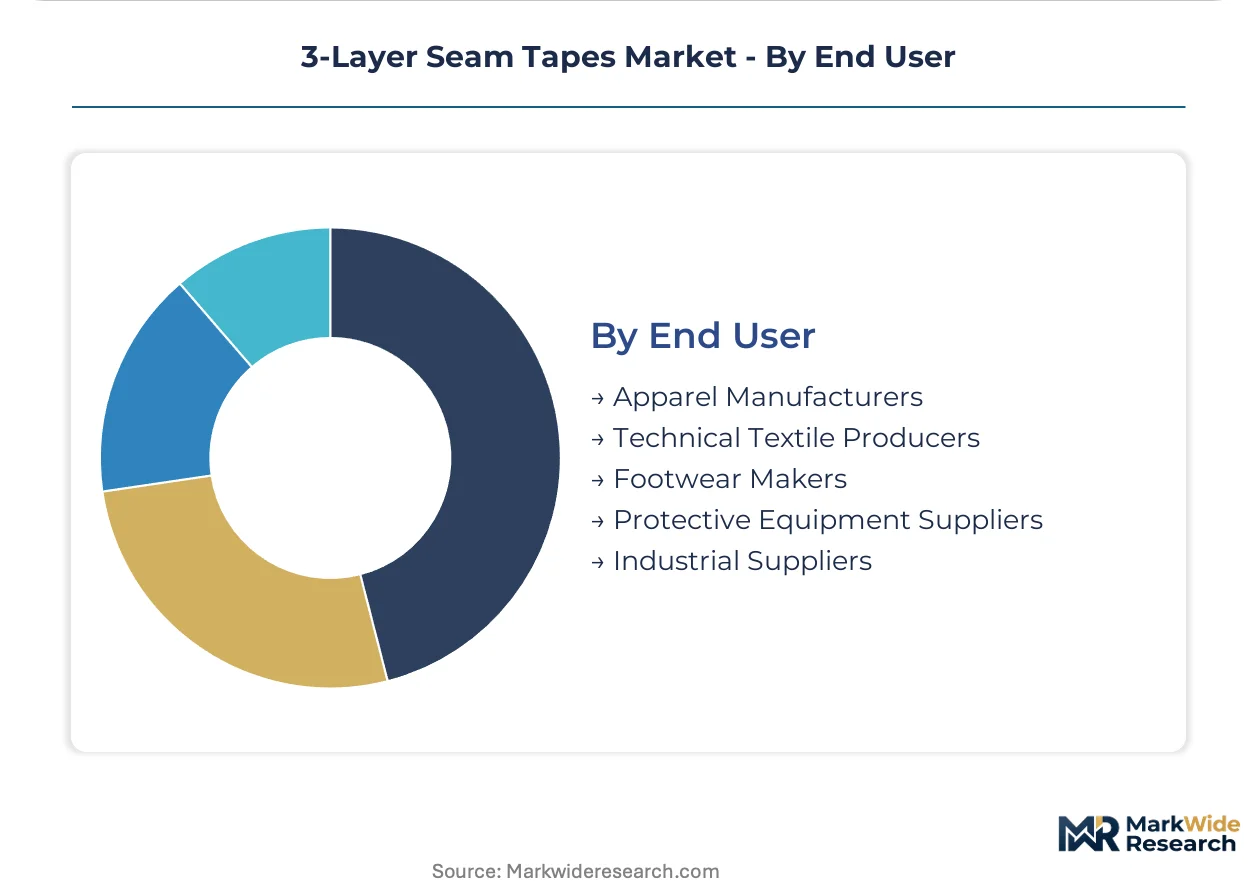
End User:
Customer type determines procurement modality, with integrated apparel manufacturers conducting direct supplier audits while industrial distributors aggregate fragmented protective equipment demand.
- Apparel Manufacturers:Vertically integrated outerwear brands and contract cut-and-sew operations with in-house seam-sealing equipment. US and German performance labels now bypass fabric converters to audit tape suppliers directly, compressing specification cycles.
- Technical Textile Producers:Automotive interior and medical textile suppliers requiring heat-activated tapes for complex three-dimensional seam geometries. Stuttgart-area automotive textile clusters anchor premium consumption for seat cover and airbag applications.
- Footwear Makers:Waterproof boot manufacturers applying tape to liner seams and gusset constructions.
- Protective Equipment Suppliers:Distributors aggregating demand from small and medium industrial laundries serving fragmented end-user bases.
- Industrial Suppliers:Maintenance, repair, and operations channels stocking adhesive tapes for field repair and aftermarket applications.
Apparel manufacturers generate the deepest specification engagement, with technical textile producers showing the steepest expansion trajectory on automotive and medical diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium technical textile demand while China scales solvent-free production capacity, revealing a bifurcation between specification leadership and manufacturing volume across the 3-layer seam tapes landscape.
Germany
Automotive interior suppliers and industrial workwear producers around Stuttgart and Munich anchor European premium tape consumption. REACH enforcement through ECHA accelerates solvent-free polyurethane lamination adoption among local converters. The Baden-Württemberg technical textile cluster drives specification pull-through for heat-activated seam sealing in seat cover and airbag applications.
United States
OSHA workplace safety standards tighten visibility mandates for highway maintenance and railway crews, expanding combined waterproof-reflective tape specifications. Performance outerwear brands in the Pacific Northwest and Northeast Corridor conduct direct supplier audits, bypassing traditional fabric converter channels. Colorado-based alpine equipment manufacturers stress-test seam-seal durability for military and emergency services procurement.
China
GB standards for protective clothing against chemical hazards mandate seam-seal integrity testing that favors documented permeation-resistant tape systems. The Yangtze River Delta and Pearl River Delta manufacturing belts scale hot-melt reactive polyurethane production lines. MIIT industrial policy incentives push domestic suppliers toward waterborne adhesive technologies to meet dual carbon goals.
India
BIS certification requirements for protective clothing under PLI scheme incentives open specification windows for compliant tape suppliers. Maharashtra and Gujarat industrial corridors attract technical apparel manufacturing investments from European brands seeking supply chain diversification. Tamil Nadu's textile processing hubs experiment with heat-seal tape formats for diving and watersports equipment exports.
3-Layer Seam Tapes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium technical apparel channels favoring specification-integrated suppliers while industrial workwear aggregates through distributor networks. The vendor base organizes around three archetypes: vertically integrated film-and-adhesive compounders, regional tape converters sourcing carrier materials externally, and niche heat-activated specialists serving protective equipment verticals. Consolidation pressures concentrate among mid-scale European and Japanese players lacking captive resin production. Strategic moves center on backward integration into polyurethane synthesis and geographic expansion into Indian technical textile corridors.
Among the named participants, Bemis Associates exemplifies the integrated compounder archetype through upstream control over film extrusion and adhesive formulation. Toray Industries anchors advanced materials positioning through polyurethane lamination research infrastructure. DingZing Advanced Material occupies the heat-activated specialization tier, representing defensible niche positioning in high-temperature industrial applications.
| Leading Market Players |
|---|
| Bemis Associates |
| Toray Industries |
| HiMEL |
| SEALON |
| LOXY AS |
| Gerlinger Industries |
| DingZing Advanced Material |
| Adhesive Films |
| San Chemicals |
| Others |
Pricing and Supply Chain Analysis
Hot-melt reactive polyurethane lamination is simultaneously compressing production costs and redistributing supply concentration toward converters with captive resin synthesis capability. REACH-mandated solvent phase-outs in Europe and MIIT dual carbon targets in China are forcing capital-intensive retooling that favors integrated compounders over merchant adhesive buyers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-grade breathable tapes while premium polyurethane systems retain margin insulation through certification scarcity. Three-tier pricing structure across REACH-certified premium, standard industrial-grade, and economy polyethylene tiers separates specification-intensive technical apparel from commodity workwear. Pricing pressure stems from MDI and polyester polyol feedstock volatility that squeezes converters lacking backward integration. Industrial distributors serving fragmented protective equipment laundries exhibit highest price sensitivity, whereas German automotive textile clusters prioritize performance consistency over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from US and German performance outerwear brands are fragmenting carrier film procurement across Taiwan, South Korea, and emerging Indian extrusion capacity. Tape production draws from aromatic polyurethane resins, polyester carrier films, and reflective microprismatic layers as core inputs. Single-source vulnerability concentrates in Taiwan's specialty film extrusion base, exposing converters to regional logistics disruption. Distribution runs through technical textile distributors in Europe, direct manufacturer-to-brand channels in North America, and industrial equipment aggregators in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European production with elevated regulatory compliance costs and scaled Chinese manufacturing with carbon-transition investment requirements.
For Market Incumbents: Hedge margin erosion from solvent-free reformulation costs by securing captive polyurethane synthesis capacity in Germany or Japan. Accelerate certification pre-qualification for India's BIS protective clothing standards before PLI scheme incentives saturate specification windows. Prioritize direct technical audit relationships with US Pacific Northwest outerwear brands to bypass fabric converter gatekeepers.
For New Entrants and Emerging Players: Mid-sized Indian protective equipment distributors represent an underserved buyer archetype with unconsolidated tape procurement and limited REACH-certified supplier access. Foundry and welding workwear segments in Germany's industrial belt offer lowest competitive density for heat-activated silicone specialists. Pursue specification partnerships with Maharashtra-based technical apparel contract manufacturers as European brands diversify supply chains.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional tape converters lacking backward integration but holding established mill relationships. Five-to-ten-year viability hinges on successful solvent-free transition completion and Indian regulatory certification capture. Monitor ECHA enforcement intensity against perfluorinated compound residues as inflection indicator for accelerated supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Synthesis | Captive resin production insulates margins from MDI price volatility and REACH reformulation timelines. |
| REACH Certification Pre-Qualification | Early solvent-free system validation secures specification lock-in with Scandinavian defense and German police tenders. |
| Direct Manufacturer-to-Brand Engagement | Bypassing fabric converters compresses sales cycles and captures technical apparel specification authority. |
| India BIS Certification Investment | PLI scheme incentives create first-mover advantage in protective clothing compliance windows. |
| Heat-Activated Silicone R&D Expansion | Thermal stability above 200°C opens foundry and welding workwear segments where polyurethane degrades. |
Research Methodology
Coverage spans Germany, the United States, China, and India, with primary inputs from each market gathered through structured interviews with adhesive formulation chemists, technical apparel procurement directors, industrial workwear distributors, and automotive textile engineers. Secondary validation draws from ECHA substance restriction databases, OSHA workplace safety standard filings, Chinese GB standard technical committees, and BIS certification registries. Bottom-up segment sizing triangulates against top-down chemical industry trade flow analysis.
Granularity-level modeling disaggregates volume and value across product type, lamination technology, application end-use, and end-user procurement modality throughout the forecast period. CAGRs derive from segment-specific demand elasticity coefficients and input cost trajectory assumptions. Industry-specific forecast inputs include REACH chemical phase-down schedules, MIIT dual carbon policy implementation intensity, and BIS PLI scheme incentive disbursement patterns.
Underlying measurement precision varies by segment; breathable and reflective tape categories carry tighter precision than heat-seal and adhesive repair formats due to established end-use reporting. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and feedstock price stabilization. Deviation in ECHA perfluorinated compound restriction timelines or Taiwan logistics corridor stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.