
 Dual Energy X-Ray Absorptiometry Market | 2026-2036
Dual Energy X-Ray Absorptiometry Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Energy X-Ray Absorptiometry Market Intelligence
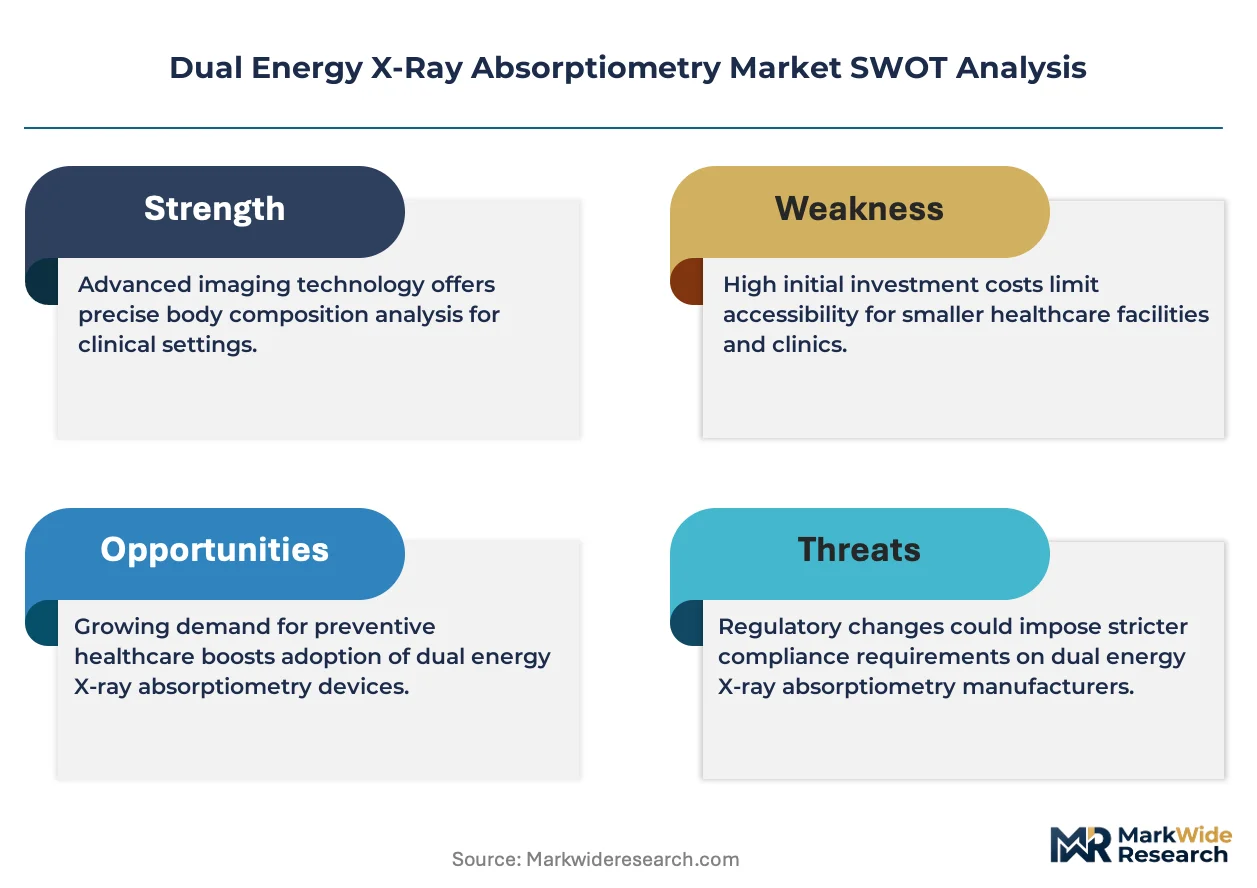
FDA 510(k) premarket notification is bifurcating competitive access between established manufacturers and newer entrants seeking clinical validation. GE Healthcare leverages its installed base of imaging platforms to cross-sell DXA upgrades across hospital networks. Hologic sustains technology leadership through proprietary detector arrays and software analytics for fracture risk assessment. Fujifilm competes by extending its digital radiography expertise into compact DXA systems for outpatient clinics.
Dual energy x-ray absorptiometry measures bone mineral density and body composition by exposing the patient to two distinct x-ray energy levels and calculating differential tissue attenuation. The technique generates precise areal bone mineral density readings in grams per square centimeter, primarily serving osteoporosis diagnosis, fracture prediction, and metabolic disease monitoring in clinical settings. Bone densitometers anchor the product landscape, while portable units represent the fastest-expanding configuration as point-of-care testing migrates beyond radiology departments. Diagnostic centers capture disproportionate margin pools compared to hospitals due to higher test throughput and dedicated reimbursement coding for outpatient bone density services.
FDA 510(k) requirements and IEC 60601-1-3 radiation safety standards govern device approval and electromagnetic compatibility for DXA systems marketed in the United States. The Centers for Medicare and Medicaid Services maintains specific reimbursement codes for bone mass measurement that directly influence provider purchasing cycles and equipment refresh rates. Stakeholders must monitor evolving clinical guideline revisions from the International Society for Clinical Densitometry that periodically redefine diagnostic thresholds and expand screening eligibility criteria.
Market Dynamics
Medicare reimbursement policy for bone mass measurement is concentrating purchasing authority within hospital procurement departments, compressing vendor negotiation cycles and accelerating equipment refresh timelines across outpatient networks.
Growth Catalysts
- Osteoporosis screening mandates:CMS reimbursement codes for bone density testing in outpatient settings drive system deployment across United States hospital networks. Physician practice guidelines from the International Society for Clinical Densitometry expand screening eligibility criteria annually.
- Detector array miniaturization:Solid-state detector technology enables portable DXA configurations for point-of-care deployment outside radiology departments. Clinic-based testing reduces patient travel burden and improves screening compliance rates.
- Body composition analysis:Metabolic disease monitoring applications extend DXA utility beyond osteoporosis into obesity management and sarcopenia assessment. Endocrinology practices represent an emerging demand vertical for multi-function systems.
Market Restraints
- Capital equipment intensity:Full-body DXA systems require substantial upfront investment, constraining independent diagnostic center expansion. Equipment financing costs compress margins for smaller outpatient operators.
- Radiation safety compliance:IEC 60601-1-3 electromagnetic compatibility standards impose lengthy certification timelines for new device submissions. Manufacturers face extended validation periods before commercial release.
- Trained technologist scarcity:Certified bone densitometry operators require specialized training in patient positioning and quality control protocols. Workforce gaps limit testing throughput expansion in rural service areas.
Strategic Opportunities
- Mobile screening units:Deployable DXA systems enable community health programs to reach underserved populations outside fixed clinical infrastructure. Medicare preventive service coverage supports reimbursement for mobile bone density testing.
- Pediatric bone health assessment:Childhood osteoporosis and metabolic bone disease monitoring represents an underpenetrated application segment. Modified software algorithms adapt adult reference databases for adolescent skeletal evaluation.
- Artificial intelligence integration:Machine learning tools for automated vertebral fracture detection and risk stratification enhance diagnostic workflow efficiency. AI-assisted image analysis reduces interpretation variability between operators.
Industry Challenges
- Inter-device calibration standardization:Measurement variability between DXA manufacturers complicates longitudinal patient monitoring. Cross-calibration protocols require ongoing quality assurance investment.
- Legacy system integration:Hospital information system connectivity demands vary across electronic health record platforms. Custom interface development extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Energy X-Ray Absorptiometry Market |
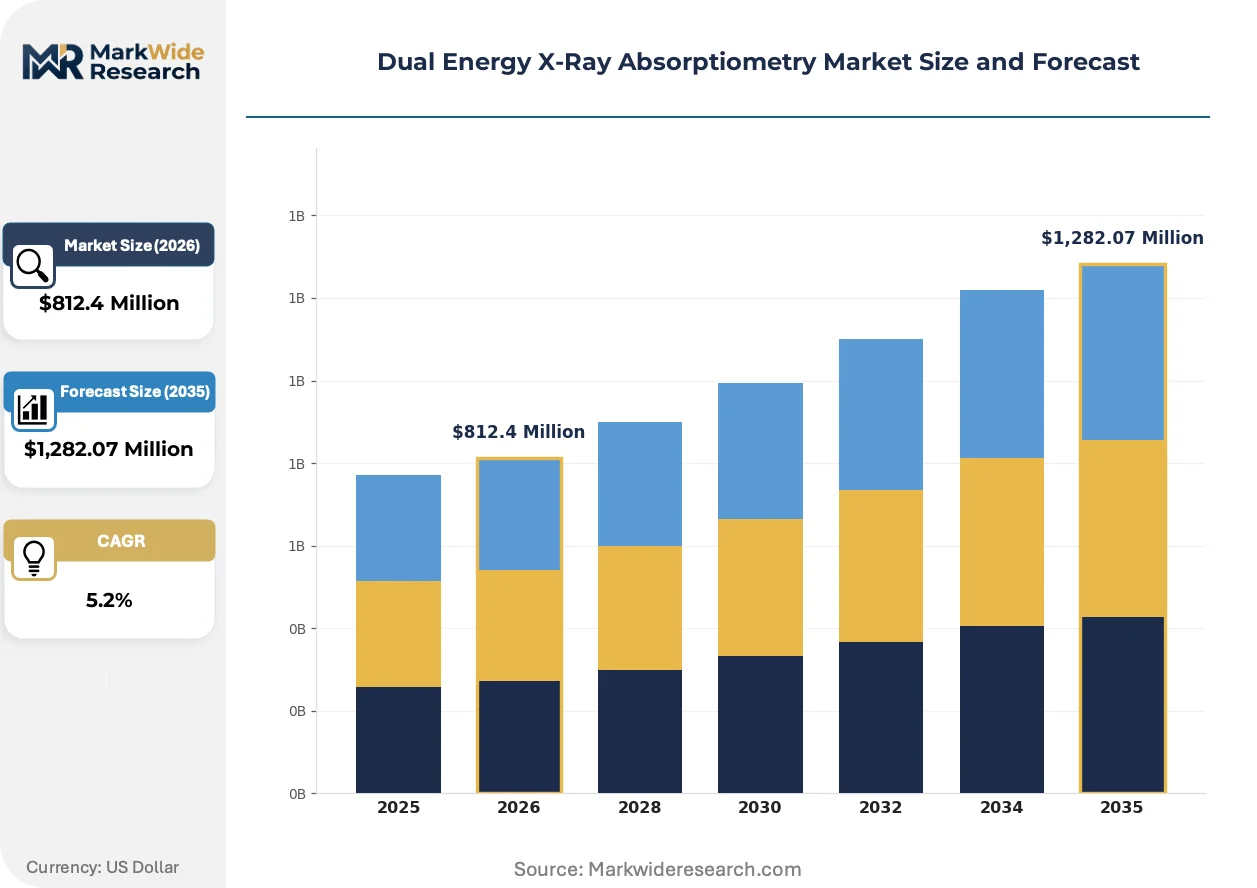
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,282.07 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Densitometers, X-Ray Systems, Table-Top Models, Portable Units End User: Hospitals, Clinics, Research Institutions, Diagnostic Centers Application: Bone Health Assessment, Body Composition Analysis, Osteoporosis Screening, Fracture Risk Evaluation Technology: DXA, Computed Tomography, Ultrasound, MRI |
| Companies Covered | GE Healthcare, Hologic, Fujifilm, OSTEOSYS, Diagnostic Medical Systems, Swissray Medical, Furuno Electric, Medilink, BeamMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Energy X-Ray Absorptiometry Market Strategic Shifts & Innovations
Software analytics and detector hardware are converging to reshape competitive differentiation, with proprietary fracture risk algorithms and compact form factors emerging as primary purchase criteria.
Photon-counting detector technology is bifurcating the installed base between legacy energy-integrating systems and next-generation spectral imaging platforms. Academic medical centers in the United States are piloting photon-counting DXA for research applications. The technology is bifurcating procurement decisions into high-performance research systems and cost-optimized clinical workhorses.
EU Medical Device Regulation (MDR) recertification requirements are compressing the product lifecycle for DXA systems marketed in European member states. Manufacturers must resubmit technical documentation under stricter clinical evidence standards. Compact system categories face disproportionate compliance burden relative to their revenue contribution.
Diagnostic centers are unbundling equipment acquisition from service contracts, negotiating standalone maintenance agreements with third-party service providers. Independent imaging chains in the United States are driving this disintermediation to reduce total cost of ownership. Radiology groups with captive technical staff increasingly self-perform preventive maintenance.
Dual Energy X-Ray Absorptiometry Market Segmentation
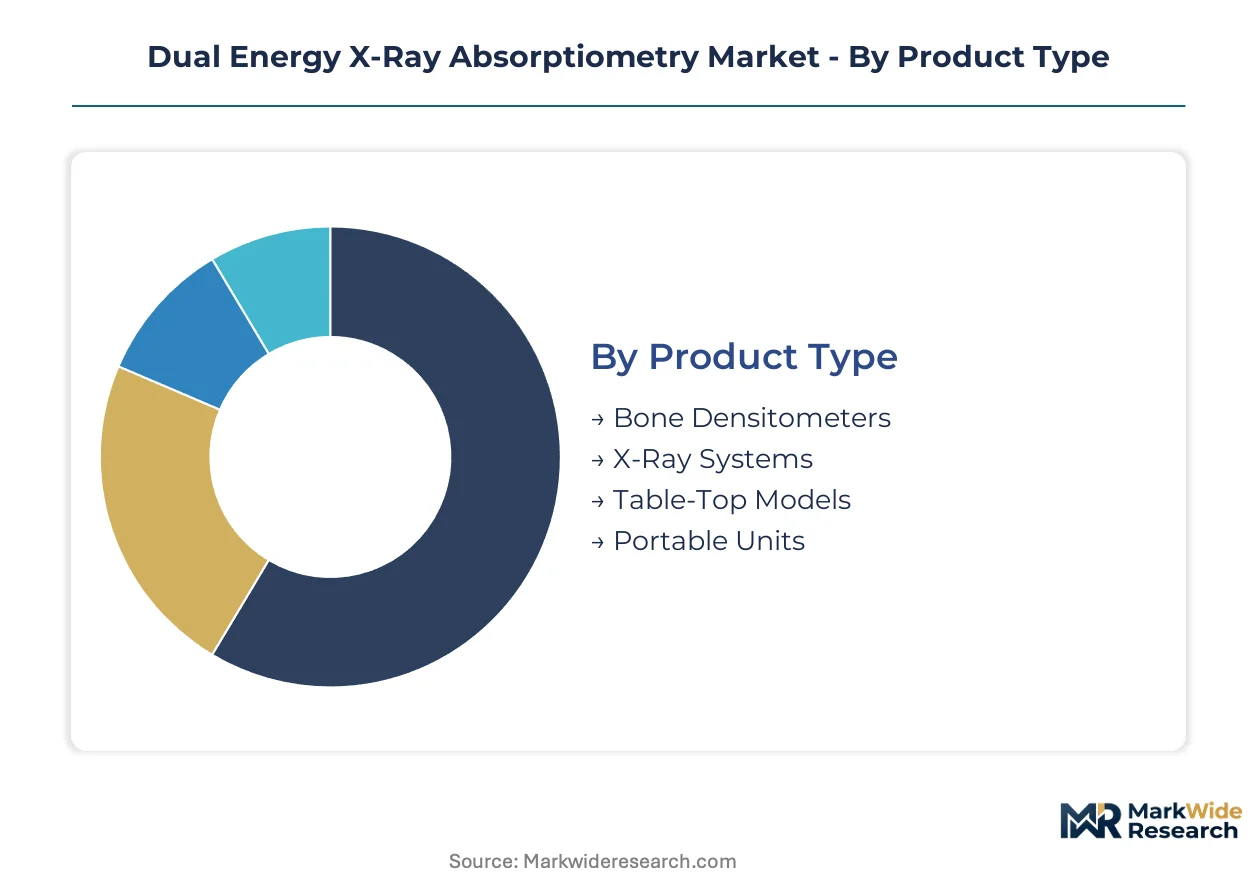
DXA market segmentation reveals distinct procurement patterns across product configurations and clinical settings. Technology differentiation and reimbursement coding create divergent margin profiles that shape manufacturer portfolio prioritization.
Product Type:
Portable configurations are driving export-led demand into emerging outpatient networks, while fixed installations concentrate in domestic hospital infrastructure.
- Bone Densitometers:Full-featured systems with dedicated scanning beds and integrated quality control phantoms anchor hospital radiology departments. Demand clusters in United States academic medical centers pursuing longitudinal research cohorts, constrained by capital equipment intensity and extended procurement cycles.
- Portable Units:Battery-powered configurations with solid-state detector arrays enable deployment outside fixed radiology suites. Diagnostic centers in Germany and France are adopting these for mobile screening programs, supported by EU preventive health funding and streamlined logistics.
- X-Ray Systems:Hybrid platforms combining general radiography with densitometry functionality serve cost-constrained facilities.
- Table-Top Models:Compact units for extremity scanning address space-limited clinic environments.
Bone densitometers command the established base. The steepest expansion runs through portable units.
End User:
Procurement authority concentrates in hospital networks with centralized equipment standardization, while independent operators pursue flexible financing structures.
- Diagnostic Centers:Dedicated imaging chains achieve higher test throughput through specialized scheduling and direct-to-consumer marketing. United States outpatient networks leverage distinct Medicare reimbursement codes for bone mass measurement, generating faster equipment refresh cycles than hospital systems.
- Hospitals:Integrated health systems prioritize interoperability with existing PACS infrastructure and enterprise EHR platforms. Purchasing decisions in United States hospital networks hinge on FDA 510(k) clearance status and service contract integration with broader imaging fleet agreements.
- Clinics:Endocrinology and primary care practices represent emerging point-of-care testing sites.
- Research Institutions:Academic medical centers drive demand for high-precision systems with research-grade calibration protocols.
Hospitals retain the dominant installed base. Diagnostic centers are gaining share fastest through outpatient volume capture.
Application:
Reimbursement policy favors screening applications in United States outpatient settings, while metabolic monitoring expands into self-pay wellness segments.
- Osteoporosis Screening:Population-scale bone density testing protocols drive system deployment in United States Medicare-eligible populations. CMS reimbursement codes for bone mass measurement create predictable revenue streams that justify capital expenditure across hospital outpatient departments.
- Body Composition Analysis:Precision measurement of lean mass, fat mass, and visceral adipose tissue extends DXA utility into obesity management and athletic performance monitoring. Sports medicine clinics in Australia and private wellness centers in United Kingdom are adopting these applications outside traditional osteoporosis pathways.
- Bone Health Assessment:Comprehensive skeletal evaluation including vertebral fracture assessment.
- Fracture Risk Evaluation:Algorithm-based 10-year fracture probability calculation for treatment decision support.
Osteoporosis screening anchors the revenue base. Body composition analysis is climbing the fastest as metabolic disease applications proliferate.
Technology:
Detector architecture and radiation dose profiles differentiate clinical adoption patterns across screening versus diagnostic use cases.
- DXA:Dual-energy x-ray absorptiometry remains the clinical reference standard for areal bone mineral density measurement with established T-score diagnostic thresholds. United States reimbursement policy explicitly favors DXA over alternative modalities for osteoporosis diagnosis, cementing its position in Medicare-covered screening programs.
- Computed Tomography:Quantitative CT provides volumetric bone density measurement independent of bone size, particularly relevant for pediatric and obese populations. Research applications in Japan and South Korea are exploring QCT for hip structural analysis beyond areal density limitations.
- Ultrasound:Radiation-free peripheral screening tool for heel bone assessment.
- MRI:Magnetic resonance-based bone microarchitecture evaluation for research applications without ionizing radiation.
DXA technology commands the established base. Computed tomography is gaining traction fastest in specialized research and pediatric applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement codes for bone mass measurement concentrate purchasing authority in United States hospital networks. EU Medical Device Regulation recertification compresses product lifecycles for European manufacturers. Japan's aging demographic sustains demand for osteoporosis screening infrastructure.
United States
CMS reimbursement policy drives system deployment across hospital outpatient departments and independent diagnostic centers. FDA 510(k) clearance pathways shape manufacturer go-to-market timelines for new device submissions. Academic medical centers in Boston and the Research Triangle pursue longitudinal research cohorts with high-precision systems.
Germany
EU preventive health funding supports mobile screening programs deploying portable DXA configurations. EU Medical Device Regulation recertification imposes stricter clinical evidence standards for technical documentation resubmission. Diagnostic centers in Munich and Hamburg achieve higher test throughput through specialized scheduling and direct-to-consumer marketing.
Japan
Quantitative CT research applications explore hip structural analysis beyond areal density limitations. PMDA regulatory frameworks govern device approval for bone densitometry systems marketed domestically. Academic institutions in Tokyo and Osaka pilot photon-counting DXA for research applications in metabolic disease monitoring.
China
NMPA approval pathways influence commercial release timelines for domestic and imported DXA systems. The country's national healthcare regulator maintains standards for electromagnetic compatibility and radiation safety compliance. Manufacturing clusters in Shanghai and Beijing concentrate assembly operations for compact table-top models serving space-limited clinic environments.
Australia
Sports medicine clinics adopt body composition analysis applications outside traditional osteoporosis pathways. TGA regulatory oversight ensures conformity assessment for medical device market authorization. Private wellness centers in Sydney and Melbourne integrate DXA systems for athletic performance monitoring and obesity management services.
Dual Energy X-Ray Absorptiometry Market Key Industry Players
Player mix skews toward diversified imaging conglomerates with established installed bases. Three manufacturers command disproportionate share through cross-selling leverage and proprietary detector technology. Strategic archetypes bifurcate between full-platform imaging suppliers and compact-system specialists. Competitive moves concentrate on detector array miniaturization and service contract disintermediation.
Among diversified imaging conglomerates, GE Healthcare and Hologic occupy anchor positions exemplifying contrasting scale strategies. GE Healthcare leverages cross-selling integration across hospital imaging fleets. Hologic sustains technology leadership through proprietary software analytics. Fujifilm represents the compact-system specialist archetype extending digital radiography expertise into outpatient clinic configurations.
| Leading Market Players |
|---|
| GE Healthcare |
| Hologic |
| Fujifilm |
| OSTEOSYS |
| Diagnostic Medical Systems |
| Swissray Medical |
| Furuno Electric |
| Medilink |
| BeamMed |
| Others |
Cost & Logistics Intelligence
Ninety-to-one-hundred-twenty-day detector array lead times concentrate pricing power with solid-state sensor foundries in Japan and South Korea, while equipment OEMs pass through component premiums via extended service contract bundling to hospital procurement departments.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked-only) creates the primary spread between premium and standard system tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with photon-counting detector configurations commanding brand premiums over legacy energy-integrating platforms. Cost compression in portable configurations is intensifying because diagnostic centers are unbundling service contracts and negotiating third-party maintenance agreements. Independent imaging chains exhibit highest price sensitivity, while academic medical centers prioritize research-grade calibration protocols over unit economics.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Shanghai and Busan to Long Beach extend inbound component cycles for solid-state detector arrays and precision x-ray tube assemblies. Manufacturing concentration clusters in China, Japan, and Germany, with final assembly drawing from Taiwanese semiconductor foundries for signal processing chips. Single-source vulnerability in high-purity germanium detector substrates creates supply chain risk given limited qualified suppliers. Distribution runs through hospital GPO contracts in the United States and specialized medical device distributors in European member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DXA market expansion sits in early-cycle territory as point-of-care deployment outside radiology departments accelerates screening penetration into primary care and endocrinology practices.
For Market Incumbents: Compound installed base advantages by cross-selling detector upgrades to existing hospital imaging fleets before portable specialists capture outpatient migration. Defend against compact-system specialists by integrating AI-assisted fracture detection software into proprietary analytics platforms. Prioritize MDR recertification investment to maintain European market access as EU regulatory timelines compress product lifecycles.
For New Entrants and Emerging Players: After-sales service disintermediation by independent diagnostic centers represents the most penetrable white-space target, as incumbents resist unbundling maintenance from equipment sales. Mobile screening unit deployment for community health programs offers reimbursement-aligned entry into United States Medicare preventive services. Pursue direct-to-clinic sales models bypassing hospital procurement committees to accelerate portable unit adoption in endocrinology practices.
For Investors and Strategic Acquirers: Long-term, this sits as a preventive-health infrastructure play because osteoporosis screening mandates and metabolic disease monitoring applications extend DXA utility beyond cyclical capital equipment replacement. Target acquisition archetypes include compact-system specialists with solid-state detector miniaturization IP and software analytics firms with FDA-cleared fracture risk algorithms. Monitor CMS reimbursement code expansions for body composition analysis as the signal to watch for demand inflection beyond traditional bone density applications.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercial launch timelines for next-generation photon-counting detector configurations in United States hospital networks. |
| Hospital System Partnership | Locks in multi-year equipment refresh cycles through integrated imaging fleet agreements with centralized procurement departments. |
| Software Companion Development | Enhances diagnostic workflow efficiency via AI-assisted vertebral fracture detection integrated with existing PACS infrastructure. |
| Reimbursement Strategy | Captures Medicare preventive service coverage for mobile bone density testing and body composition analysis applications. |
| CE Marking Pathway | Maintains European market access under MDR recertification requirements with stricter clinical evidence standards. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and clinical densitometry technologists; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and IEC standards documentation. Bottom-up unit economics triangulated against top-down market sizing across product configurations and end-user segments.
Across the analysis window, the forecasting framework modeled demand drivers by product type, end-user procurement authority, application reimbursement pathway, and detector technology generation. CAGRs derived from equipment replacement cycles, screening eligibility expansion, and portable configuration adoption curves. Forecast inputs incorporated Medicare policy stability, EU MDR implementation timelines, and solid-state detector cost curves.
Forecasts assume regulatory continuity in FDA 510(k) pathways and CMS reimbursement codes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Navigated Biopsy Needles Market