
 Diagnostic Ophthalmic Devices Market | 2026-2036
Diagnostic Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Ophthalmic Devices Market Analysis
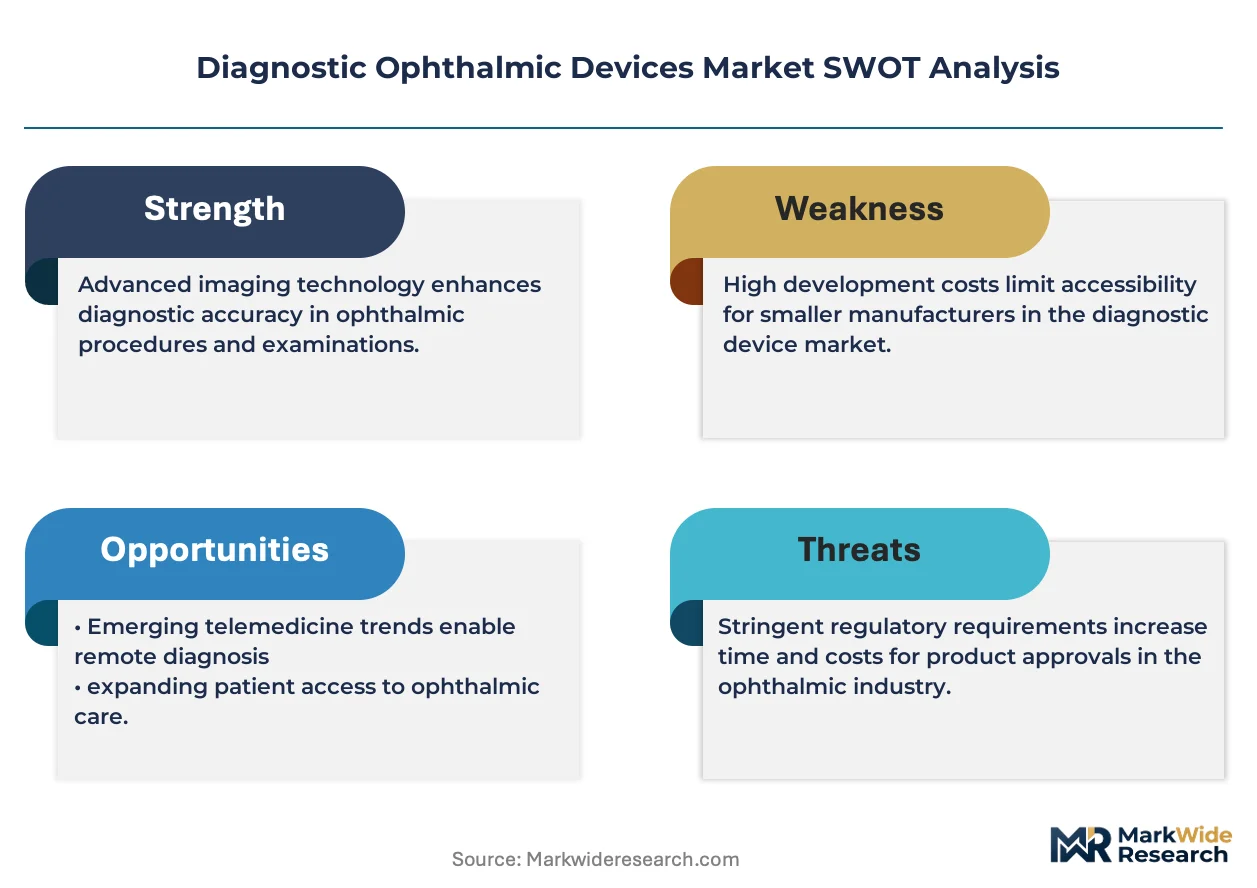
Capital-intensity divergence between integrated optical manufacturers and modular device assemblers is bifurcating competitive returns in diagnostic ophthalmic devices. Carl Zeiss Meditec leverages captive lens-grinding capabilities and vertically controlled supply chains to sustain premium positioning across OCT and fundus imaging platforms. Haag-Streit competes through specialized slit-lamp engineering and Swiss precision manufacturing heritage that anchors its installed base in European university hospitals. Topcon Corporation dominates Asian ophthalmology clinic networks through localized service infrastructure and cost-calibrated retinal imaging portfolios.
Diagnostic ophthalmic devices comprise precision optical instruments engineered to measure, image, and quantify ocular structures and visual function, typically resolving retinal layers at 5-10 micron precision through interferometric or confocal methods. These systems serve primary clinical purposes of early disease detection, surgical planning, and treatment monitoring across progressive conditions such as glaucoma and diabetic retinopathy. Optical coherence tomography commands the deepest clinical integration and replacement cycle visibility among product type categories, while fundus autofluorescence within technology segments attracts fastest-growing adoption for geographic atrophy monitoring in macular degeneration. Retinal imaging systems concentrate margin pools in hospital capital budgets, whereas ophthalmology clinics drive volume expansion for compact, automated visual field analyzers.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access barriers for diagnostic ophthalmic devices, with notified body capacity constraints in Europe extending conformity assessment durations. Japan's PMDA enforces JIS-aligned quality management standards that filter non-compliant imports from Southeast Asian manufacturing origins. Stakeholders must monitor evolving reimbursement coding for AI-assisted image interpretation, as payor acceptance of automated diagnostic outputs will determine whether software-enabled devices capture incremental value or compress hardware pricing across clinic and hospital segments.
Market Dynamics
Automated diagnostic platforms are compressing replacement cycles across hospital ophthalmology departments as artificial intelligence-assisted interpretation gains FDA 510(k) clearance and EU MDR conformity acceptance, forcing capital equipment vendors to embed software subscription revenue into hardware pricing models.
Growth Catalysts
- Preventive screening mandates:Medicare coverage expansion for diabetic retinopathy screening in United States outpatient clinics is pulling spectral-domain OCT systems into primary care networks previously served only by optometry referrals.
- EU MDR Article 10 technical documentation:Stricter clinical evidence requirements for Class IIa diagnostic devices are filtering out low-cost Asian imports and consolidating procurement around established European notified body relationships.
- Swept-source OCT engineering:Deeper tissue penetration at 1050nm wavelengths is displacing time-domain systems in glaucoma progression monitoring, with adoption accelerating in Japanese university hospital networks.
Market Restraints
- Indium gallium arsenide detector supply:Single-source dependency on Japanese sensor foundries creates input cost volatility for near-infrared imaging modules.
- EU notified body capacity:MDR conformity assessment backlogs extending beyond 18 months are freezing product launch timelines for modular device assemblers without legacy CE certificates.
- Optical coherence tomography angiography:Non-invasive blood flow mapping without dye injection threatens conventional fluorescein angiography hardware installed bases.
Strategic Opportunities
- Telemedicine integration:Cloud-connected fundus cameras paired with AI grading algorithms are opening rural India and Southeast Asian clinic networks previously unreachable by field service engineers.
- Japan PMDA Sakigake designation:Expedited review pathways for breakthrough diagnostic devices are attracting R&D investment in adaptive optics for macular degeneration monitoring.
- Point-of-care convergence:Handheld OCT systems combining smartphone connectivity with MEMS scanning technology are creating new channel access through retail optical chains.
Industry Challenges
- Biomedical optics engineering talent:Scarcity of interferometry specialists with clinical translation experience is extending product development timelines for spectral calibration algorithms.
- Legacy PACS integration:Hospital IT departments face middleware complexity when connecting AI-enabled devices to existing DICOM infrastructure without native HL7 FHIR support.
Report Scope
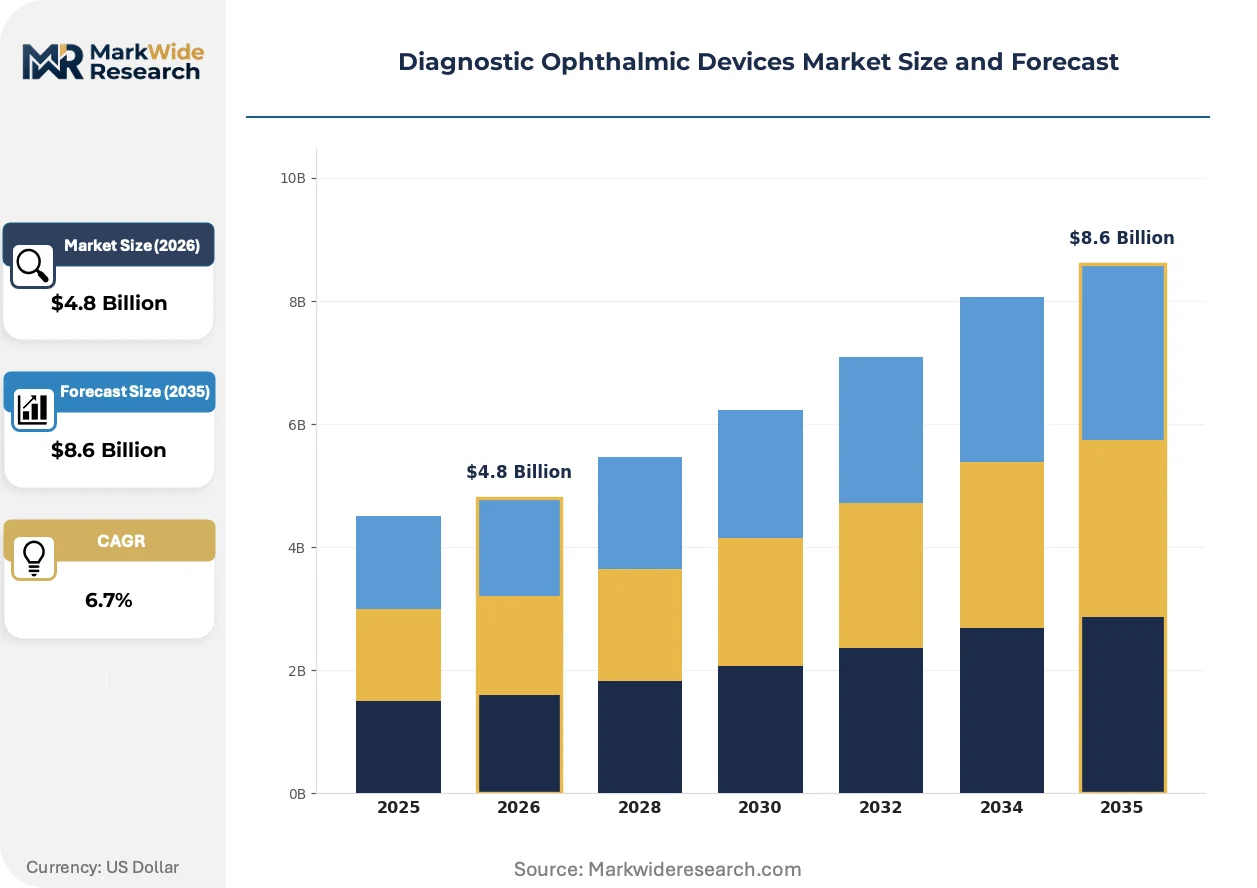
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Ophthalmic Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fundus Cameras, Optical Coherence Tomography, Visual Field Analyzers, Retinal Imaging Systems Technology: Digital Imaging, Wavefront Aberrometry, Fundus Autofluorescence, Ultrasonography End User: Ophthalmology Clinics, Hospitals, Research Institutes, Diagnostic Laboratories Application: Diabetic Retinopathy, Glaucoma Screening, Macular Degeneration, Cataract Screening |
| Companies Covered | Alcon Inc., Canon Inc., Carl Zeiss Meditec, Bausch + Lomb, Johnson & Johnson Vision Care, Topcon Corporation, Haag-Streit, Essilor International S.A., NIDEK Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Ophthalmic Devices Market Emerging Trajectories
Artificial intelligence inference engines are embedding directly into diagnostic hardware, compressing the value chain between image acquisition and clinical decision support while forcing vendors to restructure from equipment sellers to diagnostic service providers.
Swept-source optical coherence tomography is displacing spectral-domain platforms in posterior segment imaging through superior choroidal visualization and reduced motion artifacts. Academic medical centers in Germany and Japan are prioritizing swept-source procurement for geographic atrophy clinical trials. The technology is compressing hardware replacement cycles from seven years to four years as resolution benchmarks reset.
EU MDR Annex XIV post-market surveillance requirements are mandating periodic safety update reports for Class IIa diagnostic devices, extending regulatory affairs headcount needs for manufacturers. Notified body unannounced audits are increasing compliance costs disproportionately for modular device assemblers versus vertically integrated optical manufacturers. European hospital procurement committees are now requiring MDR certificate validity periods as contract evaluation criteria.
After-sales service unbundling is fragmenting buyer-vendor relationships as ophthalmology clinics in the United States negotiate remote technical support subscriptions separate from hardware maintenance agreements. Third-party ISO 13485-certified service organizations are capturing calibration and repair volume in metropolitan markets with high device density. This channel shift is most visible in California and Texas where independent practice associations aggregate purchasing leverage.
Diagnostic Ophthalmic Devices Market Segmentation
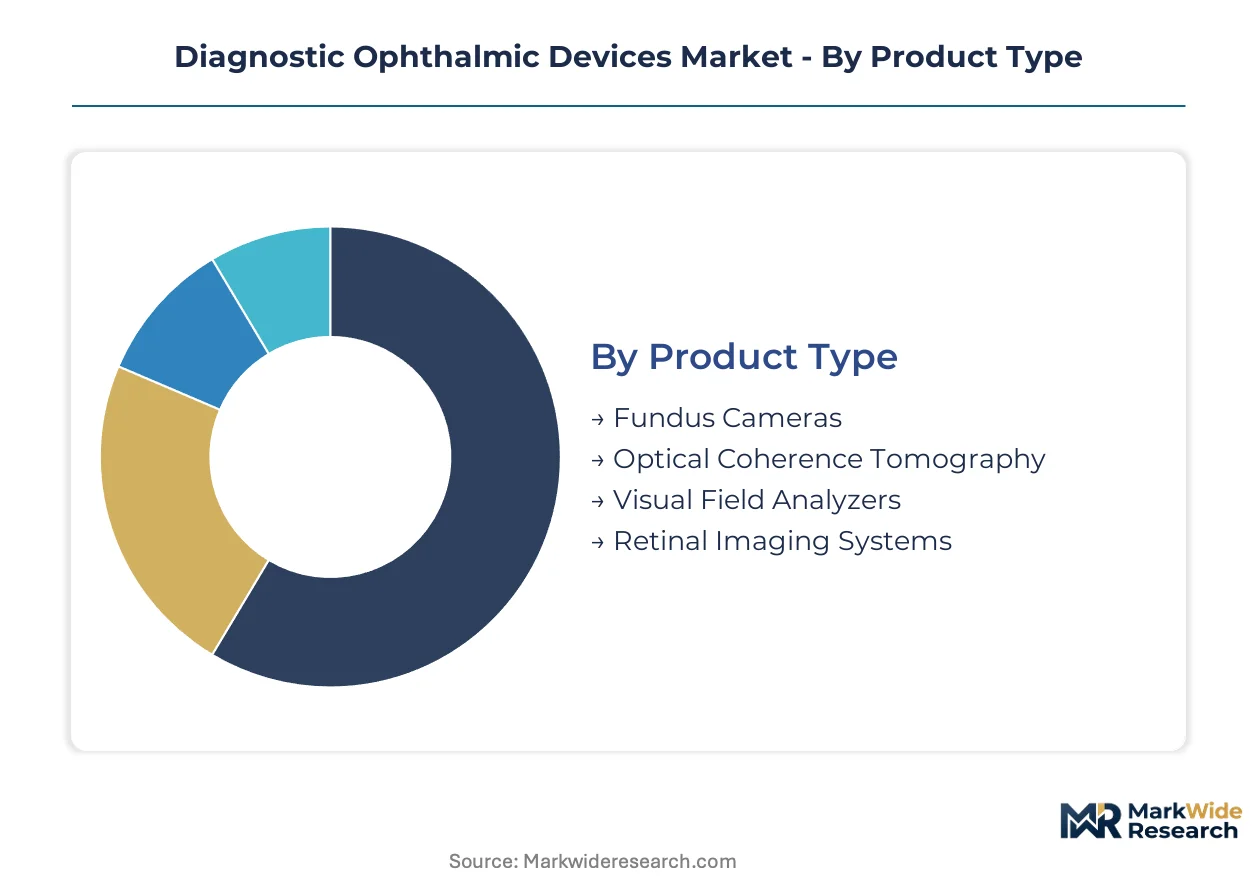
Diagnostic ophthalmic devices fragment across four intersecting dimensions that determine pricing power, service intensity, and channel access. Each category reveals distinct procurement patterns between capital-rich hospital networks and volume-driven clinic chains.
Product Type:
Hospital capital budgets absorb high-value imaging platforms while ophthalmology clinics drive replacement demand for compact diagnostic tools.
- Fundus Cameras:Non-mydriatic digital systems capture retinal images without pupil dilation, enabling diabetic retinopathy screening in United States primary care networks where Medicare reimbursement codes now cover automated grading. Procurement concentrates in outpatient clinics seeking workflow efficiency over spectral resolution.
- Optical Coherence Tomography:Interferometric imaging resolves retinal layers at micron-scale precision through spectral-domain or swept-source architectures. Japanese university hospitals prioritize swept-source systems for choroidal visualization in geographic atrophy trials, compressing replacement cycles from seven years to four.
- Visual Field Analyzers:Automated perimetry systems map peripheral vision loss patterns for glaucoma progression monitoring.
- Retinal Imaging Systems:Integrated multimodal platforms combine fundus photography with OCT angiography for comprehensive posterior segment assessment.
Optical coherence tomography dominates installed base. Fundus cameras represent where expansion concentrates.
Technology:
Regulatory clearance pathways diverge sharply between mature imaging modalities and emerging computational techniques.
- Digital Imaging:CCD and CMOS sensor-based capture systems form the backbone of fundus photography and external eye documentation. FDA 510(k) predicate device pathways accelerate market entry for incremental sensor upgrades, though EU MDR technical documentation requirements now demand clinical performance validation.
- Fundus Autofluorescence:Lipofuscin emission mapping visualizes retinal pigment epithelium health without dye injection. German academic medical centers deploy this modality for geographic atrophy endpoint assessment in macular degeneration trials, driving fastest-growing adoption among technology segments.
- Wavefront Aberrometry:Laser-based ocular wavefront sensing measures higher-order optical aberrations for refractive surgery planning.
- Ultrasonography:A-scan and B-scan acoustic imaging penetrates media opacities when optical methods fail.
Digital imaging anchors current revenue. Fundus autofluorescence is climbing the fastest.
End User:
Procurement scale and service expectations separate institutional buyers from distributed clinical networks.
- Ophthalmology Clinics:Independent and group practice settings prioritize compact footprint, automated operation, and remote technical support subscriptions. United States independent practice associations in California and Texas negotiate unbundled service agreements separate from hardware acquisition.
- Hospitals:Integrated delivery networks demand native DICOM compliance, HL7 FHIR connectivity, and enterprise PACS integration. IT middleware complexity extends procurement timelines for AI-enabled devices lacking legacy infrastructure compatibility.
- Research Institutes:Academic medical centers drive early adoption of experimental modalities for clinical trial endpoints.
- Diagnostic Laboratories:Centralized reading centers process remote image uploads for telemedicine networks.
Hospitals concentrate premium system demand. Ophthalmology clinics are gaining share fastest.
Application:
Screening mandate expansion and disease prevalence patterns reshape modality prioritization across patient populations.
- Diabetic Retinopathy:Systematic screening programs for diabetic populations drive spectral-domain OCT and fundus camera deployment into United States primary care networks previously served only by optometry referrals. Medicare coverage expansion pulls diagnostic capability downstream from specialist settings.
- Macular Degeneration:Age-related geographic atrophy monitoring demands high-resolution imaging with longitudinal stability. Japanese PMDA Sakigake designation pathways accelerate breakthrough device review for adaptive optics systems targeting this indication.
- Glaucoma Screening:Visual field analysis combined with OCT retinal nerve fiber layer assessment forms standard diagnostic protocol.
- Cataract Screening:Preoperative biometry and lens power calculation drive wavefront aberrometry utilization.
Diabetic retinopathy commands volume deployment. Macular degeneration shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States hospital systems absorb premium pricing for AI-embedded platforms, while Southeast Asian clinic networks prioritize cost-calibrated fundus cameras with remote service capabilities.
United States
Medicare coverage expansion for diabetic retinopathy screening drives spectral-domain OCT deployment into primary care networks. FDA 510(k) clearance pathways for AI-assisted interpretation compress diagnostic workflow times. The California-Texas corridor concentrates independent practice associations negotiating unbundled service agreements.
Germany
Academic medical centers prioritize swept-source OCT procurement for geographic atrophy clinical trials. EU MDR Annex XIV post-market surveillance requirements extend regulatory affairs headcount for manufacturers. The Baden-Württemberg cluster anchors precision optics manufacturing heritage.
Japan
Aging demographics and universal health coverage sustain replacement demand for high-resolution retinal imaging. PMDA Sakigake designation pathways accelerate breakthrough device review for adaptive optics systems. University hospital networks in Tokyo and Osaka drive swept-source adoption for choroidal visualization.
India
Telemedicine integration opens rural clinic networks previously unreachable by field service engineers. CDSCO import regulations filter non-compliant devices from Southeast Asian manufacturing origins. Maharashtra and Karnataka concentrate cloud-connected fundus camera deployment for AI grading algorithms.
United Kingdom
NHS screening program mandates pull automated perimetry systems into community optometry settings. MHRA post-Brexit regulatory alignment with EU MDR technical documentation extends conformity timelines. London and the Southeast concentrate research institute procurement for multimodal retinal imaging platforms.
Diagnostic Ophthalmic Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Vertically integrated optical manufacturers command premium positioning through captive lens-grinding capabilities, while modular device assemblers compete on cost-calibrated portfolios and localized service infrastructure. The market structure consolidates around heritage precision manufacturers, Asian volume suppliers, and diversified healthcare conglomerates. Dominant competitive moves include software subscription bundling into hardware pricing and regulatory certificate leveraging to filter low-cost imports.
Among heritage precision manufacturers, Carl Zeiss Meditec and Haag-Streit exemplify European archetypes anchored in university hospital networks. Topcon Corporation represents the Asian volume-supplier position with localized service infrastructure. These three occupy distinct competitive territories: German-Swiss precision engineering, Japanese clinic network density, and diversified healthcare portfolio breadth.
| Leading Market Players |
|---|
| Alcon Inc. |
| Canon Inc. |
| Carl Zeiss Meditec |
| Bausch + Lomb |
| Johnson & Johnson Vision Care |
| Topcon Corporation |
| Haag-Streit |
| Essilor International S.A. |
| NIDEK Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with embedded software subscriptions lock in both supply access and price visibility for diagnostic ophthalmic device vendors, as FDA 510(k) clearance requirements and EU MDR conformity assessments extend procurement timelines and anchor hospital buyers to established supplier relationships.
Pricing Analysis
Remote technical support subscriptions drive lifetime value for compact diagnostic platforms sold into United States ophthalmology clinics. Three-tier pricing structure across premium, standard, and economy levels separates swept-source OCT systems with AI-embedded interpretation from spectral-domain workhorses and handheld screening devices. Pricing pressure stems from third-party ISO 13485-certified service organizations capturing calibration volume in high-density metropolitan markets. Ophthalmology clinics in California and Texas exhibit highest price sensitivity through independent practice association aggregation, while Japanese university hospitals absorb premium positioning for adaptive optics systems.
Supply Chain Analysis
Japan and Germany anchor precision optical component manufacturing for diagnostic ophthalmic devices, with Swiss lens-grinding heritage feeding European university hospital procurement. Indium gallium arsenide detectors draw from Japanese sensor foundries, creating single-source dependency for near-infrared imaging modules. MEMS scanning technology and interferometric light sources rest on Taiwanese semiconductor packaging capacity. Single-source vulnerability in detector supply generates input cost volatility for swept-source OCT engineering. Distribution runs through hospital procurement committees in integrated delivery networks and independent practice associations in metropolitan clinic clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent diagnostic ophthalmic device vendors face substitution defense against AI-native software platforms that could displace hardware-centric business models, as cloud-connected fundus cameras with automated grading algorithms compress the value chain between image acquisition and clinical decision support.
For Market Incumbents: Secure notified body relationships under EU MDR Article 10 technical documentation requirements to filter low-cost Asian imports and consolidate procurement around legacy CE certificate holders. Deepen backward integration into captive lens-grinding capabilities to sustain premium positioning against modular device assemblers. Embed software subscription revenue into hardware pricing models before AI-native platforms capture diagnostic service margins.
For New Entrants and Emerging Players: Rural telemedicine infrastructure gaps in India and Southeast Asia present white-space targets where cloud-connected fundus cameras paired with AI grading algorithms bypass field service engineer dependencies. Point-of-care convergence through handheld OCT systems with smartphone connectivity opens retail optical chain channels previously locked by hospital procurement committees. Target Maharashtra and Karnataka clinic networks through CDSCO-compliant import pathways and localized technical support partnerships.
For Investors and Strategic Acquirers: Modular device assemblers with EU MDR conformity assessment backlogs represent distressed acquisition targets where regulatory certificate leveraging can filter competition and consolidate procurement relationships. Swept-source OCT engineering capabilities and adaptive optics R&D pipelines signal long-term viability across the analysis window. Watch PMDA Sakigake designation pathways for breakthrough device review acceleration as inflection indicator for Japanese market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for AI-assisted interpretation engines in United States outpatient networks. |
| EU MDR Conformity Assessment | Extends regulatory affairs headcount needs while filtering non-compliant imports from Asian manufacturing origins. |
| Hospital System Partnership | Locks in enterprise PACS integration requirements that freeze modular device assemblers without HL7 FHIR support. |
| Software Companion Development | Captures recurring revenue streams as diagnostic service providers rather than equipment sellers. |
| Reimbursement Strategy | Determines whether Medicare coverage expansion for diabetic retinopathy screening pulls spectral-domain OCT into primary care. |
Methodological Framework
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and ophthalmology clinic directors anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement codes, and hospital procurement records. Bottom-up installed base modeling and top-down expenditure flow analysis triangulated market sizing across product type, technology, end user, and application dimensions.
Sensitivity analysis tested forecast robustness across regulatory timeline scenarios and reimbursement policy shifts over the projection horizon. Segmentation modeling captured product type variation, technology maturity tiers, end user procurement scale, and application-specific modality prioritization. CAGRs derived from replacement cycle compression dynamics and preventive screening mandate expansion. Forecast inputs included swept-source OCT adoption curves in Japanese university hospitals and telemedicine integration rates in Indian rural clinic networks.
Underlying assumptions cover EU notified body capacity constraints, PMDA Sakigake designation throughput, and indium gallium arsenide detector supply stability, with deviation risk concentrated in MDR conformity assessment backlogs extending beyond standard timelines and AI-assisted reimbursement coding decisions by United States payors. Recalibration cycles align with material shifts in regulatory clearance pathways and breakthrough device designation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Hemoglobin Testing Devices Market