
 Europe Companion Diagnostics Market | 2026-2036
Europe Companion Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Companion Diagnostics Market Foresight
Oncology is pivoting toward biomarker-guided therapy selection across European hospital networks. F. Hoffmann-La Roche AG dominates immunoassay development for companion diagnostic platforms. Thermo Fisher Scientific Inc. extends its presence through NGS-based testing infrastructure. QIAGEN N.V. specializes in sample preparation technologies that anchor laboratory workflows across the region.
Companion diagnostics comprises in vitro testing systems designed to identify patient subpopulations likely to respond to specific biopharmaceutical therapies, typically employing PCR amplification, immunohistochemistry staining, or next-generation sequencing with defined analytical sensitivity thresholds. IVD platforms and biomarker assay kits constitute the core product architecture, while NGS technology captures expanding demand for multiplexed genomic profiling in oncology applications. PCR retains cost advantages in high-volume infectious disease screening across diagnostic laboratories.
The European Medicines Agency coordinates centralized marketing authorization for companion diagnostic–drug combinations, while the EU In Vitro Diagnostic Regulation mandates stricter performance evaluation and post-market surveillance standards. EMA's parallel scientific advice process with notified bodies shapes co-development timelines for pharmaceutical and diagnostic manufacturers. Stakeholders must monitor evolving harmonization between EMA opinions and national reimbursement decisions across member states.
Market Dynamics
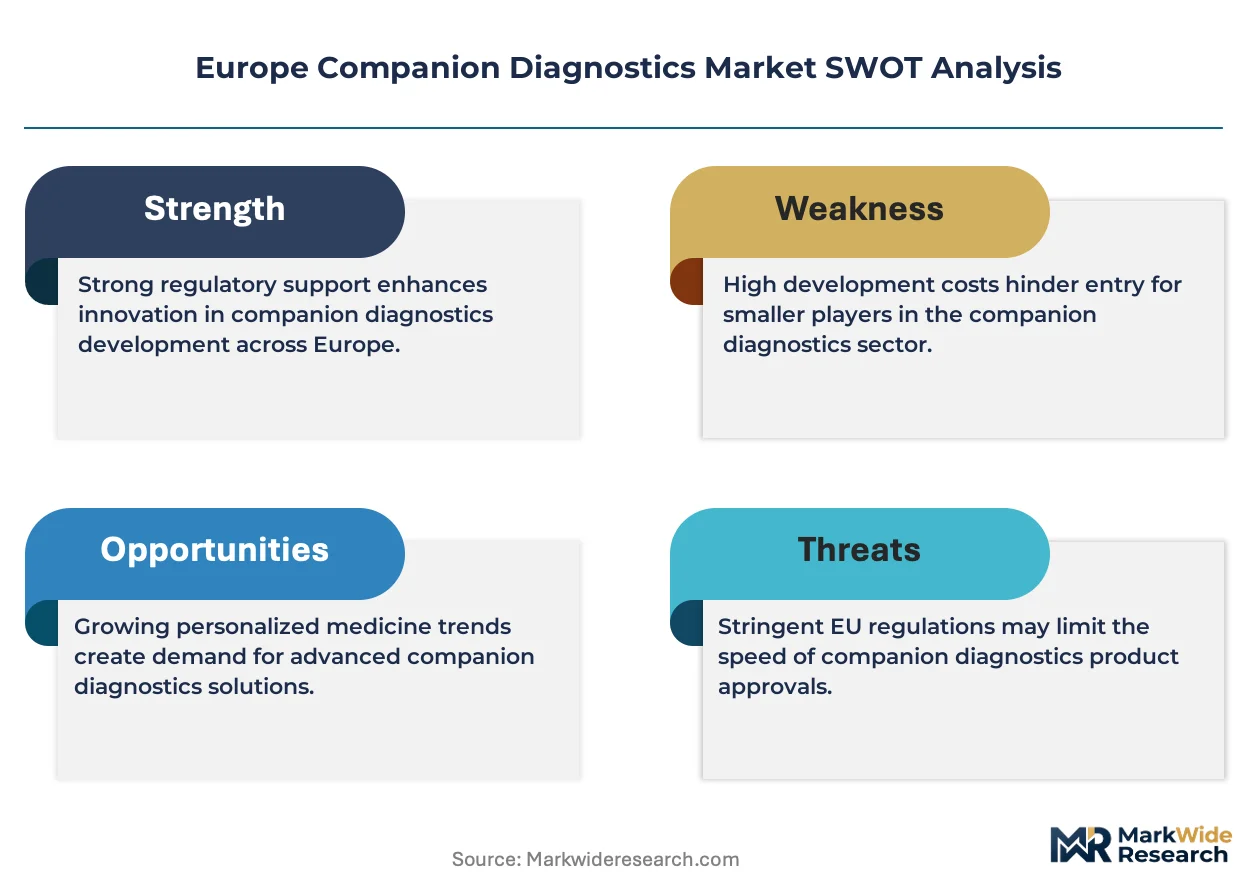
The EU In Vitro Diagnostic Regulation is compressing approval timelines and forcing laboratories to revalidate entire assay portfolios, creating a structural bottleneck that favors manufacturers with pre-existing notified body relationships.
Growth Catalysts
- Oncology Biomarker Expansion:European hospital networks are embedding companion diagnostic testing into standard cancer care pathways, with pathology departments in Germany and France prioritizing PD-L1 and EGFR testing protocols.
- EMA Parallel Scientific Advice:The centralized marketing authorization process for drug-diagnostic combinations accelerates co-development timelines, reducing regulatory uncertainty for pharmaceutical and diagnostic manufacturers.
- Next-Generation Sequencing Infrastructure:Multiplexed genomic profiling capabilities are expanding across regional reference laboratories, enabling simultaneous analysis of multiple biomarkers from single tissue samples.
Market Restraints
- IVDR Compliance Costs:The stricter performance evaluation and post-market surveillance requirements under EU In Vitro Diagnostic Regulation impose substantial documentation burdens on small and mid-sized assay developers.
- Reimbursement Fragmentation:National health technology assessment bodies in Italy, Spain, and Poland apply divergent evidentiary standards for companion diagnostic coverage, complicating market access strategies.
- Sample Preparation Bottlenecks:Formalin-fixed paraffin-embedded tissue quality variability across European pathology networks limits assay reproducibility and creates pre-analytical workflow challenges.
Strategic Opportunities
- Liquid Biopsy Integration:Circulating tumor DNA testing platforms offer non-invasive alternatives to tissue-based diagnostics, with regulatory pathways under development at EMA for oncology monitoring applications.
- Central and Eastern Europe Penetration:Poland, Czech Republic, and Hungary present underdeveloped precision medicine infrastructure where academic medical centers are establishing molecular tumor boards.
- Artificial Intelligence-Assisted Pathology:Machine learning algorithms for automated biomarker scoring are converging with digital pathology workflows, creating new value propositions for diagnostic laboratories.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories across the United Kingdom and Nordic countries face acute shortages of computational biologists capable of interpreting complex NGS variant data.
- Legacy System Interoperability:Hospital laboratory information systems require extensive middleware development to integrate companion diagnostic results with electronic health records and clinical decision support tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Companion Diagnostics Market |
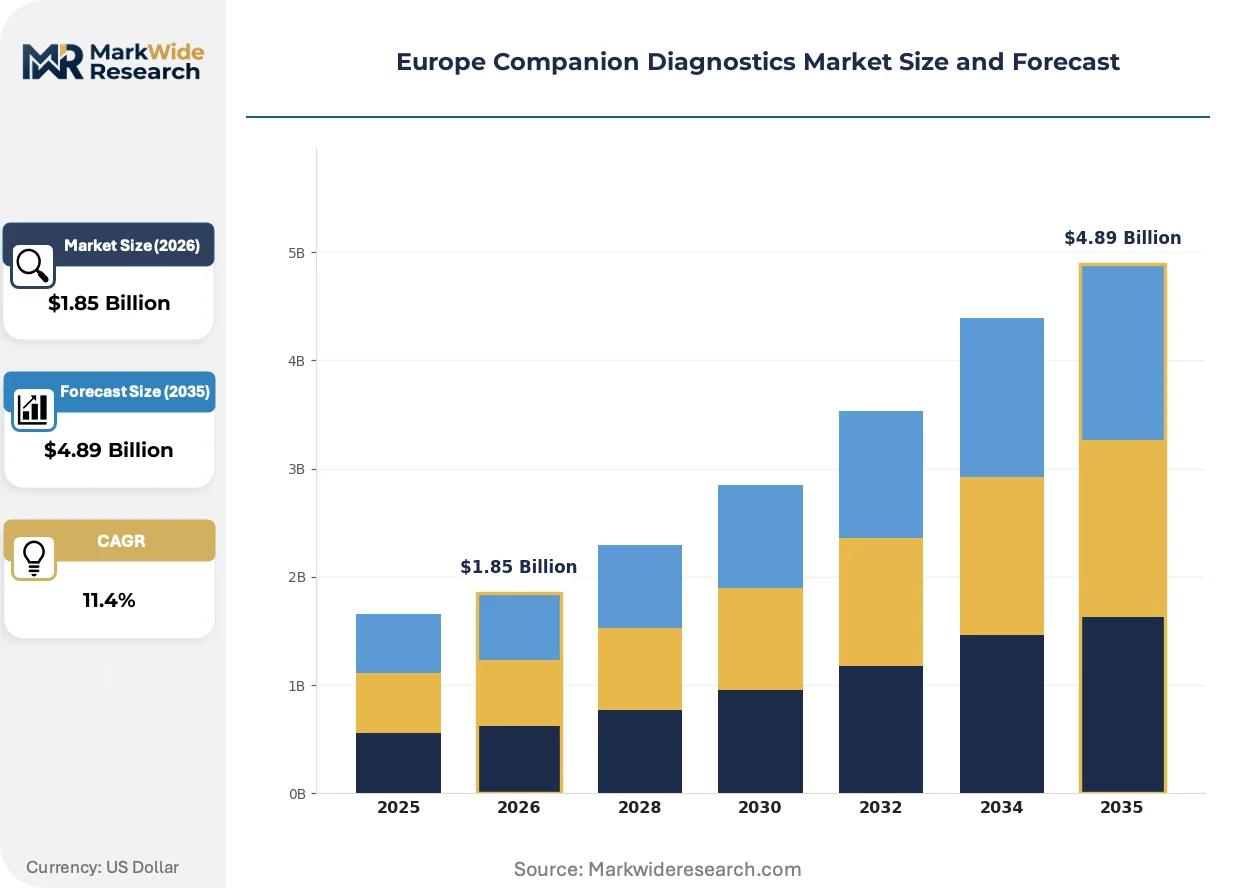
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IVD, Biomarkers, Assay Kits, Testing Platforms End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinical Organizations Technology: NGS, PCR, Immunohistochemistry, Microarray Application: Oncology, Infectious Diseases, Genetic Disorders, Cardiovascular |
| Companies Covered | Abbott Laboratories, Agilent Technologies, F. Hoffmann-La Roche AG, Thermo Fisher Scientific Inc., QIAGEN N.V., bioMerieux SA, Beckman Coulter Inc., Siemens Healthineers, Illumina Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Companion Diagnostics Market Shifts & Advancements
Multiplex biomarker platforms are displacing single-analyte testing in European oncology practice, while regulatory harmonization efforts and artificial intelligence integration are simultaneously reshaping product development and clinical deployment models.
Next-generation sequencing with defined analytical sensitivity thresholds is rewriting the economics of genomic testing in European reference laboratories. Academic medical centers in the Netherlands and Belgium are adopting comprehensive genomic profiling panels that simultaneously assess hundreds of biomarkers. This compression of per-biomarker testing cost is enabling broader patient access to precision oncology therapies previously restricted to specialized centers.
EU In Vitro Diagnostic Regulation performance evaluation requirements are mandating expanded clinical evidence packages for companion diagnostic devices. Manufacturers must now demonstrate analytical validity, clinical validity, and clinical utility through prospective studies or rigorously curated retrospective cohorts. High-risk class C and D devices face the most stringent scrutiny, with notified bodies in Germany and the Netherlands experiencing significant backlog volumes.
Hospital procurement consortia are consolidating purchasing power for companion diagnostic platforms across regional networks. Group purchasing organizations in France and the United Kingdom are negotiating multi-year supply agreements that bundle assay reagents with instrument placement. This channel concentration favors vendors offering integrated workflow solutions spanning sample preparation through automated result reporting.
Europe Companion Diagnostics Market Segmentation
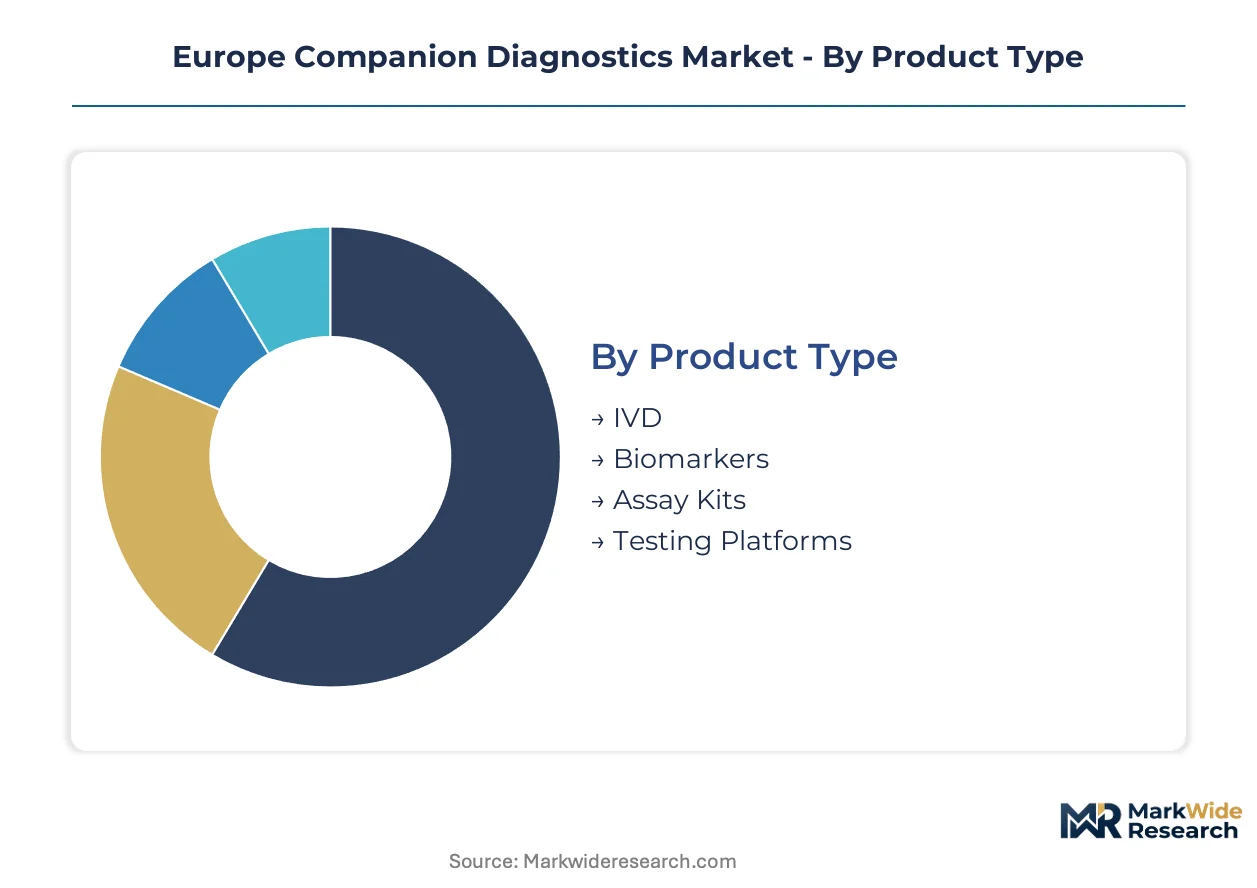
Companion diagnostics demand fragments across four structural dimensions, each with distinct capital requirements and regulatory pathways. Technology selection determines laboratory infrastructure investment, while end-user concentration shapes commercial access strategies.
Product Type:
Capital intensity peaks with integrated testing platforms requiring substantial instrument placement and service infrastructure.
- IVD:In vitro diagnostic systems encompass fully automated analyzers and reagent cartridges designed for high-throughput clinical laboratories. German hospital networks prioritize IVD platforms with integrated quality control modules to satisfy EU IVDR documentation requirements.
- Biomarkers:Protein and nucleic acid signatures serve as predictive indicators for therapeutic response, with PD-L1 expression and EGFR mutation status commanding priority placement in French oncology protocols. Biomarker assay development demands extensive clinical validation cohorts under EMA parallel scientific advice frameworks.
- Assay Kits:Single-use reagent sets enable decentralized testing without major capital equipment.
- Testing Platforms:Integrated hardware-software systems combine sample processing with automated result interpretation.
IVD absorbs the bulk of installed capacity; biomarkers are expanding most quickly.
End User:
Procurement authority concentrates with organizations managing the largest patient volumes and most complex reimbursement negotiations.
- Hospitals:European university hospitals in Heidelberg, Paris, and London anchor precision medicine programs with embedded molecular pathology departments. Hospital pathology networks in France negotiate centralized purchasing agreements that bundle companion diagnostic reagents with multi-year service contracts.
- Diagnostic Laboratories:Regional reference laboratories in the Netherlands and Belgium process high-volume biomarker testing for distributed hospital networks. These facilities face acute pressure to validate entire assay portfolios under IVDR performance evaluation deadlines.
- Research Institutions:Academic medical centers drive biomarker discovery and early clinical validation studies.
- Clinical Organizations:Specialized cancer centers coordinate molecular tumor boards for therapy selection.
Hospitals command the dominant share of current spending; diagnostic laboratories are climbing the fastest as regional consolidation accelerates.
Technology:
Platform selection hinges on throughput requirements, multiplexing capability, and total cost per reportable result.
- NGS:Next-generation sequencing enables simultaneous analysis of hundreds of genomic alterations from limited tissue samples. Comprehensive genomic profiling panels are gaining priority placement in Netherlands and Belgium academic centers seeking to compress per-biomarker testing economics.
- PCR:Polymerase chain reaction retains cost advantages for high-volume single-gene testing in infectious disease screening. German diagnostic laboratories deploy PCR-based companion diagnostics for EGFR and BRAF mutation detection in lung and melanoma indications.
- Immunohistochemistry:Protein expression staining dominates PD-L1 testing for immuno-oncology patient selection.
- Microarray:Comparative genomic hybridization supports copy number variation analysis in hematologic malignancies.
PCR maintains the largest installed base; NGS is gaining share fastest as panel reimbursement stabilizes across European markets.
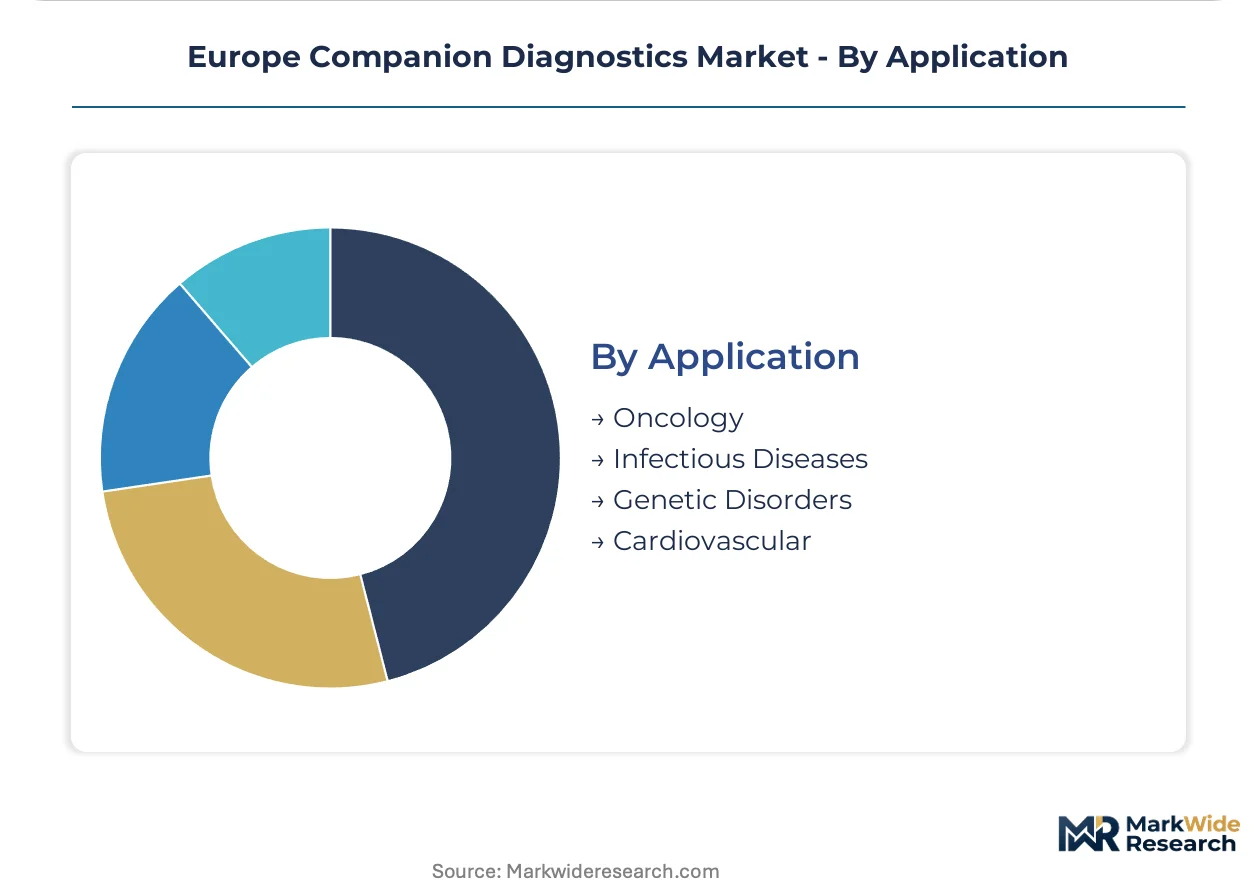
Application:
Clinical utility validation requirements vary sharply across disease categories, with oncology commanding the most mature regulatory precedents.
- Oncology:Solid tumor and hematologic malignancy applications dominate companion diagnostic development pipelines, with lung cancer, breast cancer, and colorectal cancer indications leading biomarker-guided therapy approvals. Pathology departments across Germany and France have embedded PD-L1, EGFR, and HER2 testing into standard care pathways.
- Infectious Diseases:Antimicrobial resistance profiling and viral load monitoring drive demand for rapid molecular diagnostics. HIV and hepatitis C genotyping applications concentrate in high-volume screening programs.
- Genetic Disorders:Pharmacogenomic testing for inherited metabolic conditions supports rare disease therapeutic development.
- Cardiovascular:Clopidogrel metabolism genotyping represents the most established cardiovascular companion diagnostic application.
Oncology captures the dominant share of current revenue; infectious disease applications are expanding most quickly as antimicrobial stewardship programs mandate resistance profiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of companion diagnostic platforms concentrates in Germany, Switzerland, and the Netherlands, while clinical consumption spreads across hospital networks in France, the United Kingdom, and Italy. This geographic split shapes regulatory compliance priorities and supply chain logistics for manufacturers serving European markets.
Germany
University hospitals in Heidelberg and Munich anchor precision medicine infrastructure, driving demand for PD-L1 and EGFR testing protocols. The Federal Institute for Drugs and Medical Devices enforces EU IVDR compliance timelines that compress product approval windows. Notified bodies in Berlin and Munich face substantial backlog volumes for high-risk device classifications.
France
Parisian academic medical centers coordinate molecular tumor boards for biomarker-guided therapy selection, embedding companion diagnostics into standard oncology pathways. The French National Agency for Food, Environmental and Occupational Health Safety oversees clinical trial approvals for diagnostic-drug combinations. Hospital procurement consortia in the Île-de-France region negotiate multi-year supply agreements for integrated testing platforms.
United Kingdom
NHS pathology networks in London and Manchester face acute bioinformatics talent scarcity for NGS variant interpretation. The Medicines and Healthcare products Regulatory Agency manages post-Brexit device registration pathways parallel to EU IVDR requirements. Genomic England's comprehensive profiling programs expand biomarker testing access across regional hospital trusts.
Netherlands
Reference laboratories in Rotterdam and Utrecht process high-volume multiplexed genomic profiling for distributed hospital networks. The Dutch Healthcare Authority coordinates reimbursement negotiations for comprehensive genomic panels. Academic centers in Leiden and Amsterdam pioneer artificial intelligence-assisted pathology workflows for automated biomarker scoring.
Italy
Lombardy and Emilia-Romagna host emerging molecular pathology programs where academic medical centers establish precision medicine infrastructure. The Italian Medicines Agency applies national health technology assessment standards that diverge from centralized EMA opinions. Northern hospital networks prioritize PCR-based testing for cost-sensitive infectious disease applications.
Europe Companion Diagnostics Market Competitive Landscape
Top-tier vendors anchor the integrated platform segment, while mid-sized assay developers concentrate on specialized biomarker applications. The vendor base stratifies across three tiers: multinational conglomerates with full workflow solutions, regional specialists in sample preparation technologies, and emerging entrants in liquid biopsy platforms. Consolidation pressures favor manufacturers with pre-existing notified body relationships and established service infrastructure. Dominant competitive moves include strategic partnerships for co-development timelines and portfolio diversification into artificial intelligence-assisted pathology.
Within the multinational tier, F. Hoffmann-La Roche AG, Thermo Fisher Scientific Inc., and QIAGEN N.V. represent distinct strategic archetypes. Roche exemplifies the vertically integrated diagnostic-pharmaceutical model with immunoassay development capabilities. Thermo Fisher occupies a position spanning NGS-based testing infrastructure and laboratory consumables. QIAGEN anchors the sample preparation technology segment that underpins regional laboratory workflows. These three firms collectively illustrate the competitive necessity of spanning multiple technology modalities to secure hospital procurement contracts.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Agilent Technologies |
| F. Hoffmann-La Roche AG |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| bioMerieux SA |
| Beckman Coulter Inc. |
| Siemens Healthineers |
| Illumina Inc. |
| Others |
Supply & Pricing Matrix
Hospital procurement consortia in France and the United Kingdom anchor purchasing power for companion diagnostic platforms, concentrating price negotiation leverage with organizations managing multi-year supply agreements that bundle reagent cartridges with instrument service contracts.
Pricing Analysis
Cost-down pressure on assay kits accelerates because diagnostic laboratories face compressed revalidation timelines under EU IVDR performance evaluation deadlines. Pricing stratifies across premium, standard, and economy tiers based on analytical sensitivity thresholds and notified body certification grade. German university hospitals demonstrate lowest price sensitivity given embedded quality control requirements, while Polish and Czech regional laboratories prioritize per-test economics.
Supply Chain Analysis
Freight costs for temperature-controlled reagent shipments from Switzerland and the Netherlands to Southern European markets impose working capital burdens on regional distributors. Manufacturing of NGS platforms concentrates in the United States and China, while sample preparation consumables source primarily from German and Dutch production facilities. Single-source vulnerability around semiconductor components for sequencing instruments creates procurement risk. Distribution runs through authorized dealer networks serving hospital pathology departments and reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European companion diagnostics sits in a technology-transition phase where next-generation sequencing displaces single-analyte PCR testing for oncology biomarker profiling.
For Market Incumbents: Anticipate margin compression in high-volume PCR segments as laboratories consolidate purchasing around comprehensive genomic profiling panels. Deepen backward integration into sample preparation chemistry production to secure supply continuity. Prioritize CE marking pathway acceleration for Class C and D devices to maintain notified body queue position against emerging entrants. For New Entrants and Emerging Players: Liquid biopsy platforms offer technology-first wedge into monitoring applications where regulatory pathways remain under development at EMA. Target Central and Eastern European molecular tumor boards in Poland, Czech Republic, and Hungary where precision medicine infrastructure remains underdeveloped. Pursue academic medical center partnerships for clinical validation cohorts before commercial scale. For Investors and Strategic Acquirers: The window for entry favors mid-cap assay developers with established IVDR technical documentation and pre-existing notified body relationships. Long-term viability hinges on portfolio breadth spanning sample preparation through automated interpretation. Watch EMA parallel scientific advice throughput volumes as inflection signal for co-development pipeline health.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Completion | Notified body backlog in Germany and Netherlands creates first-mover advantage for compliant submissions. |
| Liquid Biopsy Regulatory Pathway Development | EMA oncology monitoring guidance shapes competitive positioning for circulating tumor DNA platforms. |
| Artificial Intelligence-Assisted Pathology Integration | Machine learning algorithms for automated PD-L1 scoring converge with digital pathology workflows in Netherlands. |
| Central and Eastern Europe Geographic Expansion | Academic medical centers in Poland and Hungary establish molecular tumor boards requiring platform partnerships. |
| Comprehensive Genomic Panel Reimbursement Strategy | Dutch Healthcare Authority negotiations set precedent for multiplexed testing coverage across Benelux markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pathology department heads, diagnostic laboratory directors, regulatory affairs specialists at notified bodies, and hospital procurement managers combined with EMA submission databases, IVDR technical documentation registries, and hospital purchasing consortium contracts. Bottom-up instrument placement counts and top-down biomarker test volume estimates were triangulated against reimbursement claims data.
Granularity-level modeling tracked technology platform, application indication, end-user facility type, and country-specific regulatory cluster across the projection horizon. Segment-level CAGRs derived from test volume growth curves, instrument replacement cycles, and panel reimbursement trajectory assumptions. Forecast inputs incorporated EMA parallel scientific advice throughput trends, IVDR transition timeline compliance rates, and NGS platform placement data from academic medical center capital expenditure disclosures.
Several conditions sit outside the modeled scope, including post-market surveillance outcome data not yet available under IVDR transitional provisions and speculative regulatory decisions on liquid biopsy coverage. Forecasts reflect documented assumptions around reimbursement stabilization timelines and laboratory consolidation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Lung Biopsy Systems Market