
 Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market | 2026-2036
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market Foresight
Buyer concentration across hospital procurement networks is rebalancing as independent diagnostic centers and physician-owned orthopedic practices fragment the traditional customer base. Hologic leverages its installed base in women's health imaging to sustain recurring revenue from software upgrades and service contracts. GE Healthcare anchors its position through backward integration into detector manufacturing, reducing component lead times. Siemens Healthineers differentiates via AI-enabled scan automation that compresses exam duration.
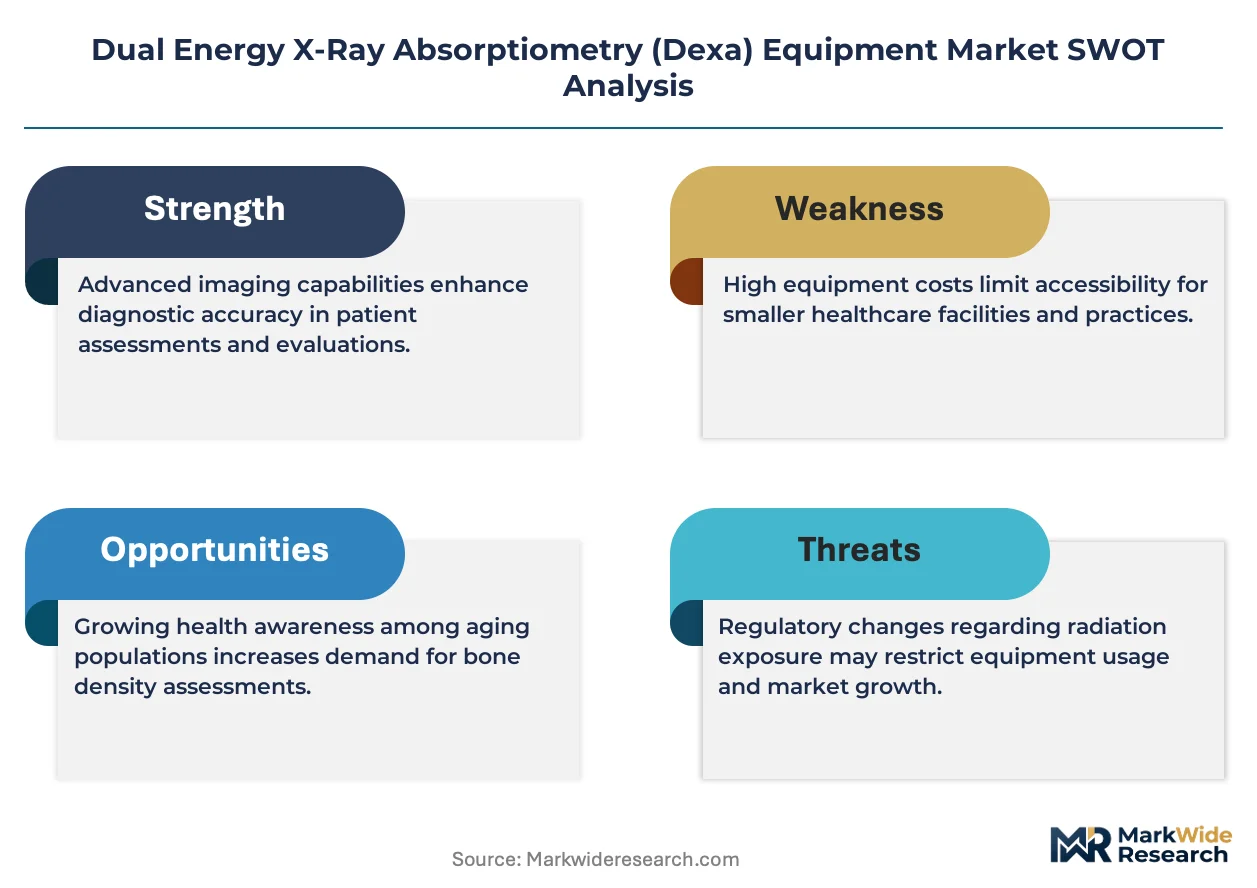
Dual Energy X-Ray Absorptiometry equipment utilizes two distinct X-ray energy spectra to differentiate bone mineral content from soft tissue, achieving precision within one percent for bone density quantification. The technology serves primary clinical purposes in osteoporosis screening, fracture-risk stratification, and longitudinal monitoring of metabolic bone disorders. Bone density scanners occupy the mature core of the product mix, while whole body scanners capture expanding utilization in sports medicine and bariatric assessment programs where body composition analysis drives purchasing decisions. Peripheral scanners face margin compression as point-of-care ultrasound alternatives erode their role in primary screening workflows.
FDA maintains stringent 510(k) substantial equivalence requirements for DXA systems, while the EU Medical Device Regulation imposes enhanced clinical evidence standards that extend certification timelines for new entrants. Japan's PMDA enforces JIS-aligned quality management protocols that filter non-compliant imports. Stakeholders must monitor reimbursement coding revisions for bone mass measurement as payors tighten prior authorization criteria.
Market Dynamics
AI-enabled scan automation is compressing exam durations and forcing incumbents to retrofit software architectures, while reimbursement coding revisions for bone mass measurement tighten prior authorization criteria across major payor networks.
Growth Catalysts
- Japan's PMDA quality protocols:JIS-aligned standards filter non-compliant imports, elevating certified manufacturers and protecting premium equipment margins.
- Sports medicine body composition analysis:Whole body scanners capture expanding utilization in athletic performance programs and bariatric assessment workflows.
- Aging demographics in Germany:Replacement cycles sustain demand as reimbursement stability encourages hospital capital expenditure on precision bone density systems.
Market Restraints
- Point-of-care ultrasound substitution:Peripheral scanners face margin compression as primary care physicians adopt cheaper alternatives for initial osteoporosis screening.
- EU MDR clinical evidence requirements:Enhanced documentation standards extend certification timelines for new entrants, concentrating market access among established players.
- Detector component supply concentration:GE Healthcare's backward integration into captive detector manufacturing leaves independent manufacturers exposed to semiconductor foundry bottlenecks.
Strategic Opportunities
- Independent diagnostic center channel expansion:Physician-owned orthopedic practices fragment traditional hospital procurement networks, creating direct sales opportunities outside group purchasing organizations.
- Software upgrade recurring revenue:Hologic's installed base in women's health imaging demonstrates service contract monetization potential for AI-enhanced diagnostic algorithms.
- US reimbursement coding tailwinds:Medicare coverage determinations for vertebral fracture assessment expand billable indications beyond standard bone mineral density testing.
Industry Challenges
- FDA 510(k) substantial equivalence pathways:Predicate device identification delays compress product launch windows for iterative hardware improvements.
- Legacy PACS integration complexity:Hospital information system interoperability requirements extend implementation timelines and inflate deployment costs.
- Radiologic technologist training gaps:Specialized DXA certification scarcity limits equipment utilization rates in high-throughput screening programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market |
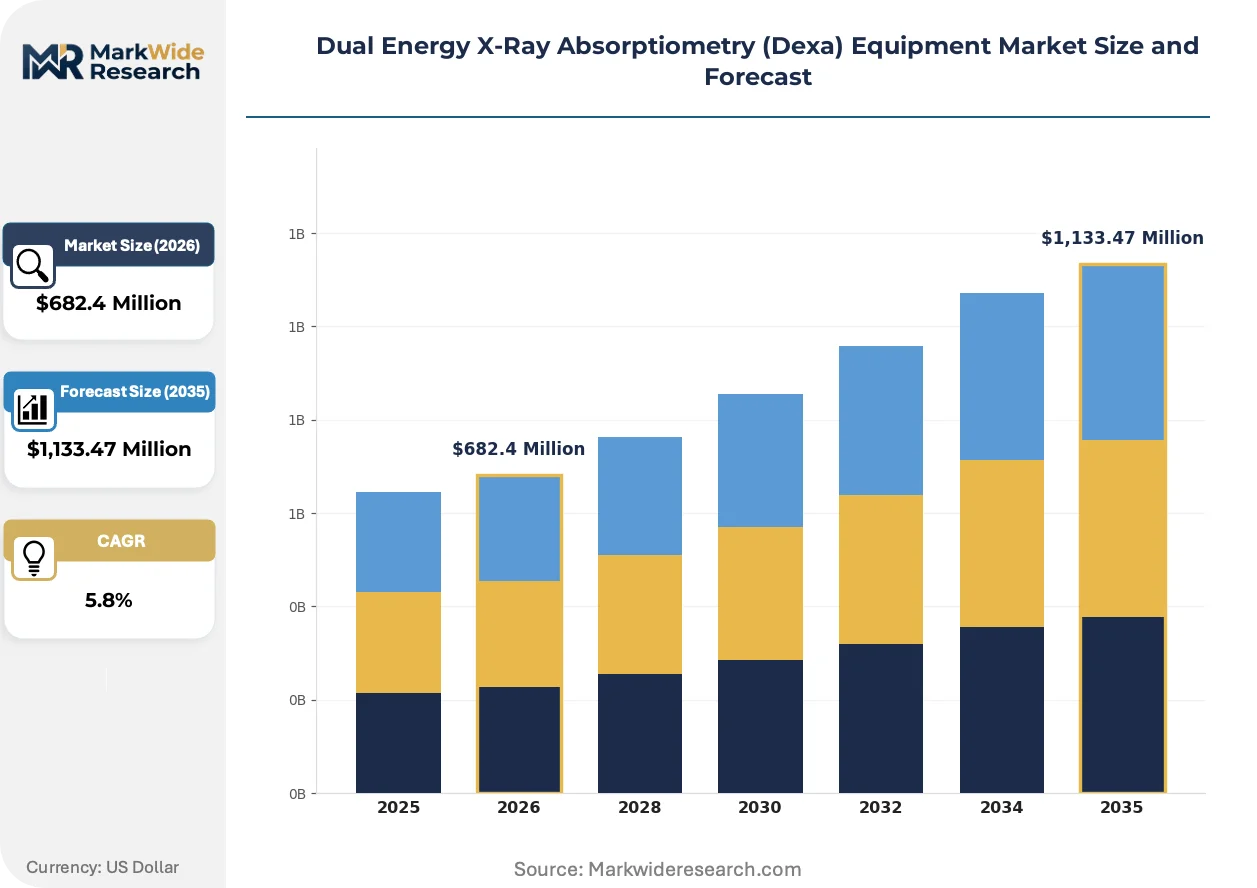
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,133.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Density Scanners, Multi-Functional Scanners, Peripheral Scanners, Whole Body Scanners Application: Osteoporosis Diagnosis, Body Composition Analysis, Cancer Treatment Monitoring, Orthopedics End User: Hospitals, Diagnostic Centers, Research Institutions, Fitness Centers Technology: DXA, Ultrasound, MR Imaging, CT Imaging |
| Companies Covered | GE Healthcare, Hologic, Fujifilm, Diagnostic Medical Systems, OSTEOSYS, Siemens Healthineers, Furuno Electric, Swissray, BeamMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market Shifts & Advancements
Scan automation and machine learning inference are displacing manual region-of-interest placement, while regulatory harmonization efforts between FDA and notified bodies create divergent compliance burdens.
AI-enabled vertebral fracture detection is integrating into standard lumbar spine acquisition protocols, automating morphometric assessment that previously required radiologist interpretation. Academic medical centers in the United States deploy these algorithms to compress reporting turnaround times. Siemens Healthineers is integrating this capability across its scanner portfolio, enabling differentiation in competitive hospital tenders.
The EU Medical Device Regulation imposes post-market surveillance obligations that force manufacturers to maintain clinical evidence registries for legacy predicate devices. Notified bodies in Germany and France demand expanded biocompatibility documentation for patient contact surfaces. DXA system OEMs are responding by consolidating technical file management and accelerating MDR transition projects for high-revenue product lines.
Buyer committees now unbundle service contracts from equipment financing, pressuring OEMs to compete on transparent hourly labor rates and parts availability guarantees. Independent diagnostic centers in Japan negotiate multi-vendor maintenance agreements that break manufacturer service monopolies. This behavioral shift concentrates purchasing power among procurement specialists who benchmark total cost of ownership across ten-year equipment lifecycles.
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market Segmentation
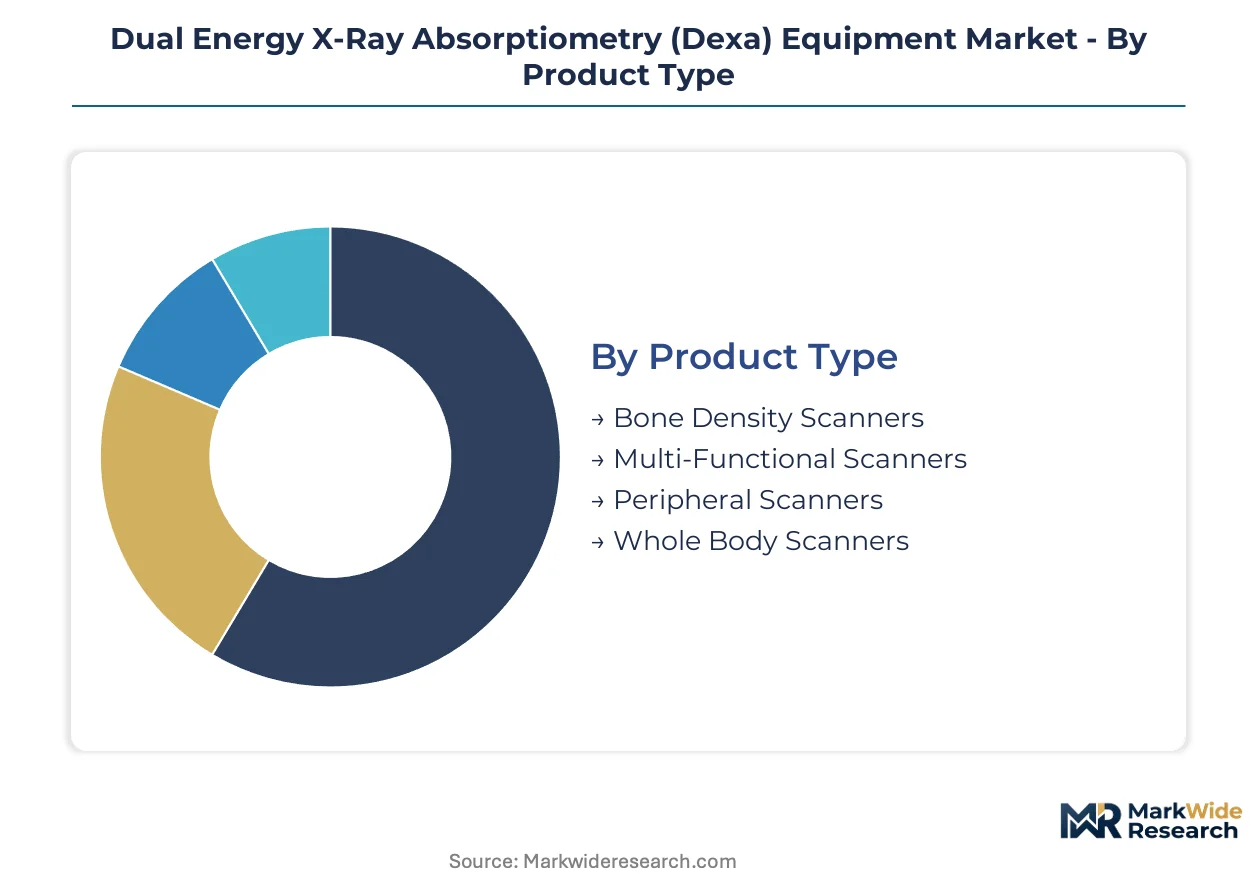
Dual Energy X-Ray Absorptiometry equipment segments diverge sharply by clinical utility and capital intensity. Procurement committees weight precision requirements against throughput economics when allocating budgets across scanner categories.
Product Type:
Technical specifications governing beam geometry and detector resolution define the product hierarchy.
- Bone Density Scanners:These systems deploy narrow-angle fan beam geometry optimized for lumbar spine and proximal femur quantification. Demand concentrates in Germany and Japan where osteoporosis screening programs sustain replacement cycles at hospital outpatient departments.
- Whole Body Scanners:Extended scan tables and high-output X-ray tubes enable total body composition analysis with regional fat and lean mass distribution. Sports medicine programs in the United States drive purchasing decisions as athletic performance monitoring expands beyond research settings.
- Multi-Functional Scanners:Modular detector arrays support both axial skeletal and appendicular measurements through software-configured acquisition protocols.
- Peripheral Scanners:Compact footprint units target heel and forearm density assessment in primary care workflows.
Mature deployment sits with Bone Density Scanners. Newer deployment is concentrated in Whole Body Scanners.
Application:
Clinical indication breadth determines reimbursement coding and equipment utilization rates.
- Osteoporosis Diagnosis:Fracture-risk stratification using T-score classification against young adult reference populations remains the core reimbursed indication. Medicare coverage determinations in the United States anchor demand at diagnostic centers serving aging patient panels.
- Body Composition Analysis:Segmental lean mass quantification supports sarcopenia assessment and bariatric surgical planning. Academic medical centers in Japan deploy these protocols for metabolic syndrome research cohorts.
- Cancer Treatment Monitoring:Bone mineral density tracking during androgen deprivation or aromatase inhibitor therapy.
- Orthopedics:Pre-operative planning and post-surgical healing assessment in arthroplasty populations.
Osteoporosis Diagnosis commands established procedure volumes. Body Composition Analysis is gaining share fastest among emerging indications.
End User:
Capital availability and patient throughput requirements segment the buyer base.
- Hospitals:Integrated health systems leverage group purchasing organization contracts to standardize on multi-detector platforms. Reimbursement stability in Germany encourages capital expenditure on precision systems with ten-year depreciation schedules.
- Diagnostic Centers:Physician-owned orthopedic practices fragment traditional procurement networks. Independent operators in the United States negotiate direct manufacturer relationships outside hospital purchasing consortia.
- Research Institutions:NIH-funded longitudinal studies and pharmaceutical trial networks.
- Fitness Centers:Corporate wellness programs and high-performance athletic facilities.
Hospital procurement dominates installed base maintenance. Diagnostic Centers represent the steepest expansion trajectory for new unit placements.
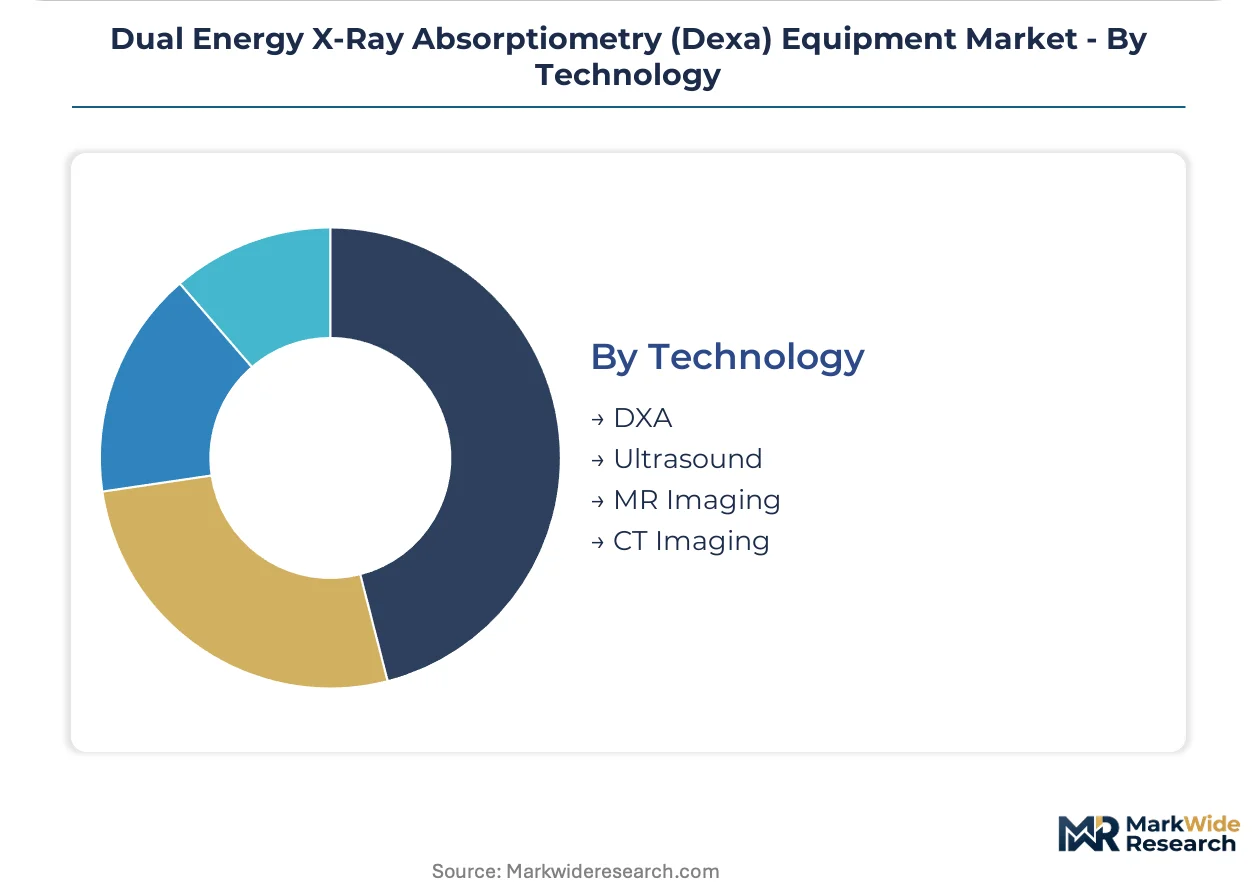
Technology:
Imaging modality selection trades radiation exposure against measurement precision and anatomical coverage.
- DXA:Dual-energy subtraction algorithms achieve one percent precision for bone mineral content quantification. FDA 510(k) clearance pathways and established CPT coding sustain incumbent positioning against competing modalities.
- Ultrasound:Zero-ionizing-radiation profile enables point-of-care screening in primary care settings. Peripheral deployment in Japan's community health centers challenges dedicated heel densitometers on cost and portability.
- MR Imaging:Magnetic resonance-based bone microarchitecture assessment without ionizing radiation.
- CT Imaging:Quantitative computed tomography enables volumetric density measurement and three-dimensional fracture modeling.
DXA anchors clinical standard-of-care. Ultrasound is displacing peripheral DXA in screening workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
X-ray tube manufacturing clusters in Germany and detector foundries in Japan anchor equipment supply chains for bone density systems. Reimbursement stability in aging economies sustains replacement demand, while regulatory divergence between FDA and EU MDR shapes market access patterns.
United States
Medicare coverage determinations for vertebral fracture assessment expand billable indications beyond standard bone mineral density testing. FDA maintains stringent 510(k) substantial equivalence requirements that compress product launch windows for iterative hardware improvements. Academic medical centers in Boston and the Research Triangle deploy AI-enabled scan automation to compress reporting turnaround times.
Germany
Replacement cycles sustain demand as reimbursement stability encourages hospital capital expenditure on precision bone density systems. Notified bodies in Germany and France demand expanded biocompatibility documentation for patient contact surfaces under EU MDR. Industrial clusters in Bavaria and Baden-Württemberg concentrate detector component manufacturing and technical file management operations.
Japan
Aging demographics and reimbursement stability sustain replacement cycles at hospital outpatient departments. PMDA enforces JIS-aligned quality management protocols that filter non-compliant imports and elevate certified manufacturers. Academic medical centers in Tokyo and Osaka deploy whole body scanners for metabolic syndrome research cohorts and sarcopenia assessment protocols.
China
Community health centers expand osteoporosis screening coverage under national chronic disease management programs. NMPA medical device registration pathways require domestic clinical trials for imported DXA systems. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta assemble peripheral scanners for primary care workflows.
South Korea
Corporate wellness programs and high-performance athletic facilities drive purchasing decisions for body composition analysis systems. MFDS enforces quality management system certification aligned with ISO 13485 for radiological equipment. Seoul Capital Area hospitals standardize on multi-detector platforms through group purchasing organization contracts.
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care ultrasound alternatives and software-defined diagnostic platforms. The vendor base concentrates around imaging conglomerates with captive detector supply chains and independent specialists with modular hardware architectures. Three archetypes dominate: conglomerates with backward integration into semiconductor manufacturing, women's health imaging specialists with installed base monetization strategies, and regional fabricators with cost-optimized peripheral systems. Competitive moves center on AI-enabled software retrofitting and multi-vendor service contract unbundling.
Within the conglomerate tier, GE Healthcare and Siemens Healthineers exemplify players with upstream control over detector manufacturing and scan automation capabilities. Hologic occupies a position representing women's health imaging specialists with recurring revenue potential from service contracts and software upgrades. BeamMed and OSTEOSYS sit within the regional specialist archetype, anchoring cost-competitive positioning in peripheral and whole body scanner categories.
| Leading Market Players |
|---|
| GE Healthcare |
| Hologic |
| Fujifilm |
| Diagnostic Medical Systems |
| OSTEOSYS |
| Siemens Healthineers |
| Furuno Electric |
| Swissray |
| BeamMed |
| Others |
Supply & Pricing Matrix
AI-enabled scan automation is compressing exam durations and simultaneously reshaping cost economics and supply concentration as OEMs retrofit software architectures and source specialized inference processors. Detector foundry bottlenecks in Japan and semiconductor supply constraints are amplifying pricing power for manufacturers with captive component production, while independent assemblers face margin compression from input scarcity.
Pricing Analysis
Warranty and service contract unbundling is fragmenting traditional equipment financing bundles as buyer committees negotiate transparent hourly labor rates and parts availability guarantees separately from capital purchases. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled multi-detector platforms from basic bone density systems and cost-optimized peripheral units, with price differentiation driven by certification tier and after-sales service depth. Pricing pressure stems from point-of-care ultrasound substitution eroding peripheral scanner margins. Independent diagnostic centers exhibit highest price sensitivity, while integrated hospital systems prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
Domestic-content mandates under China's NMPA registration pathways are reshaping sourcing as foreign OEMs establish local assembly operations to bypass import clinical trial requirements. Manufacturing clusters concentrate in Germany for X-ray tube production, Japan for detector foundries, and China for peripheral scanner assembly. Component dependencies include high-purity germanium crystals, ceramic X-ray tube housings, and precision stepper motors. Single-source vulnerability sits with specialized semiconductor foundries supplying signal processing ASICs. Distribution runs through hospital group purchasing organizations in the United States and direct manufacturer relationships with independent diagnostic centers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue upstream control over detector manufacturing to secure component supply and compress lead times against foundry bottlenecks.
For Market Incumbents: Hedge against point-of-care ultrasound substitution by accelerating AI-enabled software retrofitting across installed bases and securing multi-year service contracts with independent diagnostic centers. Deepen backward integration into captive detector production to insulate margins from semiconductor foundry volatility, while maintaining FDA 510(k) clearance momentum for iterative hardware improvements.
For New Entrants and Emerging Players: The price-point gap between premium whole-body scanners and economy peripheral units opens white-space opportunities in mid-tier multi-functional systems for physician-owned orthopedic practices. Target diagnostic center channel expansion outside hospital procurement networks, where direct sales relationships bypass GPO pricing pressure. Pursue reimbursement strategy development for body composition analysis indications as the fastest-penetrating emerging application.
For Investors and Strategic Acquirers: Exit pathways concentrate in conglomerate acquisition of independent specialists with modular hardware architectures and regional regulatory certifications. Long-term viability favors manufacturers with software-defined diagnostic platforms and recurring revenue from algorithm upgrades. Watch Medicare coverage determinations for vertebral fracture assessment as the inflection signal for expanded billable indication breadth.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Software Retrofitting | Compresses exam duration and differentiates tenders against ultrasound alternatives. |
| Backward Integration into Detectors | Reduces lead times and insulates margins from Japanese foundry bottlenecks. |
| Diagnostic Center Channel Expansion | Captures fragmented demand outside hospital GPO procurement networks. |
| Reimbursement Strategy Development | Expands Medicare coverage for vertebral fracture assessment beyond bone density. |
| MDR Transition Acceleration | Maintains EU market access amid enhanced clinical evidence requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and radiologic technologists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical file registries, CMS Medicare coverage determinations, and hospital procurement databases. Bottom-up unit shipment estimates triangulated against top-down expenditure projections across product type, application, end user, and technology segments.
Data-stream reconciliation across shipment volumes, installed base depreciation schedules, and reimbursement code utilization produced value estimates over the projection horizon. Segmentation dimensions modeled include scanner category, clinical indication, buyer archetype, and imaging modality, with CAGRs derived from replacement cycle analysis and demographic-driven demand elasticity. Forecast inputs incorporated PMDA quality protocol compliance rates and EU MDR certification timeline extensions.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time service contract pricing transparency introduce uncertainty bands around aftermarket revenue projections. Forecasts reflect assumptions on reimbursement stability and detector supply normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Cath Lab Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Global Medical Lighting Technologies Market