
 Spinal Traction Market | 2026-2036
Spinal Traction Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Traction Market Analysis
ISO 13485 certification cycles for medical device quality management is collapsing from a three-year recertification window toward continuous audit models, raising barriers for smaller manufacturers. BTL leverages its European manufacturing footprint to sustain multi-market registrations across EEA member states. Saunders Group anchors its competitive position through specialized distribution in North American chiropractic channels.
Spinal traction applies controlled mechanical force to the spine through motorized, pneumatic, or manual systems to decompress intervertebral discs and relieve nerve root pressure, typically delivering forces between 30 to 150 pounds with treatment durations of 15 to 30 minutes per session. Electric traction systems command premium positioning due to programmable force curves and integrated patient monitoring, while pneumatic traction units occupy the fastest-growing tier as portable home-care configurations expand. Chiropractic clinics represent a concentrated margin pool where device placement ties to recurring service revenue streams.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) framework govern device classification, clinical evaluation, and post-market surveillance obligations for traction equipment manufacturers. The FDA's evolving software-as-a-medical-device guidance intersects with cloud-based deployment models, creating compliance complexity for connected traction platforms. Stakeholders must monitor how FDA enforcement discretion for wellness versus medical claims reshapes marketing boundaries for home-use traction products.
Market Dynamics
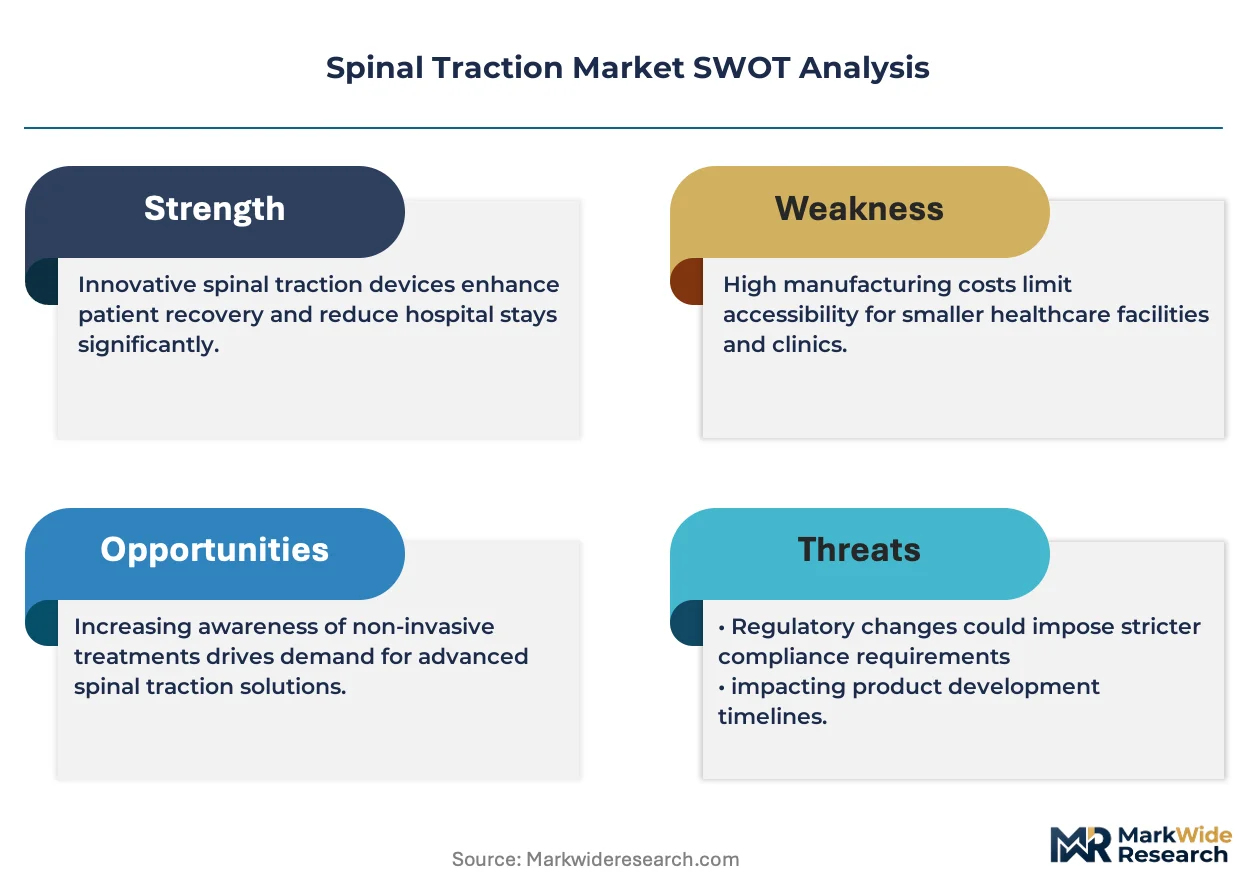
Spinal traction equipment faces intensifying pressure from ISO 13485 quality management recertification cycles collapsing toward continuous audit models, which disproportionately burdens smaller manufacturers while favoring established players with dedicated regulatory infrastructure.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:Unified clinical evaluation standards across EEA member states streamline multi-market registrations for compliant manufacturers, reducing duplicate testing burdens.
- Outpatient protocol shifts:Rehabilitation centers in the United States are expanding electric traction system adoption as non-surgical spinal decompression therapy gains reimbursement traction under commercial insurance plans.
- Pneumatic traction miniaturization:Advances in portable home-care configurations are unlocking patient-managed treatment models outside clinical settings.
Market Restraints
- FDA 510(k) documentation tightening:Powered traction devices now face elevated clinical evidence requirements that extend clearance timelines and raise development costs for new entrants.
- Component supply concentration:Precision force sensors and medical-grade actuators cluster among specialized German and Japanese suppliers, creating input vulnerability.
- Manual traction substitution:Low-cost mechanical systems retain share in price-sensitive emerging markets, compressing margin expansion for automated platforms.
Strategic Opportunities
- Cloud-connected traction platforms:Integration of remote patient monitoring with decompression protocols creates recurring data-service revenue streams alongside hardware sales.
- Home-care channel development:Direct-to-patient distribution models bypass traditional chiropractic clinic gatekeepers, capturing margin otherwise allocated to clinical intermediaries.
- United States aging demographics:Medicare Advantage expansion into supplemental spinal therapies widens addressable patient pools for reimbursed traction interventions.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-disciplinary expertise combining mechanical force control with clinical biomechanics concentrates among established medical device hubs, constraining R&D scaling.
- Legacy system integration friction:Electromechanical traction units must interface with heterogeneous electronic health record architectures across fragmented US hospital networks.
- Software-as-a-medical-device compliance complexity:FDA guidance evolution for algorithmic force-adjustment features creates uncertainty in validation protocols for AI-enabled traction systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Traction Market |
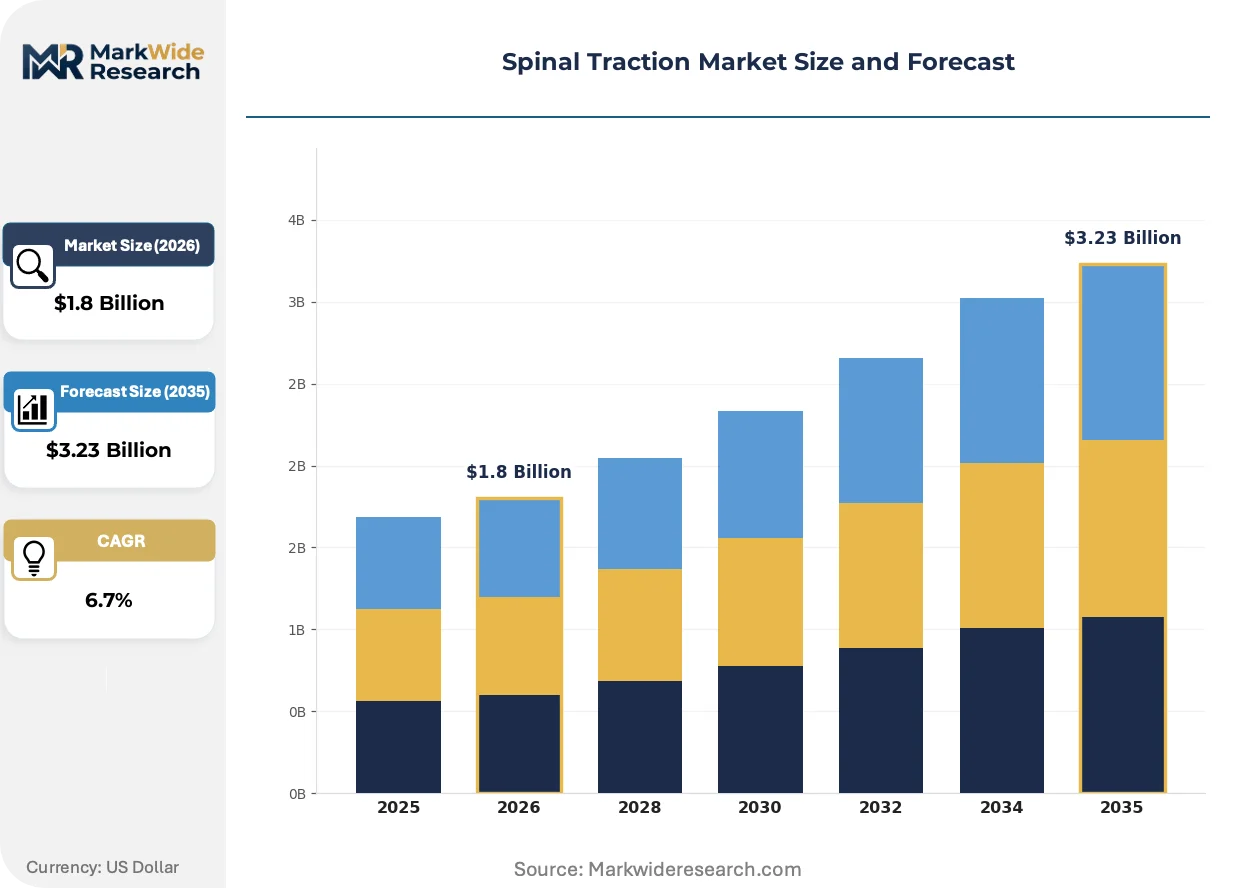
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Traction Devices, Electric Traction Systems, Pneumatic Traction Units, Traction Tables End User: Hospitals, Rehabilitation Centers, Home Care, Chiropractic Clinics Deployment: On-premise, Cloud-based, Mobile Solutions, Hybrid Systems Operation Mode: Static Traction, Dynamic Traction, Intermittent Traction, Continuous Traction |
| Companies Covered | BTL, Spinetronics, LLC, Saunders Group, Chattanooga, North American Medical Corporation, Hill Laboratories Company, VAX-D Medical Technologies, Spinal Designs International, Scrip, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Traction Market Emerging Trajectories
Software-defined force modulation is fragmenting traditional equipment categories, while regulatory frameworks for connected medical devices and shifting site-of-care preferences reshape competitive boundaries.
Programmable force curve technology is fragmenting the distinction between clinical-grade and consumer-grade traction systems. Chiropractic clinics in the United States are adopting these platforms to differentiate service offerings through personalized decompression protocols. The technology is fragmenting equipment procurement decisions across multiple budget owners—clinical operations, IT security, and revenue cycle management—rather than centralized capital planning.
The EU Medical Device Regulation (MDR) post-market surveillance requirements are intensifying clinical follow-up obligations for traction device manufacturers. This policy shift forces systematic collection of real-world performance data across distributed patient populations. Class IIa traction equipment with software components faces the steepest compliance adaptation, with manufacturers restructuring quality management systems to accommodate periodic safety update reporting.
After-sales service unbundling is separating hardware ownership from maintenance and calibration contracts in North American chiropractic channels. Independent practice owners increasingly favor subscription-based technical support over traditional warranty-inclusive purchases. This behavioral shift concentrates most visibly in multi-site clinic networks where standardization across dispersed locations drives preference for vendor-managed equipment uptime guarantees.
Spinal Traction Market Segmentation
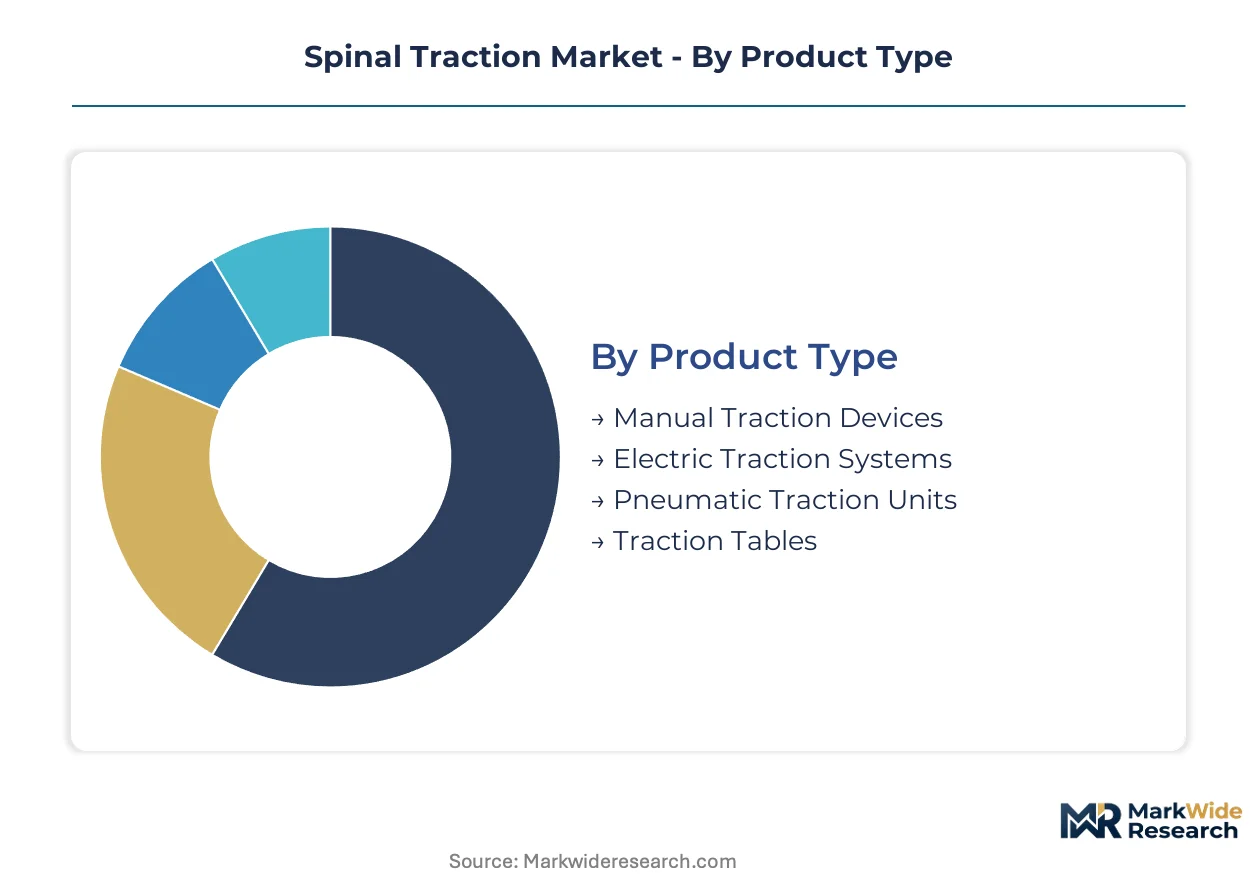
Segmentation in spinal traction equipment reveals divergent commercial models across clinical and patient-managed settings. Product architecture, site-of-care deployment, and reimbursement pathways create distinct margin structures that manufacturers must navigate simultaneously.
Product Type:
Geographic concentration varies sharply: electric and pneumatic systems dominate US and Western European exports, while manual traction remains concentrated in domestic production across emerging markets.
- Manual Traction Devices:Mechanical force application through pulley-and-weight configurations or therapist-assisted positioning. Demand clusters in price-sensitive markets across Southeast Asia and Latin America where clinical labor costs offset capital equipment investment.
- Electric Traction Systems:Programmable motorized platforms delivering precise force curves with integrated patient monitoring. Rehabilitation centers in the United States drive procurement volume as commercial insurance reimbursement for non-surgical spinal decompression expands.
- Pneumatic Traction Units:Portable air-pressure systems enabling patient-managed therapy outside clinical settings. German and Japanese component suppliers dominate precision actuator sourcing.
- Traction Tables:Integrated platforms combining motorized traction with positioning surfaces. Chiropractic clinics in North America represent the primary installation base.
Electric traction systems command the established base. The steepest expansion runs through pneumatic traction units.
End User:
Cost-tier stratification separates capital-intensive hospital installations from recurring-revenue chiropractic models and direct-to-patient home care channels.
- Hospitals:Acute care and surgical recovery units deploying Class IIa traction equipment under centralized procurement. EHR integration requirements and biomedical engineering staffing constrain vendor selection to established manufacturers with dedicated regulatory infrastructure.
- Rehabilitation Centers:Outpatient facilities expanding electric traction adoption as non-surgical protocols gain reimbursement traction under US commercial insurance plans. Multi-site networks favor vendor-managed equipment uptime guarantees over traditional warranty-inclusive purchases.
- Home Care:Patient-managed therapy models bypassing clinical gatekeepers through direct-to-patient distribution. FDA enforcement discretion for wellness versus medical claims reshapes marketing boundaries for this channel.
- Chiropractic Clinics:Independent and networked practices generating recurring service revenue through device-tied treatment protocols. After-sales service unbundling concentrates most visibly in multi-site networks where standardization drives preference for subscription-based technical support.
Chiropractic clinics anchor current volume. Home care is climbing the fastest as portable configurations unlock patient-managed treatment models.
Deployment:
Application architecture separates legacy electromechanical installations from emerging connected platforms requiring IT security and revenue cycle coordination.
- On-premise:Standalone electromechanical units operating without network connectivity. Legacy hospital infrastructure across fragmented US networks creates integration friction for these systems.
- Cloud-based:Remote patient monitoring integration with decompression protocols creating recurring data-service revenue streams. FDA software-as-a-medical-device guidance evolution creates validation uncertainty for algorithmic force-adjustment features.
- Mobile Solutions:Smartphone-controlled pneumatic units enabling location-independent therapy management. Patient data flows trigger GDPR compliance obligations for European deployments and HIPAA considerations in US markets.
- Hybrid Systems:Local processing with cloud analytics backup, accommodating clinical settings with intermittent connectivity. Procurement decisions fragment across clinical operations, IT security, and revenue cycle management budget owners.
On-premise systems retain the installed base. Cloud-based deployment is gaining share fastest through remote monitoring integration.
Operation Mode:
Volume concentration favors intermittent protocols in clinical settings, while continuous and static modes serve distinct therapeutic indications and patient tolerance profiles.
- Static Traction:Sustained force application without modulation, typically 15-30 minute durations. Cervical and lumbar decompression protocols in chiropractic clinics utilize this mode for disc herniation presentations.
- Dynamic Traction:Force variation synchronized with patient movement or respiratory cycle. Advanced rehabilitation centers in Germany and Switzerland deploy these systems for complex spine pathology.
- Intermittent Traction:Cyclic force application with programmed hold and rest intervals. US outpatient rehabilitation protocols favor this mode for patient tolerance and reduced muscle guarding.
- Continuous Traction:Uninterrupted force delivery over extended durations, primarily in surgical recovery and inpatient settings. Acute care hospitals utilize this mode for post-operative spinal stabilization.
Intermittent traction dominates clinical procurement. Dynamic traction shows the steepest expansion trajectory through advanced rehabilitation protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rehabilitation centers and chiropractic clinics concentrate procurement authority across distinct national healthcare reimbursement architectures. Commercial insurance coverage for non-surgical spinal decompression therapy varies sharply by jurisdiction, fragmenting addressable patient pools.
United States
Medicare Advantage expansion into supplemental spinal therapies widens reimbursed traction intervention access for aging populations. FDA 510(k) premarket notification pathways govern powered traction device clearance with tightening clinical evidence documentation. The Southeast corridor from Florida through Georgia hosts dense chiropractic clinic networks where multi-site standardization drives vendor-managed equipment uptime preferences.
Germany
Advanced rehabilitation centers in Bavaria and Baden-Württemberg deploy dynamic traction systems for complex spine pathology protocols. EU Medical Device Regulation post-market surveillance requirements force systematic real-world performance data collection across distributed patient populations. The Stuttgart medical technology cluster concentrates precision actuator engineering talent for pneumatic traction component sourcing.
Japan
Aging demographics and statutory long-term care insurance coverage sustain institutional demand for electric traction systems in metropolitan Tokyo and Osaka rehabilitation networks. PMDA medical device classification rules intersect with METI industrial standards for electromechanical therapeutic equipment. The Nagoya precision manufacturing belt supplies medical-grade force sensors to domestic and export markets.
China
Private rehabilitation chain expansion in Shanghai and Beijing metro areas absorbs imported electric traction platforms alongside domestic manual system production. NMPA medical device registration requirements for Class II therapeutic equipment create multi-year approval timelines for foreign manufacturers. The Yangtze River Delta medical device manufacturing zone hosts contract assemblers serving price-sensitive provincial hospital procurement.
United Kingdom
NHS Integrated Care Systems in England are piloting outpatient spinal decompression protocols within musculoskeletal service redesign frameworks. MHRA post-Brexit medical device regulations maintain EU MDR alignment with additional UKCA marking requirements. The Cambridge-Oxford-London healthcare innovation corridor attracts traction technology startups targeting remote patient monitoring integration.
Spinal Traction Market Vendor Landscape
Player mix skews toward mid-cap specialists with dedicated regulatory infrastructure alongside diversified rehabilitation equipment conglomerates. The vendor base concentrates among European and North American manufacturers with multi-decade clinical channel relationships. Two strategic archetypes dominate: ISO 13485-certified platform specialists sustaining continuous audit compliance, and diversified physical therapy conglomerates leveraging cross-product bundling. Competitive moves center on cloud-connected platform development and subscription-based after-sales service unbundling.
Within the European manufacturing tier, BTL leverages its multi-market registration footprint across EEA member states to sustain compliance advantage. Saunders Group anchors North American chiropractic channel positioning through specialized distribution relationships. Chattanooga occupies the diversified equipment conglomerate archetype with cross-modal rehabilitation technology portfolios. These three entities exemplify how regulatory infrastructure scale and channel specialization erect barriers against smaller manufacturers facing collapsing ISO 13485 recertification windows.
| Leading Market Players |
|---|
| BTL |
| Spinetronics, LLC |
| Saunders Group |
| Chattanooga |
| North American Medical Corporation |
| Hill Laboratories Company |
| VAX-D Medical Technologies |
| Spinal Designs International |
| Scrip, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with German and Japanese precision actuator suppliers lock in component access and price visibility for electric traction system manufacturers navigating FDA 510(k) clearance cycles. These contractual structures insulate established players from spot-market volatility in medical-grade force sensors while compressing margin flexibility for smaller competitors unable to commit to minimum volume thresholds.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate chassis and frame procurement for traction table manufacturers. Three-tier pricing structure across premium programmable systems, standard electric platforms, and economy manual devices reflects ISO 13485 certification grade and after-sales service bundling. Pricing pressure stems from pneumatic traction miniaturization enabling direct-to-patient distribution that bypasses clinical markup layers. Chiropractic clinic networks exhibit lowest price sensitivity due to recurring service revenue attachment, while provincial hospitals in emerging markets drive aggressive negotiation on capital equipment.
Supply Chain Analysis
Inventory cycles for precision force sensors and medical-grade actuators stretch 16-20 weeks, constraining production flexibility for order surges. Component sourcing concentrates in Germany, Japan, and the United States, with Stuttgart and Nagoya engineering clusters anchoring pneumatic actuator and sensor supply. Raw material dependencies span medical-grade aluminum alloys, specialty polymers for patient contact surfaces, and rare-earth magnets for motorized systems. Single-source vulnerability runs through Japanese torque sensor suppliers serving Class IIa device manufacturers. Distribution runs through specialized medical device distributors in North America and direct hospital procurement teams in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal traction market is entering a cyclical recovery phase as Medicare Advantage expansion into supplemental spinal therapies broadens reimbursed patient access. Outpatient protocol shifts toward non-surgical interventions provide the cyclical driver justifying strategic positioning.
For Market Incumbents: Compound regulatory infrastructure advantage by accelerating ISO 13485 continuous audit compliance investments before smaller competitors exhaust recertification capacity. Deepen backward integration into precision actuator supply through captive sourcing agreements with Stuttgart engineering clusters. Channel control through vendor-managed equipment uptime guarantees defends against after-sales service unbundling threats from independent technical support providers. For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways for pneumatic home-care configurations offer fastest clearance velocity for algorithmic force-adjustment features. White-space concentration sits in direct-to-patient distribution models bypassing chiropractic clinic gatekeepers, particularly in United States Southeast corridor metro areas. Target Medicare Advantage supplemental benefit carve-outs as the most penetrable reimbursement channel. Go-to-market execution should anchor on smartphone-controlled deployment with HIPAA-compliant data architecture. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap platform specialists with existing EU MDR technical documentation and multi-site chiropractic network relationships. Long-term viability across the projection horizon favors manufacturers with cloud-connected traction platforms generating recurring data-service revenue alongside hardware placement. Acquisition target archetype: ISO 13485-certified pneumatic specialists with home-care regulatory clearances. Signal to watch: FDA enforcement discretion tightening on wellness versus medical claims for direct-to-patient marketing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Platform Development | Remote patient monitoring integration creates recurring data-service revenue streams alongside hardware sales. |
| FDA 510(k) Pre-Submission Investment | Early engagement with FDA software-as-a-medical-device guidance reduces validation uncertainty for algorithmic features. |
| EU MDR Technical Documentation Buildout | Periodic safety update reporting capabilities sustain multi-market registration across EEA member states. |
| Direct-to-Patient Channel Establishment | Bypassing chiropractic clinic intermediaries captures margin otherwise allocated to clinical gatekeepers. |
| Vendor-Managed Uptime Guarantee Programs | Subscription-based technical support aligns with multi-site clinic network standardization requirements. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with rehabilitation center directors, chiropractic clinic owners, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and commercial insurance reimbursement policy filings. Bottom-up triangulation across installed base estimates and top-down cross-check against equipment manufacturer revenue disclosures anchored volume and value outputs.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture, site-of-care deployment, operation mode, and reimbursement pathway. CAGRs were derived from weighted regression across historical procurement trends and protocol adoption curves. Industry-specific inputs included Medicare Advantage supplemental benefit expansion trajectories and EU MDR post-market surveillance compliance cost burdens.
Decision-makers should treat outputs as directional under assumptions of sustained commercial insurance reimbursement for non-surgical spinal decompression and stable FDA software-as-a-medical-device guidance evolution; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Contact Thermometer Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
EEG Electrodes Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Solar Surgical Light Market