
 United States Biopsy Devices Market | 2026-2036
United States Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biopsy Devices Market Intelligence
The United States biopsy devices market is consolidating around a widening gap between premium automated systems and commodity manual instruments. Medtronic plc leverages its integrated surgical ecosystem to anchor high-margin vacuum-assisted platforms in tertiary care networks. Hologic, Inc. specializes in stereotactic breast biopsy systems, sustaining technology leadership through dedicated imaging-to-biopsy workflows. Cardinal Health, Inc. competes on distribution density, controlling hospital supply chain access for disposable needle sets.
Biopsy devices are instruments engineered to extract tissue specimens for histopathological examination, typically incorporating stainless steel cannulas with gauge ranges from 8G to 20G and vacuum-assisted aspiration mechanisms rated for tissue core lengths up to 20 millimeters. Their primary commercial purpose centers on enabling minimally invasive cancer diagnosis while reducing patient trauma and procedure time relative to open surgical excision. Needle biopsy devices dominate procedural volume across outpatient settings, though vacuum-assisted devices command superior margin pools in breast and prostate applications. Image-guided biopsy procedures, particularly ultrasound-guided and stereotactic modalities, represent the fastest-expanding procedure category as interventional radiology suites multiply within community hospital systems. Automated systems technology is displacing manual instrument kits in high-throughput diagnostic labs where standardized tissue quality and reduced operator variability drive purchasing criteria.
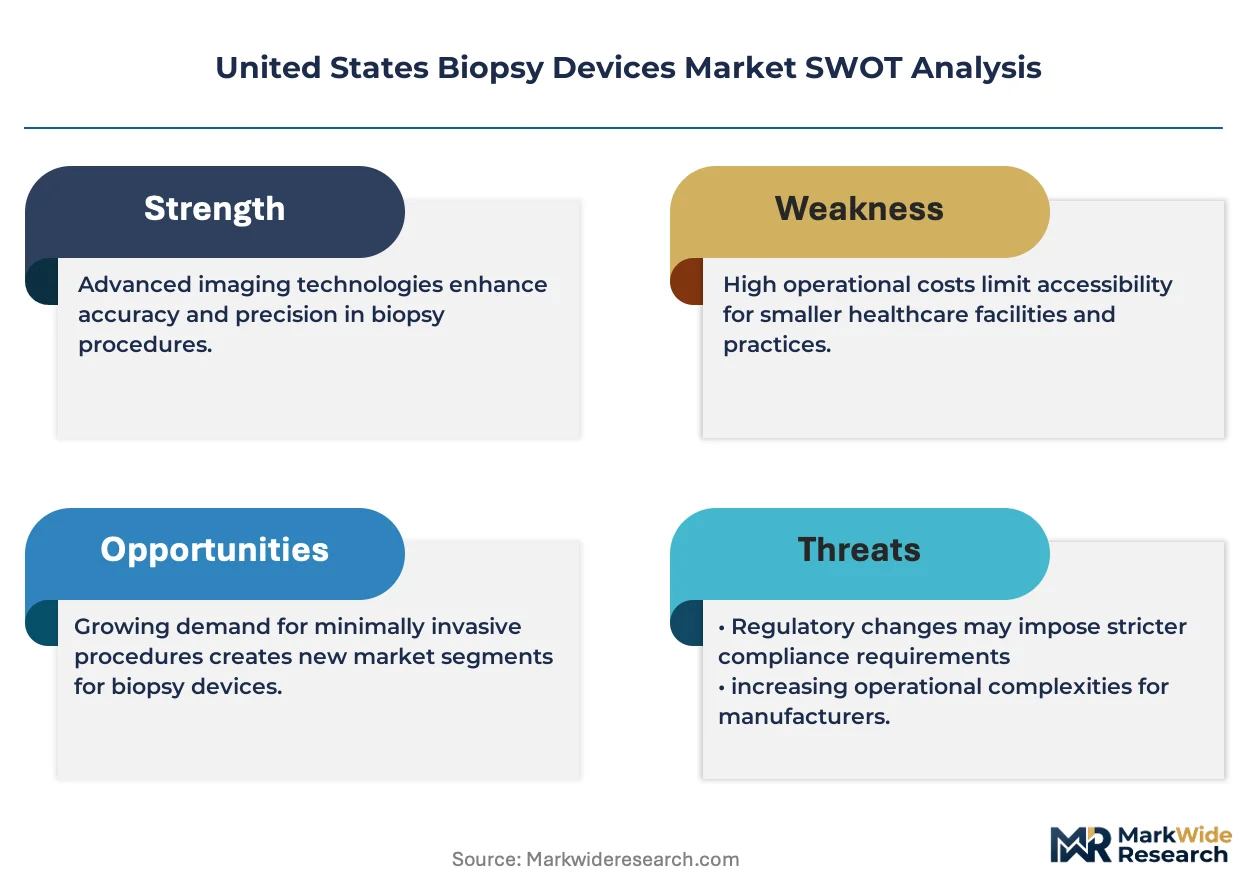
FDA 510(k) clearance requirements and HIPAA privacy mandates govern device commercialization and patient data handling, with the former extending development timelines and the latter constraining cloud-connected biopsy tracking systems. OSHA bloodborne pathogen standards additionally shape disposable instrument demand by mandating single-use protocols in ambulatory settings. Stakeholders must monitor CMS reimbursement rate adjustments for image-guided procedures and state-level certificate-of-need regulations affecting capital equipment placement in consolidated health systems.
Market Dynamics
Automated vacuum-assisted biopsy platforms are displacing manual needle kits across United States oncology networks, compressing procedure variability while elevating capital intensity requirements for ambulatory surgery centers.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage for stereotactic breast biopsy procedures in outpatient settings accelerates capital deployment by community hospital systems.
- Interventional radiology suite proliferation:Texas, California, and Florida oncology corridors drive demand concentration for ultrasound-guided and MRI-compatible biopsy systems.
- FDA 510(k) pathway efficiency:Class II device premarket notification timelines enable faster commercialization of iterative needle gauge and vacuum pressure improvements.
Market Restraints
- Stainless steel cannula cost volatility:Medical-grade 304/316L steel pricing fluctuations squeeze margin pools on disposable needle sets.
- Single-use mandate compliance:OSHA bloodborne pathogen standards elevate per-procedure supply costs relative to reusable instrument alternatives.
- Certificate-of-need barriers:State-level CON regulations in consolidated health systems delay capital equipment placement in secondary markets.
Strategic Opportunities
- Cloud-connected tracking systems:HIPAA-compliant specimen chain-of-custody platforms create service revenue attachment opportunities.
- Rural ambulatory penetration:Underserved markets in Mountain and Plains states present whitespace for mobile stereotactic biopsy units.
- Prostate fusion biopsy convergence:MRI-ultrasound registration technology integration opens urology-specific automated system demand.
Industry Challenges
- Interventional radiologist training pipeline:Fellowship program capacity constraints limit procedure volume expansion regardless of equipment availability.
- Legacy PACS integration complexity:Image-guided biopsy workstations require costly middleware development for hospital IT ecosystem compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biopsy Devices Market |
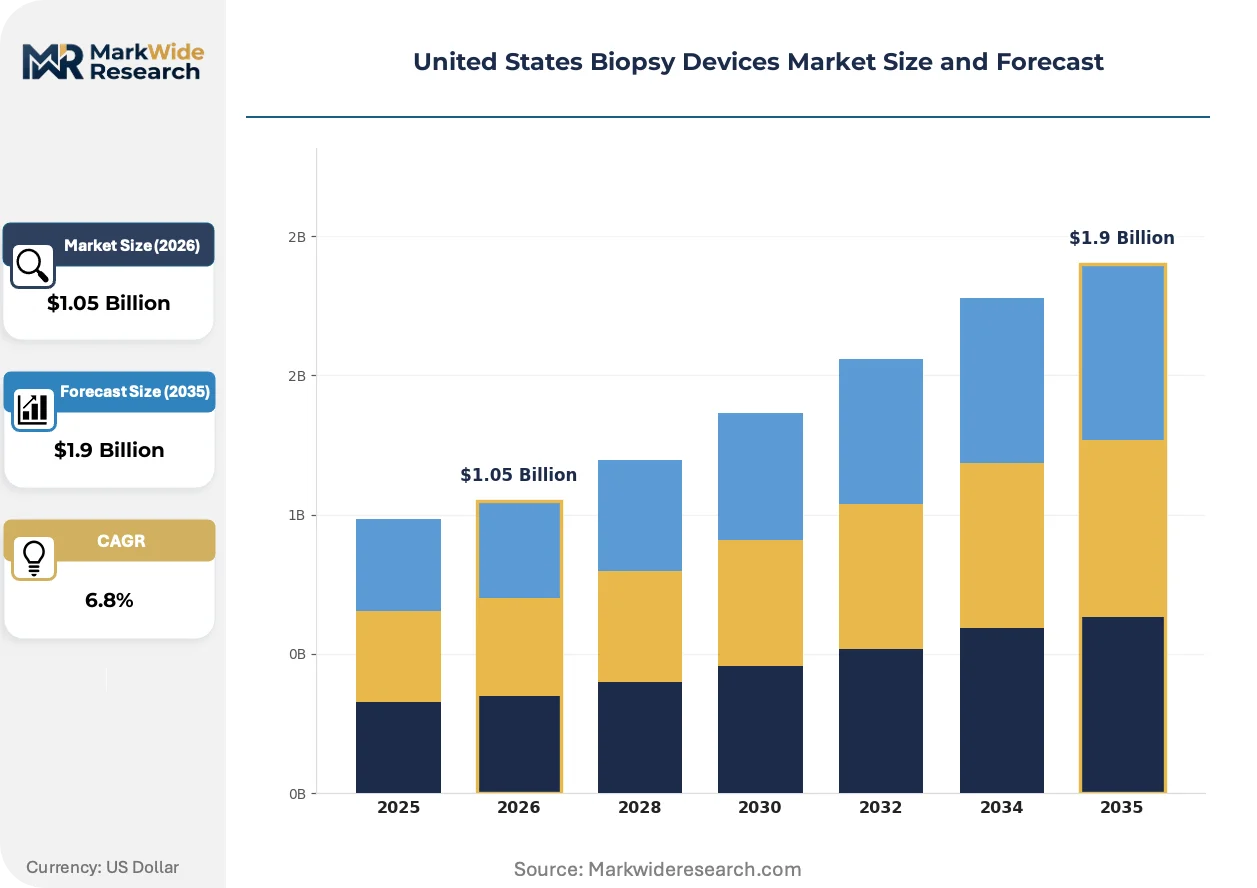
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy Devices, Core Biopsy Equipment, Vacuum-Assisted Devices, Surgical Biopsy Tools End User: Hospitals, Diagnostic Labs, Outpatient Clinics, Cancer Research Centers Procedure Type: Image-Guided Biopsy, Stereotactic Biopsy, Ultrasound Biopsy, MRI-Guided Biopsy Technology: Manual Devices, Automated Systems, Disposable Biopsy Instruments, Reusable Kits |
| Companies Covered | Devicor Medical Products, Inc., Medtronic plc, Cardinal Health, Inc., Hologic, Inc., Danaher Corporation, Becton, Dickinson and Company, Boston Scientific Corporation, Cook Medical, Argon Medical Devices, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biopsy Devices Market Strategic Shifts & Innovations
Biopsy device architecture is fragmenting along procedure-specific optimization lines, with manufacturers decoupling core aspiration mechanisms from imaging modality interfaces to accelerate platform iteration cycles.
Disposable needle cartridge design is modularizing around gauge-standardized interfaces that accommodate 8G through 20G configurations within single vacuum-assisted driver platforms. Community hospital systems in the Southeast are adopting these systems at twice the replacement rate of standalone manual kits. This modularity is compressing capital commitment thresholds for mid-tier diagnostic labs while fragmenting aftermarket service revenue streams.
FDA 510(k) substantial equivalence requirements for Class II biopsy devices are tightening predicate device justification standards, extending premarket review timelines for novel vacuum pressure specifications. Manufacturers are responding by anchoring submissions to established predicate families with conservative technical deltas. Breast biopsy system categories face the most pronounced documentation burden increases.
Hospital supply chain consolidation is compressing vendor rosters to three or fewer preferred biopsy device suppliers per integrated delivery network. Group purchasing organizations are unbundling capital equipment from disposable commitments, forcing manufacturers to compete on per-procedure economics rather than bundled financing. This pattern is most visible in California-based health systems with centralized procurement functions.
United States Biopsy Devices Market Segmentation
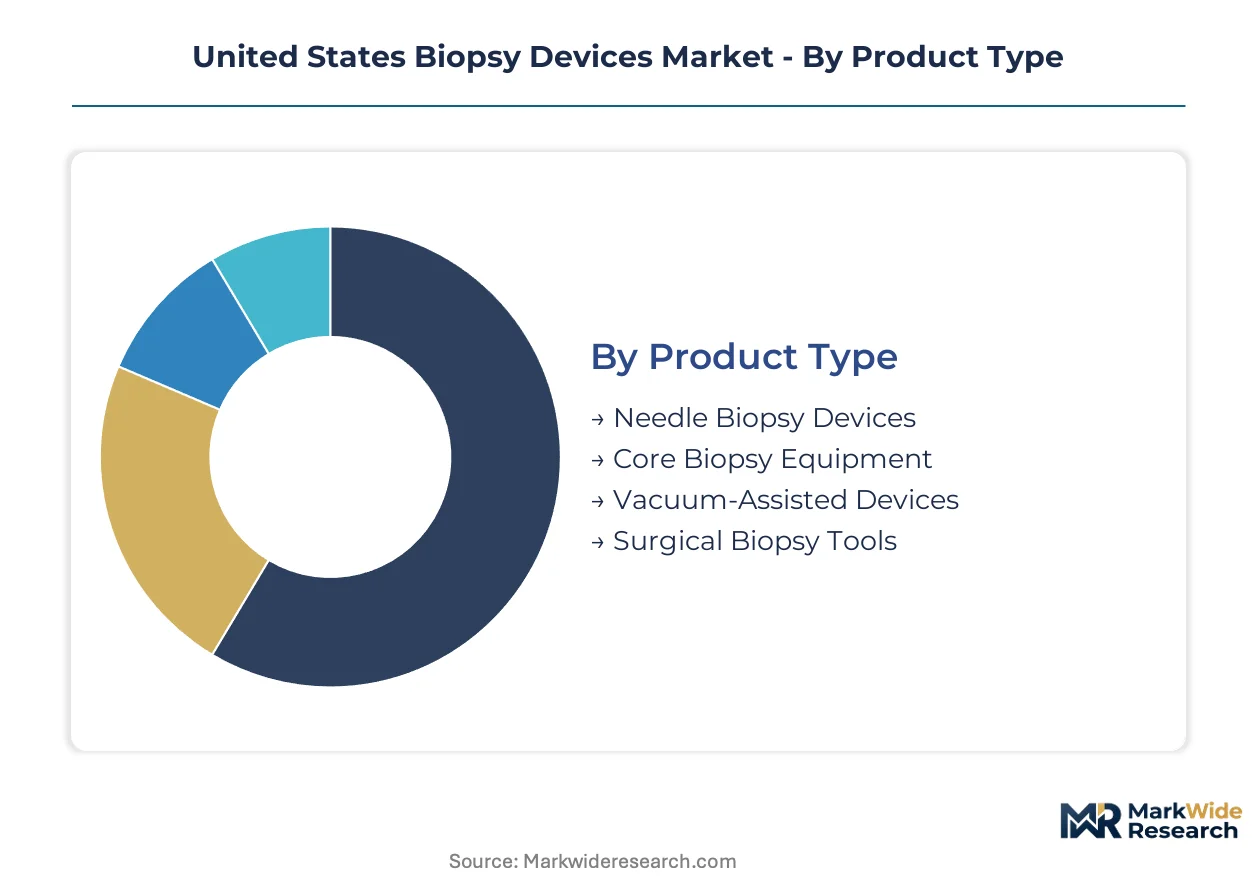
Biopsy device purchasing decisions fragment across procedure specificity, capital intensity, and reimbursement alignment. Each segmentation axis reveals distinct margin pools and vendor positioning strategies.
Product Type:
Customization intensity varies from commodity needle sets to integrated vacuum platforms requiring dedicated capital planning.
- Needle Biopsy Devices:Stainless steel cannulas in 8G-20G configurations dominate procedural volume across ambulatory settings. Texas oncology corridors absorb the highest throughput as community hospitals expand same-day diagnostic capacity.
- Vacuum-Assisted Devices:Automated aspiration mechanisms rated for 20mm tissue cores command premium positioning in breast and prostate applications. California integrated delivery networks concentrate procurement of these systems for stereotactic suites.
- Core Biopsy Equipment:Spring-loaded mechanisms for solid organ sampling serve interventional radiology departments with moderate capital budgets.
- Surgical Biopsy Tools:Excisional and incisional instruments retain relevance in cases demanding larger specimen volumes where percutaneous methods prove inadequate.
Most installed capacity flows through Needle Biopsy Devices. Expansion is steepest in Vacuum-Assisted Devices.
End User:
Customer concentration shapes pricing power, with consolidated systems extracting per-procedure economics from vendors.
- Hospitals:Tertiary care networks anchor capital equipment decisions, deploying vacuum-assisted platforms across interventional radiology and surgical oncology departments. Florida health systems drive concentration through certificate-of-need enabled expansion.
- Diagnostic Labs:High-throughput reference laboratories standardize on automated systems to minimize operator variability and specimen quality drift. California-based chains influence national purchasing patterns through volume aggregation.
- Outpatient Clinics:Freestanding ambulatory surgery centers prioritize disposable instrument efficiency over capital intensity.
- Cancer Research Centers:Academic medical centers demand MRI-compatible and fusion-registered systems for protocol development.
Procurement volume concentrates in Hospitals. Margin expansion is strongest in Diagnostic Labs.
Procedure Type:
Imaging modality integration determines workflow complexity and reimbursement capture.
- Image-Guided Biopsy:Ultrasound-directed procedures dominate outpatient volume through real-time visualization and minimal facility requirements. Texas community hospital systems deploy these across expanding interventional radiology suites.
- Stereotactic Biopsy:X-ray coordinated breast tissue extraction commands dedicated capital investment and specialized technician training. CMS reimbursement expansion accelerates deployment in California and Florida networks.
- Ultrasound Biopsy:Portable guidance systems enable point-of-care deployment in ambulatory settings with lower infrastructure thresholds.
- MRI-Guided Biopsy:Closed-bore and open-magnet compatible devices serve academic centers and specialized prostate diagnostic programs.
Procedure volume concentrates in Image-Guided Biopsy. Technical sophistication is advancing fastest in Stereotactic Biopsy.
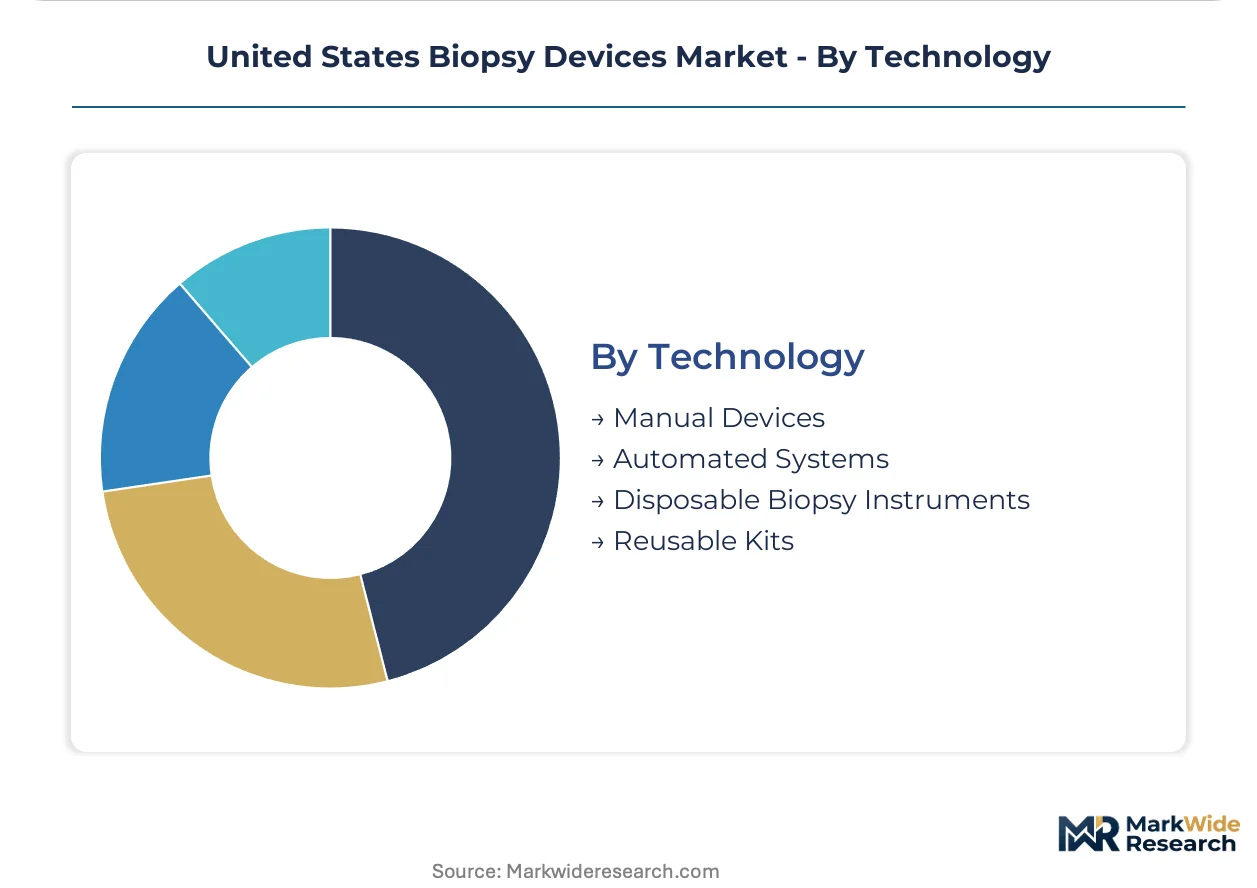
Technology:
Capital-labor tradeoffs define adoption curves across customer tiers.
- Automated Systems:Vacuum-assisted drivers with standardized needle interfaces compress procedure variability and elevate tissue specimen consistency. Southeast community hospitals adopt these at twice the replacement rate of manual alternatives.
- Disposable Biopsy Instruments:Single-use protocols mandated by OSHA bloodborne pathogen standards dominate ambulatory settings where reprocessing infrastructure is absent.
- Manual Devices:Low-cost spring-loaded and fine-needle aspiration kits retain share in resource-constrained environments and backup scenarios.
- Reusable Kits:Sterilizable instruments persist in select surgical applications despite regulatory pressure toward disposable protocols.
Revenue concentration sits with Disposable Biopsy Instruments. Capital deployment is shifting toward Automated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional radiologist density in Texas, California, and Florida anchors national procedure volume distribution. These three states concentrate over forty percent of active biopsy-capable physicians. Workforce clustering directly shapes equipment procurement patterns across hospital systems.
Texas
MD Anderson Cancer Center and Houston Methodist anchor stereotactic breast biopsy deployment in the Texas Medical Center corridor. FDA 510(k) clearance timelines for Class II vacuum-assisted devices align with state certificate-of-need pathways governing capital equipment placement. Dallas-Fort Worth health systems expand same-day diagnostic capacity through ambulatory surgery center networks.
California
Kaiser Permanente and Sutter Health consolidate procurement through centralized supply chain functions in the Bay Area and Los Angeles basins. HIPAA compliance mandates constrain cloud-connected specimen tracking system vendors serving these integrated delivery networks. San Diego oncology corridors drive MRI-compatible biopsy system demand for prostate fusion applications.
Florida
AdventHealth and HCA Florida anchor interventional radiology suite expansion across the I-4 corridor from Tampa to Orlando. State-level CON regulations enable controlled capital deployment in secondary markets without equipment oversupply. Miami-Dade academic medical centers specialize in pediatric biopsy protocols requiring dedicated needle gauge configurations.
New York Metro
Memorial Sloan Kettering and NYU Langone anchor high-throughput diagnostic lab standardization on automated vacuum-assisted platforms. OSHA bloodborne pathogen enforcement in dense urban ambulatory settings accelerates single-use instrument conversion. Westchester and Long Island community hospitals lag Manhattan tertiary centers in stereotactic suite penetration.
Midwest
Cleveland Clinic and Northwestern Medicine anchor image-guided biopsy standardization across Ohio and Illinois corridors. Rural health systems in Indiana and Michigan deploy mobile stereotactic units to address interventional radiologist scarcity. Chicago-based group purchasing organizations unbundle capital equipment from disposable commitments, forcing per-procedure economics competition.
United States Biopsy Devices Market Key Industry Players
Capital-heavy integrated surgical ecosystem providers compete with asset-light specialized imaging-to-biopsy workflow designers. The vendor base concentrates around three strategic tiers: diversified medical technology conglomerates, diagnostic imaging specialists, and distribution-anchored supply chain controllers. Market consolidation accelerates through hospital system vendor roster compression and group purchasing organization centralization. Competitive positioning depends on securing preferred supplier status within integrated delivery networks and demonstrating per-procedure cost efficiency against manual instrument alternatives.
Within the diversified medical technology tier, Medtronic plc exemplifies capital-intensive platform anchoring through integrated surgical ecosystems. Hologic, Inc. occupies a position as imaging-to-biopsy workflow specialist with dedicated breast health focus. Cardinal Health, Inc. represents distribution density archetype controlling hospital supply chain access for disposable instrument flows. These three anchors demonstrate the strategic segmentation between capital equipment, imaging integration, and supply chain control vectors shaping procurement decisions.
| Leading Market Players |
|---|
| Devicor Medical Products, Inc. |
| Medtronic plc |
| Cardinal Health, Inc. |
| Hologic, Inc. |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Cook Medical |
| Argon Medical Devices, Inc. |
| Others |
Cost & Logistics Intelligence
Interventional radiologist concentration in Texas, California, and Florida oncology corridors generates labor-cost differentials that widen spreads between premium vacuum-assisted platforms and commodity manual kits. FDA 510(k) clearance timelines and OSHA single-use mandates compound cost layering across pricing tiers.
Pricing Analysis
Bundled capital-plus-disposable contracts are fragmenting into unbundled per-procedure economics as group purchasing organizations separate equipment financing from needle set supply commitments. Three-tier pricing structure across premium automated systems, standard vacuum-assisted platforms, and economy manual instruments reflects differentiation by FDA predicate device lineage and imaging modality integration depth. Pricing pressure stems from stainless steel 304/316L cannula cost volatility squeezing margin pools on high-volume disposable sets. Outpatient clinics exhibit highest price sensitivity; tertiary care networks anchor premium tier absorption.
Supply Chain Analysis
Dual-sourcing qualification requirements for medical-grade stainless steel cannulas are mandating supplier redundancy across domestic and offshore forging operations. Manufacturing concentrates in the United States, Germany, and Japan for precision cannula fabrication; Taiwan and South Korea anchor electronics for automated driver systems. Supply chain risk centers on medical-grade steel tariff exposure disrupting just-in-time needle set production. Distribution runs through Cardinal Health and regional group purchasing organization channels into integrated delivery network warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in Mountain and Plains states where interventional radiologist scarcity delays automated system deployment despite favorable CMS reimbursement differentials versus coastal markets.
For Market Incumbents: Deploy cloud-connected specimen tracking capabilities to anchor service revenue attachment against disposable commoditization pressure from distribution-anchored competitors. Consolidate preferred supplier status within California and Florida integrated delivery networks through dedicated imaging-to-biopsy workflow integration. Counter emerging manual kit challengers by accelerating modular needle cartridge standardization across vacuum-assisted platforms. For New Entrants and Emerging Players: MRI-ultrasound fusion registration technology for prostate biopsy applications offers the most penetrable white-space wedge against established breast-focused incumbents. Target rural ambulatory surgery centers in Texas secondary markets with mobile stereotactic unit leasing models bypassing certificate-of-need capital barriers. Pursue direct-to-clinic distribution partnerships circumventing compressed GPO vendor rosters. For Investors and Strategic Acquirers: Valuations sit cheapest among diagnostic imaging specialists lacking automated biopsy platform integration but holding FDA 510(k) predicate device libraries. Long-term viability favors acquisition targets with HIPAA-compliant cloud infrastructure and established hospital IT middleware compatibility. Watch for interventional radiology fellowship program expansion rates as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated predicate device anchoring compresses premarket review timelines for iterative vacuum pressure specifications. |
| Hospital System Partnership | Preferred supplier status within Kaiser Permanente or Sutter Health secures per-procedure economics against bundled competitors. |
| Software Companion Development | HIPAA-compliant specimen chain-of-custody platforms create recurring service revenue attachment beyond hardware sales. |
| Reimbursement Strategy | CMS coverage expansion for stereotactic breast biopsy in outpatient settings drives capital deployment velocity. |
| CE Marking Pathway | European MDR compliance enables offshore revenue diversification for domestic manufacturers facing GPO consolidation pressure. |
Research Approach
Multiple input streams — primary interviews with interventional radiologists and hospital purchasing committees, secondary validation through FDA 510(k) filings and CMS reimbursement databases, and triangulation against GPO contract disclosures — were reconciled to construct market estimates. Conversations with biomedical engineers and ambulatory surgery center administrators informed procedure volume assumptions. Bottom-up modeling of needle set consumption and top-down reconciliation against capital equipment shipment data anchored value projections.
Data-stream reconciliation across product type, end user concentration, procedure modality, and technology adoption intensity generated segment-level forecasts over the projection horizon. CAGRs were derived from fitted growth curves against historical capital deployment patterns and interventional radiology workforce expansion trajectories. Modeling incorporated stainless steel pricing indices, certificate-of-need regulatory status by state, and cloud-connected tracking system penetration rates as industry-specific inputs.
The model holds under stable FDA Class II device review timelines and sustained CMS outpatient reimbursement; deviation in OSHA bloodborne pathogen standard enforcement intensity or medical-grade steel tariff regimes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Biopsy Devices Market