
 Contactless Vital Sign Monitoring Device Validation Test Platforms Market | 2026-2036
Contactless Vital Sign Monitoring Device Validation Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Vital Sign Monitoring Device Validation Test Platforms Market Insights
Class A electromagnetic immunity certification is unwinding legacy test platform specifications across the contactless vital sign monitoring supply chain. Philips leverages in-house radar calibration laboratories to sustain North American market presence. GE HealthCare anchors its competitive stance through end-to-end validation workflows spanning thermal imaging and ultrasonic modalities. Medtronic differentiates by specializing in cardiac-focused test protocols that satisfy emerging IEC 60601-2-47 derivative standards.
Contactless vital sign monitoring device validation test platforms comprise calibrated hardware-software systems that verify measurement accuracy, signal fidelity, and safety compliance for non-contact physiological sensors operating across radio-frequency, optical, and acoustic detection principles. These platforms simulate patient-present conditions using anthropomorphic phantoms and controlled motion artifacts to certify devices for clinical deployment prior to regulatory submission. Radar-based technology segments lead current platform deployments due to penetration advantages through clothing and bedding materials. Cloud-based deployment architectures represent the fastest-expanding configuration as telehealth providers demand distributed validation access across multi-site provider networks.
FDA premarket notification requirements under 21 CFR 892.2050 classifications intersect with IEC 60601-1-2 electromagnetic compatibility standards to define test platform functional baselines for US market entry. The EU Medical Device Regulation and CE marking processes under Notified Body supervision impose additional clinical validation documentation burdens that shape platform feature prioritization. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled contactless monitoring algorithms to anticipate validation protocol amendments that will reshape platform R&D roadmaps.
Market Dynamics
Radar-based validation suites are compressing platform refresh cycles as hospital ICUs and telehealth providers demand electromagnetic compatibility thresholds that exceed legacy specifications. Philips and GE HealthCare are reconfiguring calibration laboratory networks to capture Class A immunity certification workflows.
Growth Catalysts
- Telehealth network expansion:Multi-site provider networks in the United States require distributed validation access, accelerating cloud-based platform deployments across remote patient monitoring reimbursement pathways.
- IEC 60601-1-2 harmonization:Electromagnetic compatibility standard convergence between FDA 21 CFR 892.2050 classifications and EU Medical Device Regulation reduces duplicate certification burdens for cross-border device submissions.
- Radar penetration advantages:Radio-frequency detection through clothing and bedding materials eliminates skin-contact artifacts, driving procurement of phantom-based validation systems in sleep medicine and neonatal care units.
Market Restraints
- Phantom material cost volatility:Tissue-mimicking gel formulations and anthropomorphic casting compounds face petroleum-derived input price swings that compress platform manufacturer margins.
- Calibration laboratory concentration:North American radar calibration infrastructure clusters around FDA-registered facilities in Massachusetts and California, creating geographic supply risk for validation service access.
- Acoustic modality substitution:Ultrasonic validation platforms for cardiac monitoring applications capture budget allocations that otherwise flow to radio-frequency test suites.
Strategic Opportunities
- Japan reimbursement maturation:METI-aligned remote patient monitoring incentive structures create first-mover advantage for validation platform vendors establishing PMDA premarket consultation relationships.
- AI algorithm validation protocols:Emerging FDA guidance on artificial intelligence-enabled contactless monitoring creates white space for test platforms incorporating synthetic data generation and algorithmic bias detection modules.
- Thermal-optical convergence:Hybrid validation workflows combining infrared thermography with radar signal processing address multi-parameter monitoring device certification requirements in single-platform configurations.
Industry Challenges
- Electromagnetic compatibility engineering talent scarcity:Specialized expertise in IEC 60601-1-2 test method execution concentrates among legacy medical device regulatory consultants, constraining platform R&D team scaling.
- Notified Body queue compression:EU Medical Device Regulation clinical validation documentation review timelines extend CE marking cycles, delaying platform feature releases synchronized with device manufacturer product launches.
- Legacy hospital IT integration friction:Validation platform data formats require middleware development for seamless electronic health record connectivity, adding implementation complexity for procurement decision-makers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Vital Sign Monitoring Device Validation Test Platforms Market |
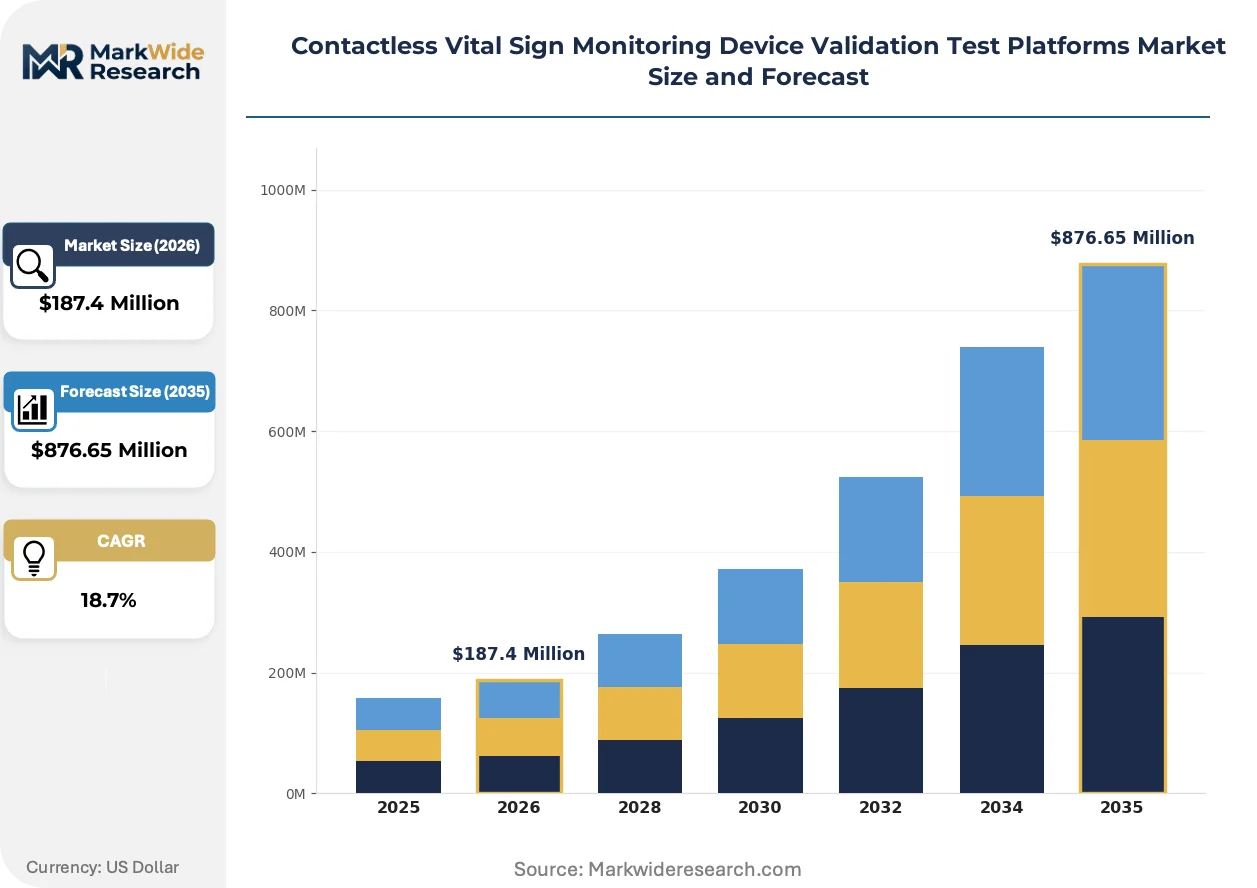
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar-Based, Camera-Based, Infrared, Thermal Imaging, Ultrasonic Application: Sleep Analysis, Stress Detection, Respiratory Monitoring, Cardiac Evaluation, Fitness Tracking End User: Research Institutes, Telehealth Providers, Diagnostic Laboratories, Sports Science Centers, Insurance Firms Deployment: On-Premise, Cloud-Based, Edge Computing, Hybrid Systems |
| Companies Covered | Philips, GE HealthCare, Medtronic, Omron Healthcare, Abbott Laboratories, Dexcom, Boston Scientific, VitalConnect, AliveCor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Vital Sign Monitoring Device Validation Test Platforms Market Trends and Innovations
Cloud-native validation architectures are restructuring how telehealth providers access distributed test capabilities, while regulatory artificial intelligence guidance is forcing platform feature roadmaps toward algorithmic transparency modules.
Digital phantom libraries with programmable motion artifact simulation are displacing physical anthropomorphic casting for repetitive validation cycles. Telehealth providers and medical device manufacturers are adopting these synthetic patient models at accelerating pace to compress premarket submission timelines. This displacement is enabling platform-as-a-service business models that reduce capital expenditure barriers for mid-sized device developers.
FDA premarket guidance on electromagnetic compatibility thresholds is intersecting with tightened IEC 60601-1-2 Edition 4.1 requirements to elevate shielding effectiveness testing mandates. Industrial consequence includes mandatory anechoic chamber investments for platform operators seeking dual US-EU market coverage. Cardiac-focused radar validation protocols face the most acute compliance pressure, with Medtronic and specialty cardiac sensor developers accelerating shielding redesign cycles.
Hospital procurement committees are consolidating validation platform vendor relationships around end-to-end workflow coverage rather than point-solution acquisitions. Medical device manufacturers are displacing standalone thermal imaging or ultrasonic test suites with multi-modality platforms that certify radar, optical, and acoustic sensors through unified phantom interfaces. Germany and Japan exhibit the most concentrated preference consolidation, with university hospital procurement offices driving standardization toward three-vendor shortlists.
Contactless Vital Sign Monitoring Device Validation Test Platforms Market Segmentation
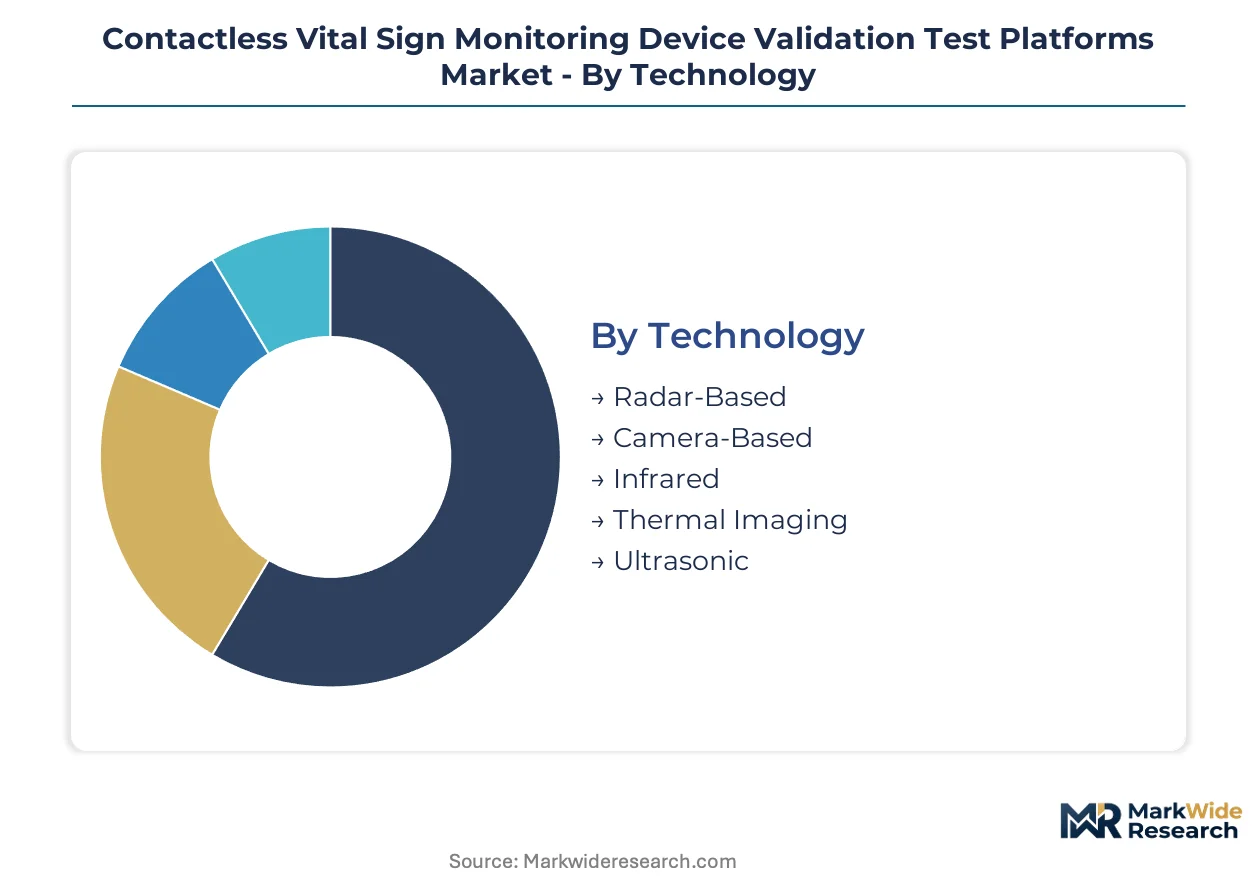
Validation platform procurement patterns diverge sharply across detection modalities and deployment architectures. Segment boundaries determine pricing power, with cloud-native configurations and radar-based systems commanding premium positioning.
Technology:
Margin pools concentrate in radio-frequency and optical detection segments where phantom calibration complexity sustains pricing premiums.
- Radar-Based:Radio-frequency detection through clothing and bedding eliminates skin-contact artifacts. Hospital ICUs in the United States and sleep medicine units in Germany drive procurement for phantom-based validation systems.
- Camera-Based:Optical flow algorithms process facial colorimetric changes for heart rate variability assessment. Telehealth providers in Japan favor these platforms for remote patient monitoring reimbursement pathways.
- Infrared:Near-infrared spectroscopy platforms target peripheral oxygenation validation.
- Thermal Imaging:Infrared thermography systems measure cutaneous temperature distribution for stress detection applications.
- Ultrasonic:Doppler-based cardiac output validation competes for budget allocations in cardiology-focused test suites.
The dominant share belongs to Radar-Based systems, while Camera-Based platforms are closing the gap fastest through telehealth network expansion.
Application:
Volume concentration tracks reimbursement pathway maturity, with respiratory and cardiac applications anchored to established CPT codes.
- Respiratory Monitoring:Apnea-hypopnea index validation drives phantom-based test suite procurement. Sleep medicine centers in Massachusetts and California anchor North American demand.
- Cardiac Evaluation:Radar-derived ballistocardiography and photoplethysmography validation satisfy IEC 60601-2-47 derivative standards. Medtronic and specialty cardiac sensor developers accelerate shielding redesign cycles.
- Sleep Analysis:Polysomnography-equivalent contactless validation targets home sleep testing market expansion.
- Stress Detection:Autonomic nervous system assessment through thermal-optical fusion addresses workplace wellness applications.
- Fitness Tracking:Consumer-grade device validation represents price-sensitive demand tier.
Respiratory Monitoring captures the largest installed base, though Cardiac Evaluation is expanding most quickly through FDA premarket guidance tightening.
End User:
Customer type determines procurement authority structure, with telehealth providers driving cloud-native feature roadmaps.
- Telehealth Providers:Multi-site networks require distributed validation access across reimbursement-mature markets. Cloud-based platform deployments accelerate through United States remote patient monitoring incentive structures.
- Research Institutes:Academic medical centers in Germany and Japan prioritize multi-modality platforms for algorithm development.
- Diagnostic Laboratories:Centralized testing facilities favor on-premise configurations with high-throughput phantom automation.
- Sports Science Centers:Athlete monitoring applications demand portable validation systems for field deployment.
- Insurance Firms:Risk assessment use cases drive interest in population-scale validation data aggregation.
Telehealth Providers command the dominant procurement volume, while Research Institutes are gaining share fastest through AI algorithm validation protocol development.
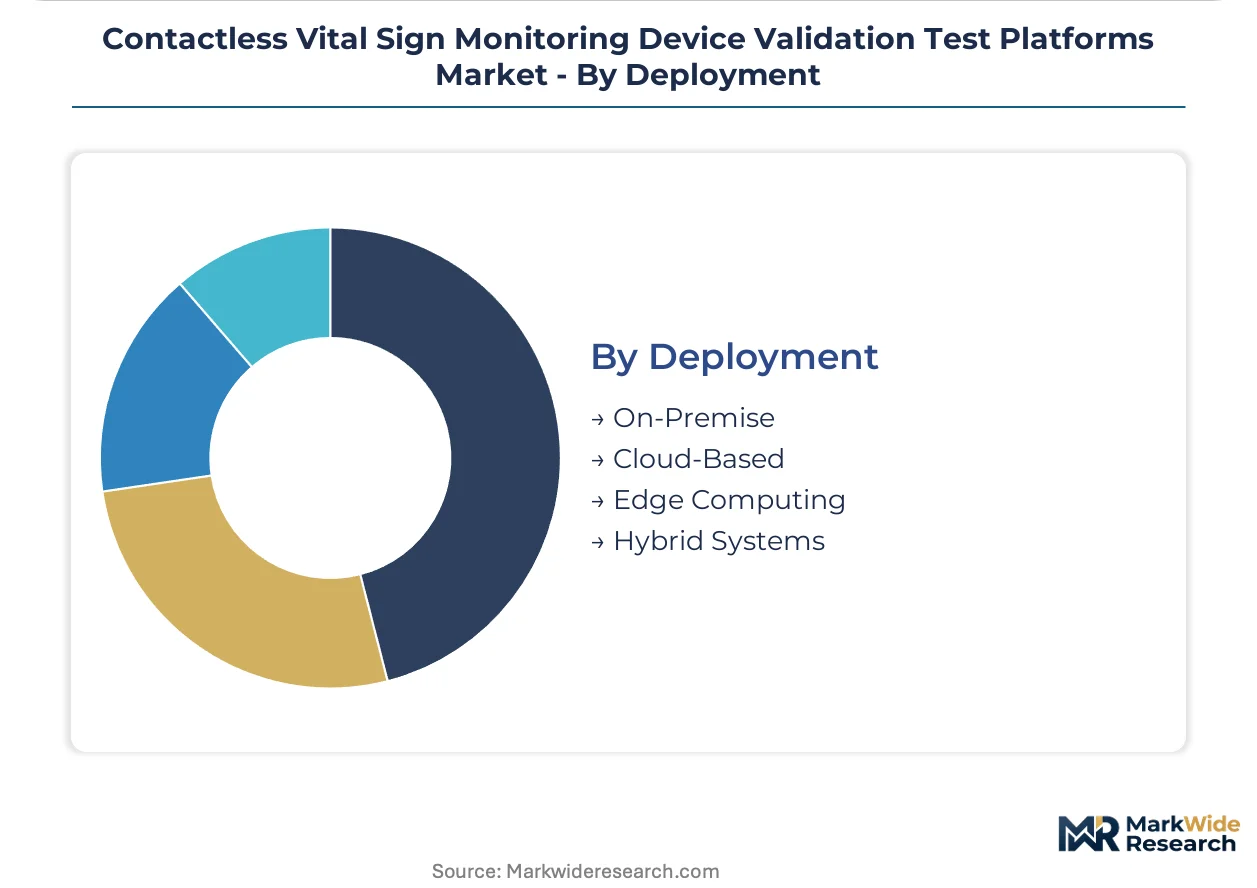
Deployment:
Architecture choice reflects IT infrastructure maturity and data sovereignty requirements across end-user organizations.
- Cloud-Based:Distributed validation access enables multi-site provider network coverage. Telehealth procurement committees prioritize these configurations for reduced capital expenditure barriers.
- On-Premise:Anechoic chamber integration and phantom automation systems anchor high-throughput certification workflows. FDA-registered facilities in Massachusetts and California concentrate this demand.
- Edge Computing:Latency-sensitive validation for real-time algorithm feedback loops.
- Hybrid Systems:Split architectures balance data sovereignty with remote collaboration features.
On-Premise retains the largest installed base, though Cloud-Based configurations are climbing the fastest through platform-as-a-service business model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telehealth providers in Japan exhibit the lowest price elasticity for validation platforms, while sports science centers in Brazil face acute budget constraints that compress procurement timelines. Hospital procurement committees in Germany demonstrate intermediate sensitivity, prioritizing multi-modality coverage over single-technology point solutions.
United States
Hospital ICUs in Massachusetts and California drive phantom-based radar validation procurement for sleep medicine applications. FDA premarket notification requirements under 21 CFR 892.2050 intersect with tightened electromagnetic compatibility thresholds to elevate platform specifications. The Greater Boston cluster anchors North American calibration laboratory infrastructure, concentrating FDA-registered facilities that service cross-border device submissions.
Germany
University hospital procurement offices standardize validation vendor relationships around three-platform shortlists covering radar, optical, and acoustic modalities. EU Medical Device Regulation clinical validation documentation requirements under Notified Body supervision extend CE marking cycles and reshape feature prioritization. The Bavaria region concentrates multi-modality platform R&D activity, with Munich-based academic medical centers driving algorithm development partnerships.
Japan
METI-aligned remote patient monitoring incentive structures create first-mover positioning for validation platform vendors establishing PMDA premarket consultation relationships. The country's national pharmaceutical regulator tightens electromagnetic immunity certification workflows for cardiac-focused radar applications. The Kanto region around Tokyo anchors telehealth network expansion, with cloud-based platform deployments accelerating across reimbursement-mature provider networks.
United Kingdom
NHS procurement frameworks prioritize distributed validation access for multi-site telehealth provider networks, compressing capital expenditure barriers through platform-as-a-service adoption. MHRA convergence with EU Medical Device Regulation standards reduces duplicate certification burdens for cross-border device submissions. The London-Southeast corridor concentrates diagnostic laboratory demand for high-throughput phantom automation systems.
South Korea
MFDS regulatory harmonization with IEC 60601-1-2 Edition 4.1 requirements elevates shielding effectiveness testing mandates for cardiac radar validation protocols. The Seoul Capital Area anchors telehealth provider procurement of camera-based platforms for remote patient monitoring reimbursement pathways. Daegu-Gyeongbuk region research institutes prioritize multi-modality configurations for AI algorithm validation protocol development.
Contactless Vital Sign Monitoring Device Validation Test Platforms Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the validation platform supply chain. The market structure consolidates around diversified medical device conglomerates with captive calibration infrastructure, while mid-sized specialists occupy niche modality segments. Three archetypes dominate: end-to-end workflow providers, cardiac-focused protocol specialists, and cloud-native platform-as-a-service vendors. Competitive moves concentrate on strategic partnerships for phantom material supply security and geographic expansion into reimbursement-mature Asian markets.
Within the diversified conglomerate tier, Philips and GE HealthCare represent archetypal end-to-end workflow providers with established North American market presence. Medtronic occupies a distinct position as a cardiac-focused protocol specialist, exemplifying the specialist archetype that differentiates through IEC 60601-2-47 derivative standard compliance. These three companies anchor competitive dynamics, with their respective positioning in radar calibration laboratories, multi-modality coverage, and cardiac sensor shielding redesign cycles shaping platform feature roadmaps and vendor consolidation patterns.
| Leading Market Players |
|---|
| Philips |
| GE HealthCare |
| Medtronic |
| Omron Healthcare |
| Abbott Laboratories |
| Dexcom |
| Boston Scientific |
| VitalConnect |
| AliveCor |
| Others |
Pricing and Supply Chain Analysis
Ninety-day phantom material lead times compress platform manufacturer margins while concentrating pricing power among FDA-registered calibration laboratories in Massachusetts and California. This inventory-to-certification nexus tethers valuation to electromagnetic compatibility testing throughput rather than hardware production scale alone.
Pricing Analysis
After-sales service contracts and recalibration subscriptions generate lifetime value exceeding initial platform sales by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 60601-1-2 Edition 4.1 certification grade and phantom automation density. Pricing pressure stems from acoustic modality substitution in cardiac monitoring applications, where ultrasonic validation platforms capture budget allocations. Telehealth providers exhibit lowest price sensitivity due to reimbursement pathway maturity, while sports science centers face acute capital constraints.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for petroleum-derived phantom gel formulations and anechoic chamber shielding materials. Manufacturing concentrates in the United States, Germany, and Japan, with tissue-mimicking compound production anchored in Massachusetts and Bavaria. Raw material dependencies include radar substrate laminates, infrared detector arrays, and anthropomorphic casting polymers. Single-source vulnerability concentrates in FDA-registered calibration infrastructure. Distribution runs through medical device OEM direct sales and GPO-negotiated hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as AI algorithm validation protocols create specialist niches alongside diversified conglomerate dominance. Telehealth network expansion fragments procurement authority across multi-site provider organizations.
For Market Incumbents: Fortify calibration laboratory networks through captive phantom material supply and Class A immunity certification investments. Electromagnetic compatibility engineering talent scarcity threatens R&D scaling velocity. Backward integration into tissue-mimicking gel formulations defends margin position against petroleum input volatility. For New Entrants and Emerging Players: PMDA premarket consultation fast-tracks unlock Japan reimbursement maturation before diversified conglomerates consolidate relationships. White space concentrates in cloud-native platform-as-a-service configurations for mid-sized device developers. Target telehealth procurement committees with distributed validation access and reduced capital expenditure positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates spinning non-core validation platform divisions. Five-to-ten year viability hinges on AI algorithm validation protocol standardization. Signal to monitor: FDA guidance finalization on artificial intelligence-enabled contactless monitoring algorithms.| Strategic Initiative | Industry Significance |
|---|---|
| Class A Immunity Certification Investment | Philips and GE HealthCare anchor competitive positioning through anechoic chamber infrastructure in Massachusetts. |
| Cloud-Native Platform Deployment | Telehealth providers in the United States accelerate distributed validation access across reimbursement-mature networks. |
| Phantom Material Supply Security | Petroleum-derived gel formulation volatility threatens margin compression for platform manufacturers without captive supply. |
| AI Algorithm Validation Protocol Development | FDA premarket guidance on artificial intelligence-enabled monitoring creates white space for synthetic data generation modules. |
| PMDA Premarket Consultation Relationship | METI-aligned remote patient monitoring incentives in Japan reward first-mover validation platform vendors. |
Research Methodology
The analysis maps radar-based, camera-based, and ultrasonic validation segments, each validated through biomedical engineers, hospital purchasing committees, telehealth procurement officers, and regulatory affairs specialists. Primary interviews with GPO contracts managers and phantom calibration laboratory directors combined with secondary validation against FDA 510(k) filings, IEC standard revision documents, CMS Medicare remote patient monitoring reimbursement data, and hospital procurement database extracts. Bottom-up platform deployment counts triangulated against top-down medical device manufacturer R&D expenditure allocations.
Consistency checks validated volume and value outputs against electromagnetic compatibility testing throughput benchmarks and calibration laboratory capacity utilization rates across the projection horizon. Segmentation dimensions modeled include detection modality, deployment architecture, end-user organization type, and regional regulatory cluster. CAGRs derived from platform refresh cycle compression rates and telehealth network expansion trajectories. Industry-specific inputs encompass FDA premarket notification timelines and Notified Body queue compression effects on CE marking cycles.
Underlying assumptions cover IEC 60601-1-2 Edition 4.1 harmonization timelines and cloud-based platform-as-a-service adoption curves, with deviation risk concentrated in electromagnetic compatibility threshold tightening and AI algorithm validation protocol amendments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Point of Care Blood Testing Devices Market