
 Allergic Rhinitis Treatment Device Market | 2026-2036
Allergic Rhinitis Treatment Device Market Size, Share, and Industry Trends Forecast 2026-2036
Allergic Rhinitis Treatment Device Market Analytics
Connected inhalation and intranasal delivery platforms is reconfiguring how allergic rhinitis treatment devices integrate with patient monitoring ecosystems. GSK Consumer Healthcare leverages its respiratory heritage to dominate over-the-counter nasal spray distribution across North American pharmacies. Bayer AG anchors its position through sustained R&D investment in antihistamine-decongestant combination formulations. Medisana AG competes in European home care channels with digitally enabled nasal irrigation systems.
Allergic rhinitis treatment devices encompass mechanical, pharmaceutical, and electroceutical systems designed to alleviate nasal inflammation, congestion, and associated symptoms through targeted delivery or physical intervention. These products typically operate at flow rates of 5–20 mL/min for irrigation systems and employ particle sizes below 10 microns for optimal nasal deposition. Intranasal sprays and nasal irrigation systems occupy mature margin pools in retail pharmacy, while smart devices and RF therapy segments represent the fastest-expanding categories as reimbursement frameworks adapt to connected health outcomes. Home care end users now drive volume growth, displacing hospital-centric procurement patterns that historically structured this sector.
The U.S. FDA oversees 510(k) clearances for intranasal drug-device combinations, while the EU MDR imposes strengthened clinical evidence requirements on RF therapy and laser treatment modalities. Japan's PMDA evaluates smart device software under revised SaMD guidelines, creating differentiated compliance burdens across major markets. Stakeholders must monitor how FDA digital health guidance and EU MDR post-market surveillance converge to reshape competitive access and product lifecycle economics.
Market Dynamics
Connected health integration is restructuring allergic rhinitis treatment device economics, as software-as-medical-device classifications force manufacturers to revalidate entire product portfolios under evolving FDA and EU MDR frameworks. This regulatory recalibration compresses development timelines while expanding post-market surveillance obligations.
Growth Catalysts
- Aging demographics in Japan and Germany:Diagnostic rates for allergic rhinitis climb among populations over 65, sustaining clinical and consumer spending on maintenance therapies.
- FDA 510(k) pathway modernization:Streamlined clearances for intranasal drug-device combinations accelerate commercialization timelines for combination spray platforms.
- Home care channel expansion:Portable nasal irrigation systems with Bluetooth connectivity capture pharmacy shelf space previously dominated by hospital-procured equipment.
Market Restraints
- Silicone and polymer input volatility:Nasal tip and reservoir manufacturing faces cost pressure from medical-grade elastomer supply tightness.
- EU MDR clinical evidence requirements:RF therapy and laser treatment modalities must generate new clinical data, extending time-to-market by 18-24 months.
- Generic antihistamine substitution:Oral tablet therapies constrain pricing power for premium intranasal delivery devices in pharmacy retail.
Strategic Opportunities
- Pediatric underpenetration in the United States:Child-specific flow rates and gamified adherence tracking remain underserved in home care settings.
- Japan's SaMD guideline evolution:PMDA software evaluation frameworks create first-mover advantages for algorithm-enabled symptom monitoring.
- Telehealth integration:Remote patient monitoring platforms are creating new reimbursement pathways for connected inhalation devices.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing for novel nasal tip materials delays product launches amid laboratory capacity constraints.
- Legacy ERP integration:Device-to-cloud data pipelines require substantial middleware investment for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergic Rhinitis Treatment Device Market |
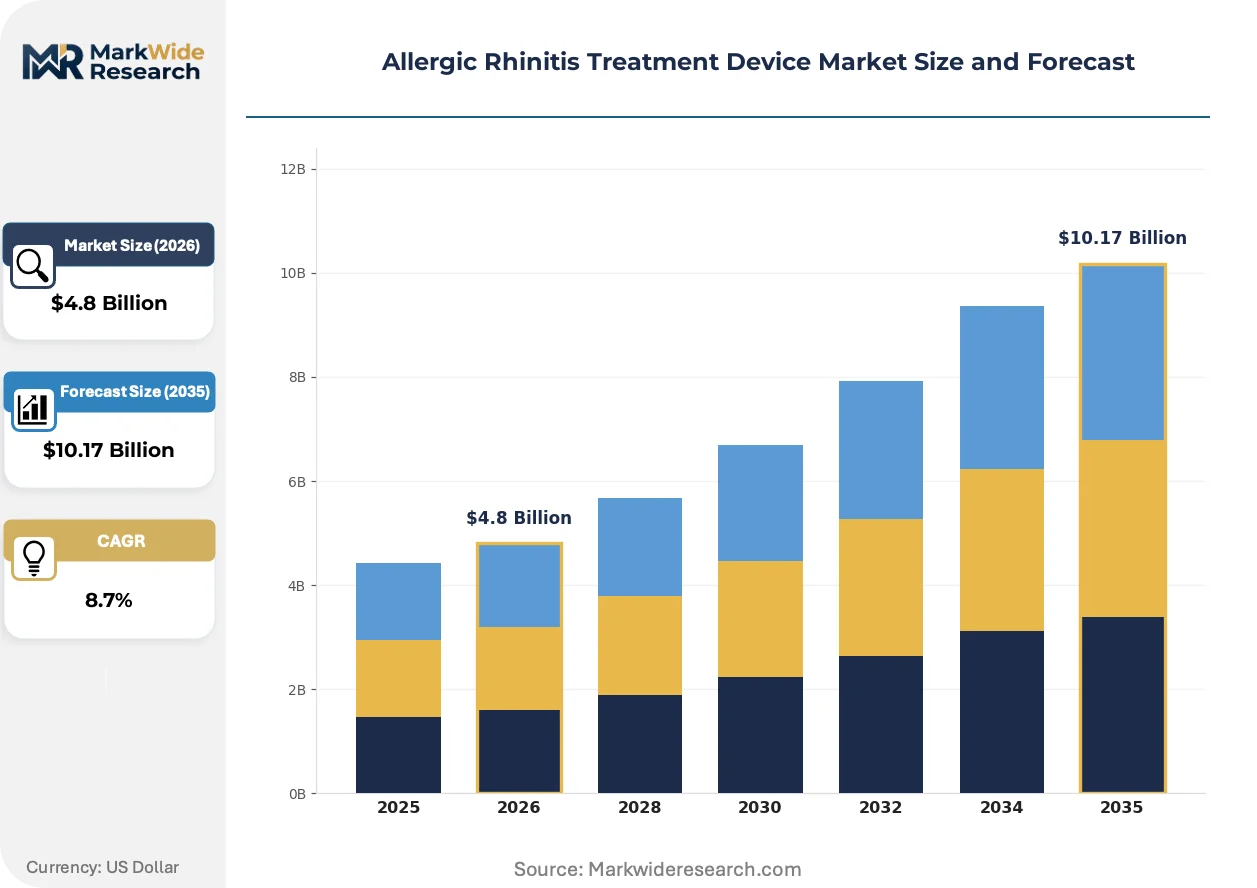
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intranasal Sprays, Oral Antihistamines, Decongestants, Nasal Irrigation Technology: Smart Devices, RF Therapy, Nanotechnology, Laser Treatment End User: Hospitals, Clinics, Home Care, Pharmacies Application: Seasonal Rhinitis, Perennial Rhinitis, Allergic Sinusitis, Preventive Care |
| Companies Covered | GSK Consumer Healthcare, Bayer AG, Medisana AG, Rhinix ApS, Beurer GmbH, NasalGuard, AirPhysio, Theravent, OptiNose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergic Rhinitis Treatment Device Market Evolving Landscape
Digital biomarker extraction and closed-loop delivery systems are redefining therapeutic value in allergic rhinitis management. Manufacturers now compete on algorithmic personalization rather than hardware specifications alone.
Smart inhalers with embedded flow sensors and mobile symptom logging are virtualizing the traditional patient-physician interaction model. Home care users in Germany and Japan adopt these platforms fastest, with pharmacy chains bundling devices with subscription adherence programs. The technology is virtualizing reimbursement structures toward outcomes-based models that reward sustained symptom control.
EU MDR post-market surveillance mandates now require active implantable and energy-emitting nasal devices to submit periodic safety update reports. Manufacturers of RF therapy systems face the steepest compliance burden, with notified bodies demanding real-world evidence registries. German and French device firms are consolidating clinical affairs functions to manage expanded documentation obligations.
Direct-to-consumer subscription models displace traditional pharmacy stocking arrangements for maintenance therapies. United States consumers increasingly expect automated refill scheduling and insurance pre-authorization handled through device-integrated apps. This channel shift concentrates customer acquisition spending on digital platforms rather than wholesale pharmacy relationships.
Allergic Rhinitis Treatment Device Market Segmentation
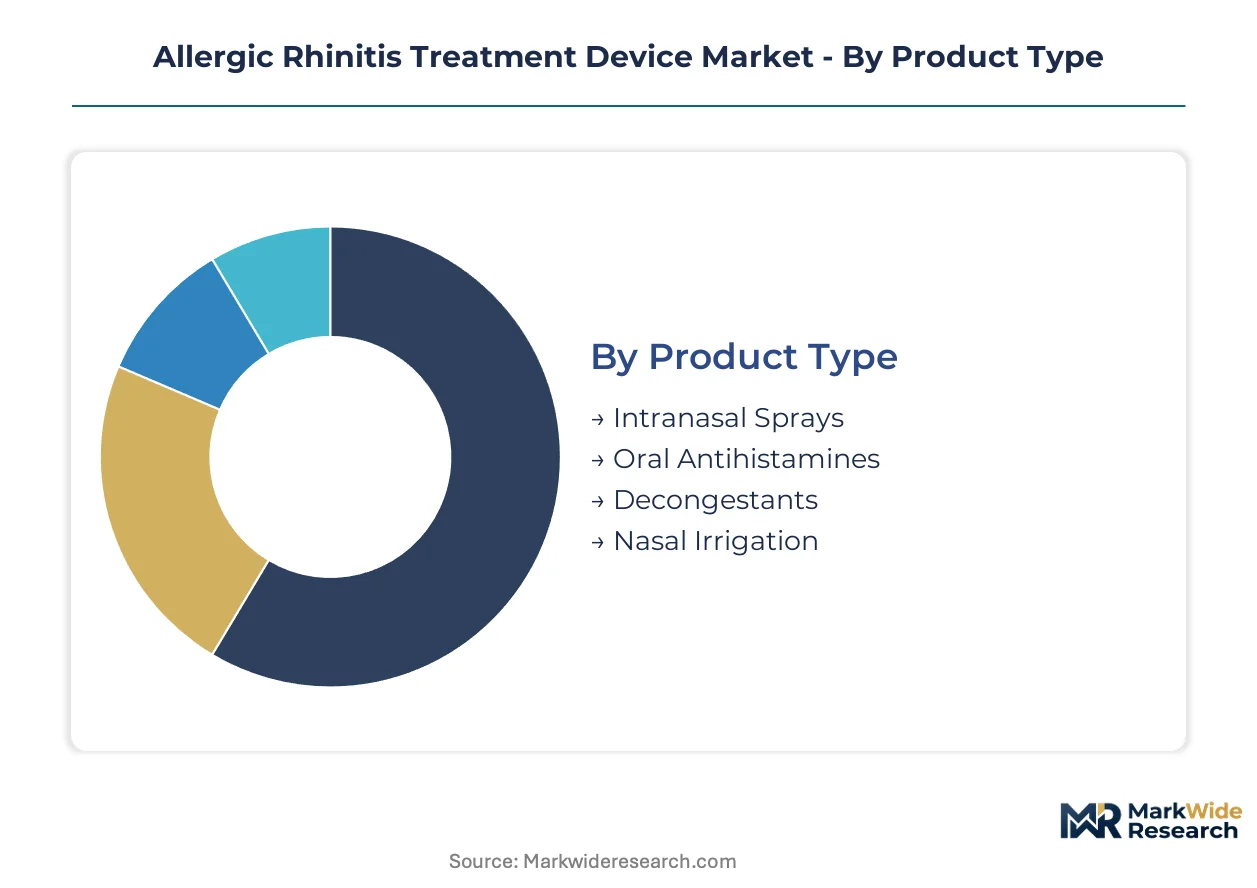
Segmentation in allergic rhinitis treatment devices reveals divergent commercial rhythms across hardware, pharmaceutical, and digital platforms. Product refresh cycles range from months for consumable sprays to years for capital-intensive smart inhalers, demanding portfolio-specific inventory and R&D strategies.
Product Type:
Replacement cycles stretch from single-season disposables to multi-year durable equipment, creating distinct working capital requirements and margin profiles across the portfolio.
- Intranasal Sprays:Metered-dose pump systems deliver corticosteroid or antihistamine formulations with particle sizes optimized for nasal cavity deposition. Pharmacy chains in the United States and Germany stock these as high-velocity consumables with seasonal demand spikes. Formulation patents and pump mechanism reliability determine supplier stickiness in this mature segment.
- Nasal Irrigation:Manual squeeze bottles and electric pulsatile systems flush nasal passages with saline at flow rates between 5–20 mL/min. Home care adoption in Japan and Germany accelerates as consumers seek drug-free maintenance options. Bluetooth-enabled irrigation systems with usage tracking now command premium shelf placement.
- Oral Antihistamines:Tablet and liquid formulations address systemic symptoms but compete intensely with generic substitution.
- Decongestants:Topical and oral vasoconstrictor formulations provide rapid symptom relief with limited duration of action.
Intranasal sprays anchor the volume base while nasal irrigation gains share at the steepest rate.
Technology:
Development timelines and regulatory burdens fragment sharply between software-enabled platforms and hardware-centric energy modalities.
- Smart Devices:Inhalers and irrigation systems embed flow sensors, accelerometers, and Bluetooth modules to capture adherence data and symptom patterns. FDA 510(k) and EU MDR software-as-medical-device classifications extend validation timelines but open reimbursement pathways through remote patient monitoring codes in the United States.
- RF Therapy:Radiofrequency energy devices target nasal turbinate reduction through controlled thermal lesioning. EU MDR post-market surveillance mandates impose 18–24 month clinical evidence generation requirements, compressing addressable margins for European manufacturers.
- Nanotechnology:Particle engineering enhances drug bioavailability and mucosal penetration in next-generation spray formulations.
- Laser Treatment:Low-level and surgical laser systems address refractory cases through photobiomodulation or tissue ablation.
Smart devices capture the steepest expansion trajectory as telehealth integration restructures prescribing economics.
End User:
Procurement authority and reimbursement access create four distinct customer segments with incompatible sales motions.
- Home Care:Direct-to-consumer channels now dominate volume for maintenance therapies, with subscription models displacing pharmacy stocking arrangements. United States consumers expect automated refill scheduling and insurance pre-authorization through device-integrated applications.
- Pharmacies:Retail chains bundle devices with adherence programs and serve as the primary discovery channel for new product introductions in Germany and Japan.
- Hospitals:Capital equipment procurement committees govern RF therapy and laser system acquisitions with extended sales cycles.
- Clinics:Specialist ENT practices prescribe premium irrigation systems and connected inhalers with direct dispensing.
Home care anchors the volume base while pharmacies experience the most rapid channel shift toward digital-physical integration.
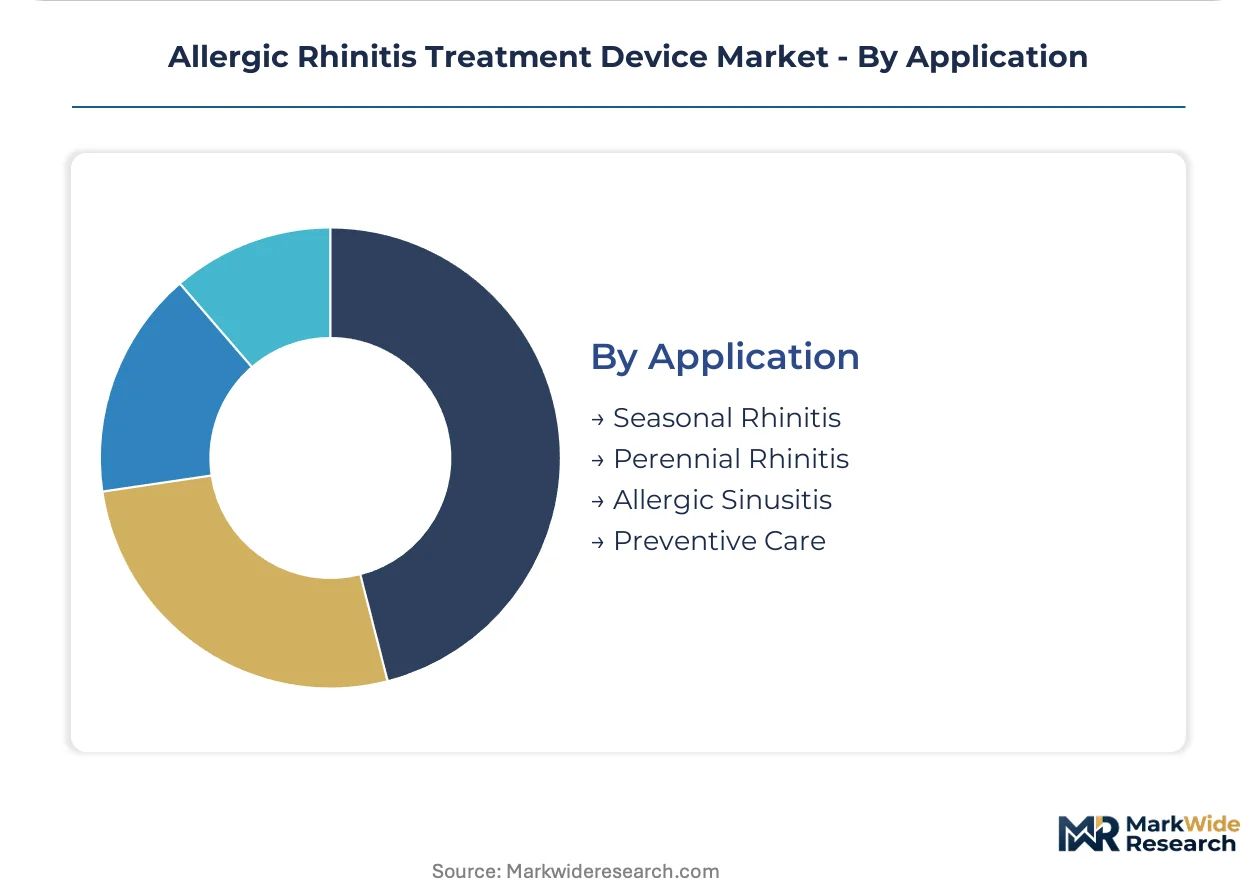
Application:
Treatment intensity and device selection vary with allergen exposure patterns and comorbidity profiles.
- Seasonal Rhinitis:Pollen-triggered symptoms drive concentrated demand spikes in spring and fall, favoring portable, rapid-onset interventions. United States and German consumers stockpile intranasal sprays and disposable irrigation supplies ahead of high-pollen forecasts.
- Perennial Rhinitis:Year-round dust mite, pet dander, and mold sensitization necessitates daily maintenance regimens. Smart devices with adherence tracking demonstrate strongest value proposition in this chronic management context.
- Allergic Sinusitis:Secondary bacterial complications from prolonged inflammation require combined pharmaceutical and mechanical intervention.
- Preventive Care:Pre-season immunotherapy and environmental control devices target high-risk pediatric and geriatric populations.
Seasonal rhinitis anchors the volume base while perennial rhinitis applications climb the fastest as chronic disease management frameworks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care buyers in aging societies drive allergic rhinitis treatment device procurement, with reimbursement access and digital health infrastructure determining regional penetration rates. Diagnostic density and connected device adoption create divergent commercial rhythms across major markets.
United States
FDA 510(k) pathway modernization accelerates intranasal drug-device combination clearances, while Medicare remote patient monitoring codes expand reimbursement for connected inhalation systems. The Boston-Cambridge medical device cluster anchors smart device R&D, with startups partnering with pharmacy chains on direct-to-consumer subscription models.
Germany
EU MDR post-market surveillance mandates impose 18–24 month clinical evidence requirements on RF therapy manufacturers, compressing margins for energy-based modalities. The Munich-Stuttgart corridor concentrates nasal irrigation device production, with Beurer GmbH and Medisana AG competing through digitally enabled home care platforms.
Japan
PMDA software-as-medical-device guidelines create first-mover advantages for algorithm-enabled symptom monitoring, as METI promotes connected health adoption among elderly populations. The Osaka-Kobe manufacturing belt produces precision nasal tip components, with local firms integrating Bluetooth modules into traditional irrigation systems.
United Kingdom
NHS England's MedTech Funding Mandate creates procurement pathways for cost-effective home care devices, while MHRA post-Brexit regulatory divergence complicates EU MDR alignment for exporters. The Cambridge-London health tech corridor attracts venture investment in pediatric-specific flow rate technologies.
China
NMPA medical device classification reforms streamline registration for Class II nasal irrigation systems, though software-enabled platforms face SAMR data security reviews. The Yangtze River Delta concentrates polymer molding capacity for medical-grade elastomer components, with domestic manufacturers scaling portable device production.
Allergic Rhinitis Treatment Device Market Competitive Landscape
Channel-controlling players compete with product-specialist players across pharmacy, home care, and direct-to-consumer routes. The market exhibits tiered consolidation, with OTC pharmaceutical incumbents commanding retail shelf space while digital health entrants capture subscription revenue. Three archetypes dominate: respiratory heritage conglomerates, precision fabrication specialists, and connected health platform builders. Competitive moves center on M&A for digital capabilities and vertical integration into medical-grade polymer supply.
Within the respiratory heritage tier, GSK Consumer Healthcare and Bayer AG exemplify pharmaceutical-device combination strategies, leveraging formulation patents and distribution scale across North American and European pharmacy networks. Medisana AG anchors the European home care specialist position, representing digitally enabled nasal irrigation system development. These three firms illustrate how regulatory compliance depth and channel relationships create defensive moats against generic substitution and software-native entrants.
| Leading Market Players |
|---|
| GSK Consumer Healthcare |
| Bayer AG |
| Medisana AG |
| Rhinix ApS |
| Beurer GmbH |
| NasalGuard |
| AirPhysio |
| Theravent |
| OptiNose |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone supply tightness from the Yangtze River Delta determines both the premium-to-economy spread in nasal irrigation systems and the geographic clustering of component suppliers. Device manufacturers face margin compression when polymer feedstock volatility coincides with EU MDR certification delays, forcing tiered sourcing strategies that separate validated suppliers from spot-market alternatives.
Pricing Analysis
Cost-plus contracts with medical-grade elastomer suppliers index to regional polymer spot markets, creating quarterly price adjustments that squeeze mid-tier device margins. Pricing stratifies across premium connected devices, standard manual systems, and economy disposables based on Bluetooth certification tier and flow-rate precision. Cost compression in the standard tier intensifies because generic antihistamine tablets constrain intranasal spray premiums. Home care consumers show highest price sensitivity, while hospital procurement committees absorb premium markups for RF therapy capital equipment.
Supply Chain Analysis
Extended payment terms from German and Japanese device assemblers to Yangtze River Delta molders have normalized 90-day cycles that strain working capital for precision nasal tip fabricators. Component sourcing draws from China for polymer molding, Germany for sensor modules, and Japan for miniaturized Bluetooth chipsets. Single-source vulnerability concentrates in medical-grade silicone suppliers serving FDA 510(k) submission timelines. Distribution runs through pharmacy chains in the United States and Germany, with direct-to-consumer subscription platforms capturing growing share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where FDA 510(k) clearance history and EU MDR technical documentation create switching costs that protect incumbent positions against software-native entrants.
For Market Incumbents: Insulate formulation patents through sustained FDA submission activity for combination drug-device platforms, while securing backward integration into medical-grade polymer supply to offset Yangtze River Delta tariff exposure. GSK Consumer Healthcare and Bayer AG anchor defensive positions through pharmacy channel control that emerging players cannot replicate without multi-year formulary negotiation. For New Entrants and Emerging Players: Pursue pediatric-specific flow rate configurations in the United States, where gamified adherence tracking remains underserved by existing portfolios. Telehealth-integrated subscription models offer the most penetrable go-to-market angle, bypassing wholesale pharmacy relationships that incumbents dominate. For Investors and Strategic Acquirers: EU MDR post-market surveillance mandates reshape the acquisition landscape toward clinical affairs capabilities and real-world evidence registry infrastructure. Targets with SaMD-validated platforms and existing notified body relationships offer strongest 5-10 year viability. Watch FDA digital health guidance evolution as the signal for reimbursement pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Modernization | Streamlined clearances accelerate intranasal drug-device combination commercialization timelines. |
| CE Marking Pathway Investment | EU MDR compliance separates sustainable players from regulatory casualties in RF therapy. |
| Hospital System Partnership | ENT clinic dispensing agreements secure premium placement for connected inhalation devices. |
| Software Companion Development | PMDA SaMD guidelines reward algorithm-enabled symptom monitoring with first-mover reimbursement. |
| Reimbursement Strategy | Medicare remote patient monitoring codes expand addressable market for Bluetooth-enabled irrigation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads at nasal device manufacturers, biomedical engineers at German and Japanese production facilities, and GPO contracts managers at United States hospital systems; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, PMDA SaMD guidance releases, and CMS reimbursement code updates. Bottom-up triangulation across component supplier interviews and top-down cross-checks against pharmacy distribution data anchored volume estimates.
Forecast inputs span product type segmentation across intranasal sprays, nasal irrigation systems, and smart devices; technology tiers from manual to Bluetooth-enabled to RF therapy; and end-user channels including home care, pharmacy retail, and hospital procurement. CAGRs were derived from adoption curve modeling across the analysis window, with specific weighting applied to aging demographic diagnostic rates in Japan and Germany and telehealth integration velocity in United States reimbursement frameworks.
Macroeconomic conditions sit as an overlay; deviation in medical-grade polymer pricing, FDA digital health guidance timing, or EU MDR notified body capacity would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway efficiency and channel shift velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market