
 Immunology-Oncology ELISA Kits Market | 2026-2036
Immunology-Oncology ELISA Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Immunology-Oncology ELISA Kits Market Foresight
Market Context
Pharmaceutical companies is rebalancing toward cancer immunotherapy pipelines, pulling demand for validated cytokine and immune checkpoint ELISA panels. Thermo Fisher Scientific leverages its clinical diagnostics infrastructure to serve high-throughput screening workflows. Bio-Techne Corporation anchors its position through specialized immunoassay content for T-cell activation markers. Abcam competes with recombinant antibody-backed ELISA kits that reduce lot-to-lot variability in longitudinal studies.
Technical Definition and Segment Structure
Immunology-oncology ELISA kits are quantitative immunoassay systems that detect soluble immune mediators—cytokines, chemokines, checkpoint proteins—using antibody-coated microplates with colorimetric or chemiluminescent readouts, typically achieving picogram-per-milliliter sensitivity for serum or plasma matrices. Their primary commercial purpose is to standardize immune monitoring across preclinical toxicology, clinical trial patient stratification, and companion diagnostic development. Research kits occupy the largest volume tier due to broad academic procurement, while diagnostic kits command premium pricing where FDA or EMA clearance creates regulatory moats. Sandwich assay technology leads in adoption for cytokine quantification, though competitive formats retain share for small-molecule metabolite detection in tumor microenvironment studies.
Regulatory Frame and Outlook
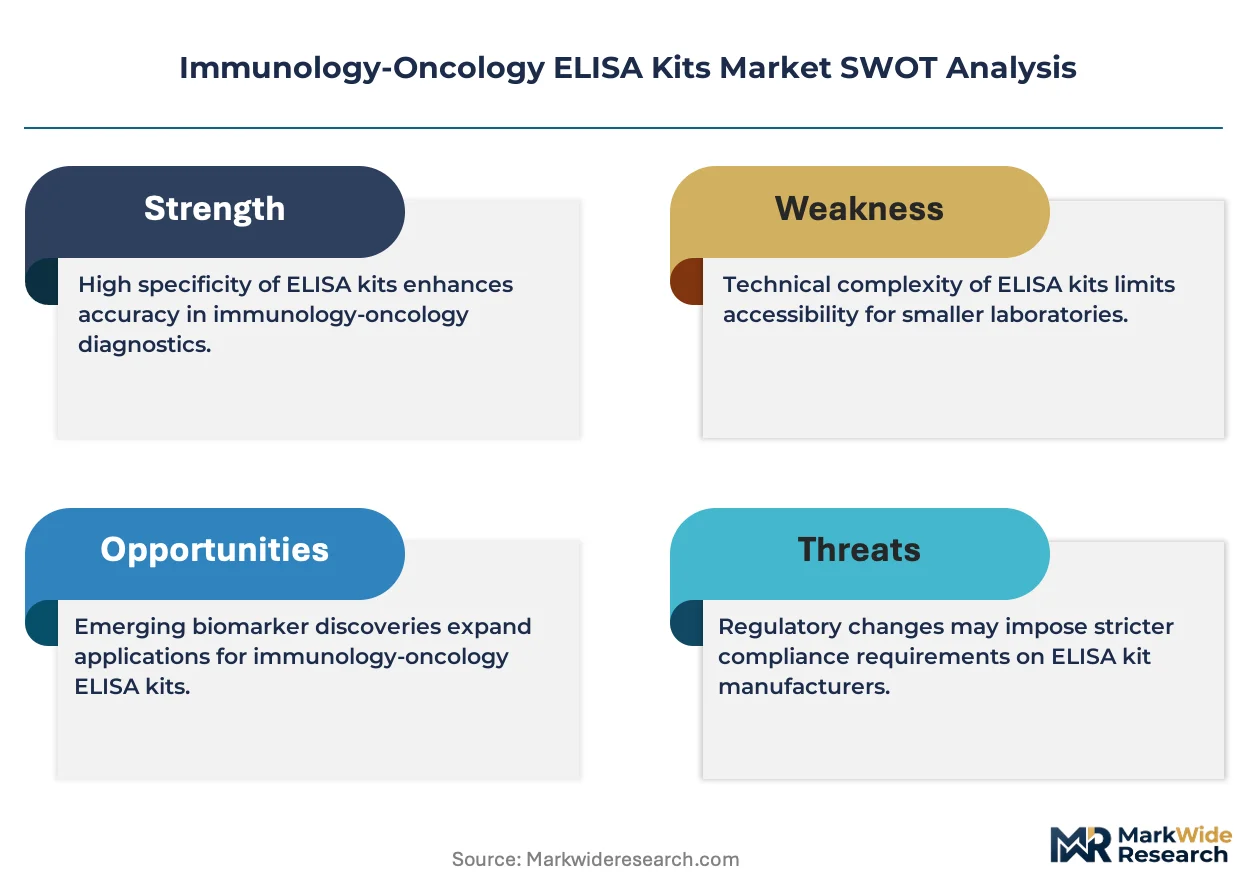
FDA 21 CFR Part 820 quality system regulations and EMA In Vitro Diagnostic Regulation standards shape manufacturing documentation and clinical claim substantiation for kit suppliers seeking commercial diagnostic status. ISO 13485 certification has become a baseline procurement filter for hospital and contract research organization buyers evaluating vendor qualification. Stakeholders must monitor evolving FDA guidance on analytical validation for multiplexed cytokine panels, as these determinations will reshape competitive access to the clinical laboratory channel.
Market Dynamics
Pharmaceutical companies are rebalancing R&D budgets toward immuno-oncology pipelines, creating concentrated demand pull for validated cytokine quantification platforms that can standardize biomarker readouts across multi-site clinical trials.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Tightening validation standards for companion diagnostic assays are pushing manufacturers toward higher specificity platforms, expanding the addressable market for premium-grade kits.
- T-cell activation marker panels:Biotech clusters in Boston and Basel are standardizing immune monitoring protocols, driving recurring procurement of research-grade ELISA systems for longitudinal toxicology studies.
- Chemiluminescent readout technology:Picogram-per-milliliter sensitivity requirements in serum matrices are accelerating replacement of colorimetric legacy systems in contract research organizations.
Market Restraints
- Recombinant antibody input costs:Lot-to-lot consistency requirements for diagnostic-grade kits create dependency on specialized mammalian cell culture suppliers with limited geographic diversification.
- FDA 21 CFR Part 820 compliance burden:Quality system documentation requirements for commercial diagnostic status create multi-year certification timelines that filter out mid-tier manufacturers.
- Multiplex bead-based assay substitution:Luminex and Meso Scale Discovery platforms are capturing cytokine panel workflows that previously defaulted to ELISA, compressing volume in high-throughput screening segments.
Strategic Opportunities
- India biotech corridor expansion:Hyderabad and Bengaluru clusters lack validated local ELISA kit manufacturing, creating white space for ISO 13485-certified suppliers to establish regional production.
- CAR-T therapy monitoring protocols:Cytokine release syndrome quantification requirements are emerging as a distinct application segment with specialized IL-6 and IFN-gamma panel demand.
- WHO prequalification pathway:Low-and-middle-income country oncology programs are creating procurement channels for cost-optimized research-grade kits with simplified regulatory documentation.
Industry Challenges
- Multiplexed cytokine panel validation:FDA guidance on analytical validation for simultaneous biomarker detection remains unsettled, creating compliance uncertainty for kit developers targeting clinical laboratory channels.
- Antibody cross-reactivity mitigation:Serum matrix interference in cancer patient samples requires extensive pre-analytical optimization, extending development timelines and inflating R&D headcount requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunology-Oncology ELISA Kits Market |
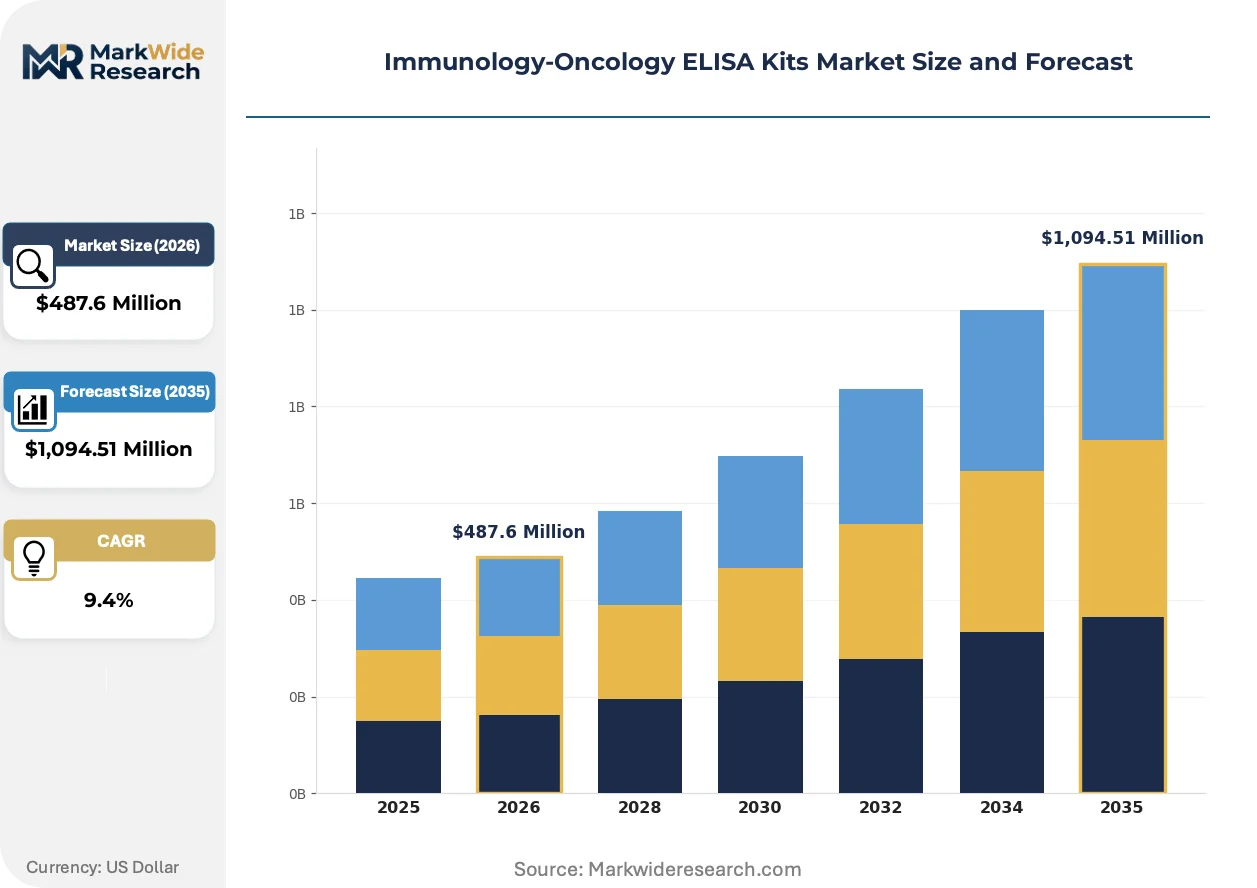
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Research Kits, Diagnostic Kits, Preclinical Kits, Assay Development Kits Application: Biomarker Discovery, Cancer Immunotherapy, Clinical Trials, Drug Development End User: Research Institutes, Pharmaceutical Companies, Clinical Laboratories, Hospitals Technology: Homogeneous Assays, Sandwich Assays, Competitive Assays, Microplate Assays |
| Companies Covered | Thermo Fisher Scientific, Bio-Techne Corporation, Abcam, BioLegend, Bio-Rad Laboratories, Merck KGaA, BD Biosciences, PerkinElmer, Enzo Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunology-Oncology ELISA Kits Market Shifts & Advancements
Automated liquid handling integration and single-plex sensitivity benchmarks are compressing the performance gap between ELISA and higher-plex alternatives, reshaping platform selection criteria in translational research settings.
Magnetic bead-based capture systems are overtaking traditional polystyrene microplate formats in high-throughput screening workflows. Large pharma toxicology groups in New Jersey and Basel are standardizing on these platforms for 384-well cytokine profiling. The shift is compressing assay time from overnight incubation to two-hour protocols, enabling same-day decision-making in dose-escalation studies.
FDA draft guidance on analytical validation for multiplexed cytokine panels is forcing kit manufacturers to submit expanded bridging studies for biomarker combinations. The industrial consequence is a bifurcation between research-use-only and investigational-use-only product lines with distinct documentation packages. Contract research organizations in Maryland and North Carolina are responding by dual-sourcing from suppliers with pre-submitted master files.
Consolidated procurement through integrated supply agreements is replacing spot purchasing in academic medical centers. Group purchasing organizations are negotiating multi-year ELISA kit contracts that bundle reagent supply with instrument service coverage. This pattern is most visible in German university hospital networks, where centralized biobank operations are standardizing on single-vendor cytokine panel portfolios to reduce lot-to-lot validation overhead.
Immunology-Oncology ELISA Kits Market Segmentation
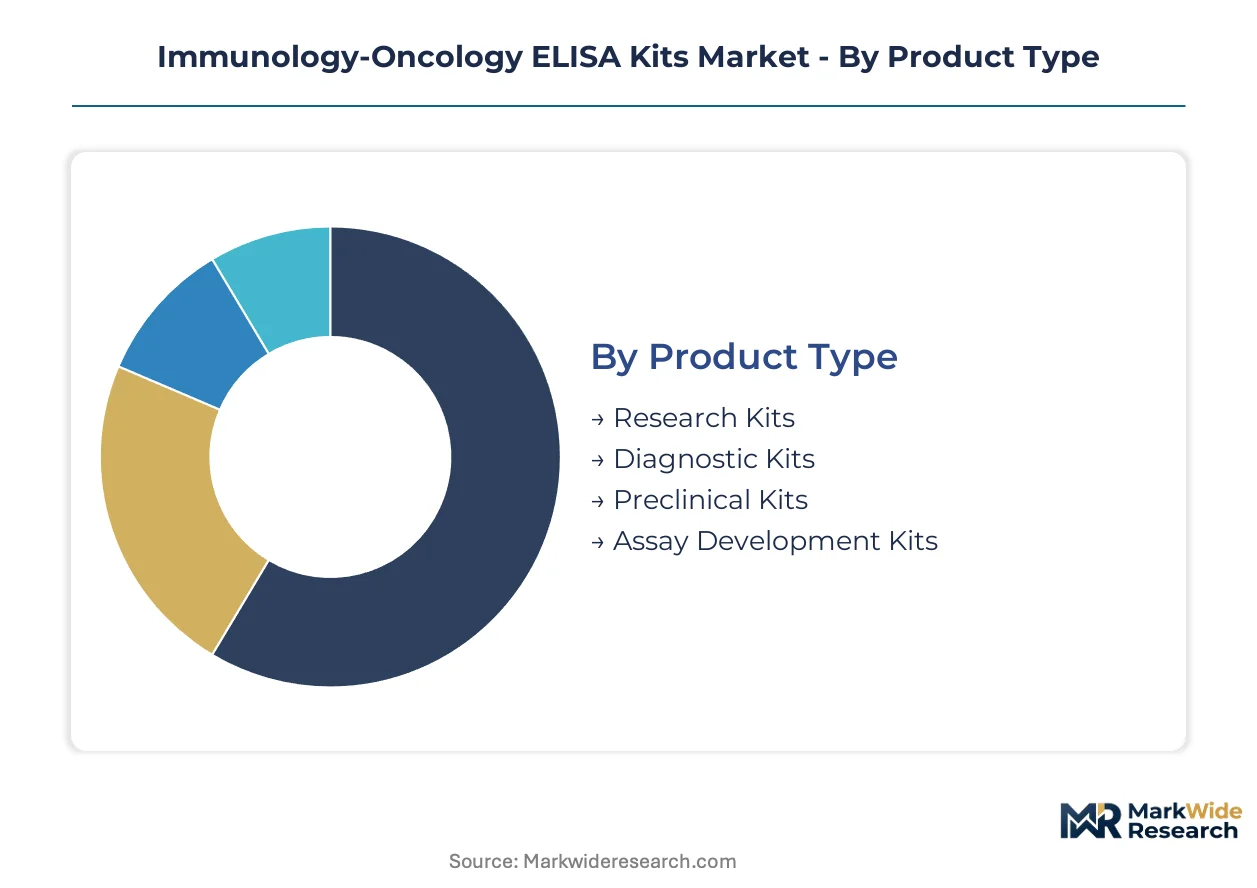
Product customization demands in immuno-oncology research create divergent procurement patterns across kit categories. Standardized diagnostic-grade systems compete with modular research platforms for capital allocation in biopharma R&D budgets.
Product Type:
Standardization depth varies sharply across this category, from off-the-shelf research consumables to FDA-validated diagnostic systems requiring multi-year certification cycles.
- Research Kits:Modular cytokine panels with unvalidated antibody pairs serve academic toxicology studies and exploratory biomarker work. Demand concentrates in Boston and Basel biotech clusters where principal investigators prioritize lot-to-lot consistency over regulatory documentation.
- Diagnostic Kits:FDA 21 CFR Part 820-compliant systems with pre-submitted master files command premium positioning for companion diagnostic development. Pharmaceutical companies in New Jersey and Maryland dual-source these for clinical trial patient stratification workflows.
- Preclinical Kits:GLP-grade reagents support IND-enabling toxicology studies with extended stability claims.
- Assay Development Kits:Antibody pair sets enable in-house ELISA construction for specialized immune checkpoint targets.
Leading the category by volume: Research Kits. Growing fastest: Diagnostic Kits.
Application:
Cost tier separation distinguishes exploratory research from regulated clinical development, with pricing multiples expanding across the value chain.
- Cancer Immunotherapy:CAR-T and checkpoint inhibitor developers require IL-6, IFN-gamma, and TNF-alpha quantification for cytokine release syndrome monitoring. Contract research organizations in North Carolina standardize these panels across multi-site Phase I/II trials.
- Clinical Trials:Longitudinal immune monitoring demands lot-matched reagent sets with 24-month stability documentation. EMA In Vitro Diagnostic Regulation compliance costs filter mid-tier suppliers from European sponsor procurement lists.
- Biomarker Discovery:Exploratory cytokine profiling in academic settings tolerates higher assay variability for cost efficiency.
- Drug Development:Preclinical to clinical bridging studies require technology transfer protocols between research and diagnostic kit formats.
Volume concentration: Cancer Immunotherapy. Steepest expansion trajectory: Clinical Trials.
End User:
Customer type determines procurement authority structure, from principal investigator discretionary spending to centralized hospital supply agreements.
- Pharmaceutical Companies:Integrated supply agreements bundle ELISA reagents with automated liquid handling service contracts. German university hospital networks consolidate cytokine panel procurement through group purchasing organizations to reduce validation overhead.
- Research Institutes:Grant-funded investigators prioritize per-assay cost over total cost of ownership, sustaining spot-purchase channels.
- Clinical Laboratories:CAP-accredited facilities require FDA-cleared kits with defined reference ranges for patient reportable results.
- Hospitals:Oncology departments in academic medical centers source research-use-only kits for correlative science studies alongside diagnostic systems.
Procurement volume leader: Pharmaceutical Companies. Fastest adoption growth: Clinical Laboratories.
Technology:
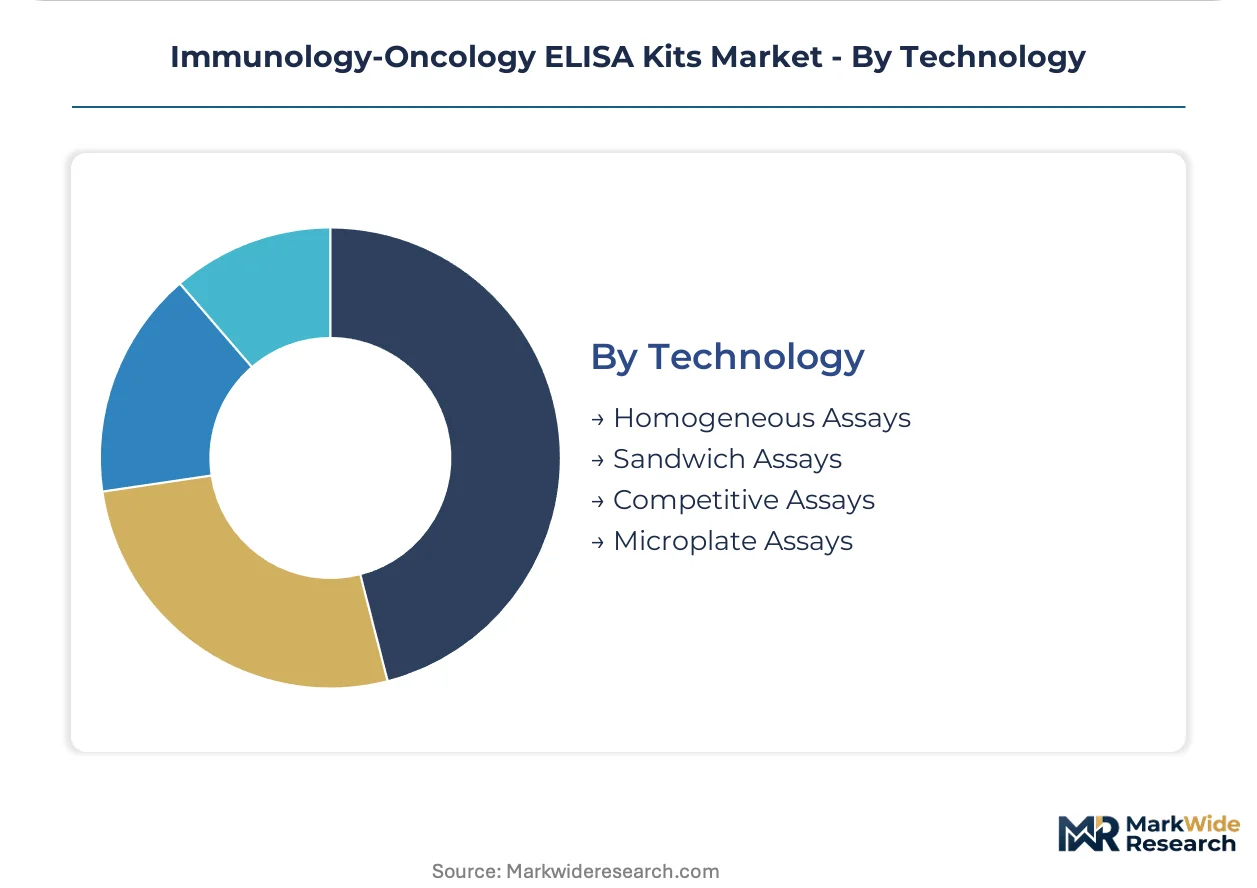
Maturity gradients separate legacy colorimetric formats from chemiluminescent systems displacing them in high-sensitivity applications.
- Sandwich Assays:Dual-antibody capture systems achieve picogram-per-milliliter sensitivity for serum cytokine quantification. Magnetic bead-based variants in 384-well formats compress incubation from overnight to two-hour protocols in Basel toxicology workflows.
- Competitive Assays:Single-antibody formats retain share for small-molecule metabolite detection in tumor microenvironment studies where molecular weight precludes sandwich construction.
- Homogeneous Assays:Mix-and-read systems eliminate wash steps for point-of-care immune monitoring applications.
- Microplate Assays:Traditional polystyrene formats persist in budget-constrained academic settings despite throughput limitations.
Technology volume leader: Sandwich Assays. Gaining share fastest: Homogeneous Assays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established biomanufacturing corridors while consumption spreads across clinical trial hubs and academic medical centers. The United States and Germany anchor supply capacity for high-specificity diagnostic-grade kits. Demand fragmentation across emerging biotech clusters is reshaping distribution network requirements.
United States
FDA 21 CFR Part 820 compliance costs filter mid-tier suppliers from commercial diagnostic procurement channels. The agency's draft guidance on multiplexed cytokine panel validation is forcing expanded bridging study submissions. New Jersey and Maryland contract research organizations dual-source diagnostic kits for multi-site Phase I/II trials.
Germany
EMA In Vitro Diagnostic Regulation standards shape manufacturing documentation requirements for kit suppliers seeking European commercial status. ISO 13485 certification has become a baseline procurement filter for hospital buyers. University hospital networks in Bavaria and North Rhine-Westphalia consolidate cytokine panel procurement through group purchasing organizations.
India
CDSCO regulatory pathways for in vitro diagnostics are tightening documentation requirements for imported research-grade kits. The country's biotech corridor expansion in Hyderabad and Bengaluru lacks validated local ELISA kit manufacturing. WHO prequalification pathways are opening procurement channels for cost-optimized research-grade systems.
China
NMPA medical device registration requirements for companion diagnostic assays are extending approval timelines for foreign kit manufacturers. Domestic biopharma R&D growth in Shanghai and Suzhou is pulling demand for immune monitoring platforms. Local CDMOs are developing in-house ELISA capabilities to reduce import dependency.
United Kingdom
MHRA post-Brexit regulatory autonomy is creating divergence from EMA validation standards for diagnostic kit suppliers. Academic medical centers in London and Cambridge sustain spot-purchase channels for research-use-only cytokine panels. Consolidated procurement through integrated supply agreements is replacing fragmented purchasing in NHS trusts.
Immunology-Oncology ELISA Kits Market Competitive Landscape
Top-tier vendors anchor the diagnostic-grade segment, while mid-tier research kit suppliers compete on per-assay cost and lot-to-lot consistency. The vendor base stratifies across three tiers: diversified life science conglomerates with clinical diagnostics infrastructure, specialized immunoassay content developers, and regional reagent fabricators serving budget-constrained academic labs. Two strategic archetypes dominate competitive positioning: platform-integrated suppliers bundling reagents with automated liquid handling service contracts, and antibody-specialized developers emphasizing recombinant-backed consistency claims. M&A activity targets complementary antibody pair portfolios, while capacity expansion concentrates in ISO 13485-certified manufacturing corridors.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies platform-integrated positioning through clinical diagnostics infrastructure. Bio-Techne Corporation occupies the specialized immunoassay content tier, anchoring its presence through T-cell activation marker expertise. Abcam represents the recombinant antibody-backed consistency archetype, competing on reduced lot-to-lot variability positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Techne Corporation |
| Abcam |
| BioLegend |
| Bio-Rad Laboratories |
| Merck KGaA |
| BD Biosciences |
| PerkinElmer |
| Enzo Life Sciences |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up antibody specialists in the United States and Germany have consolidated mammalian cell culture supply contracts, tightening input cost discipline while enabling premium pricing for ISO 13485-certified diagnostic-grade kits. This ownership concentration feeds directly into three-tier pricing structure across premium, standard, and economy levels, with certification status and volume scale as the primary differentiation drivers.
Pricing Analysis
Margin tightening in economy-tier research kits reflects recombinant antibody input cost escalation and spot-purchase channel fragmentation. Cost-down pressure on diagnostic-grade systems accelerates because pharmaceutical procurement teams negotiate multi-year integrated supply agreements bundling reagent supply with automated liquid handling service coverage. Price differentiation hinges on FDA 21 CFR Part 820 compliance documentation and lot-to-lot consistency validation. Academic research institutes exhibit highest price sensitivity; contract research organizations in New Jersey and Maryland demonstrate lowest sensitivity due to pass-through billing structures.
Supply Chain Analysis
Direct-to-pharma channels handle high-volume diagnostic kit demand from multi-site clinical trial sponsors, while distributor networks serve fragmented academic procurement. Manufacturing concentrates in the United States, Germany, and China, with CDSCO regulatory pathways in India tightening import documentation for research-grade systems. Critical inputs include recombinant antibody pairs, magnetic bead substrates, and chemiluminescent detection reagents. Single-source vulnerability in specialized mammalian cell culture suppliers creates supply chain risk, particularly for diagnostic-grade lot-to-lot consistency requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around ISO 13485 certification barriers that filter mid-tier manufacturers from clinical diagnostic procurement channels. EMA In Vitro Diagnostic Regulation compliance costs and FDA 21 CFR Part 820 quality system documentation requirements are forcing weaker players toward research-use-only positioning or exit.
For Market Incumbents: Extend platform-integrated positioning by bundling cytokine panel reagents with automated liquid handling service contracts in German university hospital networks. Deepen backward integration into recombinant antibody production to reduce dependency on specialized mammalian cell culture suppliers with limited geographic diversification. Multiplex bead-based assay substitution from Luminex and Meso Scale Discovery platforms threatens high-throughput screening volume; defend by accelerating magnetic bead-based capture system adoption in 384-well formats. For New Entrants and Emerging Players: WHO prequalification pathways in India open a window for cost-optimized research-grade kits with simplified regulatory documentation targeting low-and-middle-income country oncology programs. Hyderabad and Bengaluru biotech clusters lack validated local ELISA kit manufacturing, creating white space for ISO 13485-certified regional production. CAR-T therapy monitoring protocols represent the most penetrable application segment, with specialized IL-6 and IFN-gamma panel demand emerging from cytokine release syndrome quantification requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor antibody-specialized developers with recombinant-backed consistency claims in the United States and United Kingdom. Long-term viability over a multi-year horizon rests on regulatory moat durability and companion diagnostic assay validation capabilities. The signal to monitor is FDA final guidance on multiplexed cytokine panel analytical validation, which will reshape competitive access to clinical laboratory channels.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Creates regulatory moat for diagnostic-grade kit procurement in EMA-compliant European markets. |
| Magnetic Bead Platform Migration | Compresses assay protocols from overnight to two-hour workflows in Basel toxicology operations. |
| Recombinant Antibody Backward Integration | Reduces lot-to-lot variability exposure from specialized mammalian cell culture suppliers. |
| CAR-T Monitoring Panel Development | Captures emerging cytokine release syndrome quantification demand from cell therapy developers. |
| Integrated Supply Agreement Negotiation | Locks multi-year reagent contracts with automated liquid handling service bundling in German hospital networks. |
Research Methodology
Independent corroboration across regulatory filings, hospital procurement databases, and contract research organization sourcing records underwrites the qualitative findings. Primary interviews with regulatory affairs leads at kit manufacturers, clinical laboratory directors, pharmaceutical biomarker scientists, and group purchasing organization contracts managers combined with secondary validation from FDA 510(k) clearances, EMA In Vitro Diagnostic Regulation guidance documents, and ISO 13485 certification registries. Bottom-up kit shipment estimates and top-down biopharma R&D spending allocation analysis provide triangulation.
Rate-of-change decomposition across product type, application, end user, and technology dimensions structures the analytical framework. CAGRs derive from segment-level volume and value build-ups across the projection horizon, with kit format migration from colorimetric to chemiluminescent readouts and magnetic bead platform adoption as key forecast inputs. Segmentation modeling incorporates research versus diagnostic kit certification tier, cancer immunotherapy versus clinical trial application focus, and sandwich versus competitive assay technology splits.
The model assumes a particular technology adoption path; alternative pathways for multiplex bead-based assay platforms would alter the outlook. Forecasts reflect base-case assumptions regarding EMA In Vitro Diagnostic Regulation implementation timing and FDA multiplexed cytokine panel guidance finalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Thrombus Precursor Protein Market