
 Diagnostic Stopper Market | 2026-2036
Diagnostic Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Stopper Market Outlook
European polymer compounding capacity is rebalancing after feedstock disruptions, tightening silicone precursor availability for medical-grade closure manufacturers. West Pharmaceutical Services leverages backward integration into elastomer formulation to secure compound consistency for high-purity diagnostic stoppers. Dätwyler Holding anchors its position through Swiss-controlled cleanroom extrusion lines that service European IVD kit makers. AptarGroup competes on multi-material platform expertise, spanning rubber, silicone, and thermoplastic closure architectures.
A diagnostic stopper is a sealed closure device engineered to maintain sample integrity, prevent contamination, and enable pierceable access for automated analytical instruments; specifications include defined septum thickness, durometer hardness between 30 and 60 Shore A, and extractables profiles validated to USP Class VI standards. The product type landscape shows silicone stoppers capturing premium positioning in nucleic acid preservation due to low off-gassing, while rubber formulations dominate high-volume blood collection tubes where cost efficiency outweighs specialized performance. Application segmentation reveals laboratories and blood collection as the structural volume leaders, with sample preservation representing the fastest margin expansion as biobanking protocols proliferate.
FDA 21 CFR Part 820 quality system requirements govern U.S. diagnostic stopper manufacturing, while EU MDR and REACH frameworks constrain plasticizer and additive selections for European market access. ISO 13485 certification has become a baseline threshold for supplier qualification by multinational diagnostic device OEMs. Stakeholders must monitor evolving biocompatibility testing protocols and raw material qualification timelines to avoid supply disruptions.
Market Dynamics
Automated sample handling systems in diagnostic laboratories are compressing tolerance specifications for closure septum thickness and durometer consistency, forcing manufacturers to recalibrate extrusion and molding parameters around instrument-piercing reliability rather than manual handling durability.
Growth Catalysts
- EU MDR material traceability mandates:The tightened framework for patient-contact components is accelerating qualification of medical-grade silicone compounders who can document polymer chain provenance from feedstock to finished stopper.
- Biobanking protocol proliferation:Long-term nucleic acid preservation requirements in biorepositories are pulling demand toward low-off-gassing closure formulations that maintain sample integrity across decades of cryogenic storage.
- German diagnostic center automation:Expansion of automated sample handling systems in Mannheim, Munich, and Hamburg facilities is standardizing procurement around pre-validated, instrument-compatible closure geometries.
Market Restraints
- Silicone precursor supply concentration:European polymer compounding capacity rebalancing after feedstock disruptions has tightened availability of medical-grade silicone monomers, concentrating supply leverage with a narrow base of specialty chemical producers.
- Durometer precision limits:Current elastomer formulation science cannot reliably achieve sub-3 Shore A variation in high-volume production runs, capping automated instrument compatibility for blood collection tube applications.
- REACH plasticizer constraints:The framework's evolving restricted substance list is eliminating phthalate-based plasticizer options for rubber formulations, forcing reformulation cycles that extend qualification timelines by 12-18 months.
Strategic Opportunities
- Indian IVD kit manufacturing expansion:The country's PLI scheme for medical device production is attracting diagnostic OEMs to Hyderabad and Bengaluru, creating demand for localized stopper supply with reduced import duty exposure.
- Thermoplastic elastomer convergence:Multi-material platform expertise spanning rubber, silicone, and TPE architectures enables suppliers to capture specification shifts as instrument manufacturers seek weldable, radio-frequency-sealable closure alternatives.
- Pre-assembled collection kit standardization:Hospital consolidation in the United States is consolidating procurement authority, favoring suppliers who can deliver validated, ready-to-sterilize closure-tube assemblies rather than discrete components.
Industry Challenges
- ISO 13485 certification backlog:Multinational diagnostic device OEMs have elevated this certification to a baseline supplier qualification threshold, but notified body capacity constraints are extending audit wait times and delaying market entry.
- Extractables validation complexity:USP Class VI testing protocols now require extended leachable studies across multiple solvent systems, demanding capital investment in analytical chemistry infrastructure that mid-tier compounders struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Stopper Market |
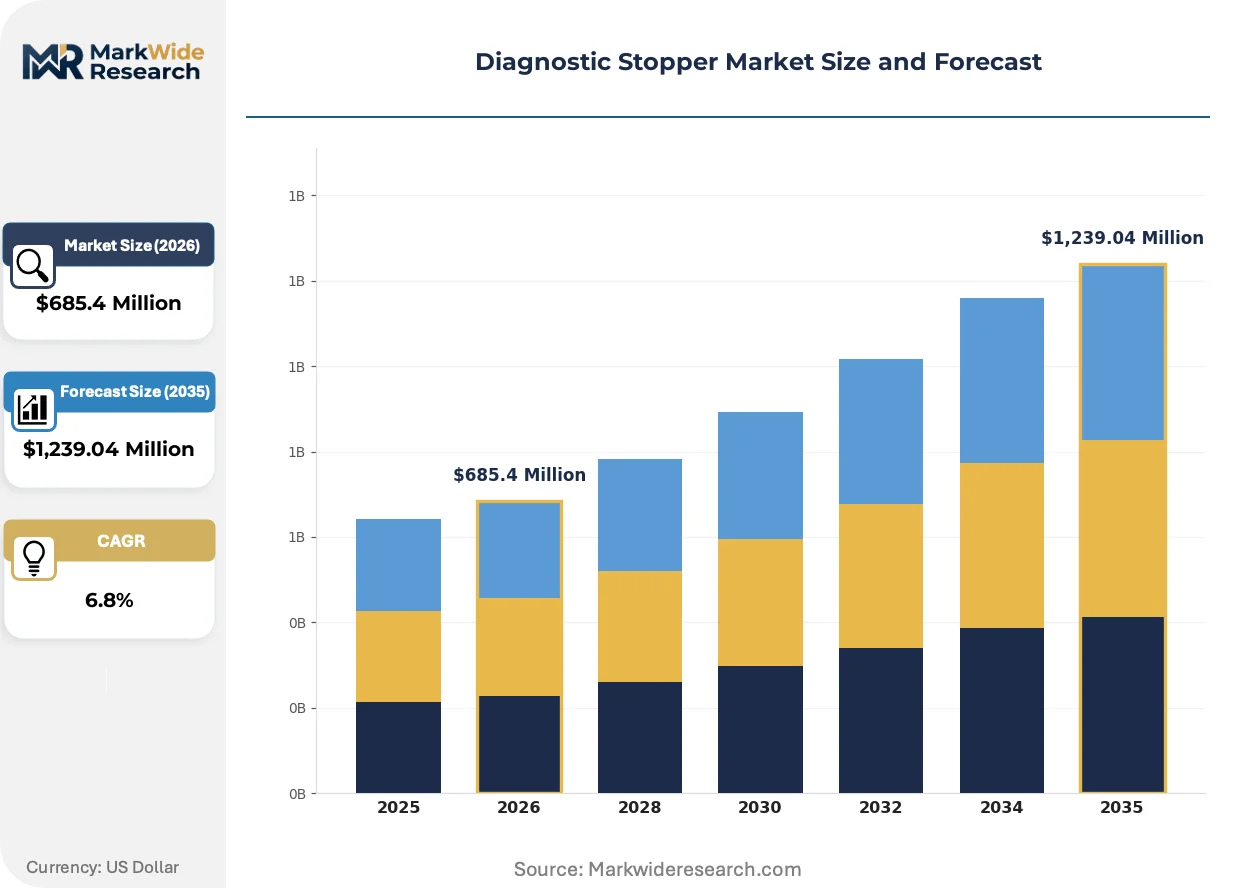
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Rubber, Silicone, Glass Application: Laboratories, Blood Collection, Sample Preservation, Medical Testing End User: Hospitals, Diagnostic Centers, Research Institutions, Pharmaceutical Companies Form: Vials, Tubes, Bottles, Containers |
| Companies Covered | West Pharmaceutical Services, AptarGroup, Dätwyler Holding, Becton Dickinson, Terumo Corporation, Schott AG, DWK Life Sciences, Gerresheimer AG, APG Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Stopper Market Strategic Shifts
Closure engineering is pivoting from passive containment toward active instrument interface design, with septum architecture now co-developed alongside automated liquid handler needle geometries rather than specified in isolation.
Co-extruded multi-layer septum technology is converging with laser-drilled access port geometries to enable precise, debris-free piercing for high-throughput analyzers. Large reference laboratories in the United States and Germany are specifying these configurations in automated workflow tenders. The convergence is compressing demand for traditional molded rubber stoppers in premium diagnostic applications while expanding addressable value per unit in instrument-compatible segments.
FDA 21 CFR Part 820 quality system requirements are tightening documentation standards for process validation and corrective action traceability. Manufacturers must now maintain device history records that link each stopper lot to specific elastomer batch, curing parameters, and inspection station outputs. Blood collection tube producers serving the US market are responding by consolidating supplier bases toward vendors with established FDA inspection histories and dedicated US-based quality management representatives.
Diagnostic OEM procurement teams are unbundling component sourcing from finished device assembly, creating direct purchasing relationships with specialized closure manufacturers that bypass traditional distribution intermediaries. This pattern concentrates in the United States where hospital system consolidation has centralized procurement authority under value-analysis committees. European diagnostic kit makers are following this model more gradually, with Swiss and German IVD producers leading the shift toward direct supplier engagement for critical patient-contact components.
Diagnostic Stopper Market Segmentation
Diagnostic stopper procurement diverges sharply between high-volume blood collection applications and precision biobanking requirements. Specification tolerances for automated instrument compatibility now override traditional material cost considerations in vendor selection.
Product Type:
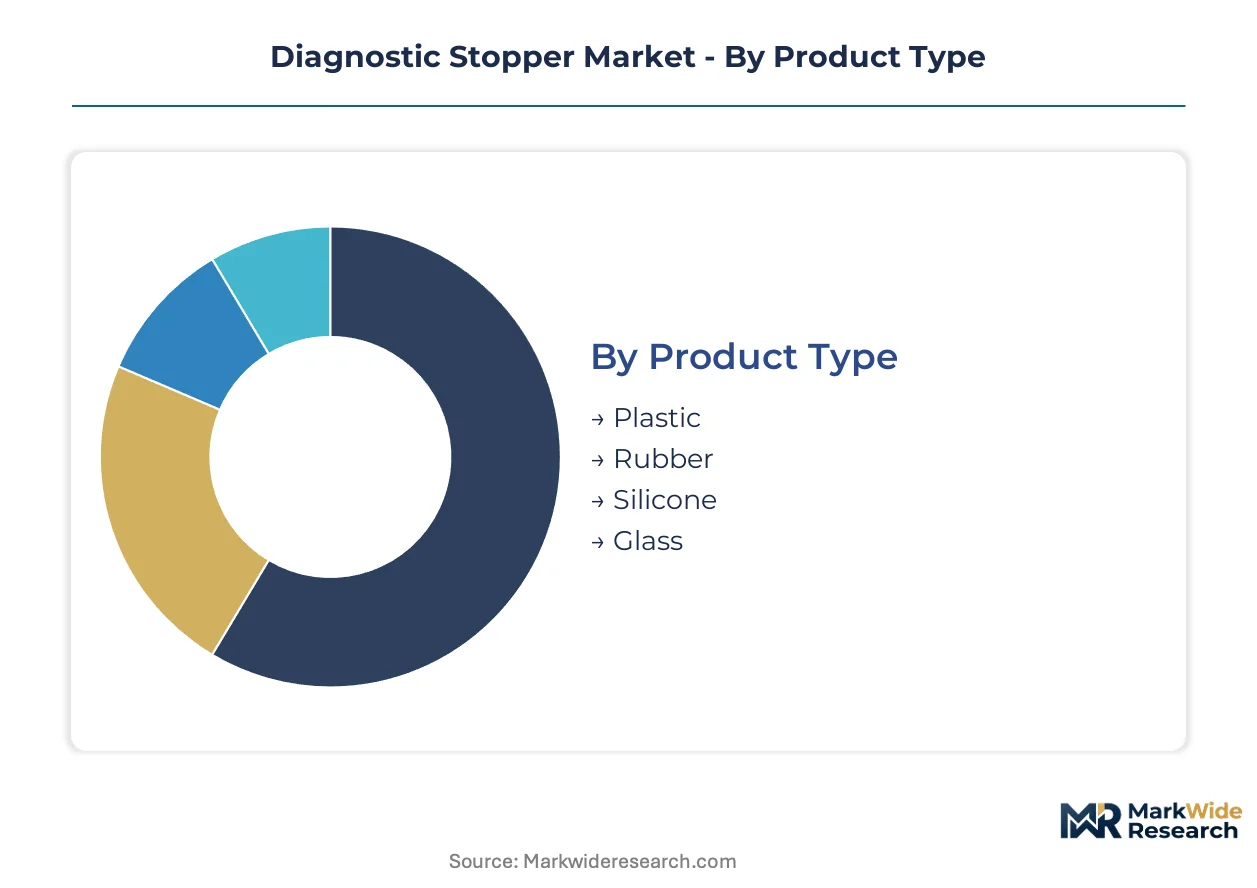
Volume leadership concentrates in rubber formulations, while silicone commands premium positioning for nucleic acid preservation protocols.
- Rubber:Butyl and bromobutyl compounds dominate blood collection tube manufacturing due to established extractables profiles and pierceability. German diagnostic centers specify rubber stoppers for high-throughput screening programs where unit economics outweigh specialized performance requirements.
- Silicone:Medical-grade platinum-cured formulations exhibit minimal off-gassing across cryogenic temperature ranges, making them essential for long-term biobanking. Demand concentrates in Swiss and German IVD kit makers serving EU MDR-compliant nucleic acid preservation workflows.
- Plastic:Thermoplastic elastomer alternatives enable radio-frequency welding and laser-drilled access ports for automated liquid handlers.
- Glass:Borosilicate stopper assemblies serve specialized chromatography and reference standard applications requiring inert gas containment.
Mature deployment sits with rubber stoppers in blood collection infrastructure. Newer deployment is concentrated in silicone formulations for biobanking and automated instrument interfaces.
Application:
Laboratory automation is compressing tolerance specifications across all application segments, with sample preservation emerging as the margin expansion frontier.
- Laboratories:Reference laboratories in the United States specify instrument-validated closure geometries for high-throughput analyzers, requiring sub-3 Shore A durometer consistency for reliable needle piercing across 24-hour operating cycles.
- Sample Preservation:Biorepository protocols demand low-off-gassing closures validated for decades of cryogenic storage, pulling specification authority toward specialized compounders with documented polymer chain provenance.
- Blood Collection:High-volume vacuum tube manufacturing prioritizes cost efficiency and supply security over specialized performance characteristics.
- Medical Testing:Point-of-care diagnostic devices require pierceable closures compatible with capillary action sample transfer mechanisms.
Specification maturity clusters in blood collection workflows. The steepest expansion trajectory belongs to sample preservation as biobanking protocols proliferate across research institutions.
End User:
Procurement centralization under value-analysis committees is reshaping supplier relationships across hospital and diagnostic center segments.
- Diagnostic Centers:Automated sample handling expansion in Mannheim, Munich, and Hamburg facilities standardizes procurement around pre-validated, instrument-compatible closure geometries with documented FDA inspection histories.
- Hospitals:Consolidated health systems in the United States bypass distribution intermediaries for direct purchasing relationships with specialized closure manufacturers capable of delivering ready-to-sterilize assemblies.
- Research Institutions:Academic biobanks prioritize documented extractables profiles and long-term material stability for irreplaceable specimen collections.
- Pharmaceutical Companies:Clinical trial material management requires closure traceability linking each lot to specific elastomer batch and curing parameters under FDA 21 CFR Part 820.
Established supply relationships dominate hospital procurement. Direct supplier engagement is expanding fastest among diagnostic centers responding to automation requirements.
Form:
Tube geometry standardization enables automated handling compatibility, while vial formats serve specialized preservation applications.
- Tubes:Vacuum blood collection tubes represent the highest volume form factor, with 13mm and 16mm diameters standardized across automated analyzer platforms.
- Vials:Cryogenic storage vials require closure systems validated for vapor-phase liquid nitrogen exposure without seal degradation.
- Bottles:Large-format diagnostic reagent containers specify threaded closures with pierceable septa for automated dispensing systems.
- Containers:Multi-well plate and microtube formats demand precision-molded closures compatible with robotic gripper mechanisms.
Volume concentration remains in tube formats for blood collection. Specification innovation is migrating toward vial and microtube geometries for biobanking and high-density storage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone precursor production concentrates in Germany's Ruhr industrial corridor and Switzerland's Basel chemical cluster, anchoring European supply security for high-purity diagnostic closures.
United States
Hospital consolidation under value-analysis committees compresses supplier bases toward vendors with established FDA inspection histories. FDA 21 CFR Part 820 documentation requirements link each stopper lot to specific elastomer batches and curing parameters. Reference laboratories in Boston and San Diego specify instrument-validated closure geometries for high-throughput analyzers.
Germany
Diagnostic centers in Mannheim, Munich, and Hamburg expand automated sample handling systems requiring pre-validated closure geometries. EU MDR material traceability mandates accelerate qualification of compounders documenting polymer chain provenance. The country's national pharmaceutical regulator enforces tightened biocompatibility testing protocols for patient-contact components.
Switzerland
Swissmedic oversight of medical device components elevates cleanroom manufacturing standards for IVD kit closures. Swiss-controlled cleanroom extrusion lines service European biobanking protocols demanding low-off-gassing formulations. Basel's chemical cluster anchors medical-grade silicone compounding capacity for nucleic acid preservation workflows.
India
The PLI scheme for medical device production attracts diagnostic OEMs to Hyderabad and Bengaluru, creating localized stopper demand. CDSCO import regulations favor domestic manufacturing for government hospital procurement. Karnataka's medical device parks concentrate molding and assembly operations for pre-assembled collection kits.
China
NMPA medical device registration requirements extend qualification timelines for imported closure components. The country's national standards body governs extractables testing protocols for blood collection tube assemblies. Yangtze River Delta chemical parks expand silicone monomer capacity serving domestic IVD manufacturers.
Diagnostic Stopper Market Competitive Environment
Global majors compete with regional champions across material science capabilities and regulatory compliance infrastructure. The vendor base separates into three tiers: integrated pharmaceutical packaging conglomerates with captive elastomer formulation, specialized closure manufacturers with multi-material platform expertise, and regional fabricators serving localized kit assembly. Competitive positioning hinges on backward integration into medical-grade silicone compounding, FDA-established quality system documentation, and direct procurement relationships with consolidated hospital systems.
Within the integrated tier, West Pharmaceutical Services exemplifies upstream control over elastomer formulation for high-purity applications. AptarGroup occupies a position spanning rubber, silicone, and thermoplastic closure architectures. Dätwyler Holding represents Swiss-controlled cleanroom manufacturing serving EU MDR-compliant diagnostic workflows.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| AptarGroup |
| Dätwyler Holding |
| Becton Dickinson |
| Terumo Corporation |
| Schott AG |
| DWK Life Sciences |
| Gerresheimer AG |
| APG Pharma |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone compounding expertise concentrates in Germany's Ruhr corridor and Switzerland's Basel cluster, with labor-cost differentials between these precision-manufacturing regions and emerging Asian hubs driving three-tier pricing spreads across premium, standard, and economy closure tiers.
Pricing Analysis
Warranty-backed extractables validation separates premium-tier silicone stoppers from unbundled rubber alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and FDA inspection history as primary differentiation drivers. Cost compression in economy-tier blood collection tubes intensifies as hospital consolidation squeezes component budgets. Reference laboratories exhibit lowest price sensitivity, prioritizing instrument compatibility over unit economics.
Supply Chain Analysis
Workforce availability for cleanroom elastomer processing limits expansion in Swiss and German manufacturing zones. Raw material sourcing draws from medical-grade silicone monomer production in Germany, bromobutyl rubber feedstock from Belgium, and platinum catalyst supply from South Africa. Single-source vulnerability concentrates in European polymer compounding capacity rebalancing after feedstock disruptions. Distribution runs through direct procurement relationships with consolidated hospital systems and diagnostic OEMs, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic stopper market sits in a technology-transition phase as thermoplastic elastomer architectures displace legacy rubber formulations for radio-frequency-sealable automated instrument interfaces.
For Market Incumbents: Cement backward integration into medical-grade silicone compounding to secure supply leverage against specialty chemical producer concentration. Expand cleanroom extrusion capacity in Switzerland to capture EU MDR-compliant nucleic acid preservation demand. Defend against thermoplastic elastomer substitution by co-developing septum architectures with automated liquid handler manufacturers.
For New Entrants and Emerging Players: Launch via direct supplier relationships with Indian diagnostic OEMs establishing operations under the PLI scheme in Hyderabad and Bengaluru. Target white-space opportunity in localized stopper supply for government hospital procurement under CDSCO domestic preference rules. Prioritize multi-material platform expertise spanning rubber, silicone, and TPE to capture specification shifts.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier compounders possessing ISO 13485 certification and established FDA inspection histories given hospital consolidation centralizing procurement authority. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than scale alone. Monitor notified body capacity constraints as inflection indicator for certification backlog resolution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Formulation | West Pharmaceutical Services secures compound consistency by controlling medical-grade silicone supply from monomer to finished stopper. |
| Multi-Material Platform Development | AptarGroup captures specification shifts toward TPE architectures through expertise spanning rubber, silicone, and thermoplastic closure designs. |
| Cleanroom Manufacturing Expansion | Dätwyler Holding anchors EU MDR-compliant supply through Swiss-controlled extrusion lines serving nucleic acid preservation workflows. |
| Direct Procurement Relationship Building | Specialized closure manufacturers bypass distribution intermediaries to capture consolidated hospital system value-analysis committee decisions. |
| Pre-Assembled Collection Kit Standardization | Suppliers delivering validated ready-to-sterilize assemblies capture procurement authority centralization under US hospital consolidation. |
Study Parameters
Independent corroboration across primary interviews with diagnostic OEM procurement directors, IVD kit manufacturing executives, hospital value-analysis committee members, and medical-grade silicone compounders underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, hospital GPO contract databases, and SEC filings of listed packaging conglomerates. Bottom-up demand modeling triangulates against top-down market sizing across material type, application segment, and end-user category.
Comparable-period anchoring to historical blood collection tube shipment data and automated analyzer installation bases establishes the forecast reference framework. Segmentation modeling spans product type, application, end user, and form factor dimensions throughout the projection horizon. CAGRs derive from elasticity-adjusted demand projections calibrated to instrument penetration rates and biobanking protocol adoption curves. Industry-specific inputs include silicone precursor supply capacity utilization and notified body certification throughput estimates.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic elastomer convergence would alter the outlook. Forecasts reflect assumptions regarding EU MDR implementation timelines, hospital consolidation trajectories, and biobanking infrastructure buildout rates. Material deviation in silicone monomer supply recovery or FDA inspection clearance timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market