
 GCC Breath Analyzer Market | 2026-2036
GCC Breath Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Breath Analyzer Market Intelligence
Leasing arrangements for law enforcement fleets are narrowing the competitive field to vendors with balance-sheet capacity for multi-year contracts. Drägerwerk AG & Co. KGaA leverages its captive service network across Gulf states to sustain recurring calibration revenue. Lifeloc Technologies, Inc. anchors its position through portable fuel-cell specialization suited for desert climate deployment. Intoximeters, Inc. competes on training-program bundling that extends customer retention beyond hardware sales.
A breath analyzer measures volatile organic compounds in exhaled breath through electrochemical or spectroscopic methods, with fuel-cell sensors delivering precision to ±0.005% blood alcohol concentration for evidentiary use. The device serves traffic enforcement, occupational health screening, and clinical metabolic monitoring across institutional settings. Portable devices dominate procurement volumes among police forces seeking roadside mobility, while tabletop configurations capture margin pools in hospital laboratories requiring chain-of-custody documentation. Smart analyzers with Bluetooth connectivity and cloud-based record management represent the fastest-expanding product tier as Saudi and Emirati agencies digitize enforcement workflows. Fuel cell technology leads the technology hierarchy for regulatory compliance, though semiconductor sensors occupy the personal-use tier on cost grounds.
SFDA's medical device classification rules and MOHAP's conformity assessment pathways shape product registration timelines and clinical-market access across Saudi Arabia and the UAE. The UAE's traffic safety federal law and Qatar's workplace health mandates create dual enforcement demand streams that manufacturers must navigate with jurisdiction-specific certification. Stakeholders should monitor harmonization gaps between Gulf national standards and ISO 17025 calibration requirements that could fragment service economics.
Market Dynamics
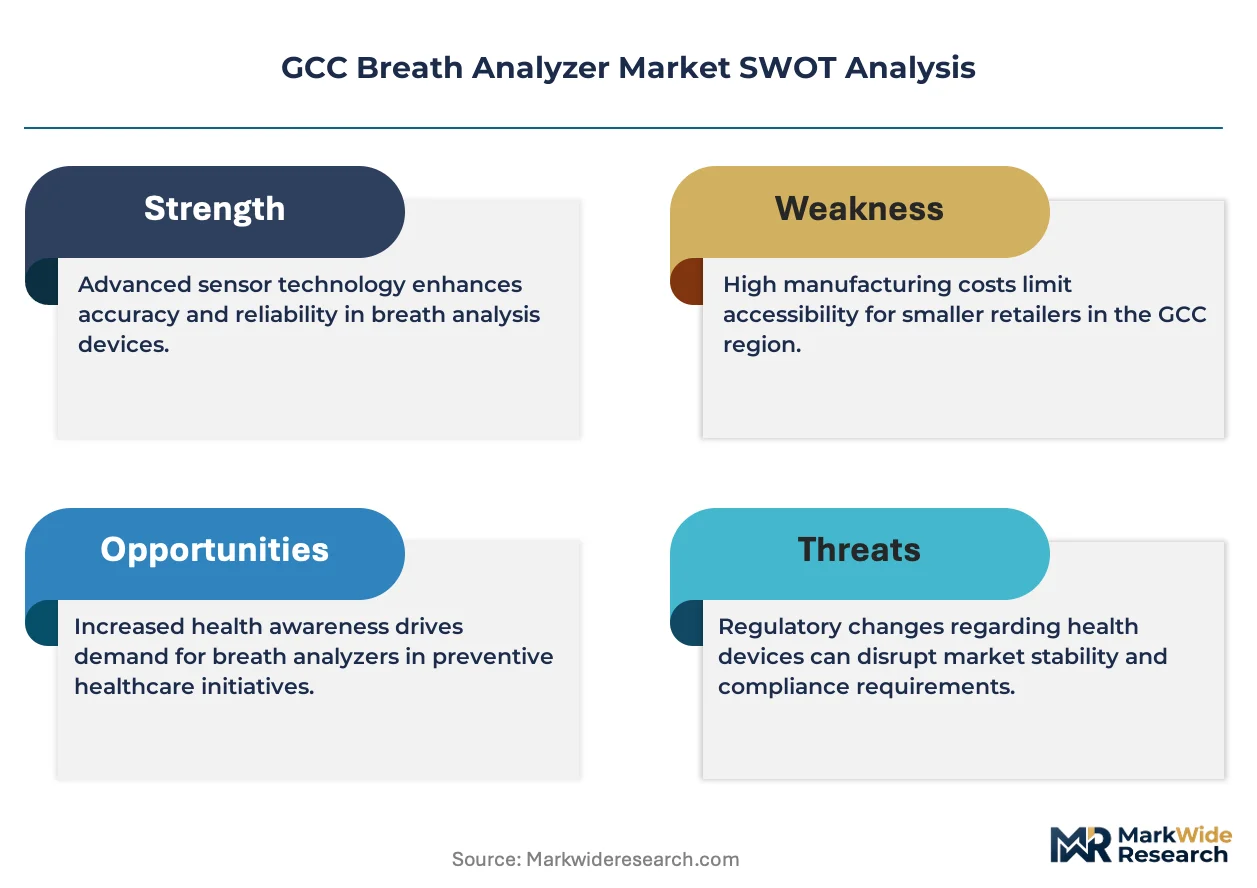
Fuel-cell sensor miniaturization is compressing device footprints while tightening evidentiary standards from SFDA and MOHAP are bifurcating the vendor base between clinical-grade and screening-tier suppliers. Leasing structures for law enforcement fleets now demand multi-year service commitments that favor balance-sheet-heavy incumbents.
Growth Catalysts
- Traffic Safety Modernization:Saudi Arabia's roadside enforcement digitization programs are replacing semiconductor-based units with fuel-cell analyzers for court-admissible readings.
- Workplace Wellness Mandates:UAE federal occupational health directives require alcohol screening across construction, logistics, and oilfield operations, institutionalizing recurring procurement cycles.
- Fuel-Cell Electrochemical Precision:The technology's ±0.005% blood alcohol concentration accuracy meets judicial evidence standards that semiconductor sensors cannot satisfy.
Market Restraints
- Platinum Catalyst Cost Volatility:Fuel-cell electrodes depend on platinum group metals whose price swings compress hardware margins and extend breakeven timelines for less capitalized vendors.
- Calibration Infrastructure Concentration:ISO 17025-accredited service laboratories cluster in Dubai and Riyadh, creating geographic bottlenecks that delay deployment in secondary cities.
- Semiconductor Sensor Substitution:Personal-use and preliminary screening markets accept lower-accuracy semiconductor units at one-fifth the fuel-cell price point, capping premium technology penetration.
Strategic Opportunities
- Qatar Workplace Health Expansion:The country's liquefied natural gas sector and FIFA-legacy infrastructure maintenance protocols are mandating breathalyzer integration into safety management systems.
- Bluetooth-Enabled Cloud Integration:Smart analyzers with real-time data transmission are capturing replacement cycles as Saudi and Emirati agencies digitize chain-of-custody documentation.
- Hospital Metabolic Monitoring:Clinical-grade tabletop configurations for diabetic ketoacidosis and metabolic disorder screening represent an underdeveloped application vertical within GCC healthcare procurement.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Manufacturers must navigate divergent SFDA medical device classification timelines and MOHAP conformity assessment pathways, fragmenting product launch schedules.
- Desert Climate Sensor Drift:Extreme temperature cycling and sand particulate exposure accelerate fuel-cell degradation, demanding enhanced sealed housing designs and shortened recalibration intervals.
- Legacy System Integration Friction:Police force record management systems require custom API development for cloud-connected analyzer data streams, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Breath Analyzer Market |
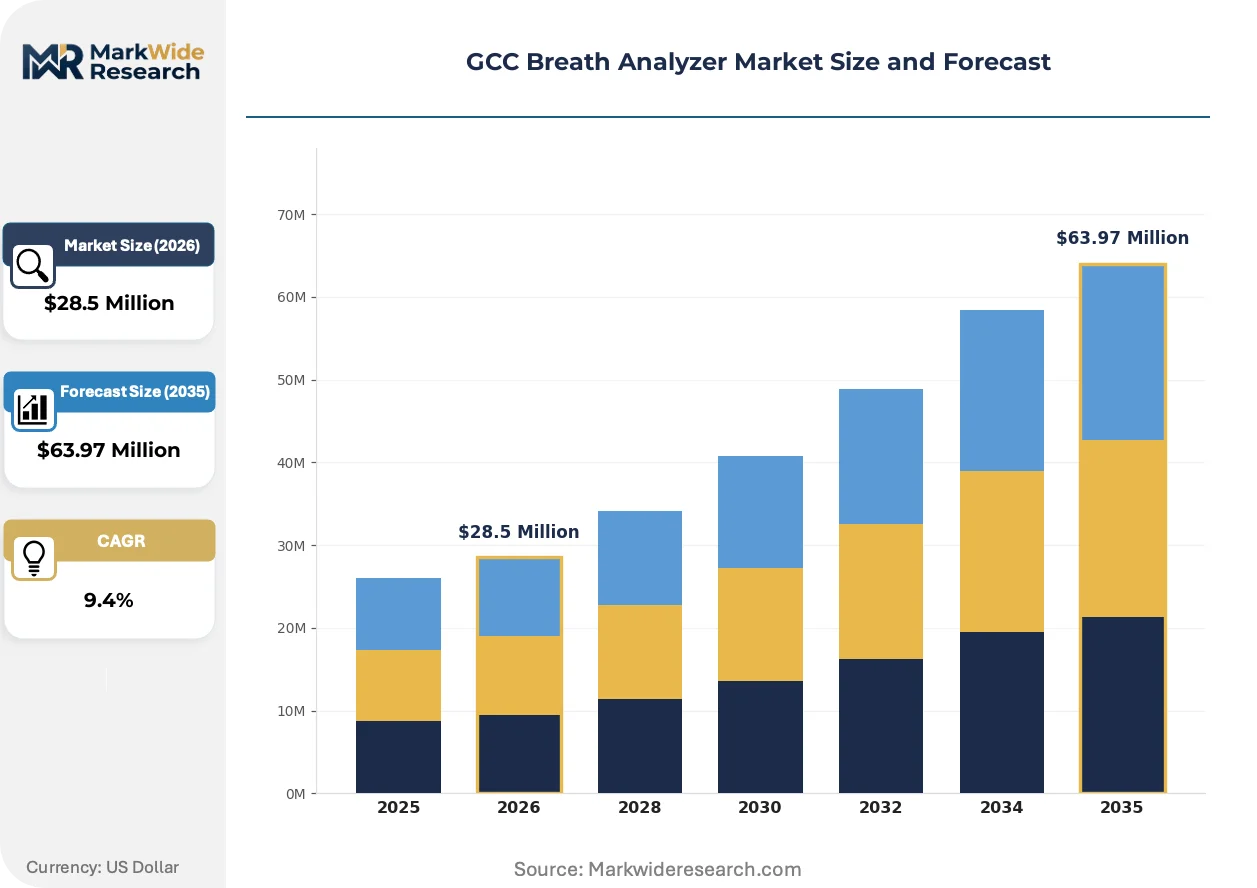
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $63.97 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Hospitals, Clinics, Law Enforcement, Personal Use Product Type: Portable Devices, Tabletop Devices, Non-Invasive Models, Smart Analyzers Technology: Infrared Spectroscopy, Gas Chromatography, Fuel Cell, Semiconductor Sensors Application: Alcohol Detection, Medical Diagnostics, Drug Testing, Research Purposes |
| Companies Covered | Drägerwerk AG & Co. KGaA, Lifeloc Technologies, Inc., Intoximeters, Inc., Alcohol Countermeasure Systems Corporation, AK GlobalTech Corporation, BACtrack, Inc., EnviteC-WISMER GmbH, Lion Laboratories, AlcoPro, Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Breath Analyzer Market Strategic Shifts & Innovations
Device connectivity architectures and sensor platform convergence are restructuring how enforcement agencies and employers capture, transmit, and archive breath alcohol data across the GCC.
Fuel-cell breath analyzers with embedded Bluetooth modules and encrypted cloud upload capabilities are virtualizing the evidence chain from roadside capture to courtroom presentation. Saudi traffic police and UAE occupational health inspectors are deploying these units at replacement rates exceeding legacy standalone devices. The shift is compressing administrative overhead while creating recurring software subscription revenue streams that hardware-centric vendors cannot capture.
SFDA's tightened medical device classification rules and MOHAP's expanded conformity assessment scope are extending registration timelines for clinical-grade analyzers by mandating local biocompatibility testing and Arabic-language labeling compliance. Manufacturers must now maintain separate regulatory dossiers for Saudi and Emirati market entry rather than leveraging mutual recognition. Hospital laboratories and diagnostic chains are absorbing these delays through extended procurement cycles that favor established registrants with dedicated Gulf regulatory affairs staff.
Law enforcement procurement committees are consolidating vendor selection around multi-year fleet leasing arrangements that bundle hardware, calibration, and training into single-source contracts. The model displaces transactional equipment purchases and locks out smaller competitors lacking balance-sheet capacity for extended payment terms. Saudi Arabia's traffic safety modernization programs and Qatar's industrial safety directives exhibit the strongest concentration of this consolidated buying pattern.
GCC Breath Analyzer Market Segmentation
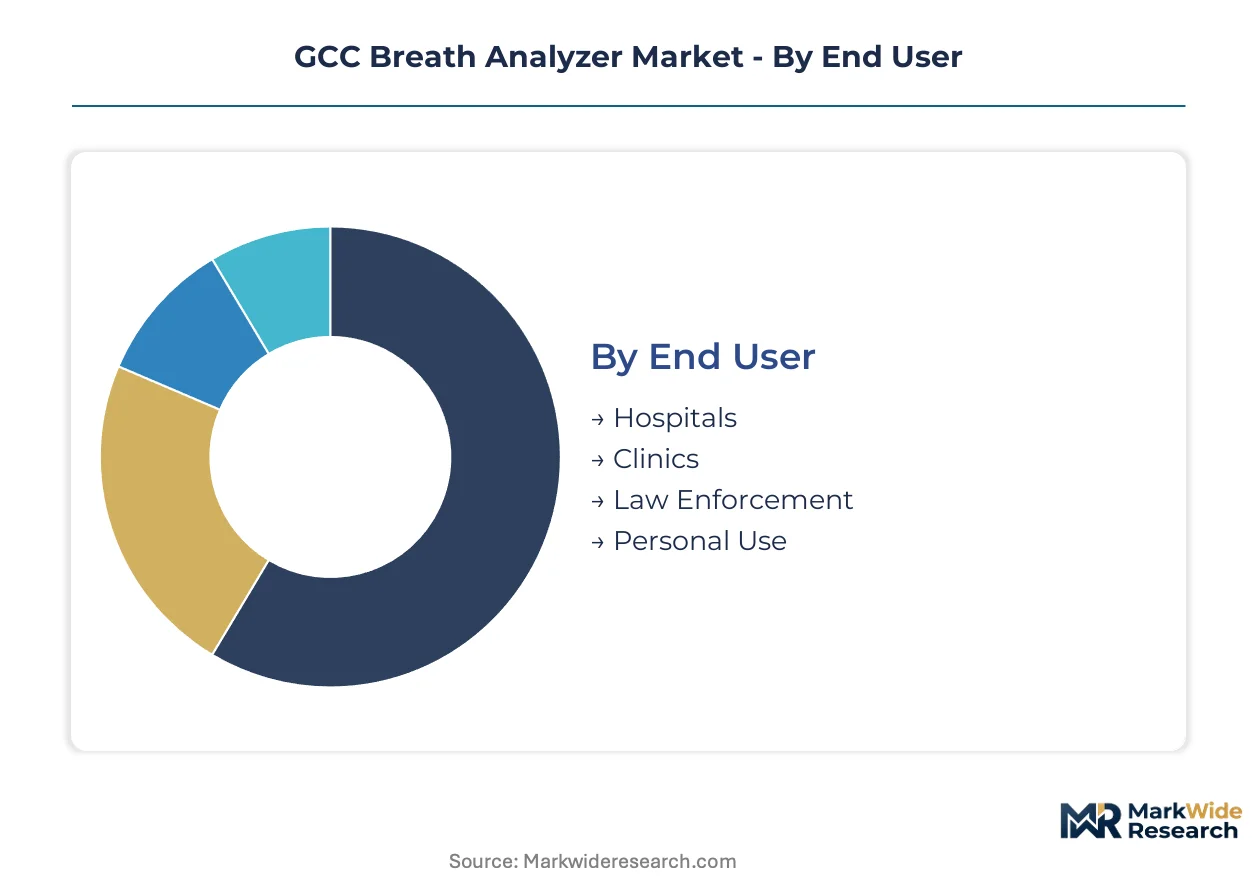
Breath analyzer procurement across Saudi Arabia, the UAE, and Qatar fragments across institutional buyers with divergent accuracy requirements and budget cycles. Understanding segment-level demand concentration reveals where fuel-cell precision commands premium pricing versus where semiconductor cost advantages dominate.
End User:
Mature enforcement infrastructure contrasts with emerging clinical adoption as regulatory pathways diverge across SFDA and MOHAP jurisdictions.
- Law Enforcement:Roadside screening units demand fuel-cell precision to ±0.005% blood alcohol concentration for court-admissible evidence. Saudi traffic police and UAE patrol fleets are consolidating procurement around multi-year leasing bundles that embed calibration services and chain-of-custody training.
- Hospitals:Clinical-grade tabletop configurations serve metabolic monitoring and toxicology laboratories. SFDA's tightened medical device classification rules are extending registration timelines, favoring established vendors with dedicated Gulf regulatory affairs staff.
- Clinics:Occupational health screening in Dubai and Riyadh absorbs portable units for workplace wellness mandates. Procurement concentrates in multi-site diagnostic chains seeking standardized fleet deployments.
- Personal Use:Semiconductor-based devices dominate this price-sensitive tier at roughly one-fifth the fuel-cell cost. Demand remains limited in GCC markets due to cultural consumption patterns and lack of retail distribution infrastructure.
Law Enforcement retains volume leadership; Hospitals hold the steepest expansion curve as metabolic screening protocols broaden.
Product Type:
Cost tier stratification separates premium fuel-cell precision from economy semiconductor screening, with connectivity features now commanding mid-tier pricing power.
- Portable Devices:Handheld fuel-cell units with sealed housings resist desert temperature cycling and sand particulate exposure. Saudi and Emirati police forces prioritize these for roadside mobility and rapid deployment scenarios.
- Smart Analyzers:Bluetooth-enabled units with encrypted cloud upload virtualize evidence chains from capture to courtroom. These are capturing replacement cycles as agencies digitize workflows, creating recurring software subscription revenue streams.
- Tabletop Devices:Laboratory-grade configurations serve hospital toxicology and forensic laboratories requiring chain-of-custody documentation. Installation concentrates in Dubai and Riyadh where ISO 17025-accredited calibration laboratories cluster.
- Non-Invasive Models:Emerging spectroscopic platforms bypass mouthpiece contact for high-throughput screening scenarios. Qatar's industrial safety protocols are piloting these for LNG facility access control.
Portable Devices command the dominant procurement volume; Smart Analyzers are climbing the fastest as enforcement digitization accelerates.
Technology:
Application specificity determines technology selection, with judicial evidence standards enforcing a rigid hierarchy of sensor precision.
- Fuel Cell:Electrochemical oxidation of ethanol at platinum catalyst electrodes delivers the ±0.005% accuracy required for evidentiary use. Platinum group metal cost volatility compresses hardware margins and extends breakeven timelines for capital-constrained vendors.
- Semiconductor Sensors:Metal oxide films detect breath alcohol through conductivity changes at substantially lower cost points. These occupy preliminary screening and personal-use markets where judicial admissibility is not required.
- Infrared Spectroscopy:Non-dispersive infrared absorption enables simultaneous multi-species detection including acetone and carbon monoxide. Research institutions and specialized metabolic clinics in the UAE deploy these for advanced diagnostic protocols.
- Gas Chromatography:Laboratory-grade separation and detection delivers the highest analytical specificity for forensic confirmation. Reference laboratories in Saudi Arabia maintain these as secondary verification for contested evidentiary samples.
Fuel Cell technology anchors institutional procurement volumes; Smart connectivity features are gaining share fastest as agencies modernize data infrastructure.
Application:
Customer type bifurcation separates regulated enforcement mandates from discretionary clinical screening with divergent reimbursement pathways.
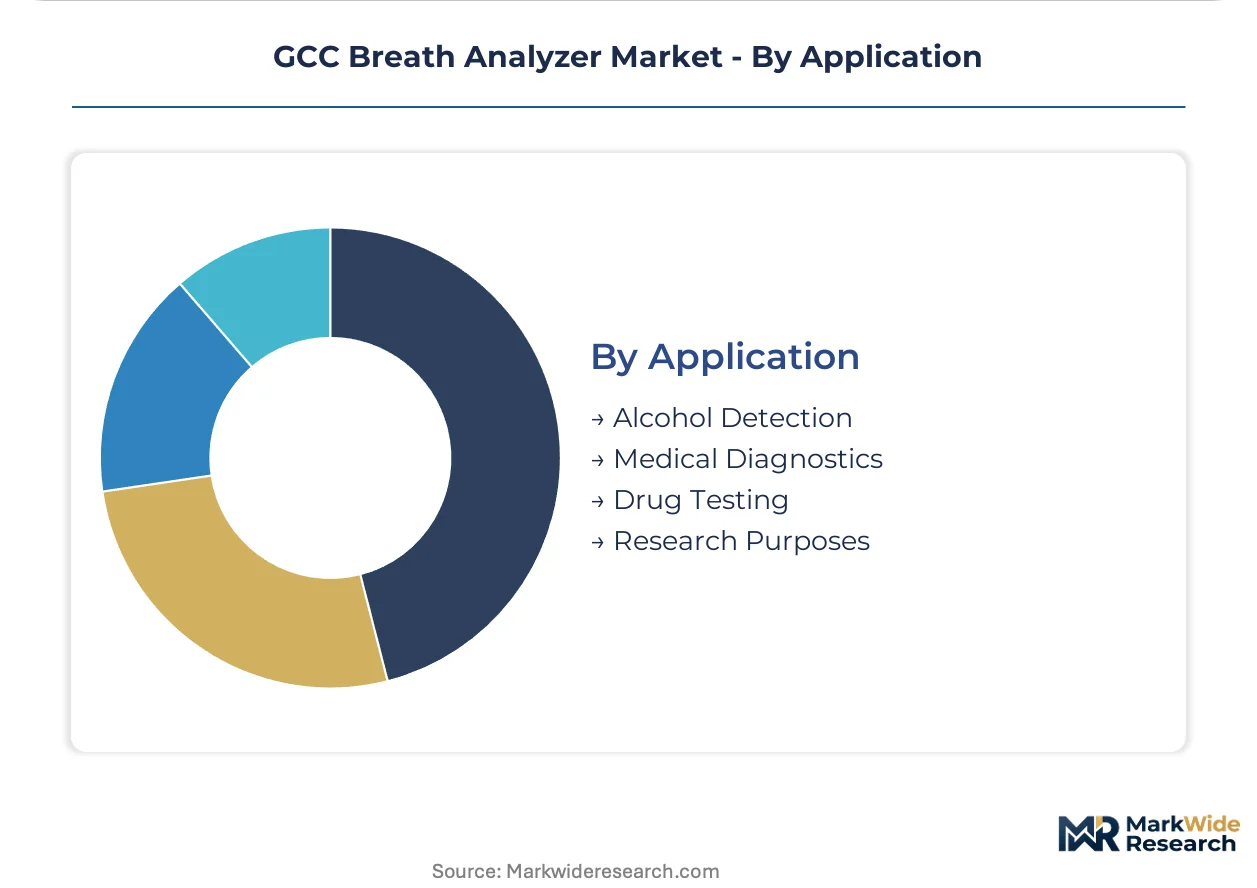
- Alcohol Detection:Traffic safety and workplace sobriety screening dominate procurement volumes across Saudi Arabia's roadside modernization programs and UAE federal occupational health directives. Fuel-cell precision is non-negotiable for judicial proceedings.
- Medical Diagnostics:Diabetic ketoacidosis and metabolic disorder screening represent underdeveloped verticals within GCC healthcare procurement. SFDA pathway complexity has slowed clinical-grade analyzer adoption relative to enforcement markets.
- Drug Testing:Oral fluid and breath-based illicit substance detection expands in Qatar's industrial safety mandates and Saudi construction sector compliance programs. Cross-reactivity challenges limit deployment to preliminary screening tiers.
- Research Purposes:Academic medical centers and public health institutions utilize analyzers for epidemiological studies and validation protocols. Procurement concentrates in Saudi Arabia's university hospital networks and Dubai's biomedical research clusters.
Alcohol Detection retains institutional procurement dominance; Medical Diagnostics represents the most underpenetrated expansion opportunity as hospital protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's traffic safety modernization programs and the UAE's workplace wellness mandates are propelling institutional procurement across the Gulf Cooperation Council. National regulators in Riyadh and Abu Dhabi are tightening accuracy standards for evidentiary-grade devices. Procurement clusters concentrate in capital cities and industrial corridors where law enforcement and occupational health screening converge.
Saudi Arabia
Roadside enforcement digitization programs are replacing legacy semiconductor units with fuel-cell analyzers for court-admissible readings. SFDA medical device classification rules now mandate local biocompatibility testing and Arabic-language labeling compliance. Riyadh and the Eastern Province anchor deployment volumes as traffic police consolidate multi-year fleet leasing arrangements.
United Arab Emirates
Federal occupational health directives require alcohol screening across construction, logistics, and oilfield operations. MOHAP conformity assessment pathways extend registration timelines for clinical-grade models entering Dubai and Abu Dhabi markets. The Dubai-Abu Dhabi corridor clusters ISO 17025-accredited calibration laboratories that service secondary city deployments.
Qatar
Industrial safety protocols in the liquefied natural gas sector are mandating breathalyzer integration into facility access control systems. FIFA-legacy infrastructure maintenance programs sustain procurement cycles for workplace health screening. Doha concentrates demand as multi-site diagnostic chains seek standardized fleet configurations.
Kuwait
Traffic enforcement agencies are piloting smart analyzer deployments with Bluetooth connectivity for digitized evidence chains. The country's national pharmaceutical regulator is evaluating alignment with GCC harmonization initiatives for medical device standards. Kuwait City absorbs initial procurement volumes before secondary governorate expansion.
Bahrain
Occupational health mandates in financial services and hospitality sectors are institutionalizing workplace screening programs. The island's compact geography reduces calibration infrastructure bottlenecks seen in larger GCC markets. Manama concentrates both enforcement and clinical procurement as regulatory timelines align with Saudi and Emirati frameworks.
GCC Breath Analyzer Market Key Industry Players
On the supply side, the industry is consolidating around vendors with balance-sheet capacity for multi-year service contracts and captive calibration networks. Three strategic archetypes dominate: German-engineered precision manufacturers with Gulf service infrastructure, North American fuel-cell specialists optimizing for desert climate resilience, and regional distributors bundling training programs for customer retention. Competitive moves center on fleet leasing consolidation and cloud-connected platform development that virtualizes evidence chains.
Within the precision-engineering tier, Drägerwerk AG & Co. KGaA anchors its position through a captive service network sustaining recurring calibration revenue across Gulf states. Lifeloc Technologies, Inc. and Intoximeters, Inc. occupy positions as North American specialists, with the former exemplifying portable fuel-cell optimization and the latter representing training-program bundling that extends retention beyond hardware transactions. These three companies collectively illustrate how vendor selection criteria have shifted from transactional equipment purchases toward integrated service ecosystems.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Lifeloc Technologies, Inc. |
| Intoximeters, Inc. |
| Alcohol Countermeasure Systems Corporation |
| AK GlobalTech Corporation |
| BACtrack, Inc. |
| EnviteC-WISMER GmbH |
| Lion Laboratories |
| AlcoPro, Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in ISO 17025-accredited calibration laboratories across Riyadh and Dubai compresses service availability and emboldens incumbent vendors to bundle multi-year leasing at premium rates. Saudi traffic police and UAE occupational health inspectors absorb these consolidated contracts because fragmented alternatives cannot meet evidentiary chain-of-custody requirements.
Pricing Analysis
Certification level creates the primary spread, with SFDA medical device registration and MOHAP conformity assessment tiers separating clinical-grade tabletop units from screening-tier portable devices. Three-tier pricing structure across premium fuel-cell, standard connected, and economy semiconductor levels dominates procurement, though platinum group metal cost volatility in fuel-cell electrodes intensifies margin pressure on precision manufacturers. Semiconductor-based preliminary screening units face acute price sensitivity from construction and logistics sectors in the UAE, while hospital laboratories in Saudi Arabia exhibit lowest sensitivity due to regulatory-mandated accuracy floors.
Supply Chain Analysis
Extended payment terms demanded by Saudi Arabia's traffic safety modernization programs and Qatar's industrial safety mandates favor vendors with captive financing facilities or balance-sheet depth for multi-year receivables. Manufacturing concentration centers on Germany, the United States, and China for fuel-cell sensor assemblies and platinum catalyst electrodes, with distribution running through Dubai-based regional hubs that service secondary GCC cities. Single-source vulnerability in platinum group metal supply from South Africa and Russia exposes hardware margins to commodity price swings, while sealed housing components for desert climate resilience draw from specialized Japanese and German industrial coating suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Saudi and Emirati procurement committees consolidate around multi-year fleet leasing bundles, displacing transactional equipment vendors and fragmenting competitive access for capital-constrained entrants.
For Market Incumbents: Insulate recurring revenue streams by embedding proprietary calibration protocols into leased device fleets that lock out third-party service competitors. Acquire or build ISO 17025-accredited laboratories in Doha and Kuwait City to preempt geographic bottlenecks that could fragment service economics. Expand Arabic-language regulatory affairs teams to compress SFDA and MOHAP registration timelines before clinical-grade competitors establish dossier precedence.
For New Entrants and Emerging Players: Qatar's liquefied natural gas sector and Bahrain's financial services occupational health mandates represent underpenetrated white-space where incumbent leasing structures have not yet consolidated. Target hospital metabolic monitoring applications in Saudi Arabia's university hospital networks, where SFDA pathway complexity has slowed established vendor penetration. Pursue Bluetooth-enabled cloud integration partnerships with regional systems integrators rather than direct hardware sales to bypass balance-sheet barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fuel-cell specialists with proven desert climate housing designs and existing Gulf regulatory dossiers, as these capabilities cannot be replicated within typical private equity hold periods. Monitor harmonization progress between SFDA medical device classification and MOHAP conformity assessment pathways as the signal for whether regional regulatory fragmentation will persist or consolidate. Continuous validation against operating reality is the recommended discipline.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Fleet Leasing Consolidation | Saudi traffic police and UAE occupational health inspectors now demand bundled hardware-calibration-training contracts. |
| Bluetooth-Enabled Cloud Platform Development | Smart analyzers with encrypted upload capabilities virtualize evidence chains and create recurring software subscription revenue. |
| ISO 17025 Laboratory Geographic Expansion | Accredited calibration capacity in Doha and Kuwait City resolves bottlenecks that delay secondary city deployments. |
| SFDA Clinical-Grade Registration Investment | Hospital metabolic monitoring applications require local biocompatibility testing and Arabic labeling compliance. |
| Desert Climate Sealed Housing R&D | Enhanced thermal cycling resistance and sand particulate protection extend fuel-cell operational life in Gulf conditions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with law enforcement procurement officers, hospital biomedical engineers, occupational health compliance managers, and fuel-cell sensor manufacturing executives. Secondary validation drew from SFDA medical device registration databases, MOHAP conformity assessment filings, customs import records for breath analyzer equipment, and ISO 17025 laboratory accreditation directories. Bottom-up demand modeling across end-user segments was triangulated against top-down market sizing from regional distributor shipment data.
Calibration against historical procurement volumes in Saudi Arabia's traffic safety programs and UAE federal occupational health directives anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include end-user type, product configuration, sensor technology, and application vertical, with CAGRs derived from weighted average of segment-level growth trajectories. Platinum group metal price indices and regulatory registration timeline datasets served as industry-specific forecast inputs.
Practitioners should monitor platinum catalyst cost volatility, SFDA-MOHAP harmonization negotiations, and law enforcement digitization budget allocations for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market