
 AI Portable Chest X-ray Triage Device Market | 2026-2036
AI Portable Chest X-ray Triage Device Market Size, Share, and Industry Trends Forecast 2026-2036
AI Portable Chest X-ray Triage Device Market Insights
Emergency care centers is collapsing the historical dominance of radiology departments as the primary buyer archetype for AI portable chest X-ray triage devices. Qure.ai leverages its deep learning pipeline to anchor deployment across South Asian screening networks. Lunit competes through computer vision specialization in pulmonary nodule detection. Siemens Healthineers sustains manufacturing scale across European and North American distribution channels.
An AI portable chest X-ray triage device integrates deep learning algorithms with digital radiography hardware weighing under fifteen kilograms, enabling point-of-care pulmonary analysis without fixed installation. The system processes anterior-posterior chest images through convolutional neural networks to flag pneumothorax, consolidation, or pleural effusion for clinician review within ninety seconds. Mobile carts command the largest installed base among product configurations due to their balance of mobility and detector size. Tuberculosis screening applications exhibit the fastest expansion trajectory as national health programs integrate AI triage into decentralized testing protocols. Handheld devices concentrate emerging demand from military and disaster response units requiring field-deployable diagnostics.
FDA 510(k) clearance and CE marking under the EU MDR govern commercial access across North America and Europe, with both frameworks tightening algorithm validation requirements for AI diagnostic software. India's CDSCO and the national tuberculosis program jointly shape procurement specifications for devices deployed in rural screening camps. Stakeholders must monitor evolving reimbursement codes for AI-augmented radiology reads, as payer decisions will determine whether point-of-care deployment expands beyond grant-funded public health programs into sustainable commercial channels.
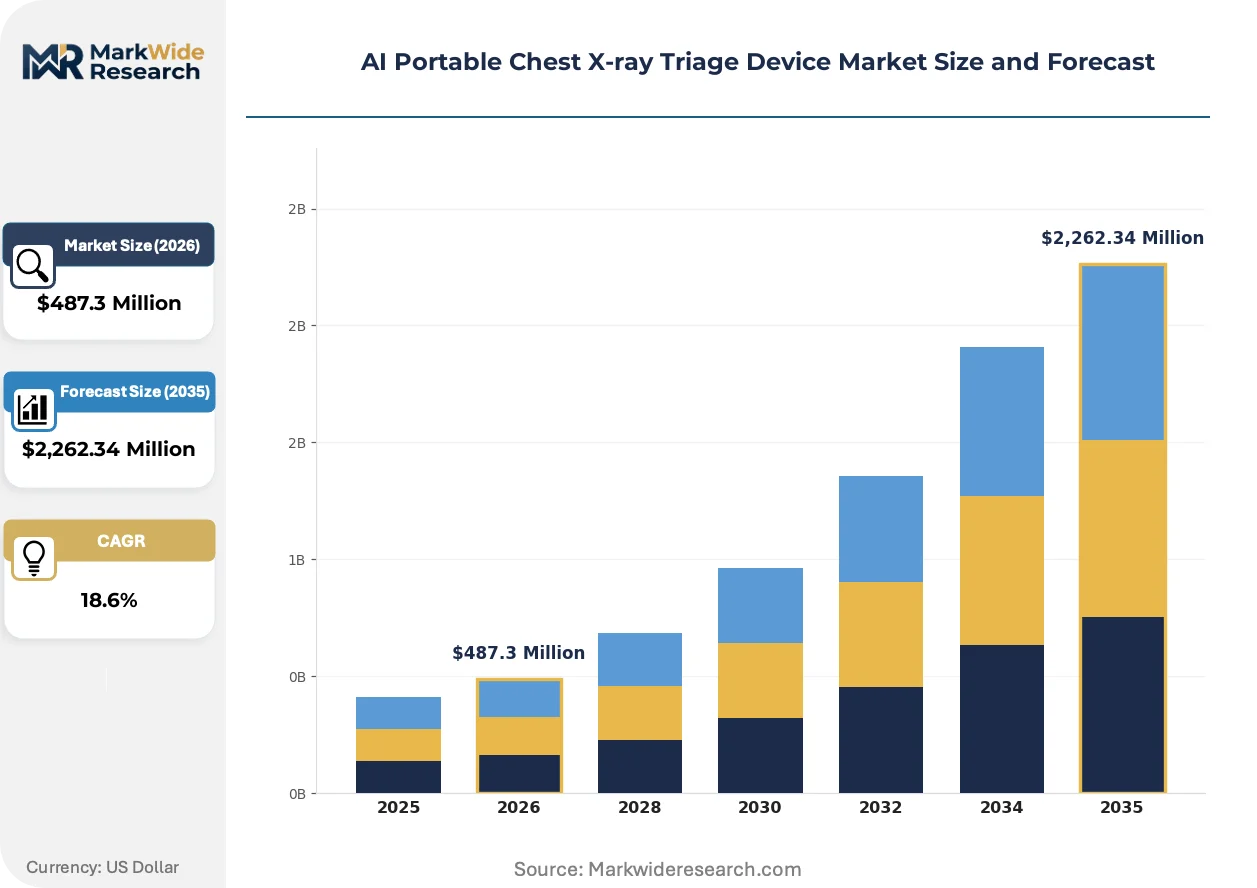
Market Dynamics
Emergency care centers are displacing radiology departments as the primary procurement channel for AI portable chest X-ray triage devices, driven by point-of-care pulmonary screening protocols and decentralized diagnostic mandates.
Growth Catalysts
- India's National Tuberculosis Elimination Program:The government's CDSCO-aligned procurement specifications for rural screening camps are accelerating deployment of mobile AI triage units across district health networks.
- FDA 510(k) clearance streamlining:Algorithm validation pathways for AI diagnostic software are compressing commercial entry timelines for device developers targeting North American emergency departments.
- Convolutional neural network advancement:Deep learning pipelines now flag pneumothorax, consolidation, and pleural effusion within ninety seconds, enabling real-time clinical decision support at bedside.
Market Restraints
- Detector manufacturing concentration:Flat-panel detector supply chains cluster in East Asian fabrication facilities, exposing procurement timelines to regional logistics disruptions.
- EU MDR algorithm validation tightening:CE marking requirements for AI diagnostic software have extended conformity assessment durations, delaying European commercial launches.
- Fixed radiography substitution:Hospital systems with existing digital radiography infrastructure resist capital redeployment toward portable alternatives despite mobility advantages.
Strategic Opportunities
- Military and disaster response procurement:Handheld device configurations under fifteen kilograms are capturing emerging demand from field-deployable diagnostic units requiring battery-operated screening.
- AI-augmented reimbursement code evolution:Payer decisions on point-of-care radiology read compensation will determine expansion beyond grant-funded public health programs into sustainable commercial channels.
- Edge computing convergence with 5G networks:Real-time image transmission to cloud-based diagnostic platforms enables remote specialist consultation in rural screening camps lacking on-site radiologists.
Industry Challenges
- Clinical validation dataset assembly:Developers face protracted timelines curating diverse, annotated chest image libraries spanning multiple pulmonary pathologies and demographic populations.
- Legacy PACS integration complexity:Emergency departments with entrenched picture archiving systems encounter friction embedding AI triage outputs into existing radiologist workflow interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Portable Chest X-ray Triage Device Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Mobile Carts, Wall-Mounted Units, Portable Racks Technology: Deep Learning, Convolutional Neural Networks, Computer Vision, Natural Language Processing, Support Vector Machines Application: Pneumonia Detection, Tuberculosis Screening, COVID-19 Triage, Pulmonary Disease Identification, Trauma Assessment End User: Clinics, Emergency Care Centers, Field Hospitals, Mobile Medical Units, Screening Camps |
| Companies Covered | Qure.ai, Lunit, VUNO, Annalise.ai, Aidoc, Delft Imaging, Oxipit, GE HealthCare, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Portable Chest X-ray Triage Device Market Trends and Innovations
Deep learning inference at the edge is restructuring how pulmonary screening occurs outside traditional radiology suites, compressing diagnostic latency while expanding deployable settings.
On-device convolutional neural network processing is supplanting cloud-dependent image analysis architectures in military and disaster response deployments. Field units operating in bandwidth-constrained environments require sub-ninety-second diagnostic outputs without satellite uplink dependency. This shift is enabling autonomous screening operations in remote terrain where connectivity infrastructure remains absent.
EU MDR Article 10 algorithm validation requirements are mandating prospective clinical performance studies for AI diagnostic software seeking CE marking. Device manufacturers must now submit multi-site evidence demonstrating sensitivity and specificity across diverse patient populations. European emergency care networks are responding by consolidating procurement specifications around MDR-compliant platforms, filtering non-conforming vendors from tender processes.
Grant-funded public health programs are fragmenting into outcome-based service contracts as national tuberculosis programs demand screening throughput guarantees rather than capital equipment ownership. Mobile cart operators in India's district health networks now contract for case detection volumes, transferring utilization risk from procurement agencies to device vendors. This reconfiguration concentrates vendor selection criteria on algorithm accuracy and fleet maintenance capabilities rather than hardware specifications alone.
AI Portable Chest X-ray Triage Device Market Segmentation
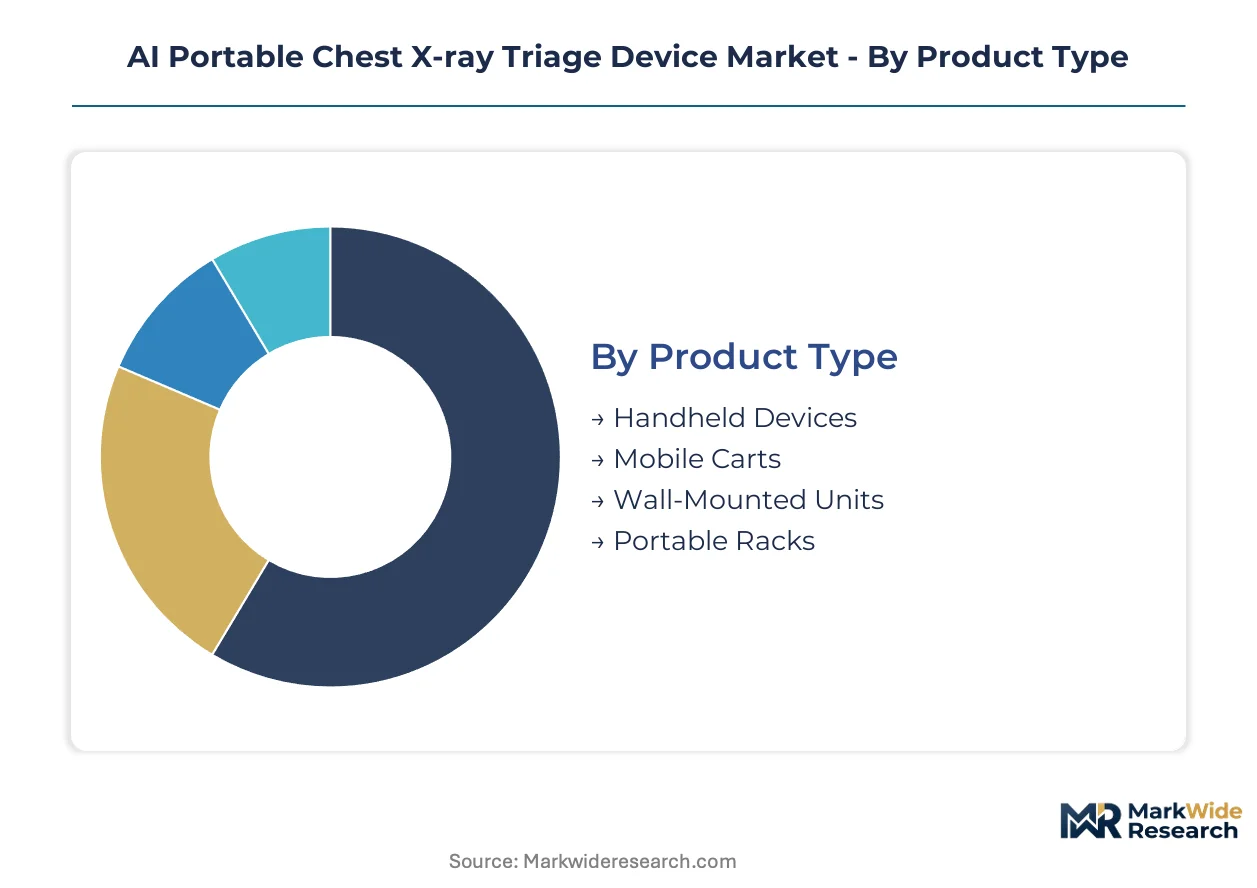
Segmentation reveals how hardware portability and algorithm sophistication combine to unlock distinct procurement channels. Each dimension exposes divergent margin structures and regulatory pathways that shape vendor positioning.
Product Type:
Mobile carts concentrate manufacturing in domestic assembly facilities serving hospital networks, while handheld configurations drive export-led demand from military and disaster response procurement agencies.
- Handheld Devices:These units weigh under fifteen kilograms and operate on battery power for autonomous field screening. India's district health networks and NATO field medical units are consolidating procurement around this form factor for rural camps and combat zones where grid connectivity fails.
- Mobile Carts:Balanced mobility with full-size flat-panel detectors positions these as the workhorse for emergency department triage bays. US emergency care centers and German hospital systems are standardizing fleet specifications around cart-based deployments that preserve image quality while enabling bedside positioning.
- Wall-Mounted Units:Semi-permanent installations serve fixed screening stations in urban clinics with space constraints. The CDSCO procurement framework for India's urban primary health centers favors this configuration for tuberculosis detection programs.
- Portable Racks:Collapsible frame systems enable rapid deployment in temporary field hospitals. UNHCR and Red Cross logistics teams specify rack-based systems for refugee camp medical infrastructure.
Mobile carts command the established base. The steepest expansion runs through handheld devices.
Technology:
Algorithm architectures stratify by computational intensity, with cloud-dependent pipelines dominating cost-sensitive public health tenders and edge-optimized networks capturing premium military contracts.
- Deep Learning:Multi-layer neural architectures enable simultaneous detection of pneumothorax, consolidation, and pleural effusion from single anterior-posterior views. Screening camps in India's National Tuberculosis Elimination Program are mandating deep learning backends for algorithm accuracy guarantees in service contracts.
- Convolutional Neural Networks:Specialized image-processing layers optimize for chest radiograph feature extraction with sub-ninety-second inference latency. Emergency care networks in the US and UK are specifying CNN-based devices for real-time triage decision support.
- Computer Vision:Traditional feature-detection approaches persist in legacy installations requiring minimal retraining. Older EU hospital systems with entrenched PACS infrastructure maintain computer vision devices for workflow compatibility.
- Natural Language Processing:Structured report generation from image findings automates documentation for rural clinics lacking radiologist coverage. South African provincial health departments are piloting NLP-augmented devices for automated case reporting to national surveillance systems.
- Support Vector Machines:Lightweight classification algorithms run on minimal hardware for ultra-low-resource settings. Médecins Sans Frontières deploys SVM-based triage tools in conflict zones where device replacement costs dominate procurement criteria.
Deep learning architectures anchor current procurement specifications. Edge-optimized CNN implementations are climbing the fastest as bandwidth constraints reshape deployment requirements.
Application:
Clinical use cases diverge sharply by reimbursement environment, with grant-funded tuberculosis programs sustaining volume and trauma applications commanding premium pricing from defense budgets.
- Tuberculosis Screening:National elimination programs in India, Indonesia, and Nigeria are driving the largest installed base through mobile camp deployments. CDSCO-aligned procurement specifications require sensitivity thresholds above ninety percent for sputum-negative case detection.
- Pneumonia Detection:Pediatric and geriatric emergency departments prioritize rapid consolidation identification to reduce antibiotic stewardship delays. US children's hospitals and Japanese geriatric centers are expanding fleet deployments for seasonal respiratory surge capacity.
- COVID-19 Triage:Post-pandemic residual demand concentrates in pandemic preparedness stockpiling by health ministries. Singapore's national strategic reserve and Brazil's SUS system maintain dormant device fleets for respiratory outbreak response.
- Pulmonary Disease Identification:Chronic obstructive pulmonary disease and interstitial lung disease screening extends utility beyond acute triage. German pulmonology clinics are integrating portable devices into home-based monitoring programs for COPD exacerbation prevention.
- Trauma Assessment:Field-deployable pneumothorax detection serves combat casualty care and mass casualty events. US Army Combat Support Hospitals and Israeli Defense Forces medical units specify trauma-optimized devices with blast-resistant housing.
Tuberculosis screening anchors the installed base. Trauma assessment applications are gaining share fastest as defense medical modernization accelerates.
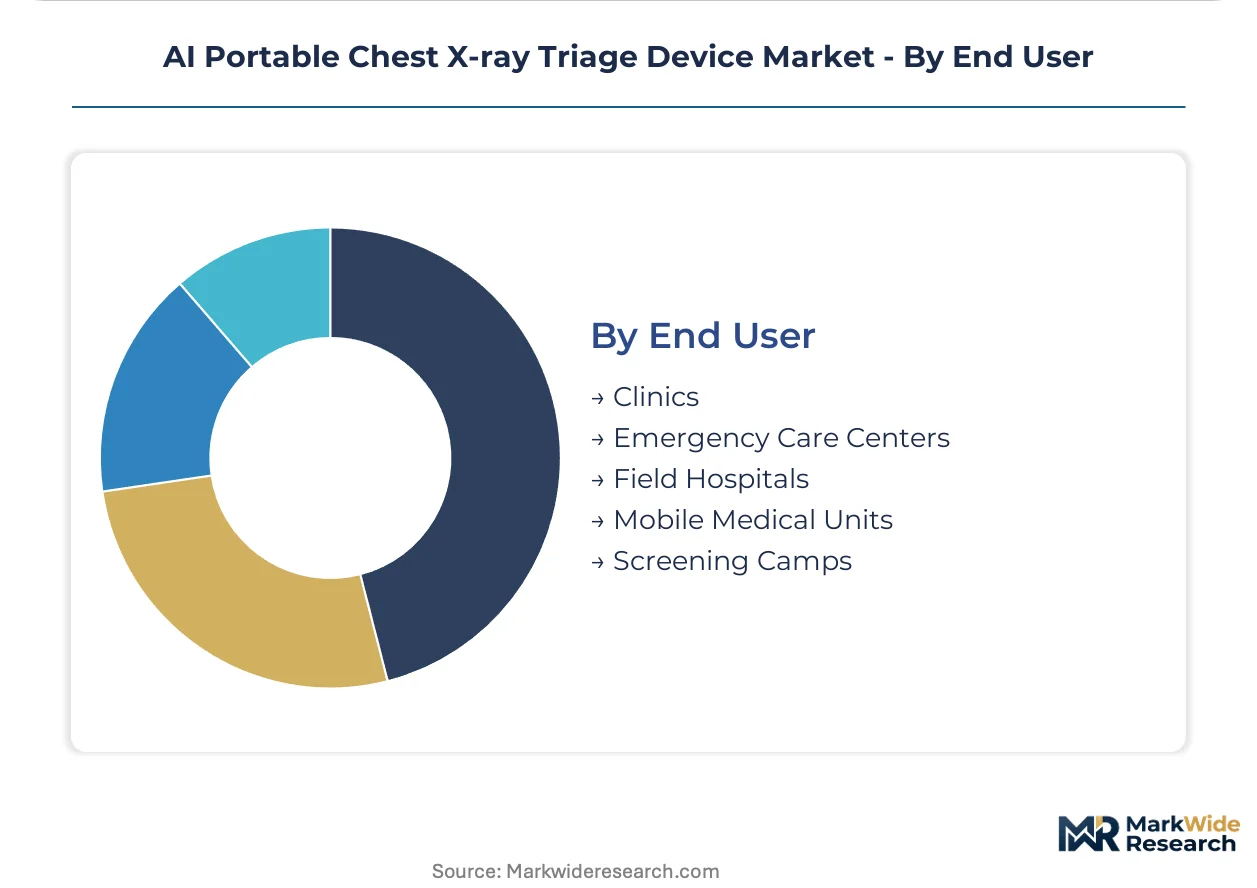
End User:
Customer archetypes fragment by capital availability, with grant-dependent screening camps demanding outcome-based contracts and emergency care centers negotiating traditional equipment financing.
- Emergency Care Centers:Point-of-care pulmonary protocols are displacing radiology department hegemony as the primary procurement channel. US freestanding emergency departments and UK urgent treatment centers are consolidating vendor selection around ninety-second triage turnaround requirements.
- Screening Camps:India's rural district health networks operate the largest fleet through national tuberculosis program service contracts. Vendors now guarantee case detection volumes rather than equipment performance, transferring utilization risk from public health agencies.
- Clinics:Urban primary health centers in Brazil, Mexico, and South Africa deploy wall-mounted units for integrated chronic disease management. Municipal health budgets favor devices with multi-pathology detection to maximize capital efficiency.
- Field Hospitals:Military and humanitarian medical infrastructure requires rapid-deployment configurations with autonomous power and minimal calibration. NATO Role 2 facilities and ICRC surgical units specify handheld devices for damage control resuscitation workflows.
- Mobile Medical Units:Bus-based and boat-based screening programs in the Philippines, Bangladesh, and Amazon basin regions demand vibration-resistant hardware. Fleet operators prioritize devices with standardized maintenance protocols to sustain remote operations.
Emergency care centers command the established base. Field hospital procurement is expanding most quickly as defense and disaster response budgets converge on portable diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flat-panel detector fabrication clusters in East Asian facilities, yet procurement specifications from national tuberculosis programs in South Asia and regulatory tightening in Europe are redrawing commercial access maps. Device vendors now calibrate regional strategies against divergent validation requirements and grant-funded procurement rhythms.
India
CDSCO-aligned procurement frameworks for the National Tuberculosis Elimination Program are driving mobile screening camp deployments across district health networks. The national tuberculosis program mandates sensitivity thresholds above ninety percent for sputum-negative case detection in rural camps. Maharashtra and Karnataka host the densest concentrations of mobile cart operators contracting for case detection volumes rather than equipment ownership.
United States
FDA 510(k) clearance streamlining for AI diagnostic software is compressing commercial entry timelines for emergency department deployments. Freestanding emergency care centers in Texas and Florida are consolidating vendor selection around ninety-second triage turnaround requirements. The Southeast corridor exhibits the fastest fleet expansion as point-of-care pulmonary protocols displace radiology department hegemony.
Germany
EU MDR Article 10 algorithm validation requirements are extending conformity assessment durations for CE marking, filtering non-conforming vendors from European tender processes. Hospital systems in Bavaria and North Rhine-Westphalia are standardizing fleet specifications around MDR-compliant mobile cart platforms. German pulmonology clinics are integrating portable devices into home-based COPD monitoring programs.
China
NMPA regulatory pathways for AI diagnostic software are structuring commercial access for domestic device developers targeting township hospital networks. Yangtze River Delta fabrication clusters supply flat-panel detectors to global assembly facilities, exposing procurement timelines to regional logistics disruptions. Provincial health commissions in Guangdong and Jiangsu are piloting outcome-based service contracts for rural screening programs.
Brazil
ANVISA regulatory frameworks are governing commercial entry for AI diagnostic devices targeting the SUS system and municipal health budgets. São Paulo and Minas Gerais municipal health departments favor wall-mounted units with multi-pathology detection for urban primary health centers. The national strategic reserve maintains dormant device fleets for respiratory outbreak response under pandemic preparedness protocols.
AI Portable Chest X-ray Triage Device Market Competitive Landscape
Concentration sits with specialized AI diagnostic software developers rather than legacy radiography hardware manufacturers, creating a bifurcated structure where algorithm accuracy and regulatory clearance velocity determine procurement outcomes. The vendor landscape stratifies across three archetypes: pure-play AI developers with regulatory-first strategies, diversified medtech conglomerates with manufacturing scale, and grant-funded public health specialists with outcome-based contracting capabilities. Dominant competitive moves include strategic partnerships between AI developers and detector manufacturers to secure supply chain access, plus geographic expansion through CDSCO and FDA clearance stacking to unlock procurement channels.
Within the pure-play AI developer tier, Qure.ai and Lunit exemplify regulatory-first strategies anchored in South Asian and North American emergency care networks respectively. Siemens Healthineers occupies a position bridging algorithm development and manufacturing scale across European distribution channels. These three entities represent the dominant competitive archetypes: deep learning pipeline specialists, computer vision specialists, and integrated medtech conglomerates with captive hardware production.
| Leading Market Players |
|---|
| Qure.ai |
| Lunit |
| VUNO |
| Annalise.ai |
| Aidoc |
| Delft Imaging |
| Oxipit |
| GE HealthCare |
| Siemens Healthineers |
| Others |
Pricing and Supply Chain Analysis
Ninety-day flat-panel detector lead times from Yangtze River Delta fabrication clusters concentrate procurement power with East Asian suppliers and compress margin buffers for device assemblers facing emergency care center price sensitivity.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across North American emergency departments, separating MDR-validated premium configurations from economy-tier grant-funded screening camp units. Three-tier pricing structure across premium, standard, and economy levels reflects algorithm accuracy guarantees, CE marking status, and after-sales service bundling. Cost compression in the economy tier is intensifying because India's national tuberculosis program shifts from capital ownership to outcome-based service contracts. Screening camps exhibit the highest price sensitivity, while military procurement units prioritize field reliability over unit cost.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes flat-panel detector shipments to logistics disruptions that cascade through global assembly networks. Manufacturing concentrates in China, South Korea, and Japan for amorphous silicon detector substrates, cesium iodide scintillator layers, and lithium-ion battery modules. Device assembly draws from these inputs while distribution runs through regional medtech distributors serving hospital networks and direct-to-government tenders for public health programs. Single-source vulnerability in East Asian fabrication facilities represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as interoperability standards enable algorithm-agnostic hardware deployment and ecosystem lock-in replaces standalone device margins.
For Market Incumbents: Fortify regulatory clearance velocity as the primary defensive moat against pure-play AI developers encroaching on emergency department procurement. Deepen backward integration into flat-panel detector supply chains to insulate margin structures from East Asian logistics disruptions. Prioritize CE marking investment under EU MDR Article 10 to filter non-compliant competitors from European tender processes. For New Entrants and Emerging Players: FDA 510(k) De Novo fast-track pathways unlock white-space penetration in US freestanding emergency care centers where point-of-care pulmonary protocols displace radiology department purchasing. Target trauma assessment applications for military and disaster response procurement, where defense budgets absorb premium pricing and specification requirements favor nimble hardware configurations. Pursue CDSCO-aligned validation partnerships with Indian state health departments to access national tuberculosis program service contract pipelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to divest non-core AI diagnostic software divisions amid portfolio rationalization pressures. Long-term viability centers on algorithm accuracy differentiation and regulatory clearance stacking across FDA, CE marking, and CDSCO jurisdictions. Watch for reimbursement code evolution for AI-augmented radiology reads as the inflection signal determining sustainable commercial channel expansion beyond grant-funded public health programs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Compresses commercial entry timelines for emergency department deployments targeting ninety-second triage turnaround requirements. |
| CE Marking Under EU MDR | Filters non-conforming vendors from European tender processes through Article 10 algorithm validation mandates. |
| CDSCO Alignment Partnership | Unlocks procurement specifications for India's national tuberculosis program rural screening camp deployments. |
| Flat-Panel Detector Supply Agreement | Secures manufacturing scale against East Asian fabrication concentration risks and logistics chokepoint exposure. |
| Outcome-Based Service Contract Model | Transfers utilization risk from public health agencies to vendors while concentrating selection criteria on algorithm accuracy. |
Research Methodology
Operator-level perspectives from emergency department physicians, biomedical engineers, GPO contracts managers, and national tuberculosis program procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, CDSCO device registrations, EU MDR conformity assessment databases, and hospital procurement contract repositories. Bottom-up installed base estimates triangulated against top-down market sizing across product type, technology architecture, and end-user segments.
Sensitivity analysis tested forecast robustness across algorithm validation timeline scenarios, flat-panel detector supply disruption assumptions, and reimbursement code adoption trajectories. Segmentation dimensions modeled include hardware portability tier, computational architecture, clinical application, and customer archetype capital availability. CAGRs derived from trend extrapolation of procurement volumes, pricing trajectory assumptions, and technology substitution elasticities. Industry-specific inputs encompassed AI diagnostic software regulatory clearance velocity and grant-funded program budget allocation patterns.
Underlying assumptions cover sustained FDA 510(k) pathway efficiency, stable East Asian detector supply chains, and gradual reimbursement expansion for point-of-care radiology reads, with deviation risk concentrated in EU MDR conformity assessment duration extensions and logistics disruptions affecting Yangtze River Delta fabrication clusters. Practitioners should keep alternative scenarios live as regulatory harmonization efforts and supply chain regionalization initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Procalcitonin Antibody Market