
 Navigated Biopsy Needles Market | 2026-2036
Navigated Biopsy Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Navigated Biopsy Needles Market Analytics
CE-marked and FDA-cleared instrument tiers is bifurcating the competitive landscape into premium navigation-enabled suppliers and conventional needle manufacturers. Medtronic plc leverages its integrated surgical navigation ecosystem to anchor high-end hospital contracts. Boston Scientific Corporation differentiates through specialized interventional oncology portfolios. Cook Group Incorporated sustains manufacturing scale across multiple guidance modalities.
Navigated biopsy needles are precision instruments incorporating electromagnetic or optical tracking sensors, typically manufactured from surgical-grade stainless steel with bevel angles calibrated for specific tissue densities, designed to enable real-time positional verification during percutaneous tissue sampling. Ultrasound-guided and CT-guided technology segments dominate current volume, while MRI-guided configurations represent the fastest-expanding margin pool due to compatibility requirements with magnetic resonance intervention suites. Automated needles capture growing share in outpatient settings where procedural throughput demands exceed manual technique capacity.
FDA 510(k) premarket notification requirements, CE marking under the EU Medical Device Regulation, and ISO 13485 quality management standards collectively govern product commercialization and clinical adoption timelines. These frameworks elevate barriers for entrants lacking established regulatory affairs infrastructure while rewarding incumbents with predicate device portfolios. Stakeholders must monitor evolving notified body capacity constraints in Europe and emerging software-as-medical-device classifications for navigation algorithms.
Market Dynamics
Electromagnetic tracking integration is compressing procedure times in interventional radiology suites, forcing manufacturers to embed sensor arrays directly into needle cannulas rather than relying on external navigation attachments.
Growth Catalysts
- Hospital outpatient expansion:Ambulatory surgical centers in the United States are deploying CT-guided navigated needles to reduce referral leakage to inpatient facilities. This channel shift accelerates volume capture outside traditional hospital radiology departments.
- FDA 510(k) predicate pathway:Established clearance routes for electromagnetic navigation accessories enable faster product line extensions. Manufacturers with existing predicate devices compress time-to-market for next-generation needle configurations.
- Oncology screening protocols:Japan's national cancer screening programs incorporate image-guided biopsy into standardized diagnostic workflows. This policy embedding creates institutional procurement mandates for navigation-enabled instruments.
Market Restraints
- Nickel-titanium alloy concentration:Shape-memory actuator supply for steerable needle tips depends on limited superelastic alloy producers in Germany and Japan. Price volatility in aerospace-grade nitinol constrains margin flexibility.
- CE marking capacity constraints:Notified body bottlenecks under the EU Medical Device Regulation extend commercialization timelines by 8-14 months for new navigation software modules. European market entry faces systematic delays.
- Conventional needle substitution:Standard coaxial biopsy systems with pre-procedural CT planning satisfy cost-sensitive hospital purchasing committees. Navigation premiums face resistance in budget-constrained public health systems.
Strategic Opportunities
- MRI-compatible sensor development:Optical tracking systems eliminating ferromagnetic components enable intervention suite compatibility with 3 Tesla magnets. This convergence addresses the fastest-expanding guidance modality segment.
- German university hospital networks:Comprehensive cancer center designations in Baden-Württemberg and Bavaria mandate minimally invasive diagnostic capabilities. Navigation needle adoption concentrates in these elite referral clusters.
- Software-as-medical-device pathways:Navigation algorithm modules qualify for streamlined regulatory review under emerging FDA digital health frameworks. Standalone software sales decouple revenue from physical instrument replacement cycles.
Industry Challenges
- Interventional radiologist training pipelines:Fellowship programs produce fewer operators proficient in electromagnetic navigation than deployment rates require. Academic medical centers face staffing constraints for complex biopsy procedures.
- Multi-modality integration complexity:Navigation systems must interface with ultrasound, CT, and MRI platforms from competing imaging equipment manufacturers. Protocol standardization across vendor ecosystems demands extensive validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Navigated Biopsy Needles Market |
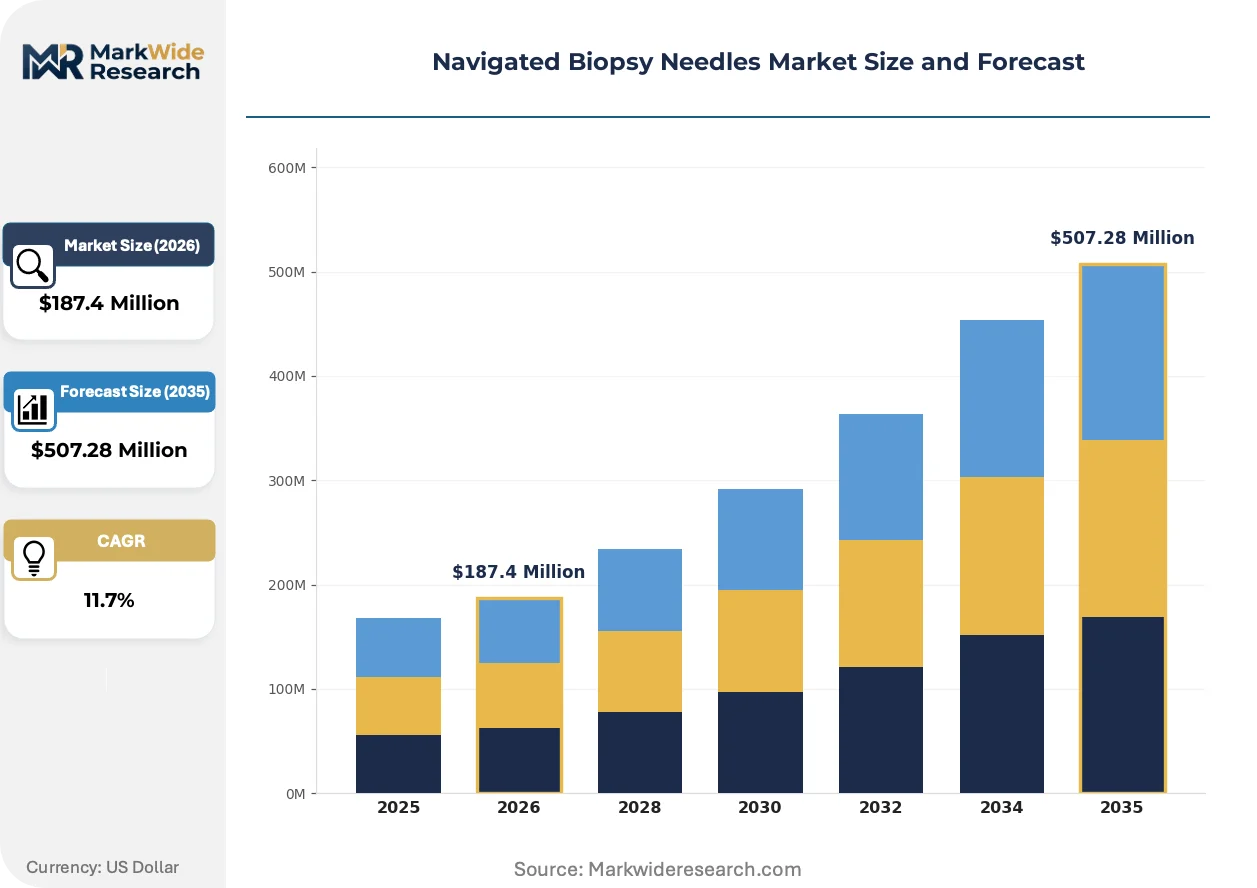
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Needles, Automated Needles, Vacuum-Assisted Needles, Laparoscopic Needles Technology: Ultrasound-Guided, MRI-Guided, CT-Guided, Optical Coherence Tomography End User: Hospitals, Outpatient Clinics, Diagnostic Laboratories, Research Institutions Application: Oncology, Infectious Diseases, Transplantation, Autoimmune Disorders |
| Companies Covered | Medtronic plc, Becton, Dickinson and Company, Boston Scientific Corporation, Olympus Corporation, CONMED Corporation, Cook Group Incorporated, Argon Medical Devices, Inc, Devicor Medical Products, Inc, IZI Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Navigated Biopsy Needles Market Evolving Landscape
Sensor miniaturization and real-time tracking algorithms are collapsing the functional gap between premium navigation systems and conventional image-guided techniques, redistributing value capture across the supply chain.
Optical electromagnetic hybrid tracking is displacing pure electromagnetic systems in high-accuracy applications. Academic medical centers in Germany and Japan are adopting fused-sensor configurations for lung and renal biopsies where respiratory motion compensation matters. This convergence is compressing the addressable market for standalone electromagnetic navigation platforms while expanding the premium tier for multi-sensor instruments.
The EU Medical Device Regulation's software classification requirements are redefining commercialization obligations for navigation algorithms. Manufacturers must now submit standalone technical documentation for tracking software updates, elevating regulatory affairs overhead. Smaller instrument suppliers without dedicated quality systems face exclusion from European procurement tenders requiring MDR-compliant technical files.
Hospital purchasing committees are unbundling navigation hardware from disposable needle contracts. United States health systems now separately negotiate capital equipment leases and per-procedure consumable pricing, compressing supplier pricing power. This disintermediation is most visible in integrated delivery networks consolidating radiology service lines across multiple states.
Navigated Biopsy Needles Market Segmentation
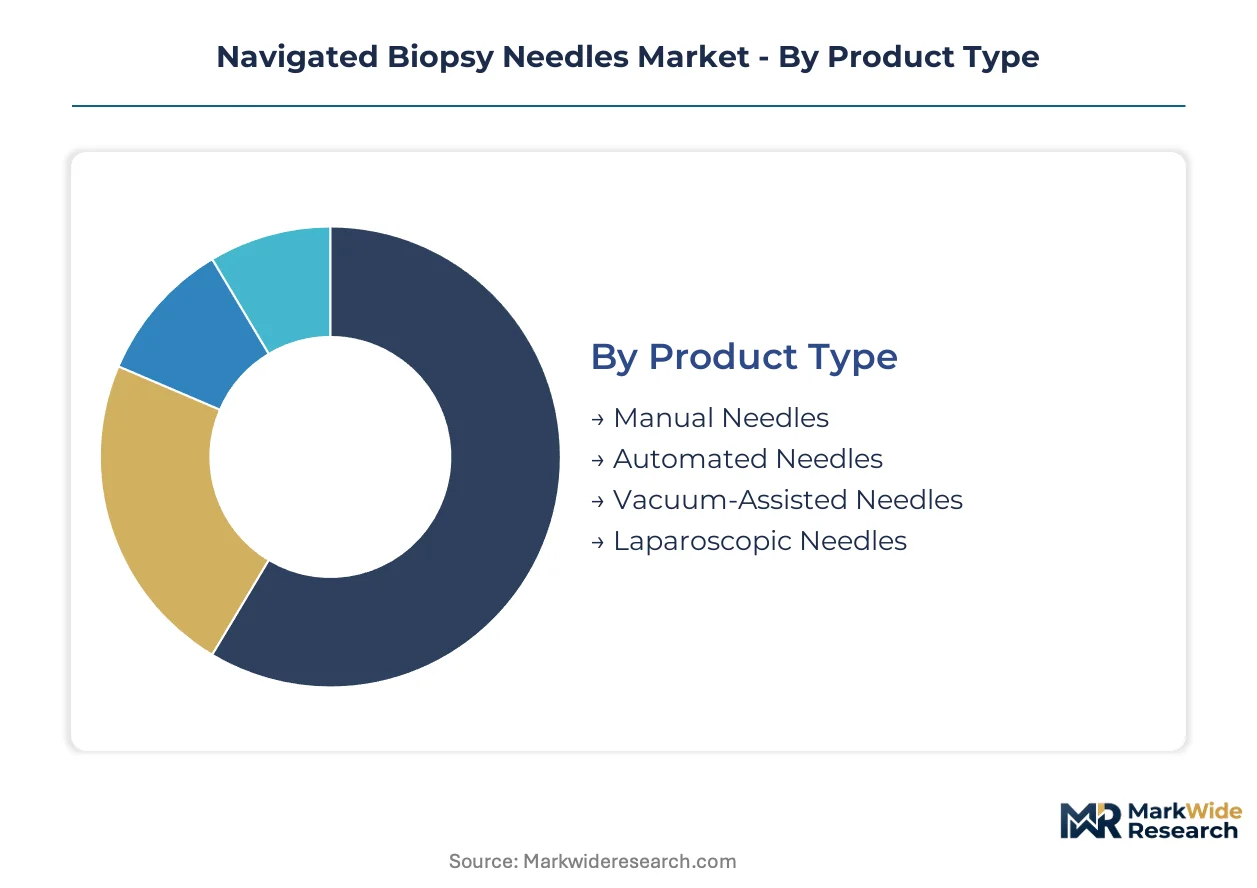
Navigated biopsy needle segmentation reveals divergent margin economics across guidance modalities and automation levels. Procurement patterns split between capital-intensive hospital installations and high-throughput outpatient consumables, reshaping supplier pricing architectures.
Product Type:
Automated configurations command premium pricing in high-volume settings where procedural throughput drives equipment ROI calculations. Manual instruments retain dominance in cost-constrained public health networks.
- Manual Needles:Surgical-grade stainless steel construction with electromagnetic sensor attachments enables real-time tracking without integrated actuator mechanisms. Demand concentrates in German university hospitals where fellowship-trained interventional radiologists prefer tactile feedback control for complex renal and pulmonary biopsies.
- Automated Needles:Spring-loaded or vacuum-actuated firing systems embed position sensors directly within the cannula housing, enabling single-operator deployment in CT suites. United States ambulatory surgical centers are standardizing these configurations to reduce staffing overhead during high-volume lung nodule sampling protocols.
- Vacuum-Assisted Needles:Continuous suction mechanisms paired with navigation arrays improve core tissue yield in breast and prostate procedures.
- Laparoscopic Needles:Curved or articulating tip designs integrate with electromagnetic tracking for intra-abdominal targeting during minimally invasive surgery.
Automated needles hold installed capacity. Vacuum-assisted configurations are rotating up the share rankings.
Technology:
Ultrasound guidance dominates procedural volume due to real-time imaging without ionizing radiation exposure. MRI-compatible tracking systems are climbing the fastest as 3 Tesla intervention suites expand in Japan and Germany.
- Ultrasound-Guided:Linear and curvilinear transducer compatibility with electromagnetic tracking attachments enables superficial and deep tissue access without CT suite scheduling constraints. United States hospital outpatient departments deploy these systems for same-day biopsy completion, reducing patient referral leakage to inpatient radiology.
- MRI-Guided:Optical or ceramic-encased electromagnetic sensors eliminate ferromagnetic interference with magnetic field homogeneity, enabling real-time navigation within closed-bore magnets. German comprehensive cancer centers in Baden-Württemberg are mandating these configurations for soft-tissue sarcoma and liver lesion characterization.
- CT-Guided:Electromagnetic tracking with respiratory gating integration addresses lung and upper abdominal targets where ultrasound penetration fails.
- Optical Coherence Tomography:Near-infrared interferometry provides microscopic-resolution tissue characterization for ophthalmic and dermatologic applications.
Ultrasound-guided systems anchor current revenue. MRI-guided platforms are gaining share fastest.
End User:
Hospital radiology departments concentrate capital equipment investment, while outpatient clinics drive consumable volume through per-procedure pricing models.
- Hospitals:Integrated surgical navigation ecosystems with multi-modality imaging suites require vendor-agnostic needle compatibility across CT, MRI, and fluoroscopy platforms. Japanese national cancer screening program mandates are embedding navigation-enabled biopsy into standardized diagnostic workflows at designated cancer centers.
- Outpatient Clinics:Standalone CT or ultrasound-guided systems with disposable needle contracts enable same-day diagnosis without inpatient admission. United States integrated delivery networks are consolidating procurement across state-level radiology service lines, unbundling capital leases from consumable pricing.
- Diagnostic Laboratories:Pathology-focused operators prioritize vacuum-assisted configurations for adequate tissue sampling in molecular profiling.
- Research Institutions:Preclinical and translational studies drive demand for experimental optical tracking and robotic needle steering prototypes.
Hospitals retain equipment density. Outpatient clinics are expanding most quickly.
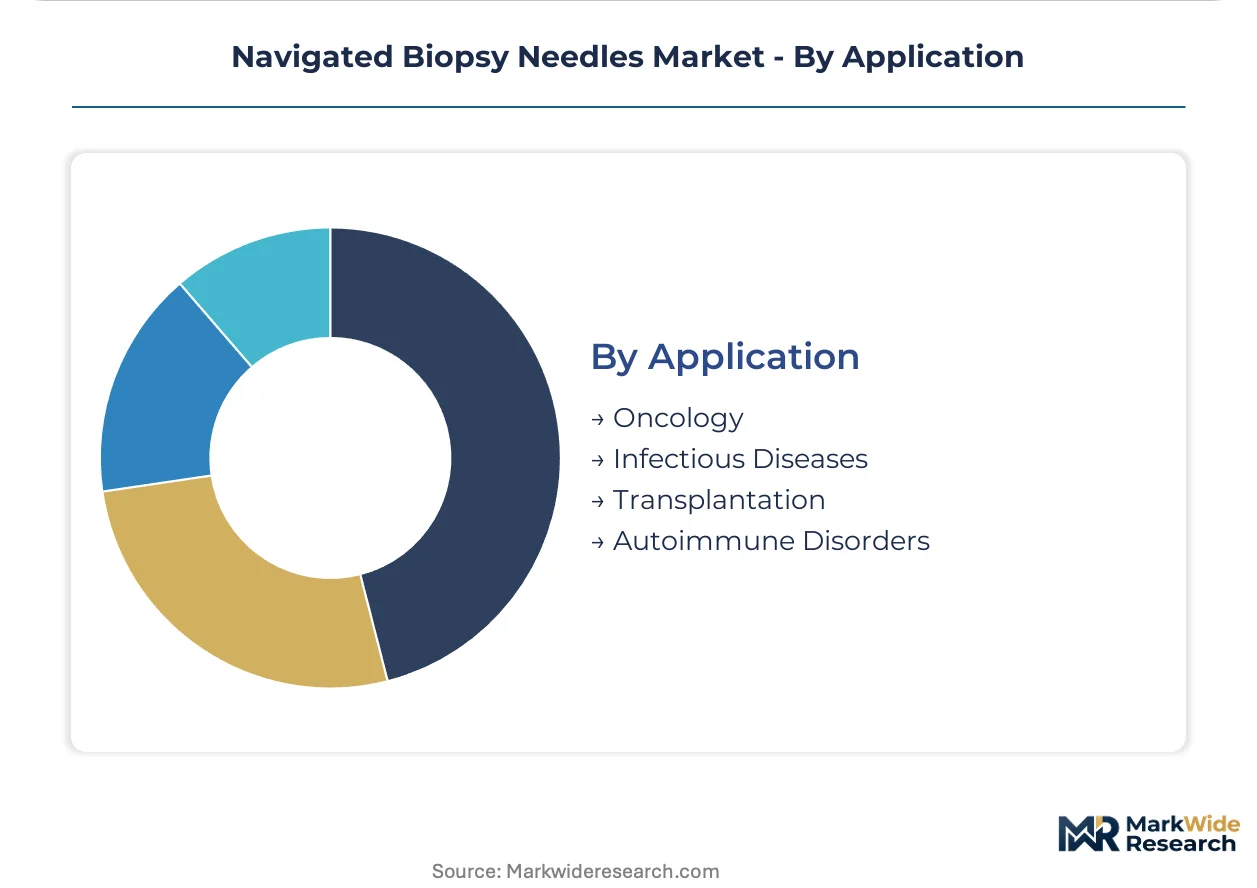
Application:
Oncology diagnostics concentrate reimbursement and procedural volume, while transplantation applications require specialized tissue core quality for graft-versus-host monitoring.
- Oncology:Lung, liver, breast, and prostate lesion characterization demands precise needle placement for histologic grading and molecular marker analysis. Japan's population-wide screening infrastructure is institutionalizing image-guided biopsy as a gateway to precision oncology treatment pathways.
- Infectious Diseases:Deep tissue or organ abscess sampling with navigation verification reduces false-negative cultures in immunocompromised patients.
- Transplantation:Post-transplant surveillance biopsies with real-time tracking ensure adequate cortical sampling for rejection grading.
- Autoimmune Disorders:Renal and muscle biopsies for lupus nephritis and myositis classification benefit from electromagnetic guidance in technically challenging anatomical locations.
Oncology anchors procedure volume. Transplantation applications are climbing the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for nitinol alloys and optical sensors tilts the trade balance toward Germany and Japan, while finished instrument exports concentrate from FDA-cleared manufacturing sites in the United States. Cross-border procurement patterns reflect divergent reimbursement frameworks rather than pure manufacturing cost arbitrage.
United States
Ambulatory surgical centers in Texas and Florida are deploying CT-guided navigated needles to capture lung nodule referrals locally. FDA 510(k) predicate pathways compress clearance timelines for electromagnetic navigation accessories. The Mayo Clinic Rochester campus anchors validation studies for next-generation optical tracking configurations.
Germany
Comprehensive cancer center designations in Baden-Württemberg and Bavaria mandate minimally invasive diagnostic capabilities with real-time navigation. CE marking under the EU Medical Device Regulation governs commercialization timelines for software-integrated instruments. The Tübingen-Stuttgart corridor concentrates superelastic alloy processing for steerable needle actuators.
Japan
PMDA alignment with FDA breakthrough device pathways accelerates approval for MRI-compatible sensor platforms. National cancer screening programs embed image-guided biopsy into standardized diagnostic workflows at designated centers. The Kanto region around Tokyo hosts the highest density of 3 Tesla intervention suites with optical tracking integration.
United Kingdom
NHS England procurement frameworks favor vendor-agnostic needle compatibility across multi-modality imaging platforms. MHRA post-Brexit regulatory autonomy creates parallel submission requirements for navigation software modules. The Oxford-Cambridge-London arc concentrates academic medical centers validating electromagnetic-optical hybrid tracking systems.
Switzerland
Swissmedic's streamlined review for Class IIa surgical instruments attracts navigation algorithm developers seeking European market entry. Precision manufacturing clusters in the Jura Arc supply ceramic-encased sensors for MRI-compatible configurations. Basel's pharmaceutical-industrial complex drives demand for biopsy instruments supporting companion diagnostic tissue acquisition.
Navigated Biopsy Needles Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs infrastructure and predicate device portfolios. The vendor base splits between consolidated multi-modality platform holders and focused navigation component suppliers. Three archetypes dominate: integrated surgical navigation ecosystems, interventional oncology portfolio specialists, and manufacturing-scale consumable suppliers. Competitive moves center on M&A for electromagnetic tracking IP and strategic partnerships with imaging equipment manufacturers.
Within the integrated ecosystem tier, Medtronic plc and Boston Scientific Corporation exemplify platform-centric positioning. Cook Group Incorporated occupies a position among manufacturing-scale specialists with multi-modality supply capabilities. These three anchors represent divergent approaches to navigating unbundled procurement trends in United States health systems.
| Leading Market Players |
|---|
| Medtronic plc |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Olympus Corporation |
| CONMED Corporation |
| Cook Group Incorporated |
| Argon Medical Devices, Inc |
| Devicor Medical Products, Inc |
| IZI Medical Products |
| Others |
Value Network & Pricing Analysis
Capacity utilization at nitinol alloy processors in Germany and Japan anchors cost floors for steerable needle actuators, concentrating supply-side leverage among superelastic alloy specialists while compressing margin flexibility for instrument manufacturers facing unbundled procurement demands.
Pricing Analysis
Hospital purchasing committees anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA 510(k) clearance tier and electromagnetic sensor integration depth. Cost compression in standard manual configurations is intensifying because conventional coaxial systems satisfy budget-constrained public health tenders. Ambulatory surgical centers exhibit highest price sensitivity; German comprehensive cancer centers show least.
Supply Chain Analysis
Inventory lead times for aerospace-grade nitinol extend procurement cycles for shape-memory actuator components. Supply concentrates in Germany, Japan, and the United States for superelastic alloys, ceramic-encased optical sensors, and surgical-grade stainless steel cannulas. Raw material dependencies include nickel-titanium alloys, electromagnetic sensor arrays, and precision-ground needle tubing. Single-source vulnerability in German nitinol processing creates structural risk. Distribution runs through integrated delivery networks consolidating radiology service lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The navigated biopsy needles market is entering a cyclical recovery phase as hospital outpatient expansion and MRI-compatible sensor development converge to reset equipment replacement timelines.
For Market Incumbents: Consolidate electromagnetic tracking IP portfolios through targeted acquisition of optical sensor specialists. Deepen backward integration into nitinol alloy supply to defend against aerospace-sector demand competition. Prioritize MDR-compliant technical documentation capacity to exploit European notified body bottlenecks excluding smaller rivals. For New Entrants and Emerging Players: Software-as-medical-device navigation algorithms represent an under-served service layer where incumbents lack dedicated quality systems. Target United States ambulatory surgical centers with standalone algorithm modules decoupled from physical instrument cycles. Pursue FDA digital health pre-certification as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among navigation algorithm developers with SaaS-tiered licensing models. Long-term viability favors acquisition targets with predicate device portfolios and established regulatory affairs infrastructure. Watch PMDA-FDA breakthrough device alignment velocity as the inflection signal for MRI-guided platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR-compliant technical documentation accelerates European commercialization timelines for software-integrated instruments. |
| Hospital System Partnership | Integrated delivery network contracts secure volume commitments across multi-state radiology service consolidations. |
| Software Companion Development | Standalone navigation algorithm modules qualify for streamlined FDA digital health review pathways. |
| Backward Integration into Sensors | In-house optical tracking production eliminates ferromagnetic component supply constraints for MRI-compatible configurations. |
| Reimbursement Strategy | Japan's national cancer screening program embedding creates institutional procurement mandates at designated centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, PMDA approval databases, hospital procurement records, and EU MDR notified body capacity reports. Bottom-up instrument shipment estimates triangulated with top-down imaging suite installation data.
Across the projection horizon, the analytical framework modeled volume and value outputs by product type, technology modality, end-user setting, and application area. CAGRs were derived from procedure volume elasticity to imaging equipment deployment rates and reimbursement pathway maturation. Forecast inputs incorporated nitinol alloy price volatility indices and fellowship program graduation trajectories.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and PMDA regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Global DNA Test Kit Market