
 Europe NMC Battery Pack Market | 2026-2036
Europe NMC Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Europe NMC Battery Pack Market Insights
Buyer concentration among European automakers is recalibrating contract structures for NMC cell supply. Volkswagen anchors its procurement through SAIC Volkswagen Power Battery, while NorthVolt AB competes on localized Swedish production. Samsung SDI Co Ltd differentiates via high-nickel chemistry roadmaps tailored to premium EV platforms.
A nickel-manganese-cobalt battery pack combines layered oxide cathodes with graphite or silicon-blend anodes in pouch, prismatic, or cylindrical formats, delivering specific energies above 250 Wh per kilogram for traction applications. The automotive product type dominates value capture as OEMs prioritize range optimization, while energy storage systems represent the fastest-growing application segment driven by grid-scale deployment mandates. Solid-state technology remains pre-commercial but absorbs disproportionate R&D investment relative to its current revenue contribution.
The EU Battery Regulation and ECHA REACH compliance frameworks enforce due diligence on cobalt sourcing and end-of-life recycling quotas, compressing margins for non-compliant imports. Germany's KBA type-approval process and France's ANSM-aligned environmental standards further segment market access by certification burden. Stakeholders must track cathode chemistry patent filings and recycling infrastructure buildout to anticipate where cell cost curves and regulatory compliance intersect.
Market Dynamics
High-nickel cathode chemistry roadmaps are compressing cobalt content thresholds while EU Battery Regulation mandates force supply chain reconfiguration across European cell production corridors.
Growth Catalysts
- EU Battery Regulation:Minimum recycled content mandates and carbon footprint declarations are accelerating qualified supplier onboarding across German and French automotive corridors.
- Energy storage systems:Grid-scale deployment obligations under national renewable integration targets are pulling NMC pack demand beyond passenger vehicle applications.
- Silicon-blend anodes:Specific energy gains above 270 Wh per kilogram are enabling platform-level range extension for premium electric vehicle architectures.
Market Restraints
- Cobalt price volatility:Concentrated DRC supply exposure creates margin compression for cathode active material producers lacking long-term offtake hedging.
- Solid-state pre-commercial gap:Disproportionate R&D absorption by unproven electrolyte architectures delays near-term cell cost curve improvement.
- ECHA REACH compliance:Due diligence burdens on conflict mineral sourcing extend qualification timelines for non-EU cell imports by 8-14 months.
Strategic Opportunities
- Swedish production localization:Arctic renewable energy access enables carbon-neutral cell manufacturing for EU Battery Regulation premium tiering.
- Second-life stationary storage:End-of-life electric vehicle pack repurposing opens circular revenue streams under extended producer responsibility frameworks.
- Solid-state convergence:Sulfide electrolyte integration with high-nickel cathodes promises thermal runaway elimination for next-generation traction applications.
Industry Challenges
- Electrolyte formulation talent:Scarcity of solid-state interface engineering expertise constrains pilot line scale-up across European research consortia.
- KBA type-approval timelines:Protracted homologation for novel cell formats delays platform integration cycles for German OEM launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe NMC Battery Pack Market |
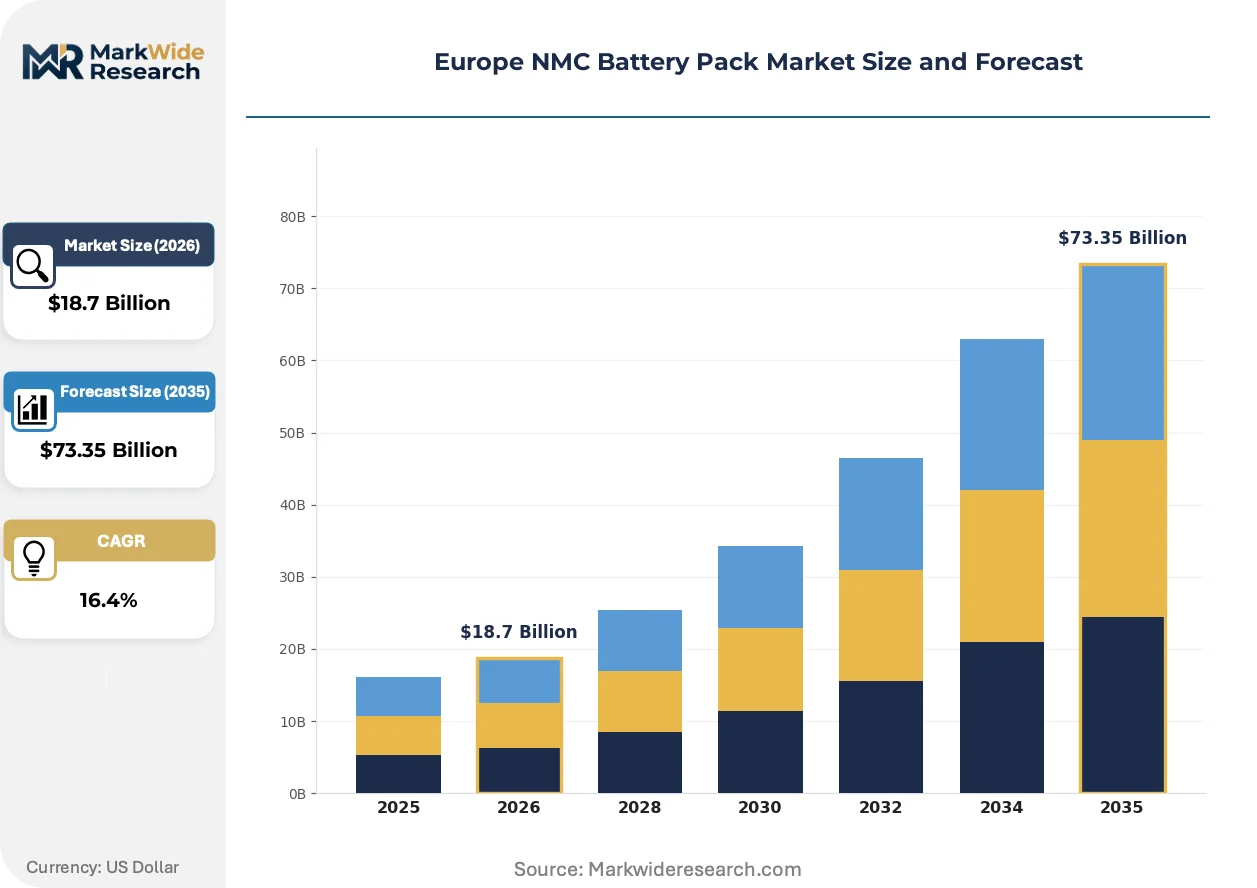
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Automotive, Industrial Application: Energy Storage Systems, Electric Vehicles, Consumer Electronics, Renewable Energy End User: Manufacturers, Utilities, Retailers, Commercial Users Technology: Lithium-Ion, Solid-State, Flow Batteries, Lead-Acid |
| Companies Covered | Contemporary Amperex Technology Co Ltd (CATL), LG Energy Solution Ltd, Samsung SDI Co Ltd, SAIC Volkswagen Power Battery Co Ltd, Groupe Renault, NorthVolt AB, Panasonic Holdings Corporation, SK Innovation Co Ltd, Deutsche ACCUmotive GmbH & Co KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe NMC Battery Pack Market Trends and Innovations
Cathode chemistry patent filings and recycling infrastructure buildout are intersecting to redefine where cell cost curves and regulatory compliance converge across European supply chains.
High-nickel NMC formulations (NMC 811 and beyond) are expanding into premium electric vehicle platforms as cobalt reduction targets harden under EU Battery Regulation thresholds. Stuttgart and Wolfsburg-based OEMs are qualifying these chemistries for 800-volt architectures. The shift is expanding into energy density benchmarks previously reserved for solid-state roadmaps.
REACH compliance enforcement on cobalt hydroxide sourcing is redirecting cathode active material procurement toward EU-certified refiners. The ECHA due diligence framework now requires supply chain documentation through smelter level. Battery pack assemblers in France and Germany are responding by pre-qualifying Nordic and Finnish refined material streams.
Automotive OEMs are consolidating cell procurement under direct contracting structures that bypass traditional tier-one integrators. Volkswagen and BMW are establishing captive supply relationships with cell producers for platform-dedicated capacity. This concentration is most visible in Germany's automotive corridor, where OEMs now specify cathode chemistry and form factor at the engineering stage.
Europe NMC Battery Pack Market Segmentation
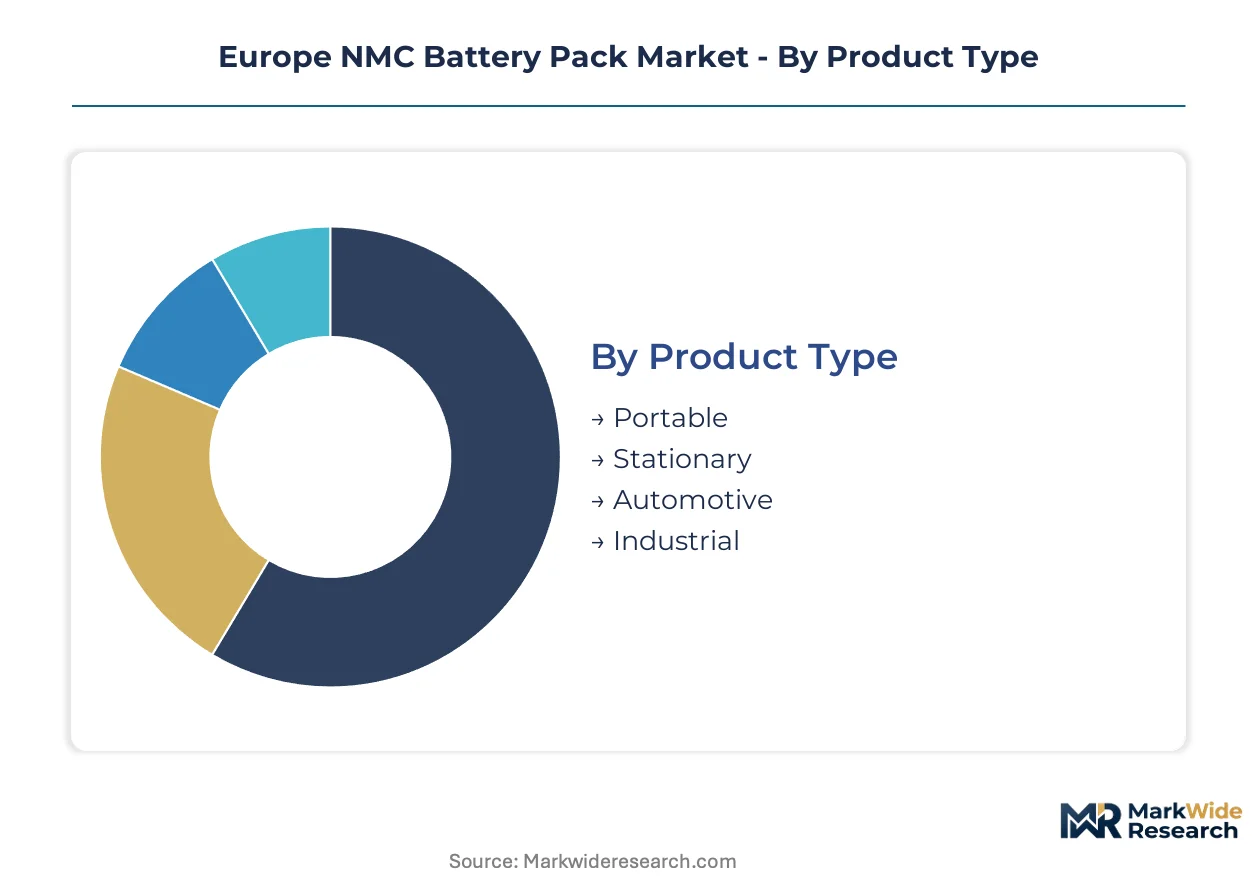
NMC battery pack segmentation in Europe reflects divergent capital requirements across mobility, stationary storage, and industrial applications. Cathode chemistry specifications and form factor standards vary sharply by end-use, forcing producers to maintain parallel qualification tracks for automotive OEMs versus grid-scale integrators.
Product Type:
Automotive and stationary formats demand the heaviest upfront investment in cell assembly lines and thermal management integration.
- Automotive:Pouch and prismatic cells configured for 400-800 volt architectures dominate procurement volumes. Stuttgart-based OEMs specify NMC 811 cathodes for premium platform range targets, while Wolfsburg anchors qualification through dedicated supply agreements.
- Stationary:Rack-mounted systems with liquid cooling infrastructure serve grid-scale deployment mandates under German and French renewable integration targets. Containerized formats absorb the majority of non-automotive cell allocation.
- Portable:Cylindrical 21700 and 18650 formats power light electric mobility and professional equipment. Lower energy density tolerances enable cost-optimized NMC 622 formulations.
- Industrial:Heavy-duty packs for material handling and port electrification require reinforced mechanical enclosures. Forklift OEMs in Germany's logistics corridor specify rapid-charge capable cell configurations.
Automotive absorbs the bulk of installed capacity; stationary is expanding most quickly.
Application:
Segment profitability stratifies by certification burden and contract duration, with mobility platforms commanding premium pricing against utility procurement.
- Electric Vehicles:Passenger car traction applications specify nickel-rich cathodes above 80% nickel content. KBA type-approval requirements extend qualification cycles for novel cell formats entering German OEM platforms.
- Energy Storage Systems:Grid-scale battery farms under national renewable targets pull NMC demand beyond automotive boundaries. French and German utilities prioritize second-life automotive packs for stationary repurposing.
- Consumer Electronics:Power tool and personal device applications favor cylindrical formats with moderate specific energy. ANSM-aligned environmental standards govern cobalt sourcing disclosure for French market access.
- Renewable Energy:Solar-plus-storage and wind farm co-location projects require multi-hour discharge duration. Nordic renewable energy corridors enable carbon-neutral manufacturing claims for EU Battery Regulation tiering.
Electric vehicles command dominant revenue share; energy storage systems are climbing the fastest.
End User:
Contract structures diverge by buyer scale, with integrated manufacturers securing dedicated capacity against spot-market exposure for smaller commercial offtake.
- Manufacturers:Automotive OEMs and tier-one integrators specify cathode chemistry at the engineering stage. Volkswagen and BMW consolidate procurement under direct cell producer relationships, bypassing traditional battery system integrators.
- Utilities:Grid operators under French and German renewable mandates procure containerized systems through framework agreements. Long-term service contracts bundle cell supply with degradation warranties.
- Commercial Users:C&I behind-the-meter installations prioritize payback period over energy density. Logistics operators in Germany's automotive corridor adopt industrial formats for fleet electrification.
- Retailers:Aftermarket and replacement channels serve independent repair networks. ECHA REACH compliance documentation requirements extend qualification timelines for non-EU cell imports.
Manufacturers lock in the majority of forward capacity; utilities are scaling fastest amid grid modernization programs.
Technology:
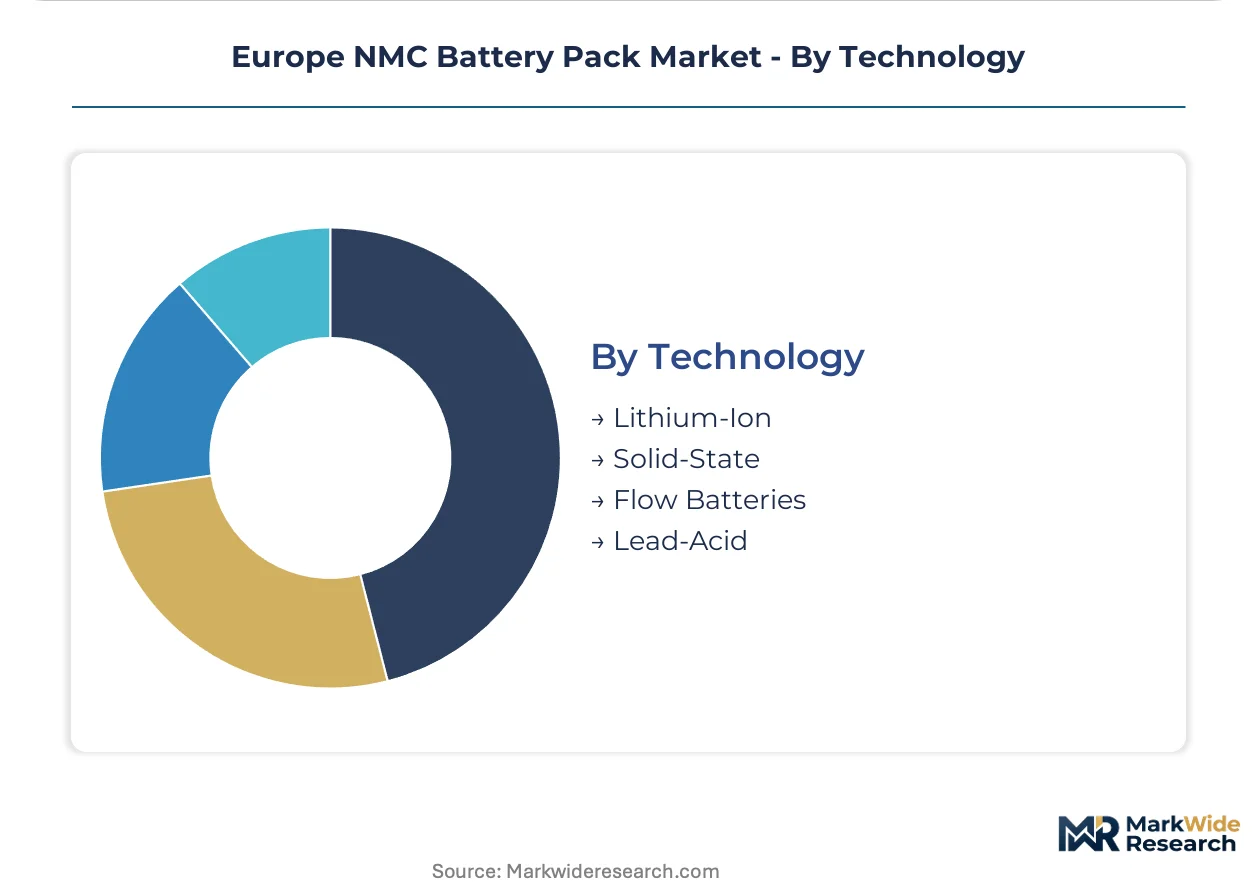
R&D allocation concentrates on solid-state pilot lines despite lithium-ion's continued commercial dominance, creating a pre-commercial investment gap.
- Lithium-Ion:Layered oxide cathodes with graphite or silicon-blend anodes deliver specific energies above 250 Wh per kilogram. High-nickel NMC formulations now expand into energy density benchmarks previously reserved for next-generation architectures.
- Solid-State:Sulfide electrolyte integration with high-nickel cathodes promises thermal runaway elimination. European research consortia face talent scarcity in solid-state interface engineering that constrains pilot line scale-up.
- Flow Batteries:Vanadium and zinc-bromide chemistries serve long-duration grid storage with decoupled power and energy scaling. NMC packs compete for shorter-duration applications where energy density outweighs cycle life.
- Lead-Acid:Mature technology retains cost advantage in backup power and starter applications. EU Battery Regulation recycling quotas and carbon footprint declarations disadvantage lead-acid against qualified lithium-ion supply chains.
Lithium-ion holds overwhelming installed base; solid-state is attracting disproportionate R&D commitment relative to near-term revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish nickel refining capacity anchors cathode active material supply for European cell producers. Arctic renewable corridors in Sweden and Norway enable carbon-neutral manufacturing claims under EU Battery Regulation tiering. Industrial clustering concentrates cell assembly and pack integration across Germany's automotive corridor.
Germany
Stuttgart and Wolfsburg anchor premium EV platform qualification for high-nickel NMC cathodes. KBA type-approval processes extend homologation timelines for novel cell formats entering OEM supply chains. Bavaria's research consortia concentrate solid-state electrolyte pilot development.
Sweden
Arctic hydropower access enables carbon-neutral cell production for EU Battery Regulation premium tiering. NorthVolt AB's localized manufacturing exemplifies supply chain reconfiguration under recycled content mandates. Västerås and Skellefteå host concentrated cathode precursor refining and cell assembly operations.
France
ANSM-aligned environmental standards govern cobalt sourcing disclosure for battery pack market access. Renault's captive supply relationships consolidate procurement under direct OEM-cell producer contracting. Dunkirk and Douai industrial zones concentrate gigafactory development along the English Channel logistics corridor.
Poland
Lower manufacturing cost bases attract cell producer capacity expansion serving German OEM demand. EU cohesion funding accelerates recycling infrastructure buildout for end-of-life pack processing. Lower Silesia's industrial zones host emerging cathode active material precursor facilities.
Finland
Nordic refined nickel streams pre-qualify under ECHA REACH due diligence frameworks for cathode procurement. Terrafame and other mining-refining integrated operations supply EU-certified material streams. Finnish Lapland's energy-intensive refining clusters leverage renewable baseload for carbon footprint declarations.
Europe NMC Battery Pack Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue localized European production under EU Battery Regulation compliance frameworks. Korean and Chinese cell producers anchor supply relationships with German OEMs through dedicated capacity agreements. Three archetypes dominate: integrated mining-refining-cell producers, pure-play cell specialists, and OEM-captive joint ventures. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure qualified supplier status.
Among Asian-headquartered cell producers, Contemporary Amperex Technology Co Ltd, LG Energy Solution Ltd, and Samsung SDI Co Ltd occupy positions across the premium and standard tiers. These companies exemplify the scale-driven archetype serving European automotive OEM demand through direct contracting structures. NorthVolt AB represents the emerging localized production vector, anchoring Swedish manufacturing capacity for EU regulatory premium tiering.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co Ltd (CATL) |
| LG Energy Solution Ltd |
| Samsung SDI Co Ltd |
| SAIC Volkswagen Power Battery Co Ltd |
| Groupe Renault |
| NorthVolt AB |
| Panasonic Holdings Corporation |
| SK Innovation Co Ltd |
| Deutsche ACCUmotive GmbH & Co KG |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers and OEM-captive joint ventures dominate European cathode active material procurement, compressing margin flexibility for independent cell assemblers while enforcing long-term offtake discipline across German and Swedish production corridors. This ownership concentration tightens pricing power at the refining tier and propagates cost pass-through obligations downstream to pack integrators under EU Battery Regulation compliance frameworks.
Pricing Analysis
Volume-scale automotive contracts capture margin at the premium tier while spot-market exposure erodes returns for smaller stationary storage integrators. Three-tier pricing structure across premium, standard, and economy levels separates KBA-qualified automotive supply from containerized grid systems and aftermarket replacement channels. Cost compression in standard-tier cells is intensifying because REACH-compliant cobalt sourcing adds qualification overhead. Utilities exhibit highest price sensitivity due to procurement framework standardization, whereas Stuttgart-based OEMs prioritize energy density performance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Volkswagen and BMW force cathode precursor qualification across Finnish and Nordic refined material streams, eliminating single-origin dependencies. Geographic supply concentration centers on China for processed cathode materials, South Korea for cell manufacturing equipment, and Finland for nickel refining. Raw material dependencies rest on cobalt hydroxide from DRC-certified smelters, lithium carbonate from South American salares, and high-purity nickel from Arctic refining corridors. Single-source vulnerability concentrates in sulfide electrolyte precursors for solid-state pilot lines. Distribution runs through direct OEM contracting structures that bypass traditional tier-one battery system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-nickel cathode chemistries are displacing legacy NMC 622 formulations across European automotive platforms, compressing qualification timelines for incumbent producers while opening white-space for localized cell manufacturing under carbon footprint tiering rules.
For Market Incumbents: Lock in captive refining relationships with Finnish nickel producers to secure REACH-compliant material streams ahead of recycled content mandate enforcement. Accelerate silicon-blend anode qualification through Bavarian research consortia to defend energy density positioning against solid-state substitute threats. Prioritize KBA type-approval pre-certification for novel cell formats to compress German OEM platform integration cycles. For New Entrants and Emerging Players: Capture Swedish gigafactory capacity allocations under Arctic renewable energy access for EU Battery Regulation premium tiering. Target Polish industrial zones for cathode precursor facilities serving German OEM demand through lower manufacturing cost bases. Pursue second-life stationary storage partnerships with French utilities as a go-to-market angle bypassing direct automotive qualification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated mining-refining specialists in Finnish Lapland with EU-certified cobalt and nickel streams. Long-term viability over the next decade hinges on vertical positioning at the cathode active material tier rather than pack assembly. Watch solid-state electrolyte pilot line scale-up announcements as the inflection signal for next-generation traction chemistry displacement.| Strategic Initiative | Industry Significance |
|---|---|
| High-Nickel Cathode Capacity Expansion | Enables NMC 811 qualification for 800-volt architectures at Stuttgart-based OEMs. |
| Arctic Renewable Energy Integration | Secures carbon-neutral manufacturing claims under EU Battery Regulation tiering for Swedish producers. |
| REACH-Compliant Refining Partnership | Locks in Finnish nickel streams pre-qualified under ECHA due diligence frameworks. |
| Solid-State Pilot Line Investment | Builds sulfide electrolyte expertise ahead of thermal runaway elimination benchmarks. |
| Second-Life Storage Joint Venture | Opens circular revenue streams under French extended producer responsibility mandates. |
Research Methodology
Multi-period observation of cathode chemistry patent filings, ECHA REACH enforcement patterns, and gigafactory capacity announcements anchored the trend analysis, supplemented by interviews with cell production engineers at European research consortia, procurement directors at German automotive OEMs, regulatory affairs specialists tracking EU Battery Regulation implementation, and recycling infrastructure planners in Poland and France. Secondary validation drew from EU customs trade databases, ECHA substance registration disclosures, national renewable integration target filings, and KBA type-approval registries. Bottom-up cell production capacity estimates triangulated against top-down automotive platform electrification forecasts.
Segment-weighting across product type, application, and technology dimensions calibrated value and volume outputs over the projection horizon. The analytical framework modeled automotive traction, stationary storage, and industrial power applications separately, with cross-segment allocation for second-life repurposing flows. CAGRs derived from regression against EV platform launch schedules and grid-scale deployment obligations. Industry-specific forecast inputs included silicon-blend anode adoption curves and solid-state pilot line capital commitment trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state commercialization timelines and DRC cobalt supply disruptions. Forecasts reflect documented assumptions on EU Battery Regulation enforcement intensity and Nordic renewable energy cost curves. Deviation in sulfide electrolyte interface engineering breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market