
 EV Charging Kiosk Market | 2026-2036
EV Charging Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Kiosk Market Foresight
Bi-directional charging integration is rewriting how EV charging kiosks interface with grid infrastructure and vehicle battery systems. ABB leverages its power electronics heritage to dominate high-capacity DC hardware for commercial deployment. Tesla sustains proprietary connector standards and supercharger network density as a competitive moat. ChargePoint anchors its position through software-agnostic roaming agreements that span multiple utility territories.
An EV charging kiosk is a self-service terminal that delivers controlled electrical energy to battery electric vehicles, typically incorporating power conversion modules rated from 7 kW AC to 350 kW DC, payment interfaces, and network connectivity for remote monitoring and load management. DC Fast Chargers command the steepest capital investment but capture premium utilization rates along interstate corridors and fleet depots where dwell time minimization drives purchasing decisions. Smart Chargers represent the fastest-expanding product category as utilities and operators prioritize demand-response capability and dynamic pricing integration. Wireless Chargers remain confined to premium pilot deployments where inductive pad installation costs can be amortized across high-value autonomous or fleet applications.
NHTSA vehicle safety standards and EPA emissions frameworks in the United States compel fleet operators to electrify, directly expanding addressable demand for kiosk infrastructure. FCC certification requirements govern wireless communication modules embedded in networked charging units, creating compliance barriers for hardware entrants. Municipalities and commercial fleet managers must monitor evolving interoperability mandates from ISO and IEC standards bodies that threaten to obsolete proprietary connector ecosystems and reshape procurement criteria across the installed base.
Market Dynamics
Bi-directional power flow protocols are forcing kiosk manufacturers to redesign hardware architectures around vehicle-to-grid interoperability rather than unidirectional charging alone. This shift compresses development cycles and elevates software competency above pure power electronics expertise.
Growth Catalysts
- NHTSA fleet electrification mandates:Commercial operators in the United States face binding tailpipe reduction schedules that necessitate depot charging infrastructure at scale.
- California municipal zoning codes:New commercial developments in Los Angeles, San Francisco, and San Diego corridors must install EV-ready electrical capacity as a condition of permitting approval.
- Dynamic pricing algorithms:Utility demand-response programs reward kiosk operators who modulate charge rates based on real-time grid congestion signals.
Market Restraints
- Copper and silicon carbide supply concentration:Power module substrates depend on processing capacity concentrated in East Asian foundries, exposing hardware margins to input volatility.
- Proprietary connector lock-in:Tesla's North American Charging Standard creates interoperability friction for non-Tesla vehicle owners at third-party kiosks.
- FCC certification timelines:Wireless communication modules embedded in networked units face 6-12 month approval queues that delay product launches.
Strategic Opportunities
- Autonomous fleet depots:Driverless commercial vehicles require unattended charging infrastructure where wireless inductive pads eliminate connector wear.
- ISO 15118-20 protocol adoption:The updated standard enables plug-and-charge authentication and bi-directional communication, opening premium service tiers.
- Rural interstate corridors:Federal infrastructure funding targets charging deserts along highways connecting secondary cities with insufficient existing coverage.
Industry Challenges
- Power electronics engineering scarcity:Kiosk manufacturers compete for talent capable of designing 350 kW DC conversion architectures with thermal management expertise.
- Legacy electrical infrastructure retrofitting:Older commercial properties require service upgrades to support high-capacity kiosk clusters, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Kiosk Market |
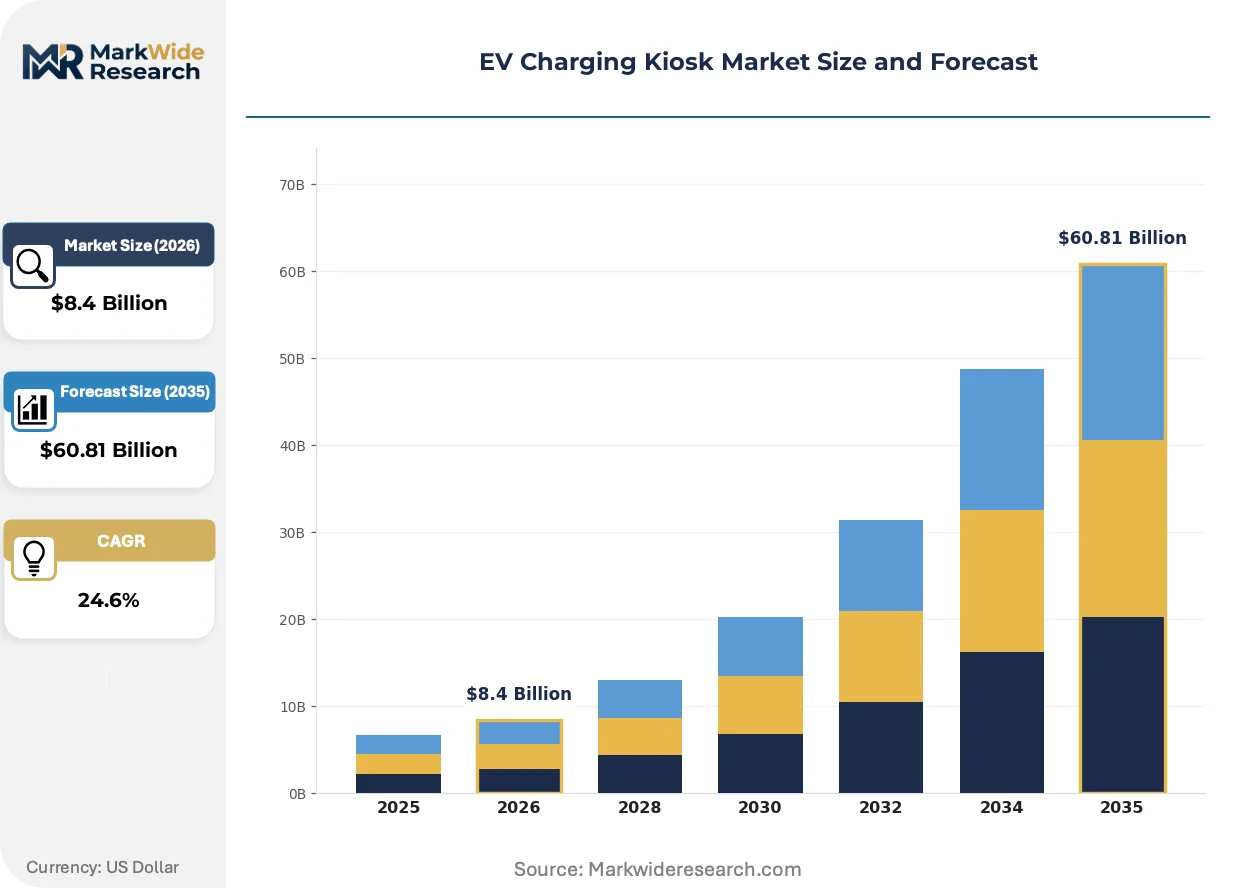
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Smart Chargers Installation Type: On-Site, Off-Site, Public Charging, Private Charging End User: Retail Locations, Commercial Fleets, Municipalities, Residential Areas Charging Speed: Level 1, Level 2, Ultra-Fast, Quick Charge |
| Companies Covered | ChargePoint, ABB, EVBox, Tesla, Wallbox, Eaton, Blink Charging, EVgo, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Kiosk Market Shifts & Advancements
Software-defined charging architectures are displacing fixed-function hardware as the primary value creation layer in kiosk systems. Operators now monetize energy management services rather than electron delivery alone.
Cloud-native load balancing platforms are digitizing how kiosk networks coordinate with utility dispatch systems. Fleet operators in California and Texas deploy these systems to arbitrage time-of-use rates. The technology is digitizing revenue models from per-kWh transactions toward grid services contracts.
EPA tailpipe regulations finalized under the Clean Air Act compel medium-duty fleet electrification by 2032. Equipment lessors and municipal procurement offices accelerate kiosk deployment timelines to meet compliance windows. California Air Resources Board enforcement mechanisms create binding demand visibility unmatched in other states.
Fleet managers increasingly bundle charging infrastructure into vehicle procurement decisions rather than treating kiosks as separate capital projects. Large logistics operators in the United States negotiate turnkey electrification packages with OEMs and infrastructure providers. This consolidation concentrates purchasing power among buyers with multi-thousand vehicle deployment scopes.
EV Charging Kiosk Market Segmentation
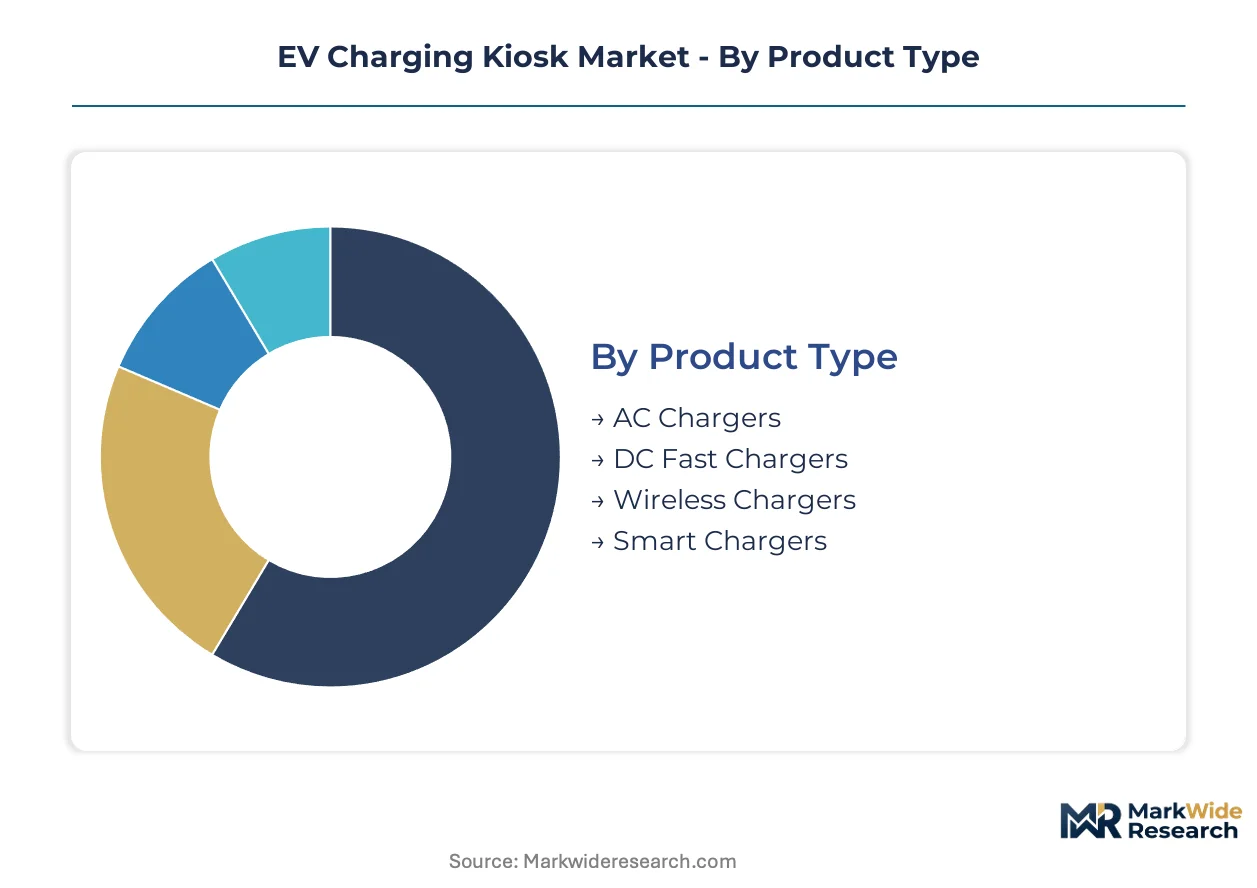
Segmentation in the EV charging kiosk market determines capital deployment efficiency and technology selection. Fleet operators prioritize DC fast charging for dwell time compression. Retail hosts favor AC units with integrated payment systems for customer retention.
Product Type:
Cost tier differentiation separates hardware categories by power electronics complexity and installation expenditure.
- AC Chargers:These units convert grid alternating current to vehicle-compatible power at 7-22 kW ratings through onboard vehicle rectifiers. Demand concentrates in workplace parking structures and multi-unit residential developments where overnight dwell times accommodate slower charge rates. Lower hardware costs and simplified electrical requirements accelerate deployment timelines.
- DC Fast Chargers:External rectification enables direct current delivery at 50-350 kW, bypassing vehicle onboard limitations. Interstate corridor operators and commercial fleet depots in California prioritize these units where charge completion within 20-30 minutes sustains vehicle utilization rates. Thermal management systems and liquid-cooled cable assemblies elevate capital intensity.
- Wireless Chargers:Inductive pad systems eliminate physical connectors through electromagnetic field coupling.
- Smart Chargers:Networked units with OCPP protocol compliance enable remote monitoring and dynamic load balancing.
AC Chargers command the established base. The steepest expansion runs through DC Fast Chargers.
Installation Type:
Application context determines site control, accessibility rules, and revenue model structure.
- On-Site:Property-attached installations at fleet depots, corporate campuses, and retail establishments where the host controls access and pricing. These deployments integrate with existing electrical infrastructure and building management systems.
- Off-Site:Standalone facilities on dedicated land parcels with grid-scale transformer capacity.
- Public Charging:Open-access installations along highways, municipal parking structures, and commercial districts serving mixed vehicle fleets. Municipal zoning mandates in Los Angeles and San Francisco corridors require these units in new commercial developments.
- Private Charging:Restricted-access deployments serving single-tenant fleets or residential associations.
Public Charging commands the established base. The steepest expansion runs through On-Site installations.
End User:
Customer type segmentation aligns procurement scale, utilization patterns, and service level requirements.
- Commercial Fleets:High-volume operators with centralized depot charging and predictable duty cycles. NHTSA tailpipe regulations compel medium-duty fleet electrification, binding procurement timelines to compliance windows. Large logistics operators negotiate turnkey electrification packages with infrastructure providers.
- Retail Locations:Shopping centers, convenience stores, and hospitality venues deploying chargers as customer acquisition tools. These hosts prioritize payment integration and dwell-time matching to transaction duration.
- Municipalities:Government-owned installations serving public transit, emergency services, and civic fleet operations.
- Residential Areas:Multi-unit dwelling installations and homeowner association deployments with shared infrastructure.
Retail Locations command the established base. The steepest expansion runs through Commercial Fleets.
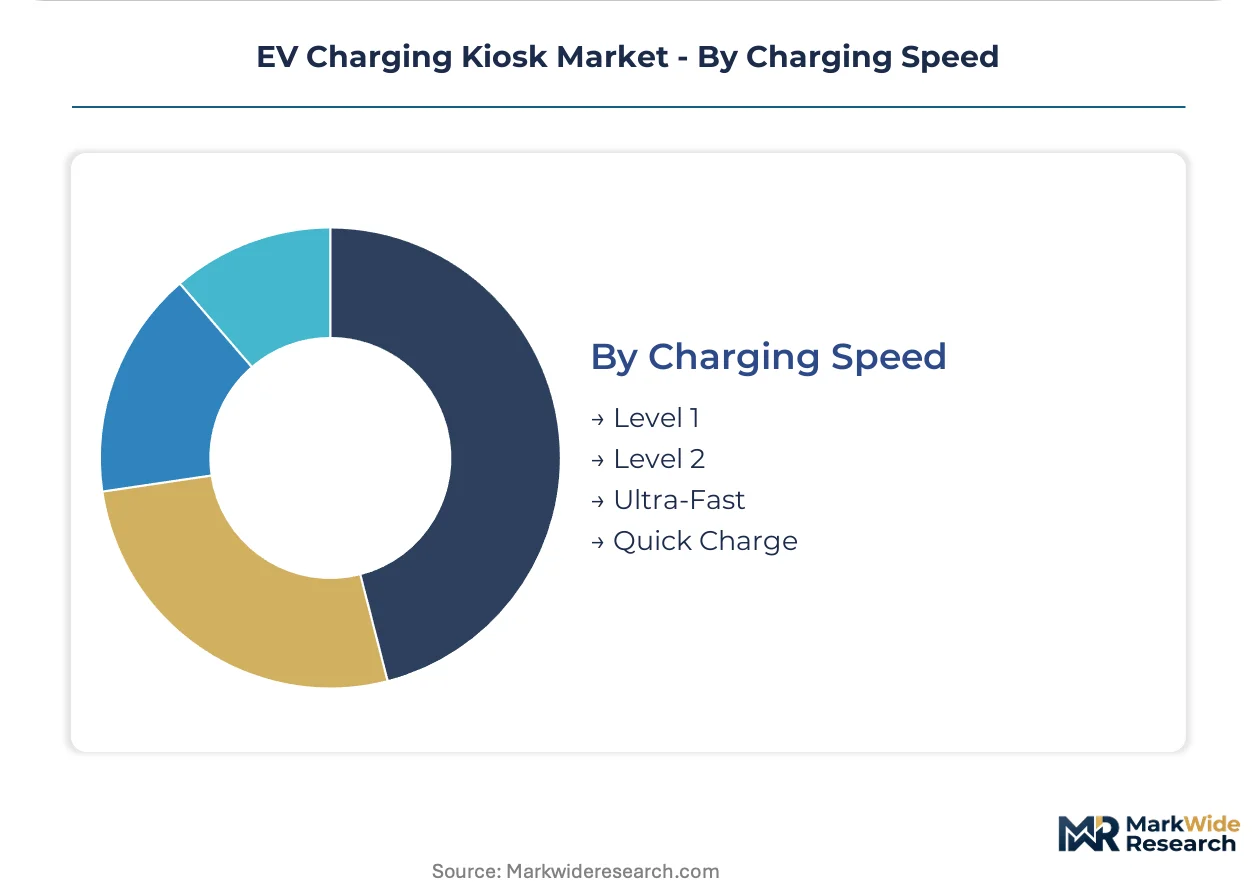
Charging Speed:
Volume throughput capacity segments hardware by power delivery rate and connector configuration.
- Level 1:Standard 120V residential outlet charging at 1-2 kW, suitable for overnight residential use with 8-12 hour charge windows. Minimal infrastructure requirements limit deployment to existing electrical access points.
- Level 2:240V alternating current delivery at 3-19 kW through dedicated circuit installation. Workplace and commercial parking operators favor these units for cost-balanced deployment across large parking inventories.
- Ultra-Fast:DC systems exceeding 150 kW with cooled cable assemblies and high-voltage architectures.
- Quick Charge:Mid-tier DC solutions in the 50-150 kW range serving secondary corridors and light commercial applications.
Level 2 commands the established base. The steepest expansion runs through Ultra-Fast systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and municipal buyers concentrate procurement power across urban corridors where electrification mandates bind deployment timelines. California's municipal zoning codes and Germany's federal infrastructure programs exemplify how regulatory frameworks reshape regional demand patterns. The analysis spans five countries where kiosk infrastructure investment aligns with binding fleet electrification schedules.
United States
Commercial fleet operators and retail hosts drive kiosk procurement across California, Texas, and Northeast corridor states. NHTSA tailpipe regulations compel medium-duty fleet electrification by 2032, binding infrastructure investment to compliance windows. Los Angeles and San Francisco municipal zoning mandates require EV-ready electrical capacity in new commercial developments, accelerating deployment density in urban cores.
Germany
Industrial fleet operators and highway corridor developers anchor demand for high-capacity DC infrastructure across Bavaria and North Rhine-Westphalia. The EU Green Deal and national fleet electrification targets mandate binding CO2 reduction schedules for commercial vehicles. Berlin-Brandenburg and Stuttgart metropolitan clusters concentrate manufacturing and logistics fleet conversion, driving depot charging investment at scale.
China
State-owned fleet operators and municipal transit agencies dominate procurement across Yangtze River Delta and Pearl River Delta manufacturing belts. MIIT new energy vehicle mandates and dual carbon goals impose binding electrification timelines on public and commercial fleets. Shenzhen and Shanghai lead urban deployment with integrated charging networks serving taxi and delivery fleet electrification.
United Kingdom
Corporate fleet managers and retail property developers drive installation across London-Southeast and Midlands logistics corridors. The country's national transport decarbonization strategy mandates phase-out dates for internal combustion commercial vehicles. Manchester and Birmingham urban clusters concentrate rapid charging hubs serving last-mile delivery electrification.
Japan
Automotive OEM-affiliated operators and convenience retail chains control deployment across Kanto and Kansai metropolitan regions. METI carbon neutrality roadmaps bind commercial fleet operators to electrification schedules aligned with 2050 targets. Tokyo-Osaka corridor infrastructure investment prioritizes highway fast-charging networks serving intercity commercial transport.
EV Charging Kiosk Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and network service layers. The vendor base organizes into three tiers: integrated platform operators managing end-to-end charging networks, power electronics specialists supplying conversion hardware, and software-agnostic connectivity providers enabling interoperability. Consolidation pressures intensify as fleet operators demand turnkey procurement packages spanning vehicles and infrastructure. Dominant competitive moves include strategic partnerships between automotive OEMs and charging network operators, plus vertical integration into power module manufacturing to secure silicon carbide supply.
Within the integrated platform tier, ChargePoint and ABB occupy positions exemplifying network-scale operators with software-agnostic roaming capabilities. Among hardware-focused specialists, Delta Electronics represents power electronics heritage applied to high-capacity DC conversion architectures. Tesla anchors the proprietary ecosystem archetype through connector standard control and captive network density.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| EVBox |
| Tesla |
| Wallbox |
| Eaton |
| Blink Charging |
| EVgo |
| Delta Electronics |
| Others |
Supply & Pricing Matrix
Copper and silicon carbide feedstock volatility compresses hardware margins across charging kiosk tiers while simultaneously accelerating contract indexation clauses that tie equipment pricing to London Metal Exchange benchmarks and semiconductor foundry utilization rates. This input-cost exposure widens spreads between premium DC fast-charging systems and economy-grade AC units as manufacturers pass through raw material escalations differentially based on power electronics complexity.
Pricing Analysis
Cost-plus contracts with LME copper indexation dominate procurement agreements between fleet operators and kiosk manufacturers, creating transparent pass-through mechanisms for substrate cost swings. Price differentiation rests on thermal management sophistication and ISO 15118-20 certification tier, with bi-directional capable units commanding substantial premiums over unidirectional hardware. Pricing pressure stems from silicon carbide MOSFET supply constraints that elevate power module costs, particularly affecting 350 kW DC architectures. Commercial fleet buyers exhibit highest price sensitivity due to volume procurement scales, while autonomous fleet developers prioritize reliability metrics over per-unit economics.
Supply Chain Analysis
High-purity copper cathode and silicon carbide wafer feedstocks anchor upstream procurement, with processing capacity concentrated in Chinese smelters and Taiwanese foundries. Power module assembly draws from South Korean packaging facilities and Japanese substrate specialists, creating multi-node dependency chains. Single-source vulnerability concentrates in 650V and 1200V silicon carbide device supply where Wolfspeed, Infineon, and STMicroelectronics control qualified automotive-grade output. Distribution runs through Tier 1 electrical distributors serving commercial construction and industrial automation channels, with direct OEM relationships emerging for fleet-scale deployments exceeding 500-unit volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across connector standards, software protocols, and regional certification requirements creates specialist opportunities as fleet electrification mandates outpace integrated platform coverage. The divergence between Tesla's North American Charging Standard and ISO/IEC harmonization timelines generates white-space for interoperability-focused entrants.
For Market Incumbents: Build certification moats around ISO 15118-20 plug-and-charge compliance and UL 2594 safety listings to defend against low-cost Asian hardware encroachment. Secure captive silicon carbide supply through multi-year foundry offtake agreements with Taiwanese power semiconductor specialists. Expand service revenue attachment rates via cloud-native load management platforms that monetize grid services beyond electron delivery. For New Entrants and Emerging Players: Rural interstate corridors between secondary cities offer underpenetrated deployment zones where federal infrastructure funding reduces site acquisition risk. Target municipal procurement offices in Midwestern states lacking California-style zoning mandates but facing NHTSA fleet electrification deadlines. Pursue hardware-agnostic software licensing models that enable rapid network integration without proprietary connector development costs. For Investors and Strategic Acquirers: NHTSA medium-duty fleet electrification mandates reshaping the acquisition landscape toward depot-charging specialists with proven thermal management IP and utility interconnection expertise. Long-term viability centers on software-defined architectures capable of bi-directional grid services monetization rather than commodity hardware margins. Watch for ISO 15118-20 protocol adoption velocity as the signal distinguishing premium acquisition targets from stranded proprietary ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Captive wafer access insulates margins against foundry utilization spikes at Taiwanese specialists. |
| ISO 15118-20 Certification Pathway | Plug-and-charge compliance unlocks premium fleet contracts requiring automated authentication. |
| Cloud-Native Load Management Platform | Demand-response integration with FERC-jurisdictional utilities creates recurring grid services revenue. |
| Bi-Directional Hardware Architecture | Vehicle-to-grid capability addresses California SGIP incentive eligibility and peak shaving applications. |
| Rural Corridor Deployment Partnership | Federal infrastructure funding access reduces site development risk in charging deserts. |
Research Methodology
A spread of perspectives from fleet operations directors, utility demand-response program managers, municipal zoning officials, and power electronics procurement leads converged on the working assumptions underlying kiosk deployment trajectories. Primary field engagement with California Air Resources Board compliance officers and NHTSA regulatory staff supplemented hardware manufacturer interviews across ABB, Delta Electronics, and ChargePoint engineering divisions. Secondary validation drew from EPA tailpipe regulation filings, FCC equipment authorization databases, and ISO/IEC standards committee documentation. Bottom-up unit economics modeling triangulated against top-down infrastructure investment forecasts from federal appropriations tracking.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with fleet electrification mandates driving demand-side constraints and silicon carbide foundry capacity governing supply-side ceilings. Segmentation dimensions spanned charging speed tier, installation context, and end-user procurement scale, with bi-directional capability adoption treated as a cross-cutting technology inflection. CAGRs derived from logistic diffusion curves fitted to historical EV penetration rates by vehicle class, moderated by electrical infrastructure upgrade timelines and utility interconnection queue depths.
Practitioners should monitor NHTSA rulemaking dockets and California Air Resources Board enforcement calendar revisions for early signals of compliance timeline acceleration or relaxation. Cross-checking against DOE Alternative Fuels Data Center station counts and utility interconnection filing volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market