
 Europe Electric Vehicle Battery Anode Market | 2026-2036
Europe Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Anode Market Insights
High-purity synthetic graphite specifications is bifurcating the competitive landscape into cost-optimized and performance-differentiated tiers. Talga Group leverages vertically integrated mine-to-anode operations in Sweden to secure feedstock control. Stora Enso anchors its position through lignin-derived hard carbon innovations sourced from Nordic forestry streams. BTR New Material Group Co. extends its manufacturing scale across European joint ventures to compete on volume delivery.
Europe electric vehicle battery anodes comprise the negative electrode materials within lithium-ion cells, typically engineered from carbonaceous substrates with intercalation potentials near 0.1 V versus Li/Li+ and reversible capacities spanning 340–360 mAh/g for graphite grades. These materials enable electron flow during discharge cycles while maintaining structural stability across thousands of charge events, serving as the foundational ion-storage medium in automotive traction batteries. Graphite formulations currently dominate installed capacity, though silicon-blend architectures represent the fastest-expanding technology segment as energy density targets tighten. Among end users, automakers directly specify anode chemistries through cell supply agreements, while tier-1 suppliers occupy margin pools by integrating anode coatings into module assembly workflows.
The EU Battery Regulation and ECHA REACH framework govern carbon footprint reporting, recycled content mandates, and substance restrictions across anode supply chains entering European assembly plants. EMA and national regulators coordinate safety assessments for novel silicon-dominant chemistries exceeding traditional graphite thermal stability thresholds. Stakeholders must monitor how delegated acts under the EU Battery Regulation redefine recyclability quotas and whether domestic precursor processing investments keep pace with cell factory ramp schedules.
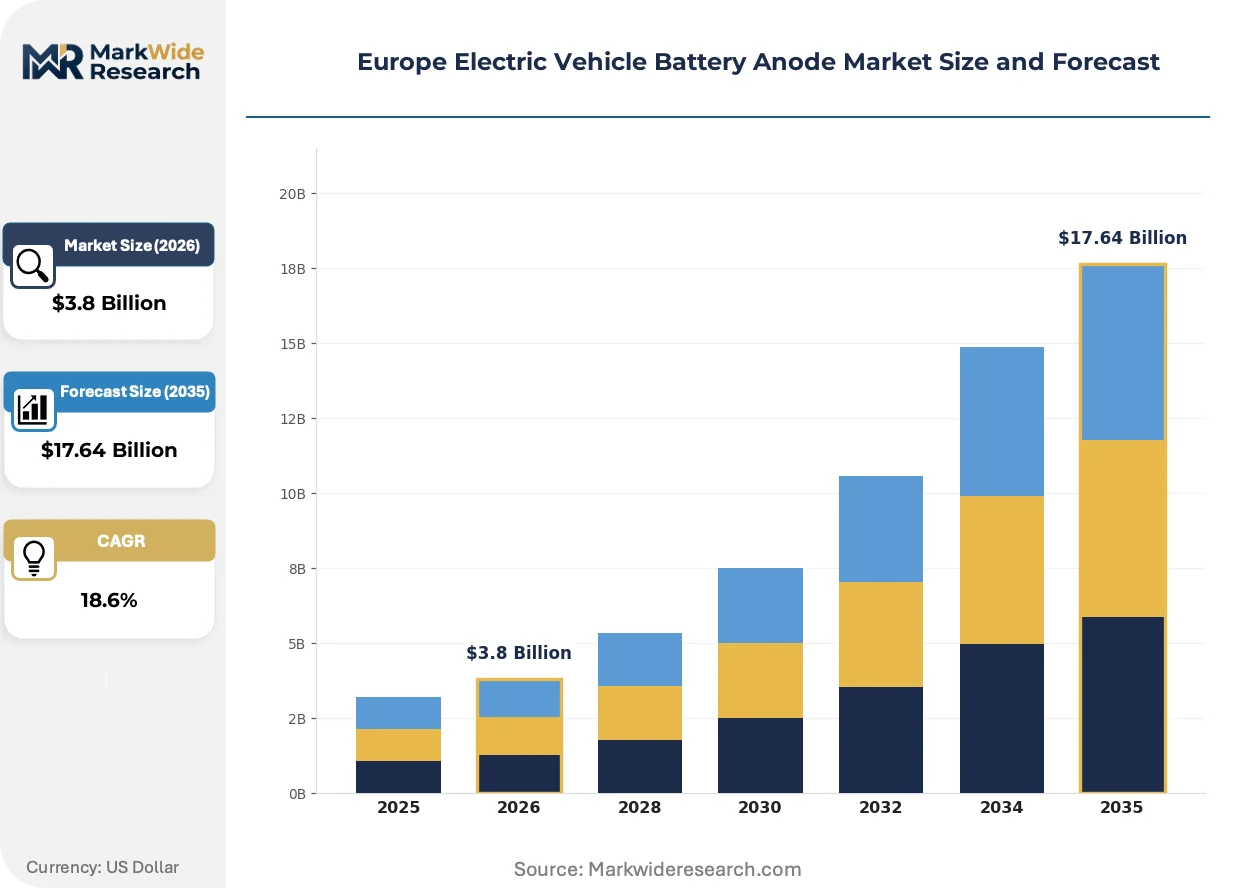
Market Dynamics
Silicon-graphite composite architectures are compressing incumbent graphite margins while EU Battery Regulation carbon footprint mandates reconfigure feedstock sourcing priorities across European cell production networks.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Delegated acts under the framework establish binding thresholds for recovered lithium, cobalt, and nickel in anode precursor streams, compelling gigafactory offtake agreements with European recyclers.
- German automotive OEM platform specifications:Premium EV architectures from Stuttgart-based manufacturers now require silicon-blend anodes exceeding 400 mAh/g reversible capacity, pulling Korean and Chinese material suppliers into joint venture structures.
- Hard carbon from Nordic forestry residues:Lignin-derived anode materials sourced from Finnish and Swedish pulp operations qualify for EU Green Deal taxonomy alignment, attracting sustainability-linked financing for capacity scale-up.
Market Restraints
- Synthetic graphite feedstock concentration:Petroleum needle coke supply for high-purity anode grades concentrates among Chinese calcination facilities, exposing European anode coaters to export license volatility and carbon border adjustment cost pass-through.
- Silicon expansion degradation:Volume swelling exceeding 300% during lithiation cycles limits silicon content in commercial automotive cells to sub-10% blends, constraining energy density gains promised by silicon-dominant architectures.
- ECHA REACH authorization bottlenecks:Novel nano-structured carbon additives face extended substance evaluation timelines, delaying qualification for high-volume automotive contracts by 18-24 months relative to incumbent graphite benchmarks.
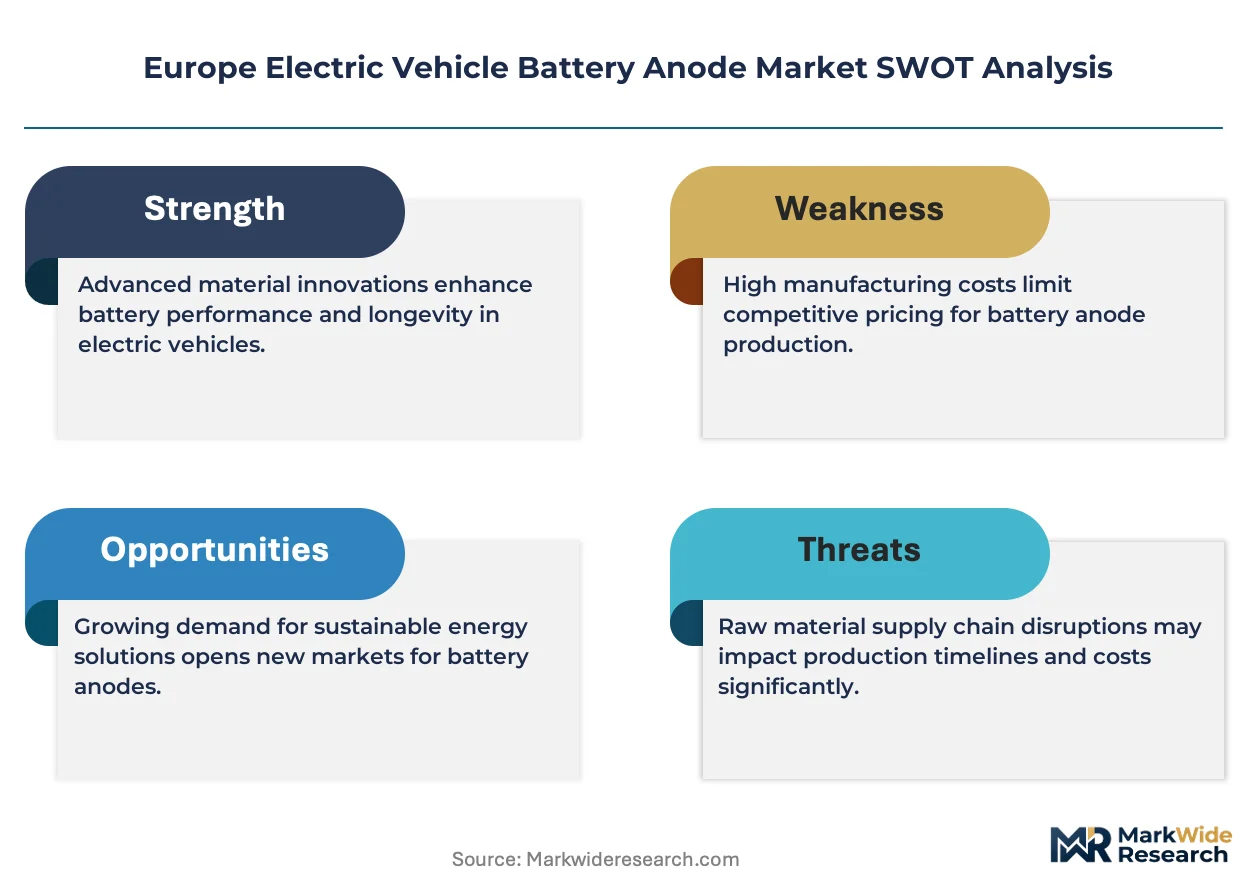
Strategic Opportunities
- Polish and Hungarian cell factory clusters:Greenfield gigafactory investments around Wrocław and Debrecen lack qualified regional anode coating capacity, creating first-mover positioning for precursor-to-coating integrated facilities.
- Pre-lithiation technology convergence:Integration of stabilized lithium metal powders with silicon-blend anodes enables compensation of initial cycle losses, opening premium pricing tiers for European suppliers mastering the stacking process.
- EU Critical Raw Materials Act domestic sourcing incentives:Strategic project status for European graphite mine developments in Finland and Portugal unlocks accelerated permitting and state aid compatibility for vertically integrated mine-to-anode operations.
Industry Challenges
- Electrode coating technician scarcity:Thin-film deposition expertise for sub-10 micrometer anode layers on copper foil substrates concentrates among Asian equipment vendors, forcing European coaters to import process engineering talent or accept yield penalties during technology transfer.
- Cell-to-pack thermal runaway certification:EMA safety assessments for silicon-rich anodes exhibiting lower thermal onset temperatures than graphite benchmarks extend validation timelines for new material introductions into automotive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Anode Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Ion, Graphite, Silicon, Hybrid End User: Automakers, Tier-1 Suppliers, Aftermarket Providers, OEMs Technology: Surface Coating, 3D Structuring, Composite Materials, Recycling Techniques Application: Passenger Vehicles, Commercial Vehicles, Buses, Two-Wheelers |
| Companies Covered | Talga Group, Stora Enso, BTR New Material Group Co., EVE Energy, AnteoTech, Novacium SAS, NEO Battery Materials Ltd, CATL, ProLogium Technology Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Anode Market Trends and Innovations
Anode material innovation is bifurcating between cost-optimized graphite grades for mass-market EVs and performance-differentiated silicon architectures for premium platforms, with regulatory carbon accounting now embedded in supplier qualification workflows.
Silicon-graphite composite formulations are fragmenting the technical specifications landscape across European cell manufacturers. These blends intercalate lithium ions through both graphite interlayer spacing and silicon alloy mechanisms, delivering 15-20% energy density improvements over pure graphite. BMW and Volkswagen procurement teams now specify silicon content minimums in cell supply agreements, compressing qualification timelines for incumbent graphite-only suppliers. The technology is fragmenting established supply relationships as Korean cathode-anode integrated producers capture premium platform contracts previously held by specialized graphite coaters.
The EU Battery Regulation's carbon footprint declaration requirements are reshaping anode supply chain documentation obligations. Cell manufacturers must now disclose cradle-to-gate emissions per kWh for anode active materials, with delegated acts phasing in maximum thresholds from 2027. European anode coaters lacking renewable electricity procurement or recycled feedstock integration face margin compression against Swedish and Norwegian competitors with hydro-powered operations. German automotive OEMs are responding by inserting carbon intensity clauses into multi-year offtake agreements, effectively screening out Chinese synthetic graphite with coal-based calcination energy profiles.
Automotive cell procurement is consolidating around direct material partnerships rather than tier-1 module supplier intermediation. OEM technical teams now specify anode chemistry, coating thickness, and binder systems in cell supply contracts, disintermediating traditional battery system integrators. This pattern concentrates in German premium EV platforms where range and charging performance specifications override cost minimization priorities. The shift is most visible in Stuttgart and Munich, where Mercedes-Benz and BMW have established dedicated cell engineering centers with direct anode material qualification capabilities.
Europe Electric Vehicle Battery Anode Market Segmentation
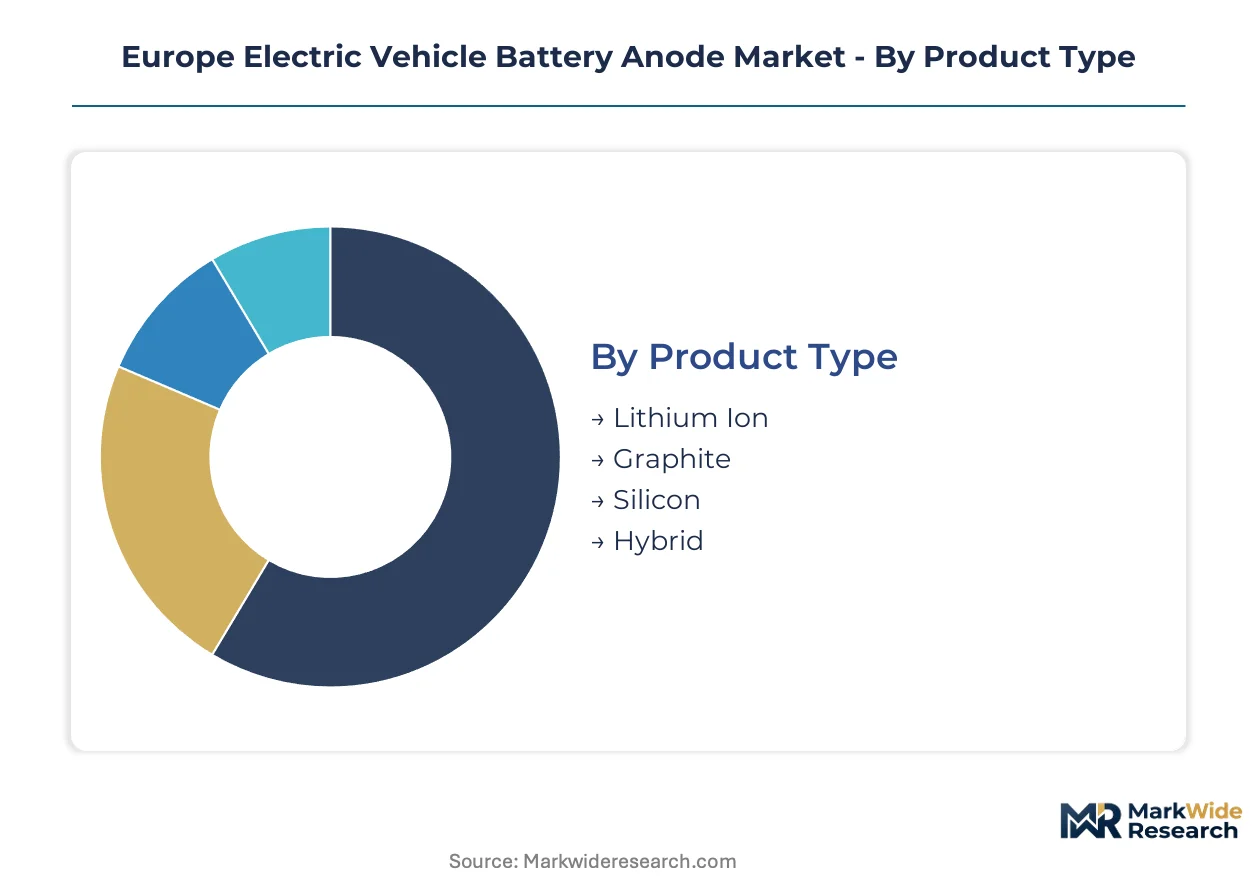
Anode procurement patterns diverge sharply between German premium EV platforms demanding silicon-graphite performance and Central European volume manufacturing optimizing for graphite cost efficiency. Segmentation reveals how EU Battery Regulation carbon accounting and cell factory geography reshape supplier qualification workflows across material categories.
Product Type:
Domestic production concentrates in Swedish synthetic graphite and Finnish hard carbon from forestry residues, while silicon precursors and hybrid formulations rely heavily on Asian import streams.
- Graphite:Synthetic and natural grades processed to 99.95% purity specifications dominate current European cell capacity. German automakers specify Swedish-mined flake graphite for premium platforms, though petroleum needle coke calcination remains concentrated in Chinese facilities.
- Silicon:Nano-structured silicon powders and silicon monoxide composites enable 400+ mAh/g reversible capacities. BMW and Volkswagen procurement teams now mandate minimum silicon content thresholds, pulling Korean suppliers into joint venture structures with European coaters.
- Hybrid:Silicon-graphite blends balancing energy density with cycle stability attract sustainability-linked financing.
- Lithium Ion:Pre-lithiated anode architectures compensate initial capacity losses in high-nickel cathode cells.
Graphite holds the largest share; momentum sits with silicon.
End User:
Cost tiers separate direct OEM material specification from tier-1 supplier intermediation, with aftermarket channels capturing replacement demand for first-generation EV fleets.
- Automakers:Mercedes-Benz and BMW engineering centers in Stuttgart and Munich now specify anode chemistry, coating thickness, and binder systems directly in cell supply contracts. This disintermediation concentrates in premium platforms where range specifications override cost minimization.
- Tier-1 Suppliers:Battery system integrators occupy margin pools by combining anode coating with module assembly workflows. Continental and Bosch operations around Dresden and Nuremberg face compression as OEMs internalize material qualification capabilities.
- Aftermarket Providers:Independent repair networks source replacement cells for aging Nissan Leaf and Renault Zoe fleets.
- OEMs:Contract manufacturers for commercial vehicle platforms accept standardized graphite specifications.
Automakers command the value chain; tier-1 suppliers face margin compression fastest.
Technology:
Volume concentration favors surface coating infrastructure, while 3D structuring and recycling techniques remain pilot-scale with longer qualification timelines.
- Surface Coating:Carbon and ceramic coatings on graphite particles suppress electrolyte decomposition and extend cycle life. European coaters around Dresden and Münster operate roll-to-roll equipment imported from Japanese vendors, though technician scarcity forces yield penalties during technology transfer.
- Recycling Techniques:Hydrometallurgical recovery of graphite and silicon from production scrap aligns with EU Battery Regulation recycled content mandates. Swedish and Finnish operations leverage hydro-powered facilities to meet carbon intensity clauses in German offtake agreements.
- 3D Structuring:Porous architectures accommodate silicon volume expansion.
- Composite Materials:Lignin-derived hard carbon from Nordic pulp streams qualifies for EU Green Deal taxonomy alignment.
Surface coating dominates installed equipment; recycling techniques climb fastest on regulatory pull.
Application:
Passenger vehicle platforms absorb capacity investments, with commercial vehicle and bus segments following distinct duty-cycle specifications.
- Passenger Vehicles:Premium sedans and SUVs from Stuttgart-based manufacturers drive silicon-graphite adoption. Range targets above 600 km necessitate energy densities that pure graphite cannot deliver, compressing qualification timelines for novel anode architectures.
- Commercial Vehicles:Heavy-duty trucks and vans prioritize cycle stability over energy density. Daimler Truck and Volvo Group specifications favor proven graphite formulations with decade-long durability validation.
- Buses:Municipal electrification programs in Warsaw and Budapest specify cost-optimized cells.
- Two-Wheelers:Micromobility fleets in Amsterdam and Copenhagen accept lower-grade natural graphite.
Passenger vehicles anchor demand; commercial vehicles offer steadiest contract visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's anode material trade flows reveal a structural deficit in synthetic graphite processing capacity against surging cell factory demand. Import dependence for petroleum needle coke calcination concentrates exposure in Chinese supply chains, while Nordic mining and forestry operations anchor emerging domestic feedstock alternatives.
Germany
Mercedes-Benz and BMW procurement teams in Stuttgart and Munich now specify silicon-graphite anode chemistries directly in cell supply contracts. The KBA coordinates EMA safety assessments for novel silicon-dominant architectures entering premium EV platforms. Cell gigafactories cluster around Dresden and Stuttgart, pulling Korean and Chinese material suppliers into joint venture structures to meet localized content requirements.
Sweden
Talga Group's vertically integrated mine-to-anode operations in Vittangi leverage hydro-powered processing to meet EU Battery Regulation carbon intensity clauses. The Swedish Mining Inspectorate accelerates permitting for strategic graphite developments under the EU Critical Raw Materials Act. Vittangi and Luleå host Europe's only vertically integrated natural graphite anode production, supplying German automakers with sub-5 kg CO2e per kWh material.
Finland
Stora Enso's lignin-derived hard carbon innovations from Kotka pulp operations qualify for EU Green Deal taxonomy alignment, attracting sustainability-linked financing. The Finnish Safety and Chemicals Agency enforces REACH compliance for novel carbon additives entering automotive supply chains. Anode precursor development concentrates in Kotka and Oulu, where forestry residue streams enable circular feedstock models distinct from petroleum-based synthetic graphite.
Poland
Greenfield gigafactory investments around Wrocław from LG Energy Solution and SK On lack qualified regional anode coating capacity, creating first-mover positioning gaps. The Polish Investment and Trade Agency administers state aid for precursor-to-coating integrated facilities under EU cohesion policy. Wrocław and Poznań cell factory clusters currently import coated anodes from Dresden and Münster, extending logistics costs and carbon footprint declarations.
France
Novacium SAS and emerging silicon precursor specialists in Grenoble anchor research corridors for next-generation anode architectures. ANSM coordinates with EMA on safety assessments for silicon-rich anodes exhibiting lower thermal onset temperatures than graphite benchmarks. The Auvergne-Rhône-Alpes region concentrates pilot-scale 3D structuring capabilities, though commercial coating scale remains concentrated in German and Swedish operations.
Europe Electric Vehicle Battery Anode Market Competitive Landscape
Concentration sits with Asian material suppliers possessing calcination and coating scale, while European players occupy niche positions in sustainable feedstock and silicon precursor innovation. The vendor base fragments across three tiers: integrated mine-to-anode operators with captive graphite deposits; forestry-derived hard carbon specialists leveraging EU Green Deal alignment; and Korean-Chinese joint ventures serving German OEM volume requirements. Dominant competitive moves include backward integration into Nordic mining assets and strategic partnerships to secure renewable electricity procurement for carbon-compliant production.
Within the integrated operator tier, Talga Group exemplifies vertically controlled supply from Swedish graphite deposits through hydro-powered processing. Stora Enso occupies a position among forestry-derived material innovators, converting lignin waste streams into hard carbon anode precursors. BTR New Material Group Co. represents the Asian-European joint venture archetype, extending manufacturing scale through European partnerships to compete on volume delivery to German cell factories.
| Leading Market Players |
|---|
| Talga Group |
| Stora Enso |
| BTR New Material Group Co. |
| EVE Energy |
| AnteoTech |
| Novacium SAS |
| NEO Battery Materials Ltd |
| CATL |
| ProLogium Technology Co. |
| Others |
Pricing and Supply Chain Analysis
Silicon-graphite composite displacement of pure graphite anodes is redrawing procurement economics and supplier geography across European cell production networks. German automotive OEMs now specify minimum silicon content thresholds in multi-year offtake agreements, compressing margins for incumbent graphite coaters while rewarding Korean and Chinese material suppliers with joint-venture access to Stuttgart and Munich engineering centers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for anode active materials, with three-tier pricing structure across premium, standard, and economy levels separating silicon-blend formulations from high-purity synthetic graphite and uncoated natural flake grades. Price differentiation rests on carbon intensity certification and coating thickness precision, with Swedish hydro-powered operations commanding premiums against Chinese coal-calcined synthetic graphite. Cost compression in standard-grade graphite is intensifying because petroleum needle coke supply concentrates among Chinese calcination facilities exposed to export license volatility. Tier-1 battery system integrators exhibit highest price sensitivity as OEMs disintermediate module suppliers, while premium platform engineering teams prioritize energy density specifications over unit cost minimization.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are extending lead times for coated anode deliveries to Polish and Hungarian cell factory clusters. Geographic supply concentration centers on China for petroleum needle coke calcination, South Korea for silicon precursor processing, and Sweden for natural graphite mining and coating. Raw material dependencies draw from Nordic forestry residues for lignin-derived hard carbon, Australian flake graphite feedstock, and metallurgical-grade silicon from hydro-powered smelters. Single-source vulnerability in Chinese needle coke calcination exposes European coaters to carbon border adjustment cost pass-through. Distribution runs through direct material partnerships with German OEM engineering centers, bypassing traditional tier-1 module supplier intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent graphite suppliers face a substitution defense against silicon-graphite composite architectures as BMW and Volkswagen procurement teams mandate minimum silicon content thresholds in cell supply agreements.
For Market Incumbents: Shield margin pools by securing backward integration into Nordic graphite mining assets under EU Critical Raw Materials Act strategic project status, and accelerate pre-lithiation technology qualification to offset initial cycle losses in high-nickel cathode configurations. Talga Group's vertically integrated mine-to-anode model in Vittangi demonstrates how captive feedstock control insulates against Chinese needle coke supply volatility. For New Entrants and Emerging Players: Anchor in the anode coating capacity gap around Wrocław and Debrecen, where LG Energy Solution and SK On gigafactories currently import coated anodes from Dresden and Münster. Target Polish and Hungarian state aid programs for precursor-to-coating integrated facilities, and qualify lignin-derived hard carbon formulations through Stora Enso's Kotka pulp operations to secure EU Green Deal taxonomy-aligned financing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European anode coaters lacking renewable electricity procurement or recycled feedstock integration, facing margin compression against Swedish and Norwegian hydro-powered competitors. Five-to-ten year viability hinges on carbon intensity clause compliance in German automotive offtake agreements. Watch for delegated acts under the EU Battery Regulation phasing in maximum cradle-to-gate emissions thresholds as the inflection indicator for stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Talga Group's Vittangi operations secure captive graphite feedstock under Swedish Mining Inspectorate accelerated permitting. |
| Joint Venture with Asian Material Suppliers | BTR New Material Group Co. extends manufacturing scale through European partnerships to meet German OEM volume requirements. |
| Green Manufacturing Transition | Stora Enso's Kotka lignin-derived hard carbon qualifies for EU Green Deal taxonomy alignment and sustainability-linked financing. |
| Pre-lithiation Technology Development | Integration of stabilized lithium metal powders with silicon-blend anodes enables premium pricing tiers for European suppliers. |
| Recycling Capacity Buildout | Swedish and Finnish hydrometallurgical operations meet EU Battery Regulation recycled content mandates for anode precursor streams. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cell factory procurement leads, OEM platform engineers, and anode coating operations managers; and secondary validation through ECHA REACH substance registrations, EU Battery Regulation delegated acts, and customs trade data for petroleum needle coke and coated anode imports. Bottom-up triangulation across cell factory capacity announcements and top-down demand modeling from German automotive production schedules were cross-referenced to establish volume estimates.
Across the analysis window, the forecasting framework segmented by material chemistry, end-user procurement tier, and coating technology infrastructure. CAGRs were derived from installed cell factory capacity ramp schedules and OEM platform electrification roadmaps, with silicon content penetration curves modeled against energy density requirements and cycle stability constraints.
Material uncertainties — EMA safety assessment timelines for silicon-rich anodes, Chinese export license volatility for needle coke, and delegated act thresholds for recycled content — sit outside the modeled envelope. Forecasts reflect documented assumptions about cell factory ramp schedules and OEM qualification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market