
 China SLI Battery Market | 2026-2036
China SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
China SLI Battery Market Insights
Battery lifecycle management services is recalibrating what Chinese manufacturers monetize beyond unit sales. Tianneng Battery Group Co. leverages its nationwide collection network to anchor aftermarket revenue streams. Contemporary Amperex Technology Co. Limited competes through R&D intensity in lithium-ion SLI alternatives. Chaowei Power dominates rural distribution channels for motorcycle and agricultural vehicle replacement demand.
China SLI (Starting, Lighting, Ignition) batteries are electrochemical storage devices engineered to deliver high cold-cranking amperage for internal combustion engine starting, with lead-acid chemistry employing pasted flat-plate or tubular positive electrodes in sulfuric acid electrolyte. The technology serves as the primary auxiliary power source for cranking torque, lighting circuits, and electronic control unit standby feed in vehicles. Lead-acid products occupy the mature volume tier with thin margin pools, while lithium-ion segments attract capital for energy density advantages in premium automotive applications. AGM technology leads replacement demand from stop-start vehicle parc growth, whereas flooded designs sustain economy-positioning in commercial trucking and marine auxiliary roles.
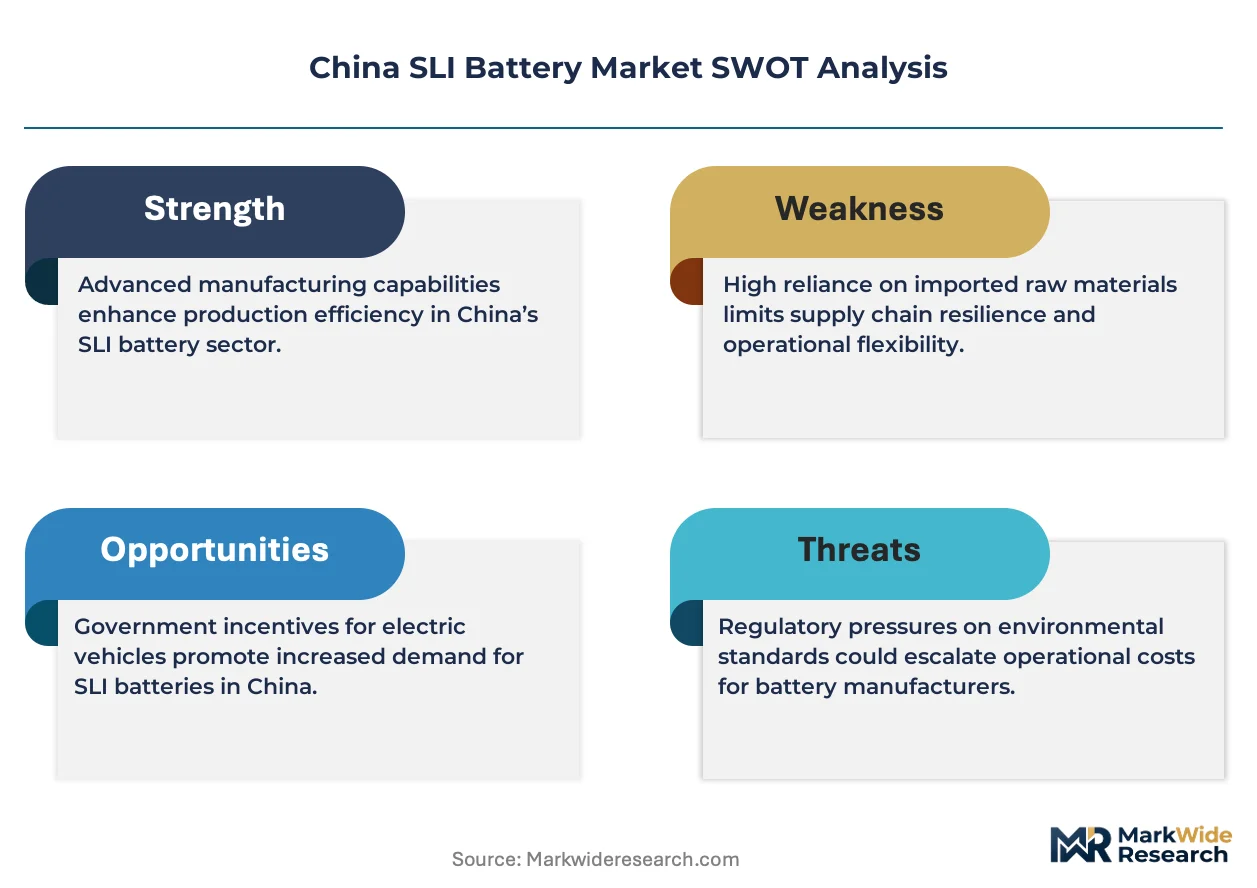
MIIT enforces GB/T standards for SLI battery capacity retention and cycle life verification, while SAMR administers market access certification that filters substandard producers from national supply chains. China's dual carbon goals are forcing lead-acid foundries to retrofit smelting emissions controls or consolidate capacity. Stakeholders must monitor how NMPA-aligned battery passport traceability requirements reshape recycling economics and OEM procurement qualification protocols.
Market Dynamics
MIIT's tightening GB/T standards for battery passport traceability are forcing lead-acid foundries to consolidate capacity or retrofit emissions controls, compressing margins while elevating compliance costs across the Yangtze River Delta manufacturing cluster.
Growth Catalysts
- Stop-start vehicle parc expansion:AGM technology demand from passenger vehicle OEMs is accelerating as domestic automakers scale micro-hybrid powertrain assembly lines across Jiangsu province.
- Dual carbon policy enforcement:MEE emissions mandates are filtering substandard smelters from national supply chains, creating qualified capacity scarcity that benefits compliant producers.
- Rural replacement cycles:Agricultural vehicle and motorcycle battery turnover in inland provinces sustains steady aftermarket volume independent of new vehicle sales volatility.
Market Restraints
- Lead price volatility:Raw material input costs for lead-acid chemistry fluctuate with LME pricing, squeezing thin margin pools in economy-tier flooded battery segments.
- Lithium-ion substitution pressure:Energy density advantages in premium automotive applications threaten SLI lead-acid's position in high-end passenger vehicle platforms.
- SAMR certification bottlenecks:Extended market access timelines for new production facilities delay capacity expansion responses to demand spikes.
Strategic Opportunities
- Battery lifecycle services:Nationwide collection network infrastructure enables aftermarket revenue streams through recycling economics and core exchange programs.
- Zhejiang port logistics integration:Export-oriented manufacturing clusters near Ningbo-Zhoushan port complex capture Southeast Asian replacement demand growth.
- GB/T 34014 compliance services:Technical consulting and testing certification for capacity retention verification creates B2B service revenue adjacent to unit sales.
Industry Challenges
- Smelter emissions retrofit capex:Legacy foundries face capital intensity requirements for MEE-compliant scrubber and wastewater systems without guaranteed capacity utilization recovery.
- Cross-provincial logistics coordination:Hazardous material transport regulations vary between Shanghai, Jiangsu, and Zhejiang jurisdictions, complicating integrated supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China SLI Battery Market |
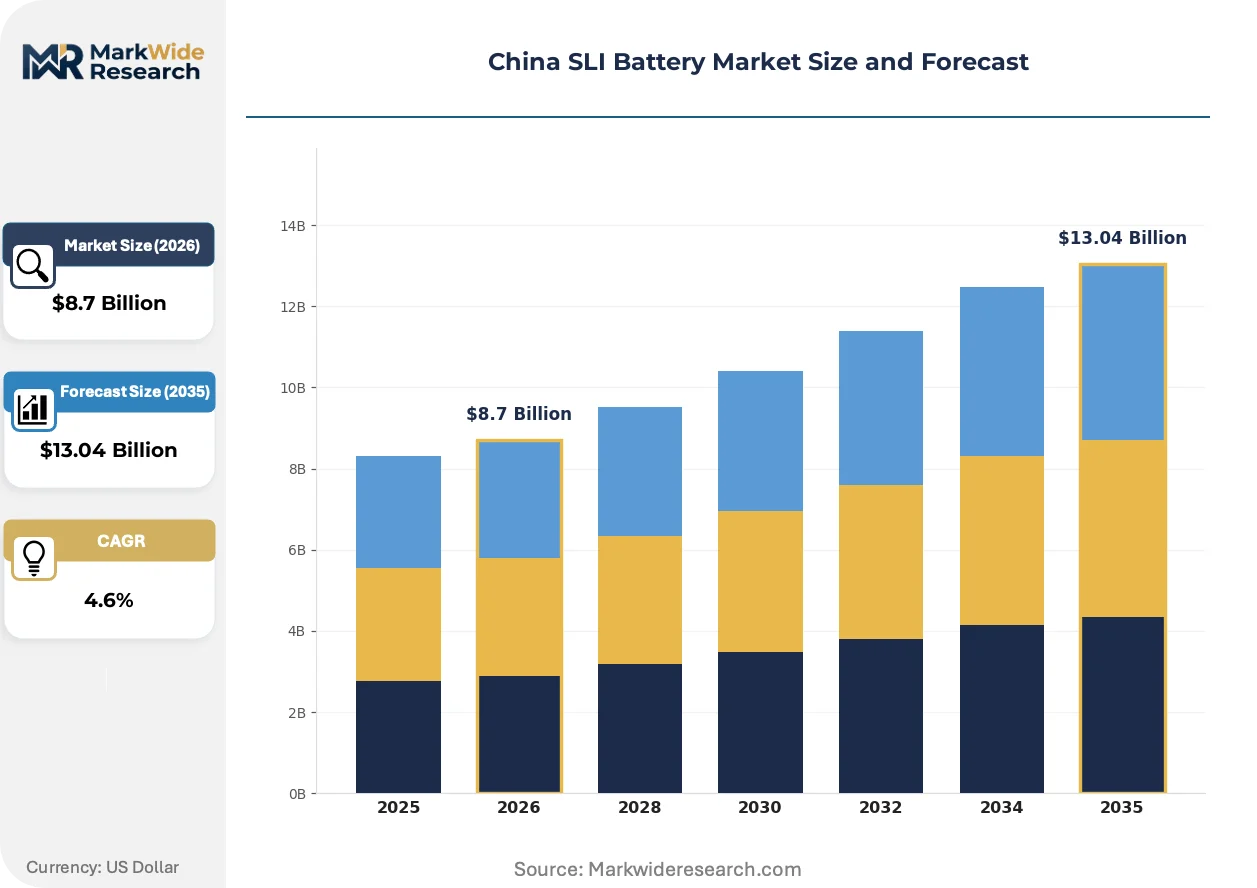
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Others End User: Automobile, Marine, Industrial, Motorcycle Technology: AGM, Flooded, Gel, Spiral Capacity: 45Ah, 60Ah, 75Ah, 100Ah |
| Companies Covered | Tianneng Battery Group Co., Leoch International Technology Limited, Contemporary Amperex Technology Co. Limited, Gotion Inc., GS Yuasa International Ltd, Camel Group, Chaowei Power, Fengfan, Exide Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China SLI Battery Market Trends and Innovations
Technology convergence between electrochemical storage and digital traceability systems is recalibrating how Chinese SLI battery manufacturers capture value beyond commodity unit sales.
AGM separator technology is overtaking flooded designs in stop-start vehicle applications due to superior cyclic durability under partial state-of-charge operation. Domestic passenger vehicle OEMs in the Yangtze River Delta are specifying AGM for 90% of new micro-hybrid platforms. This chemistry transition is compressing economy-tier flooded capacity while elevating qualified AGM separator supply scarcity.
MIIT's battery passport traceability mandate under GB/T 34014 is forcing producers to integrate blockchain-verified lifecycle data systems. SAMR market access certification now requires documented recycling chain-of-custody records. Premium automotive OEMs are qualifying suppliers exclusively on passport compliance readiness, filtering non-compliant foundries from tier-one procurement lists.
Aftermarket procurement is fragmenting from traditional distributor hierarchies toward direct-to-garage digital platforms. Independent repair shops in Guangdong and Shandong provinces now source replacement batteries through B2B e-commerce channels that bypass provincial distributor markups. This channel disintermediation compresses wholesale margin pools while shifting working capital requirements to manufacturer balance sheets.
China SLI Battery Market Segmentation
SLI battery procurement in China fragments across chemistry, application, and technical specifications that dictate margin structures. Manufacturers configure production lines around specific certification tiers rather than universal platforms.
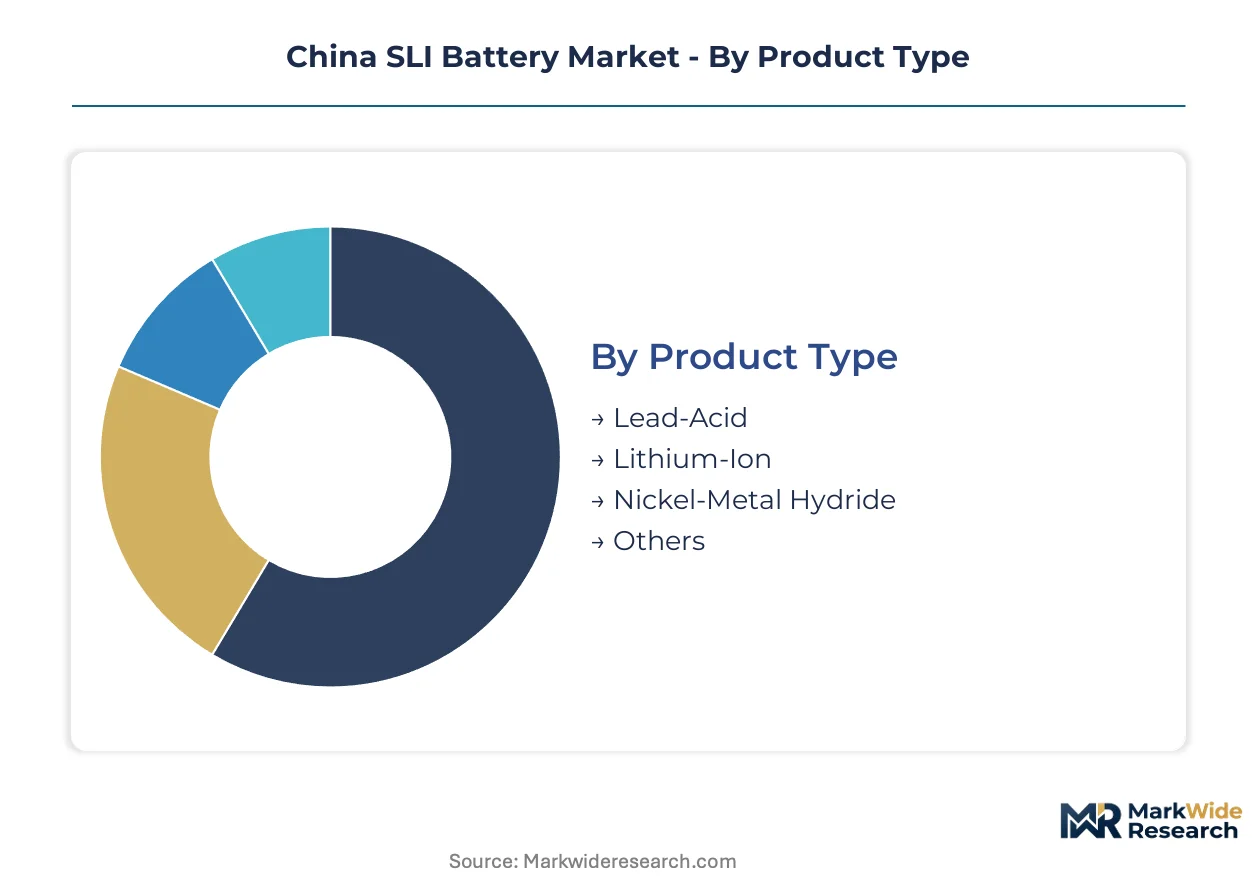
Product Type:
The customization-vs-standardization spectrum spans mature lead-acid commodity production at one extreme and lithium-ion precision manufacturing at the other.
- Lead-Acid:Pasted flat-plate and tubular positive electrode designs in sulfuric acid electrolyte deliver high cold-cranking amperage for internal combustion starting. Jiangsu province foundries concentrate flooded and AGM capacity to supply domestic OEM assembly lines. MIIT emissions mandates are filtering substandard smelters, tightening qualified supply.
- Lithium-Ion:Higher energy density chemistry attracts capital for premium passenger vehicle SLI applications where weight reduction justifies cost premiums. Contemporary Amperex Technology and CATL-affiliated operations in Fujian and Guangdong are scaling cylindrical and prismatic cell formats for automotive qualification trials.
- Nickel-Metal Hydride:Transitional chemistry occupying niche hybrid vehicle auxiliary power roles where thermal stability outweighs lithium-ion energy density advantages.
- Others:Experimental sodium-ion and solid-state prototypes under MIIT-funded R&D programs, not yet qualified for SAMR market access certification.
Most installed capacity flows through Lead-Acid. Expansion is steepest in Lithium-Ion.
End User:
Volume concentration versus margin capture divides this category between high-unit automotive OEM contracts and fragmented aftermarket replacement cycles.
- Automobile:Passenger and commercial vehicle OEM demand dominates unit volume, with Yangtze River Delta assembly plants specifying AGM for stop-start micro-hybrid platforms. GB/T 34014 traceability compliance is now mandatory for tier-one supplier qualification.
- Marine:Auxiliary power for commercial fishing fleets and inland waterway vessels in Zhejiang and Fujian provinces, where deep-cycle durability under vibration loads commands price premiums over automotive equivalents.
- Industrial:Forklift, genset, and stationary backup applications requiring extended float service life, concentrated in Guangdong manufacturing zones.
- Motorcycle:Rural replacement demand across inland provinces sustains steady aftermarket volume through Chaowei Power's distribution network, independent of new vehicle sales volatility.
Automobile absorbs the majority of qualified AGM capacity. Motorcycle replacement cycles show the most resilient demand elasticity.
Technology:
Maturity gradients separate established flooded designs from emerging AGM specifications demanded by stop-start powertrains.
- AGM:Absorbent glass mat separators enable superior cyclic durability under partial state-of-charge operation required by micro-hybrid stop-start systems. Domestic OEMs specify AGM for 90% of new passenger vehicle platforms, creating qualified separator supply scarcity.
- Flooded:Conventional liquid electrolyte designs sustain economy positioning in commercial trucking and cost-sensitive replacement markets, with margin pools compressed by lead price volatility.
- Gel:Immobilized electrolyte chemistry for deep-cycle marine and solar backup applications where maintenance-free operation justifies cost premiums.
- Spiral:Wound electrode construction delivering high power density for performance motorcycle and powersport segments.
AGM commands the steepest capacity expansion trajectory. Flooded retains the largest installed base.
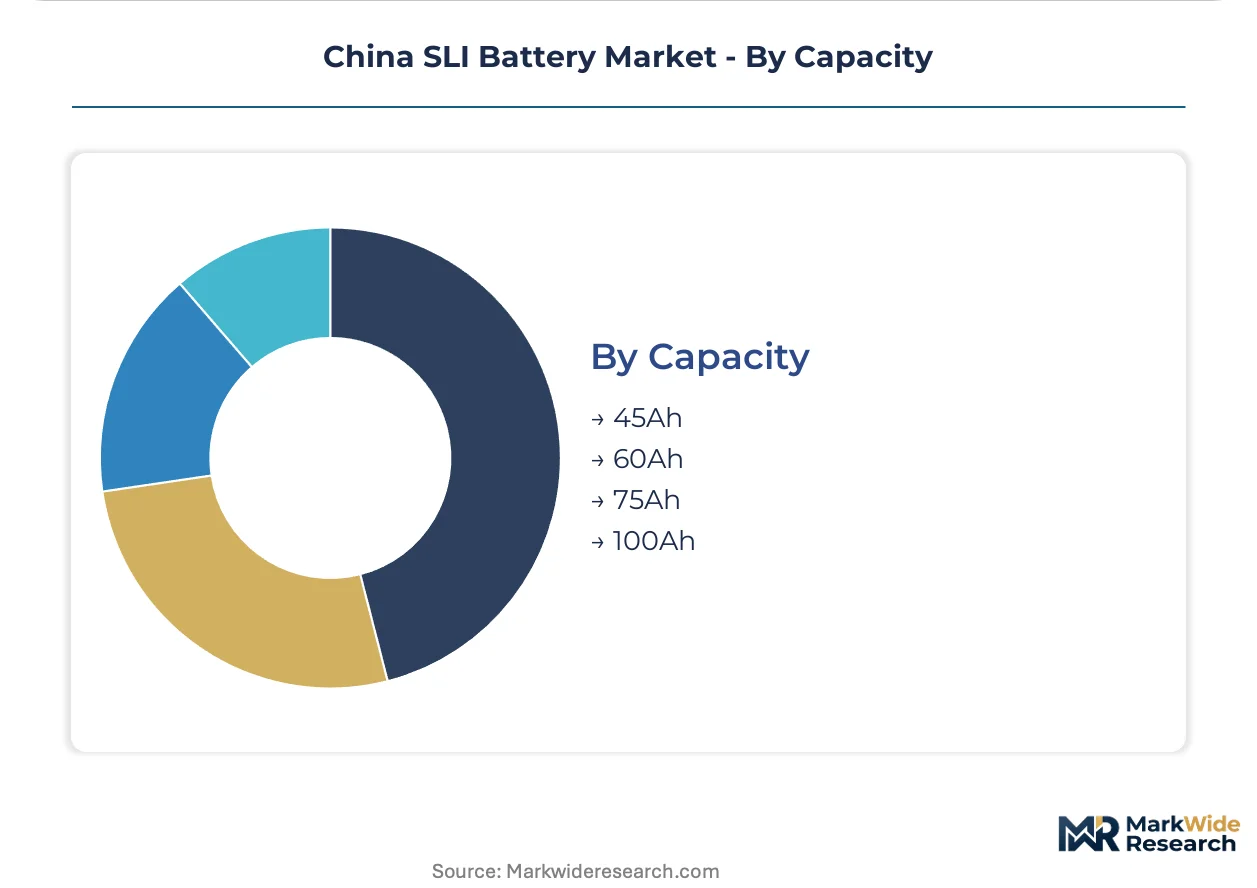
Capacity:
Scale economies favor high-volume 60Ah and 75Ah formats while specialty applications fragment procurement across the range.
- 45Ah:Compact passenger vehicle and motorcycle starting applications, dominant in Japanese-brand compact car platforms assembled in Guangdong.
- 60Ah:Mid-size sedan and crossover standard specification, capturing the highest production volume across SAIC, Geely, and BYD assembly lines.
- 75Ah:Premium passenger vehicle and light commercial truck applications, where stop-start duty cycles demand enhanced cyclic reserve capacity.
- 100Ah:Heavy commercial vehicle, marine, and industrial genset applications requiring sustained cranking torque and deep-cycle reserve.
60Ah formats run through the most production lines. 75Ah is climbing the fastest as stop-start vehicle parc expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SLI battery production infrastructure outstrips India's emerging capacity by an order of magnitude, while Southeast Asian markets absorb overflow export volumes from Zhejiang port facilities. Domestic demand concentration in the Yangtze River Delta manufacturing corridor shapes national supply chain configuration. Provincial industrial policies and emissions enforcement vary significantly across production clusters.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces concentrate 60% of qualified AGM capacity serving SAIC, Geely, and BYD assembly lines. MIIT enforces GB/T 34014 traceability standards through SAMR market access certification. Ningbo-Zhoushan port complex anchors export logistics for Southeast Asian replacement demand.
Pearl River Delta
Guangdong province motorcycle and compact vehicle battery demand sustains steady aftermarket turnover through Chaowei Power's distribution network. MEE emissions mandates filter substandard smelters from Shenzhen and Dongguan industrial zones. Guangzhou assembly plants for Japanese-brand platforms specify 45Ah formats for compact passenger vehicles.
Beijing-Tianjin-Hebei
Heavy commercial vehicle OEM demand in Hebei province drives 100Ah format production for truck and genset applications. Dual carbon policy enforcement accelerates foundry consolidation around Tianjin port logistics. Baoding and Shijiazhuang industrial clusters retrofit scrubber systems for MEE-compliant lead-acid smelting.
Sichuan-Chongqing
Western China inland markets exhibit resilient replacement cycles for agricultural vehicles and rural motorcycle fleets. SAMR certification timelines extend for new production facilities in Chengdu-Chongqing economic zone. Local distributors bypass traditional hierarchies through direct-to-garage digital procurement platforms.
Shandong Peninsula
Industrial genset and marine auxiliary applications in Qingdao and Yantai ports command price premiums for deep-cycle durability. Shandong province independent repair shops source replacement batteries through B2B e-commerce channels. Weifang and Jinan manufacturing zones concentrate flooded battery capacity for economy-tier commercial trucking.
China SLI Battery Market Competitive Landscape
Top-tier vendors anchor OEM qualification lists, while mid-scale specialists occupy aftermarket replacement channels. The vendor base stratifies across three tiers: integrated lead-acid foundries with captive smelting, lithium-ion technology aspirants targeting premium automotive platforms, and regional distributors with rural logistics dominance. Competitive moves concentrate on capacity consolidation around compliant emissions infrastructure and backward integration into recycling collection networks.
Within the integrated foundry tier, Tianneng Battery Group Co. and Chaowei Power occupy positions defined by geographic coverage depth. Contemporary Amperex Technology Co. Limited exemplifies the lithium-ion alternative archetype. Leoch International Technology Limited and Camel Group sit within mid-scale specialists serving industrial and commercial vehicle segments.
| Leading Market Players |
|---|
| Tianneng Battery Group Co. |
| Leoch International Technology Limited |
| Contemporary Amperex Technology Co. Limited |
| Gotion Inc. |
| GS Yuasa International Ltd |
| Camel Group |
| Chaowei Power |
| Fengfan |
| Exide Industries |
| Others |
Pricing and Supply Chain Analysis
Skilled AGM separator technicians concentrated in Jiangsu province command wage premiums that widen spreads between premium AGM and economy flooded battery tiers. Labor-cost differentials across the Yangtze River Delta manufacturing cluster directly feed into pricing stratification between certified OEM supply and unbranded aftermarket channels.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors for flooded lead-acid batteries as retrofit emissions compliance costs filter through to unit economics. Three-tier pricing structure across premium AGM, standard flooded, and economy unbranded levels separates SAMR-certified OEM supply from distributor-grade alternatives. Cost compression in economy flooded segments is intensifying because lead price volatility squeezes thin margin pools. Commercial trucking fleet operators exhibit highest price sensitivity, while premium passenger vehicle OEMs prioritize GB/T 34014 traceability compliance over unit cost.
Supply Chain Analysis
MIIT's domestic-content mandates for battery passport traceability are reshaping sourcing patterns toward captive lead smelting and controlled recycling networks. Primary supply draws from China, with secondary lead feedstock dependence on Australia and Peru concentrate imports. Raw material dependencies center on lead ingot, AGM separator mat, and sulfuric acid electrolyte. Single-source vulnerability concentrates in qualified AGM separator supply from Jiangsu specialty manufacturers. Distribution runs through provincial distributor hierarchies fragmenting toward direct-to-garage digital platforms in Guangdong and Shandong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by domestic OEM demand shift toward AGM specifications for stop-start micro-hybrid platforms. Premium chemistry qualification is displacing commodity flooded capacity across tier-one supplier lists.
For Market Incumbents: Anticipate lithium-ion substitution pressure in premium passenger vehicle SLI applications by accelerating R&D investment in hybrid chemistry formats. Defensive consolidation around MEE-compliant smelting infrastructure protects against foundry capacity filtering. Backward integration into nationwide recycling collection networks locks in core exchange economics against emerging lifecycle service competitors. For New Entrants and Emerging Players: Enter via rural motorcycle and agricultural vehicle replacement channels where Chaowei Power's distribution dominance leaves white-space for digital-native B2B platforms. Sichuan-Chongqing inland markets offer most penetrable geography given extended SAMR certification timelines for new production facilities. Go-to-market angle should target independent repair shops through direct-to-garage procurement platforms bypassing traditional provincial distributors. For Investors and Strategic Acquirers: Integrated automotive OEMs are the most active acquirer in this space seeking captive battery supply security. Long-term viability framing centers on qualified AGM capacity scarcity persisting through emissions compliance consolidation waves. Acquisition target archetype: mid-scale foundries with SAMR certification and retrofit scrubber infrastructure in Yangtze River Delta cluster. Signal to watch as inflection indicator: NMPA-aligned battery passport traceability requirements triggering OEM procurement qualification protocol revisions.| Strategic Initiative | Industry Significance |
|---|---|
| AGM Capacity Expansion | Jiangsu province foundries capture stop-start vehicle parc growth from SAIC and Geely assembly lines. |
| Recycling Network Integration | Tianneng's nationwide collection infrastructure anchors aftermarket revenue through core exchange programs. |
| GB/T 34014 Compliance Investment | SAMR certification for battery passport traceability filters non-compliant producers from tier-one procurement. |
| Lithium-Ion R&D Scale-Up | CATL-affiliated operations in Fujian pursue premium automotive SLI qualification trials. |
| Digital Platform Disintermediation | B2B e-commerce channels in Guangdong bypass provincial distributor markups shifting working capital. |
Research Methodology
Direct dialogue with AGM production engineers, SAMR certification specialists, OEM procurement managers, and aftermarket distributors grounded qualitative findings in operational reality. Secondary validation drew from MIIT policy circulars, MEE emissions enforcement records, customs trade data for lead concentrate imports, and vehicle production databases. Bottom-up capacity modeling triangulated against top-down demand estimates from passenger and commercial vehicle assembly forecasts.
Bottom-up analysis aggregated individual foundry capacity statements across Yangtze River Delta and Pearl River Delta clusters. Top-down demand modeling applied content-per-vehicle assumptions across stop-start micro-hybrid, conventional ICE, and commercial truck platforms. Segmentation dimensions spanned chemistry type, technology tier, capacity format, and end-use application. CAGRs were derived from slope analysis of annual demand trajectories against qualified supply expansion rates. Forecast inputs included MIIT dual carbon policy enforcement timelines and NMPA battery passport implementation schedules.
Inputs from primary stakeholder interviews were available through the study window; gaps in proprietary OEM procurement qualification data introduce uncertainty bands around tier-one supplier market share estimates. Forecasts reflect documented assumptions regarding emissions compliance retrofit completion rates and lithium-ion SLI substitution velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market