
 Lithium Ion Battery Wet Coated Diaphragm Market | 2026-2036
Lithium Ion Battery Wet Coated Diaphragm Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Battery Wet Coated Diaphragm Market Insights
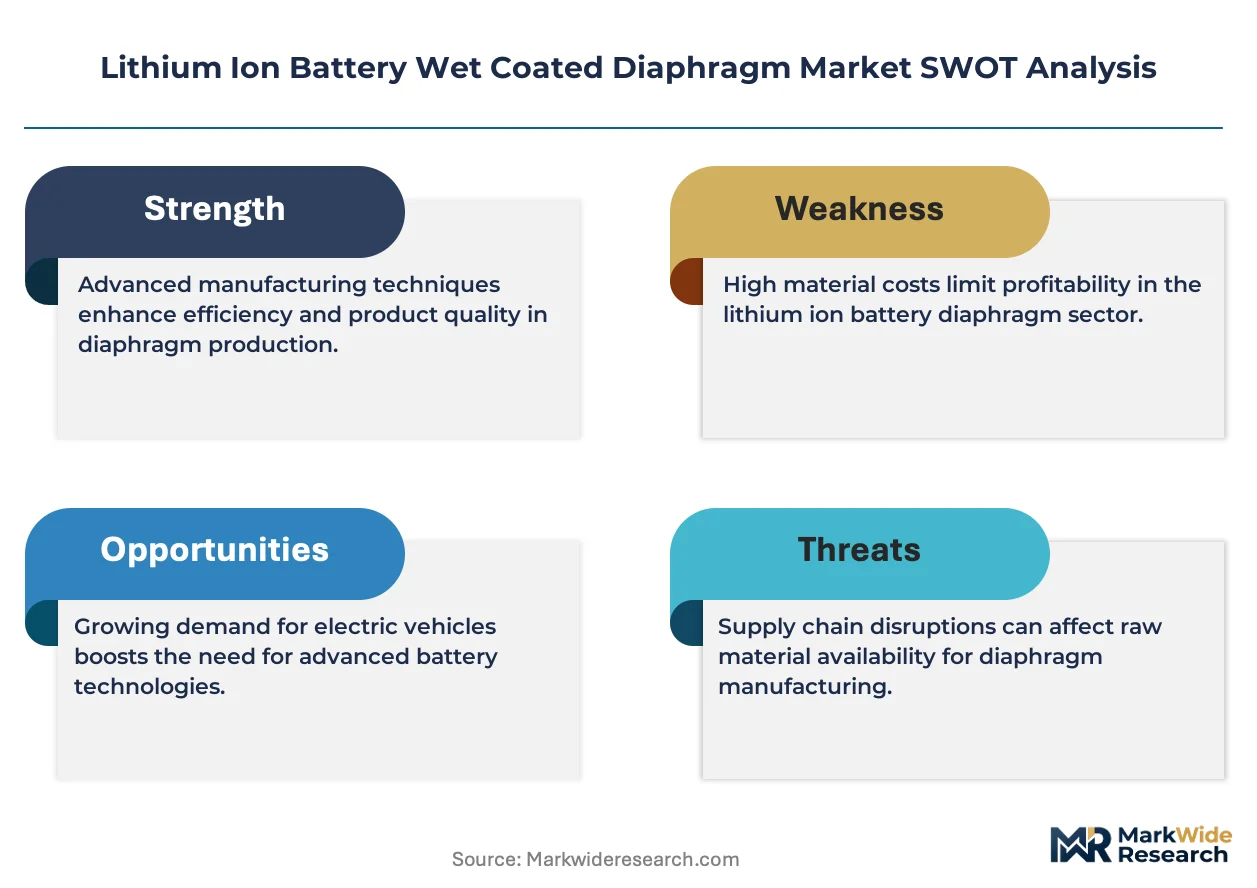
The wet coated diaphragm segment is consolidating around a sharp split between premium ceramic-coated separators for electric vehicles and commodity polyolefin films for consumer electronics. Asahi Kasei leverages its multi-layer coating technology to dominate high-voltage automotive contracts. Toray sustains cost leadership through integrated polymer resin-to-film production in Japan. SK Innovation anchors supply security for Korean cell makers via captive coating lines near Gumi.
A lithium ion battery wet coated diaphragm is a microporous polyolefin membrane, typically polyethylene or polypropylene, with a ceramic or polymer coating applied via aqueous slurry deposition to enhance thermal stability and electrolyte wettability; the coating layer, measured at 2-4 micrometers, prevents dendrite penetration and reduces internal short-circuit risk in cells operating above 4.2 volts. Separator products command the largest value share as coating complexity rises, while Electric Vehicle applications absorb the fastest volume growth as OEMs specify multi-layer ceramic architectures. Coating material inputs, particularly alumina and boehmite slurries, concentrate margin pools where binder chemistries differentiate performance.
The EU Battery Regulation and China's GB/T standards enforce traceable coating thickness tolerances and thermal shutdown temperature documentation, compelling manufacturers to retest legacy formulations. Japan's METI subsidizes domestic separator R&D to reduce reliance on imported ceramic powders. Stakeholders must monitor how solid-state battery timelines reshape wet coated diaphragm investment horizons without assuming linear cathode demand.
Market Dynamics
Cell chemistry evolution toward nickel-rich cathodes and silicon-anode architectures is forcing separator suppliers to engineer coatings that withstand higher voltages and mechanical stress during cycling.
Growth Catalysts
- EU Battery Regulation:Mandated carbon footprint declarations and recycled content quotas are accelerating wet coated separator qualification as OEMs seek traceable, high-performance components for compliance.
- Silicon-anode adoption:Volume expansion of silicon particles during lithiation demands ceramic-coated separators with enhanced puncture resistance, pulling advanced coating formulations into mainstream cell designs.
- South Korea's Gumi-Pohang cluster:Concentrated cathode-anode-separator co-location is reducing logistics friction and enabling just-in-time coating supply to LG Energy Solution and SK Innovation cell plants.
Market Restraints
- Alumina powder supply concentration:High-purity ceramic feedstock production concentrates in Chinese and Japanese suppliers, exposing coaters to input cost volatility and geopolitical supply risk.
- Polyolefin resin integration:Backward integration into polymer extrusion requires capital intensity that mid-tier coating specialists cannot match, consolidating margin capture with resin-to-film producers.
- Solid-state battery timeline uncertainty:Oxide and sulfide electrolyte architectures threaten to eliminate porous separators entirely, compressing wet coated diaphragm investment horizons without clear cathode demand visibility.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Domestic cell manufacturing incentives are creating first-mover advantage for separator coaters establishing local slurry deposition capacity ahead of demand scale-up.
- Stationary storage applications:Grid-scale battery deployments tolerate thicker, lower-cost ceramic coatings, opening volume tiers below automotive specification stringency.
- Water-based binder convergence:Replacement of solvent-based PVDF with aqueous acrylic systems reduces coating line emissions and aligns with EU Green Deal manufacturing protocols.
Industry Challenges
- Coating uniformity metrology:Sub-micron thickness control across 2-meter web widths demands spectroscopic inline inspection systems that strain technical talent pools in optical engineering.
- Dual certification timelines:Simaneous pursuit of GB/T 36276 and UL 2580 approvals for Chinese and North American automotive markets extends product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Battery Wet Coated Diaphragm Market |
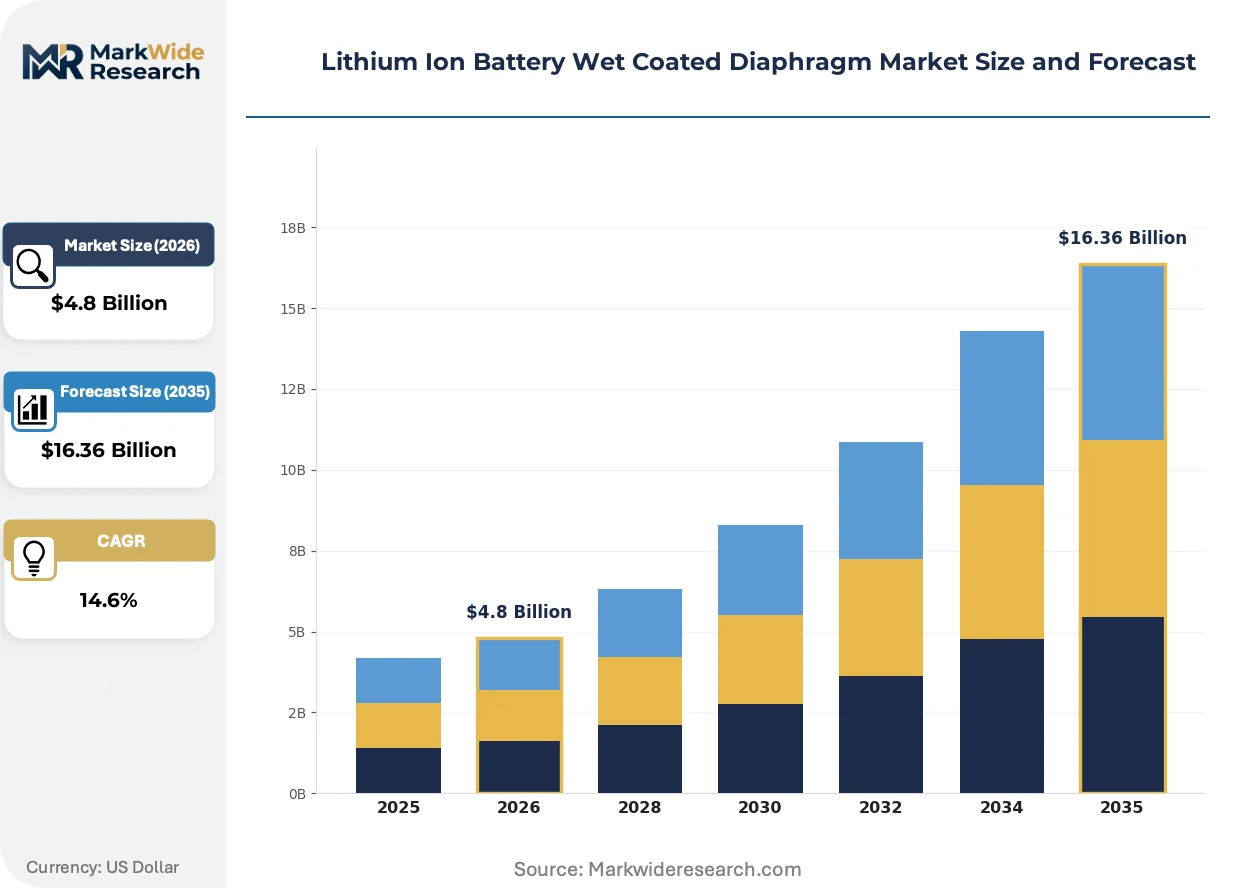
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Separator, Coating Material, Binder, Conductive Additive End User: Automotive, Electronics, Energy Storage, Power Tools Application: Electric Vehicles, Portable Devices, Renewable Energy Systems, UPS Manufacturing Stage: Raw Material Processing, Coating, Assembly, Quality Testing |
| Companies Covered | Asahi Kasei, Toray, SK Innovation, Cangzhou Mingzhu, Yunnan Energy New, Liaoyuan Hongtu Lithium Diaphragm Technology, Chongqing Yuntianhua Niumi, W-Scope, UBE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Battery Wet Coated Diaphragm Market Trends and Innovations
Separator architecture is bifurcating toward hyper-engineered multi-layer stacks for traction batteries versus simplified single-coat designs for stationary applications, with coating chemistry becoming the primary differentiation lever.
Boehmite ceramic slurries are overtaking alumina as the preferred coating material for high-voltage cells above 4.35 volts due to superior thermal stability and reduced electrolyte decomposition. Korean cell makers specify boehmite-to-polymer ratios above 9:1 for next-generation nickel-cobalt-manganese cathodes. This material shift is compressing legacy alumina coating capacity utilization and forcing equipment retrofits for slurry rheology management.
China's NMPA battery safety standards now require documented thermal shutdown temperature windows and dendrite penetration resistance testing for all automotive-qualified separators. Manufacturers must submit coating thickness distribution data and batch traceability records. European cell suppliers are adopting these protocols preemptively to streamline dual-market certification, accelerating alignment between GB/T and UN 38.3 testing frameworks.
Long-term offtake agreements are displacing spot procurement as cathode and cell makers seek coating capacity reservation amid supply security concerns. Tier-one automotive OEMs now contract directly with separator coaters, bypassing traditional distributor channels. This pattern concentrates most visibly in Germany, where Volkswagen and BMW have established dedicated supplier development programs for ceramic coating qualification.
Lithium Ion Battery Wet Coated Diaphragm Market Segmentation
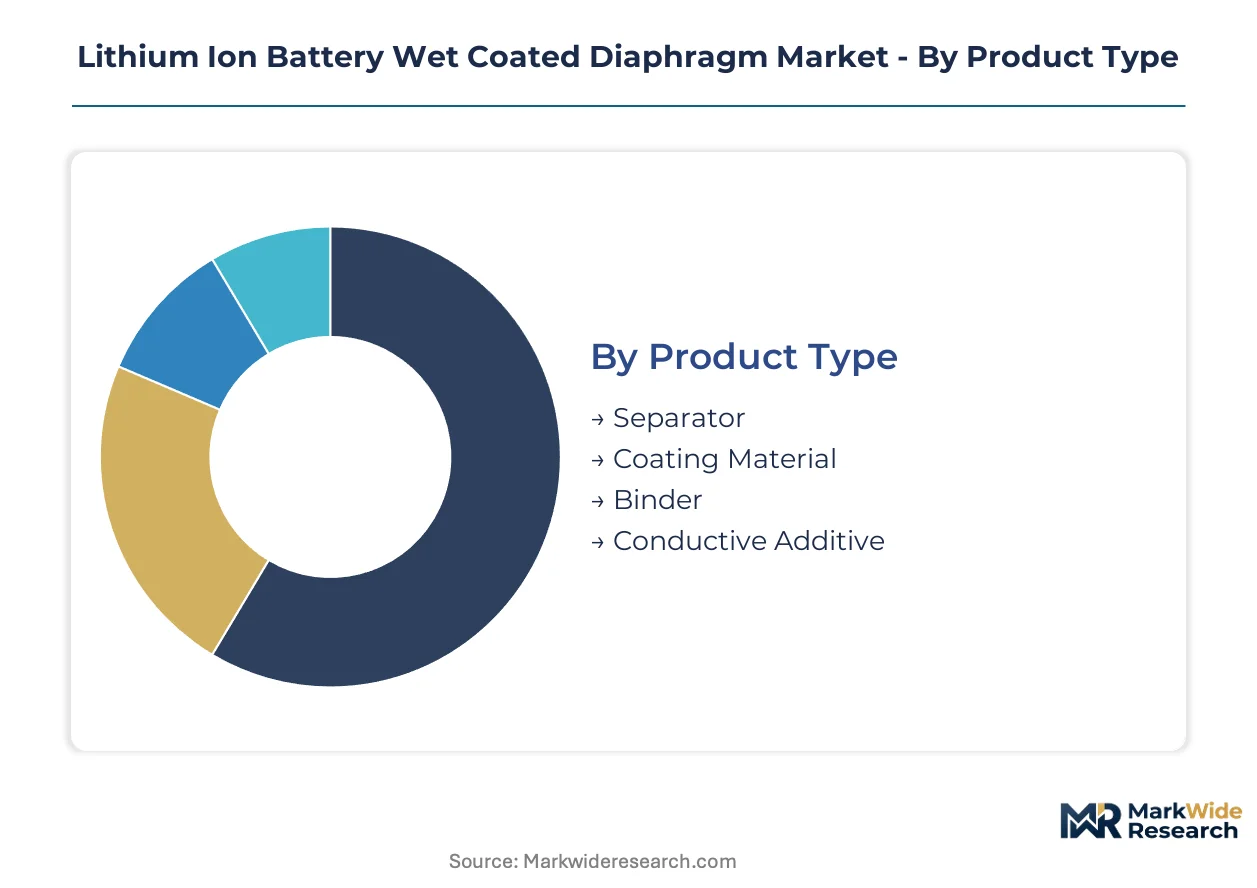
Wet coated diaphragm procurement splits sharply between standardized commodity grades and engineered specifications that command premium qualification cycles. Coating chemistry, end-use voltage requirements, and manufacturing traceability tiers determine pricing power and supplier selection criteria across each segment boundary.
Product Type:
Customization intensity varies from fully specified multi-layer ceramic stacks to interchangeable commodity inputs with limited formulation variance.
- Separator:Microporous polyethylene or polypropylene substrates, 12-25 micrometers thick, serve as the mechanical scaffold for ceramic deposition. Automotive cell makers in Germany and South Korea now mandate boehmite-coated tri-layer architectures for nickel-rich cathodes above 4.35 volts, disqualifying single-layer suppliers from premium contracts.
- Coating Material:Alumina and boehmite ceramic slurries constitute the functional thermal barrier. China's NMPA safety standards and the EU Battery Regulation enforce documented coating thickness distributions, pushing coaters toward aqueous boehmite systems with superior dendrite blocking at elevated voltages.
- Binder:Polyvinylidene fluoride and aqueous acrylic systems anchor ceramic particles to the polyolefin substrate. Water-based acrylic binders are displacing solvent-based PVDF in European coating lines to align with EU Green Deal emissions protocols.
- Conductive Additive:Carbon black and carbon nanotube dispersions enhance ionic conductivity at the electrolyte-separator interface. Demand concentrates in high-rate automotive cells where internal resistance directly impacts fast-charge capability.
Most installed capacity flows through Separator substrates. Expansion is steepest in Coating Material slurries as ceramic loading ratios climb for next-generation cell chemistries.
End User:
Application voltage and safety certification stringency create four distinct procurement tiers with divergent technical specifications.
- Automotive:Traction battery separators must survive nail penetration tests and thermal runaway propagation protocols under GB/T 36276 and UL 2580. OEMs in Germany, Japan, and South Korea now contract directly with coating specialists, bypassing distributors to secure capacity reservation.
- Electronics:Consumer device cells tolerate thinner ceramic coatings and less rigorous batch traceability. Japanese and South Korean electronics manufacturers prioritize cost-optimized single-layer polyethylene films for smartphone and laptop applications.
- Energy Storage:Grid-scale battery deployments accept thicker, lower-cost ceramic layers with reduced puncture resistance requirements. Stationary installations in India and Germany are absorbing surplus alumina coating capacity as automotive specifications tighten.
- Power Tools:High-discharge cylindrical cells demand moderate ceramic loading for mechanical abuse tolerance. This segment sources predominantly from Chinese coating houses serving cordless tool OEMs with simplified qualification pathways.
Automotive commands the dominant revenue share. Energy Storage is climbing fastest as grid-scale deployments scale in India and Europe.
Application:
Cell format and duty cycle differentiate four end-use contexts with distinct separator performance envelopes.
- Electric Vehicles:Pouch and prismatic cells for passenger vehicles require multi-layer ceramic coatings with sub-micron thickness uniformity across 2-meter web widths. South Korea's Gumi-Pohang cluster anchors the densest concentration of qualified coating capacity serving LG Energy Solution and SK Innovation.
- Portable Devices:Smartphone and tablet batteries utilize thinner separators with minimal ceramic loading to maximize volumetric energy density. Japanese suppliers dominate this tier through integrated resin-to-film production cost structures.
- Renewable Energy Systems:Solar-plus-storage and wind farm installations prioritize cycle life over power density, accepting thicker separators with enhanced electrolyte retention. India's PLI scheme for ACC batteries is stimulating domestic coating capacity for this application tier.
- UPS:Uninterruptible power supply batteries emphasize float life reliability and low self-discharge over mechanical abuse resistance. Lead-acid replacement cycles in data centers are pulling lithium-ion separator demand with simplified coating specifications.
Electric Vehicles absorbs the majority of qualified coating output. Renewable Energy Systems is expanding most quickly as grid storage procurement accelerates.
Manufacturing Stage:
Capital intensity and technical barrier height create asymmetric margin distribution across the production chain.
- Raw Material Processing:High-purity alumina and boehmite powder synthesis concentrates among Japanese and Chinese suppliers. Geopolitical supply risk and input cost volatility plague coaters lacking long-term offtake agreements with ceramic feedstock producers.
- Coating:Aqueous slurry deposition onto extruded polyolefin webs demands spectroscopic inline inspection systems for sub-micron thickness control. Equipment retrofits for boehmite rheology management are compressing legacy alumina line utilization.
- Assembly:Separator winding and cell stacking integration occurs at battery cell plants, not coating facilities. Just-in-time supply chains in South Korea's Gumi-Pohang cluster minimize logistics friction between coating lines and cell assembly.
- Quality Testing:Dendrite penetration resistance, thermal shutdown temperature documentation, and coating thickness distribution validation extend product qualification cycles by 12-18 months for dual GB/T and UL certification.
Coating captures the dominant margin pool. Quality Testing is expanding fastest as regulatory documentation requirements proliferate under China's NMPA standards and the EU Battery Regulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coating engineers and polymer scientists concentrate in South Korea's battery belt, Japan's chemical corridors, and Germany's automotive supply networks, anchoring regional production capabilities.
South Korea
LG Energy Solution and SK Innovation drive separator demand through multi-layer ceramic specifications for nickel-rich cathodes. The country's MFDS enforces battery safety documentation aligned with UN 38.3 testing frameworks. The Gumi-Pohang cluster hosts captive coating lines feeding just-in-time supply chains to cell assembly plants.
China
Domestic cell makers CATL and BYD absorb volume from alumina and boehmite coating specialists serving the EV transition. NMPA battery safety standards mandate thermal shutdown temperature windows and dendrite penetration resistance testing. Jiangsu and Zhejiang provinces concentrate slurry deposition capacity near cathode production zones.
Japan
Integrated resin-to-film producers leverage polymer extrusion expertise for cost-optimized polyethylene substrates. METI subsidizes domestic separator R&D to reduce ceramic powder import dependence. Nagoya and Osaka industrial corridors anchor Toray and Asahi Kasei production networks serving automotive OEMs.
Germany
Volkswagen and BMW direct supplier development programs for ceramic coating qualification in traction battery applications. The EU Battery Regulation mandates carbon footprint declarations and recycled content quotas for separator procurement. Stuttgart and Munich engineering clusters host technical qualification teams bridging OEM and coater specifications.
United States
Domestic cell manufacturing incentives under the IRA stimulate coating capacity reservation discussions with Korean and Japanese suppliers. NHTSA and UL 2580 standards govern automotive separator safety certification. Michigan and Tennessee battery plant locations are pulling coating logistics investment toward Midwest and Southeast industrial zones.
Lithium Ion Battery Wet Coated Diaphragm Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the wet coated diaphragm value chain, creating a tiered structure where integrated polymer resin-to-film manufacturers capture margin pools unavailable to standalone coating specialists. The market consolidates around three strategic archetypes: integrated chemical conglomerates with captive raw material positions, specialized separator coaters with equipment-scale advantages, and emerging regional players leveraging domestic cell manufacturing incentives. Competitive moves center on backward integration into ceramic powder synthesis and long-term offtake agreements that lock in cathode maker procurement.
Within the integrated chemical tier, Asahi Kasei and Toray exemplify resin-to-film production models that compress coating input costs. SK Innovation anchors the captive supply archetype through co-located capacity serving Korean cell makers. Among Chinese specialists, Cangzhou Mingzhu and Yunnan Energy New occupy positions shaped by domestic EV demand scale and NMPA regulatory alignment.
| Leading Market Players |
|---|
| Asahi Kasei |
| Toray |
| SK Innovation |
| Cangzhou Mingzhu |
| Yunnan Energy New |
| Liaoyuan Hongtu Lithium Diaphragm Technology |
| Chongqing Yuntianhua Niumi |
| W-Scope |
| UBE |
| Others |
Pricing and Supply Chain Analysis
Tier-one automotive OEMs in Germany and South Korea now contract directly with separator coaters, compressing distributor margins and anchoring pricing power in long-term offtake agreements with volume-commitment clauses.
Pricing Analysis
Long-term offtake agreements now dominate premium automotive contracts, while spot procurement persists in consumer electronics tiers. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer boehmite-coated automotive specifications from single-layer alumina industrial grades and commodity polyolefin films. Cost compression in standard tiers is intensifying because Chinese coating houses are absorbing surplus alumina capacity. Consumer electronics buyers exhibit highest price sensitivity; German automotive OEMs prioritize qualification security over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen, BMW, and Korean cell makers, bypassing traditional distribution. Raw material supply concentrates in China, Japan, and South Korea for high-purity alumina and boehmite powders, polyolefin resins, and aqueous binder systems. Ceramic feedstock production draws from Chinese and Japanese suppliers, exposing coaters to geopolitical supply risk. Distribution runs through just-in-time pipelines in South Korea's Gumi-Pohang cluster, with captive coating lines feeding adjacent cell assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme for ACC batteries offers cost-advantaged capacity expansion against EU Green Deal compliance costs that inflate European manufacturing economics.
For Market Incumbents: Anticipate solid-state battery timeline uncertainty by securing backward integration into boehmite powder synthesis and locking Korean cathode maker procurement through dedicated coating line investments. Defend margin position by retrofitting legacy alumina lines for aqueous binder systems before EU emissions protocols tighten. Priority lever: captive ceramic feedstock supply. For New Entrants and Emerging Players: Enter via India's stationary storage segment, where grid-scale deployments tolerate thicker, lower-cost ceramic coatings with simplified qualification pathways. Target surplus alumina coating capacity absorption as automotive specifications tighten toward boehmite. Go-to-market angle: water-based binder convergence for EU Green Deal alignment. For Investors and Strategic Acquirers: Chemical conglomerates with resin-to-film integration are the most active acquirer in this space, seeking coating specialists with equipment-scale advantages. Five-to-ten year viability hinges on wet coated diaphragm demand persisting through solid-state battery uncertainty. Target acquisition archetype: specialized coaters with spectroscopic inline inspection capabilities. Signal to watch: Korean cell maker boehmite-to-polymer ratio specifications above 9:1.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Synthesis | Reduces exposure to Chinese and Japanese alumina supply concentration for coaters. |
| Long-term Offtake Agreement with Cathode Maker | Locks capacity reservation for LG Energy Solution and SK Innovation procurement security. |
| Equipment Retrofit for Boehmite Rheology Management | Enables qualification for nickel-rich cathode specifications above 4.35 volts. |
| Aqueous Binder System Transition | Aligns coating line emissions with EU Green Deal manufacturing protocols. |
| Captive Coating Line Co-location | Feeds just-in-time supply chains in South Korea's Gumi-Pohang battery cluster. |
Research Methodology
Coverage spans South Korea, China, Japan, Germany, and the United States, with primary inputs from each. Separator coating specialists, cathode procurement leads at cell makers, polyolefin resin suppliers, ceramic powder producers, and automotive OEM supplier development teams contributed through structured interviews. Secondary validation drew from NMPA battery safety filings, EU Battery Regulation documentation, METI subsidy disclosures, and customs trade data for alumina and boehmite powder flows. Bottom-up capacity modeling triangulated against top-down cathode demand projections.
Granularity-level framing applied product type, end user, application, and manufacturing stage dimensions at the country level. CAGRs were derived through slope analysis of installed coating capacity against qualified cell production forecasts. Industry-specific inputs included boehmite-to-polymer ratio specifications from Korean cell makers and thermal shutdown temperature documentation requirements under China's GB/T standards. Volume and value outputs reflect a triangulated approach across the analysis window.
Inputs from NMPA safety filings and EU regulatory disclosures were available through the study window; gaps in solid-state battery commercialization timelines introduce uncertainty bands around long-term diaphragm demand assumptions. Forecasts reflect assumptions about cathode chemistry evolution and coating qualification cycle durations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Global Next Generation Batteries Market