
 Carbon Battery Bank Market | 2026-2036
Carbon Battery Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Battery Bank Market Outlook
The carbon battery bank market is pivoting on a widening gap between premium electrochemical systems and commodity lead-carbon hybrids. Hitachi Chemical leverages its materials science heritage to dominate high-purity activated carbon electrode supply. Jiangxi JingJiu Power Science & Technology Co., Ltd. anchors China's domestic replacement cycle with vertically integrated lead-carbon production. Leading Edge Power competes in off-grid African and Southeast Asian deployments where cost-per-kWh dictates procurement decisions.
A carbon battery bank is an electrochemical or capacitive energy storage assembly utilizing carbon-based electrodes—typically activated carbon, hard carbon, or carbon nanotube composites—to enhance charge acceptance, cycle life, and partial state-of-charge performance in lead-acid or hybrid architectures, primarily deployed for grid stabilization, renewable integration, and backup power applications. Stationary systems occupy the dominant revenue share due to data center and telecom infrastructure refresh cycles across Asia-Pacific. Grid-scale solutions represent the fastest expansion trajectory as utility providers in India and China replace conventional battery farms with carbon-enhanced alternatives offering 3,000-plus cycle life. Portable systems sustain niche margins in expeditionary military and remote industrial monitoring applications where weight and temperature resilience override unit economics.
China's MIIT enforces GB standards for battery recycling and carbon content disclosure, while India's CEA mandates frequency regulation capabilities that carbon-enhanced systems uniquely satisfy. Japan's METI directs subsidy flows toward capacitive storage demonstrations incorporating domestic carbon fiber electrodes. Stakeholders must monitor how evolving carbon sourcing rules under China's MEE and India's BIS efficiency labeling reshape supplier qualification timelines and regional manufacturing footprints.
Market Dynamics
China's MIIT battery recycling directives and India's CEA grid interconnection mandates are forcing a bifurcation between premium electrochemical systems and commodity lead-carbon hybrids, compressing procurement timelines for carbon-enhanced storage arrays.
Growth Catalysts
- India's CEA frequency regulation mandates:Utility-scale solar developers must install storage with rapid response capabilities, directing procurement toward carbon-enhanced lead-acid banks that satisfy technical specifications.
- China's dual carbon policy framework:State-owned power groups in Shandong province are replacing lead-acid infrastructure with carbon-enhanced alternatives, creating concentrated demand pull.
- Activated carbon anode manufacturing:Domestic production of high-purity carbon electrodes is scaling in China's industrial corridor, reducing import dependency for battery assemblers.
Market Restraints
- Hard carbon feedstock volatility:Biomass-derived precursor costs fluctuate with agricultural commodity markets, squeezing margin predictability for anode manufacturers.
- Shandong supplier concentration:Three-quarters of China's lead-carbon hybrid output originates from state-affiliated producers in one province, creating geographic risk exposure.
- Lithium-ion substitution pressure:Falling lithium carbonate prices and improving LFP cycle life threaten carbon battery positioning in grid-scale tenders.
Strategic Opportunities
- Southeast Asian off-grid electrification:Indonesia's remote island networks and Philippine telecom towers present untapped demand for cost-optimized lead-carbon hybrids.
- Japan's METI capacitive storage subsidies:Demonstration project funding for carbon fiber electrode systems opens premium market entry for advanced materials suppliers.
- Data center UPS refresh cycles:Asia-Pacific hyperscale facilities are evaluating carbon-enhanced alternatives to conventional VRLA banks for partial state-of-charge resilience.
Industry Challenges
- Electrochemical engineering talent scarcity:Carbon anode formulation and cell balancing expertise concentrates in Japanese and Chinese research institutes, limiting workforce mobility.
- BIS certification timelines:India's efficiency labeling requirements for stationary batteries extend product qualification cycles by eight to twelve months.
- Legacy lead-acid infrastructure lock-in:Existing battery room footprints and charging infrastructure constrain rapid technology transitions for industrial users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Battery Bank Market |
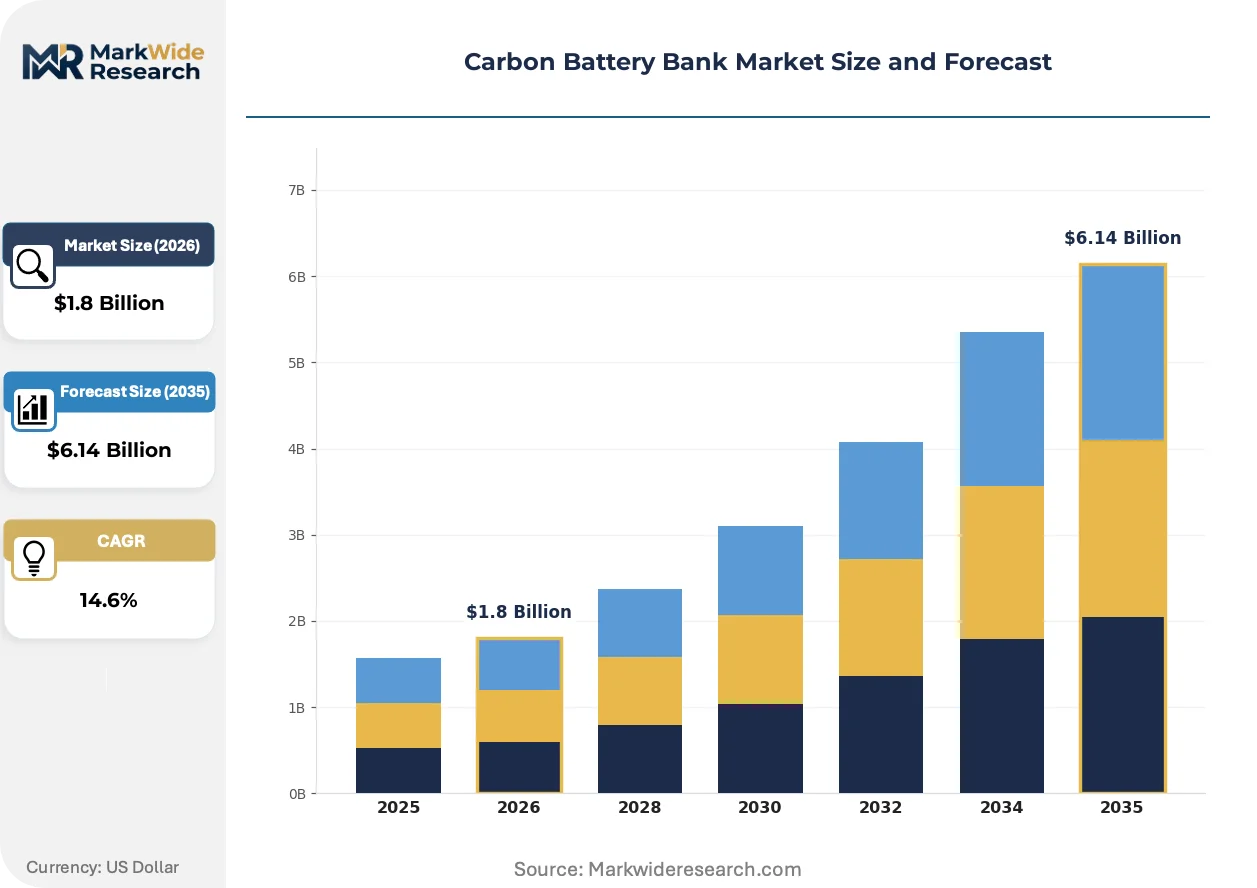
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Stationary Systems, Grid-Scale Solutions, Hybrid Systems End User: Residential, Commercial, Industrial, Utility Providers Technology: Electrochemical Storage, Capacitive Storage, Thermal Storage, Mechanical Storage Installation: On-Site, Off-Site, Containerized, Modular |
| Companies Covered | Hitachi Chemical, Leading Edge Power, CDN Solar, Shandong Sacred Sun Power Sources Co., Ltd., Sunergy Solar, IPS Integrated Power Systems Inc., Jiangxi JingJiu Power Science & Technology Co., Ltd., Helios Power Solutions, Narada Asia Pacific Pte. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Battery Bank Market Strategic Shifts
Carbon battery architectures are fragmenting along performance-tier lines as activated carbon, hard carbon, and carbon nanotube composites compete for distinct application envelopes. Material science advances and regulatory disclosure requirements are accelerating electrode formulation disclosure.
Hard carbon anodes synthesized from lignin precursors are converging with lead-carbon hybrid architectures to extend cycle life beyond three thousand cycles at partial state-of-charge. Telecom infrastructure operators in India and Southeast Asia are piloting these systems for remote tower backup. This convergence is compressing the performance gap between premium lithium-ion and commodity lead-acid alternatives in temperature-extreme deployments.
China's MEE is enforcing carbon content disclosure under evolving GB standards for battery recycling, compelling manufacturers to document electrode material provenance and end-of-life recovery pathways. Industrial buyers now require supply chain transparency certifications before tender participation. Grid-scale procurement in Shandong and Jiangsu provinces is most affected, with state-owned utilities inserting carbon accounting clauses into supply agreements.
Buyer evaluation criteria are hardening around total cost-of-ownership metrics rather than upfront capital expenditure, disrupting traditional distributor-led sales channels. Industrial power users and renewable developers now engage electrode suppliers directly for technical validation. This pattern is most visible in India's utility-scale solar segment, where developers bypass integrators to negotiate carbon anode specifications with manufacturers.
Carbon Battery Bank Market Segmentation
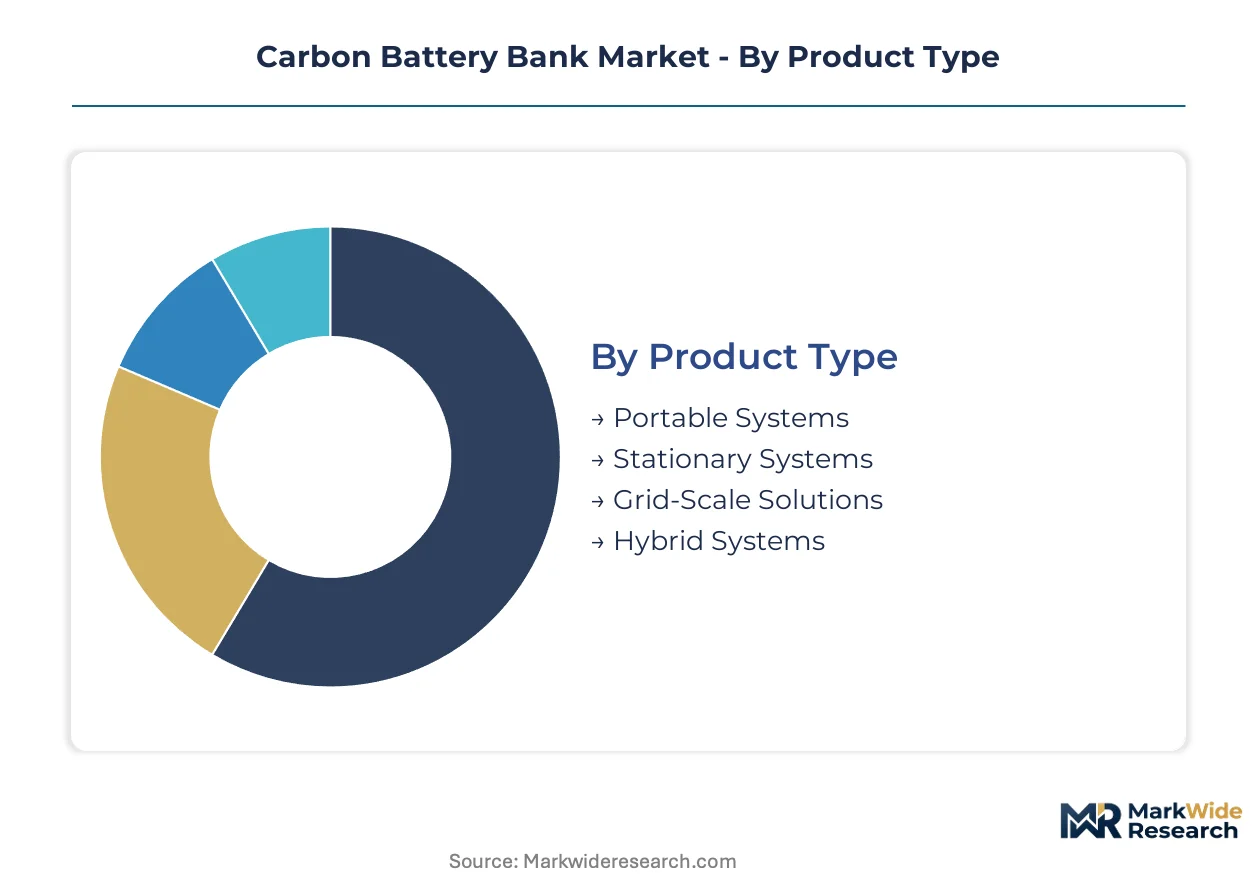
Carbon battery bank procurement decisions diverge sharply across application scales and technical architectures. Buyers evaluate cycle life requirements, grid interconnection mandates, and total cost-of-ownership differently depending on deployment context and regulatory environment.
Product Type:
Procurement volume concentrates in stationary infrastructure, though grid-scale tenders are accelerating fastest under renewable integration mandates.
- Stationary Systems:Fixed-installation carbon-enhanced lead-acid banks dominate data center and telecom backup applications across Asia-Pacific. India's CEA frequency regulation requirements and China's Shandong industrial corridor replacement cycle sustain concentrated demand for systems rated above three thousand cycles.
- Grid-Scale Solutions:Utility-scale carbon battery arrays integrate activated carbon anodes for rapid response and partial state-of-charge resilience. Indian solar developers and Chinese state-owned power groups in Jiangsu province are the primary procurement drivers under interconnection mandates.
- Portable Systems:Expeditionary military and remote industrial monitoring applications in Southeast Asia sustain niche demand where temperature resilience overrides unit economics.
- Hybrid Systems:Lead-carbon architectures combining conventional plates with carbon-enhanced negative electrodes serve cost-sensitive industrial users in India's manufacturing belt.
Volume sits with Stationary Systems; growth tilts toward Grid-Scale Solutions.
End User:
Customer procurement authority determines specification stringency and qualification timeline intensity.
- Utility Providers:State-owned power groups in China and licensed discoms in India drive bulk procurement with technical specifications mandating carbon content disclosure under MIIT and CEA frameworks. Tender volumes concentrate in Shandong and Tamil Nadu.
- Industrial:Manufacturing facilities and process industries evaluate total cost-of-ownership metrics for backup power, with petrochemical and steel clusters in China's industrial corridor showing fastest adoption curves.
- Commercial:Data center operators and telecom infrastructure owners across Asia-Pacific refresh UPS systems with carbon-enhanced alternatives for partial state-of-charge resilience.
- Residential:Off-grid electrification programs in Indonesia and the Philippines sustain limited demand for small-scale lead-carbon hybrids.
Procurement authority concentrates with Utility Providers; specification evolution is steered by Industrial buyers.
Technology:
Electrode material selection determines performance tier and regulatory compliance pathway.
- Electrochemical Storage:Activated carbon and hard carbon anode systems dominate commercial deployment, with lignin-derived hard carbon extending cycle life beyond three thousand cycles in telecom backup trials across India.
- Capacitive Storage:Carbon fiber electrode systems qualify for Japan's METI subsidy demonstrations, positioning premium materials suppliers for grid stabilization contracts.
- Thermal Storage:Limited integration with carbon battery architectures in industrial process heat applications.
- Mechanical Storage:No material overlap with carbon electrode chemistries; excluded from carbon battery bank classification for procurement purposes.
Commercial deployment favors Electrochemical Storage; subsidy flows are redirecting toward Capacitive Storage.
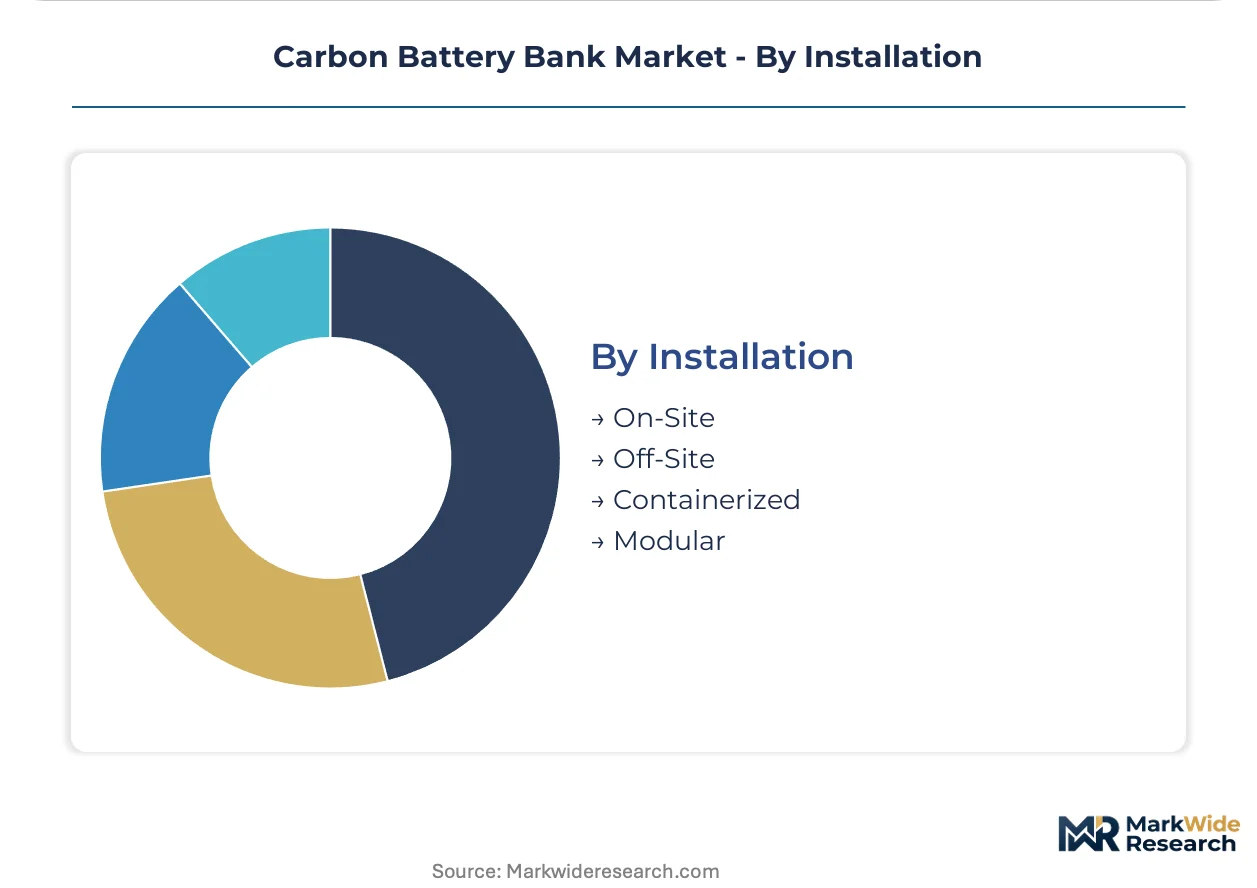
Installation:
Site constraints and mobility requirements determine packaging architecture and supply chain configuration.
- Containerized:Pre-integrated carbon battery banks in standard shipping containers dominate utility-scale tenders in India and China, compressing field installation timelines and satisfying CEA interconnection deadlines.
- Modular:Rack-mounted systems with hot-swappable carbon-enhanced cells serve data center operators in Singapore and Tokyo requiring incremental capacity expansion without facility shutdown.
- On-Site:Custom-integrated installations persist in legacy industrial facilities with constrained battery room footprints.
- Off-Site:Centralized storage parks with dedicated grid connection points serve renewable developers in Gujarat and Rajasthan seeking pooled frequency regulation services.
Deployment velocity favors Containerized systems; flexibility premiums sustain Modular growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's industrial corridor concentrates China's carbon battery bank procurement, with state-owned power groups replacing legacy lead-acid infrastructure at scale. India's utility-scale solar developers accelerate storage procurement under CEA frequency regulation mandates. Japan's METI directs subsidy flows toward advanced electrode demonstrations.
China
Shandong and Jiangsu provinces anchor domestic demand as state-owned utilities execute lead-acid replacement cycles. MIIT battery recycling directives and dual carbon goals redirect manufacturing investment toward electrochemical systems with activated carbon anodes. The Yangtze River Delta hosts scaling production of high-purity carbon electrodes, reducing import dependency for battery assemblers serving grid-scale tenders.
India
Tamil Nadu and Gujarat drive utility-scale procurement as solar developers install carbon-enhanced banks to satisfy CEA interconnection mandates. BIS efficiency labeling requirements extend product qualification timelines, compressing procurement windows for international suppliers. The Delhi-NCR corridor concentrates telecom infrastructure operators piloting hard carbon anode systems for remote tower backup applications.
Japan
METI subsidy programs for capacitive storage demonstrations redirect domestic electrode manufacturers toward carbon fiber electrode systems. Kansai and Chubu industrial zones host materials science research institutes supplying formulation expertise to regional battery developers. Osaka-based fabricators qualify for grid stabilization contracts requiring premium electrode performance specifications.
Indonesia
Remote island networks sustain off-grid electrification demand for cost-optimized lead-carbon hybrids. The country's national energy regulator mandates storage integration for distributed renewable projects, directing procurement toward containerized carbon battery banks. Java-Bali corridor telecom towers present concentrated deployment opportunities for temperature-resilient backup systems.
South Korea
Seoul Capital Area data center operators evaluate carbon-enhanced alternatives to conventional VRLA banks for partial state-of-charge resilience. MFDS industrial safety frameworks and national carbon accounting standards reshape supplier qualification requirements for stationary storage procurement. Busan-Ulsan manufacturing belt facilities pilot hybrid systems for process backup applications.
Carbon Battery Bank Market Competitive Environment
Premium-margin players sit above commodity-margin players across electrode purity and cycle life specifications, with materials science heritage commanding pricing power in high-purity activated carbon supply. The market structures around three archetypes: vertically integrated lead-carbon hybrid manufacturers, specialized activated carbon electrode suppliers, and off-grid deployment specialists optimizing cost-per-kWh economics. Capacity expansion and direct technical engagement with industrial buyers constitute the dominant competitive moves, bypassing traditional distributor channels.
Among Japan-based materials specialists, Hitachi Chemical occupies a position exemplifying premium-tier electrode supply anchored in carbon fiber and activated carbon heritage. Jiangxi JingJiu Power Science & Technology Co., Ltd. and Shandong Sacred Sun Power Sources Co., Ltd. represent the vertically integrated Chinese archetype, with corporate structures indicating captive production of carbon-enhanced negative electrodes for domestic replacement cycles. Leading Edge Power sits within the off-grid specialization tier, with geographic naming suggesting deployment focus in African and Southeast Asian markets where cost optimization overrides performance premiums.
| Leading Market Players |
|---|
| Hitachi Chemical |
| Leading Edge Power |
| CDN Solar |
| Shandong Sacred Sun Power Sources Co., Ltd. |
| Sunergy Solar |
| IPS Integrated Power Systems Inc. |
| Jiangxi JingJiu Power Science & Technology Co., Ltd. |
| Helios Power Solutions |
| Narada Asia Pacific Pte. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Hard carbon precursor feedstock indices, tracking lignin and biomass-derived input costs, cascade through electrode manufacturing tiers into three distinct pricing bands: premium activated carbon systems for grid-scale tenders, mid-grade lead-carbon hybrids for industrial backup, and cost-optimized configurations for off-grid deployments.
Pricing Analysis
Cycle-life guarantees anchor value-based pricing, with utility providers in Shandong and Tamil Nadu paying premiums for systems rated above three thousand cycles at partial state-of-charge. Price differentiation separates METI-subsidized capacitive storage demonstrations from commodity lead-carbon hybrids serving Southeast Asian telecom towers. Cost compression in the standard tier intensifies as falling lithium carbonate prices erode carbon battery positioning in Indian solar tenders. Industrial power users in China's manufacturing belt show lowest price sensitivity, prioritizing total cost-of-ownership over upfront capital expenditure.
Supply Chain Analysis
China's MIIT domestic-content mandates for battery recycling and carbon electrode production are redirecting procurement toward Shandong and Jiangsu province suppliers, reducing import dependency for activated carbon anodes. The supply chain draws from Indonesian coconut shell charcoal for activated carbon feedstock, Japanese carbon fiber for premium capacitive electrodes, and domestic Chinese lignin processing for hard carbon precursors. Single-source vulnerability concentrates in Shandong's state-affiliated producer cluster, where three-quarters of national lead-carbon hybrid output originates. Distribution runs through direct technical engagement channels, with industrial buyers bypassing distributors to negotiate electrode specifications with manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon battery bank market sits in a technology-transition phase, with hard carbon anode systems displacing conventional lead-acid infrastructure across Asia-Pacific grid and industrial applications.
For Market Incumbents: Hedge against lithium-ion substitution pressure by deepening in-house production of high-purity activated carbon electrodes in the Yangtze River Delta, while securing long-term offtake agreements with Shandong state-owned utilities to lock in replacement-cycle volumes. Prioritize BIS and GB standards certification investment to compress qualification timelines for Indian and Chinese tenders. For New Entrants and Emerging Players: Launch via containerized system partnerships targeting Indonesia's remote island electrification programs, where national energy regulator mandates for distributed renewable storage integration outpace local supply capacity. Penetrate the Philippine telecom tower backup segment with temperature-resilient lead-carbon hybrids optimized for partial state-of-charge cycling in tropical climates. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated electrode manufacturers with captive carbon anode production in China's industrial corridor, where MIIT recycling directives and dual carbon policy enforcement are consolidating supplier tiers. Watch for inflection in Indian CEA tender volumes as frequency regulation mandates tighten across Tamil Nadu and Gujarat solar developments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Anode Production | Captive supply of activated carbon electrodes reduces import dependency for battery assemblers serving Shandong utility tenders. |
| Direct Technical Engagement with Industrial Buyers | Bypassing distributor channels accelerates qualification cycles for data center operators evaluating carbon-enhanced UPS alternatives. |
| Containerized System Platform Standardization | Pre-integrated shipping container formats compress field installation timelines for Indian solar developers under CEA interconnection deadlines. |
| Hard Carbon Anode R&D Partnership | Lignin-derived precursor collaborations with research institutes extend cycle life beyond three thousand cycles for telecom backup applications. |
| Carbon Content Disclosure Certification Program | MEE-compliant material provenance documentation enables participation in state-owned utility procurement with carbon accounting clauses. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving carbon electrode R&D directors, utility procurement officers at state-owned power groups, telecom infrastructure operators, and EPC contractors executing containerized battery installations. MIIT battery recycling directives, CEA interconnection mandate documentation, and Shandong provincial tender databases supplemented bottom-up volume estimates, while top-down reconciliation against Asia-Pacific stationary storage investment flows validated market sizing across the analysis window.
Data-stream reconciliation integrated electrochemical storage deployment tracking by electrode material type, installation architecture segmentation across containerized and modular formats, and end-user procurement authority clustering by utility, industrial, and commercial categories. CAGRs were derived from segment-level volume trajectories and value-per-kWh pricing bands, with hard carbon anode adoption curves and lithium-ion substitution elasticity serving as key forecast sensitivity inputs throughout the projection horizon.
Feedstock price volatility in biomass-derived precursors, regulatory timeline slippage in BIS certification processes, and lithium carbonate market dynamics are the dominant revision risks for carbon battery bank demand forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Advance Battery Technologies Market