
 France Lithium-Ion Battery for Electric Vehicle Market | 2026-2036
France Lithium-Ion Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
France Lithium-Ion Battery for Electric Vehicle Market Insights
The direct supply channel between cell producers and French automotive OEMs is narrowing as manufacturers seek tighter control over chemistry specifications and delivery timelines. Automotive Cells Company leverages its Stellantis-TotalEnergies-Saft consortium structure to anchor domestic cathode supply. Verkor competes through its planned gigafactory in Dunkirk, positioning itself as a volume alternative to Asian imports. Saft Groupe SA specializes in high-performance NMC formulations, extending its legacy industrial battery expertise into automotive applications.
The France lithium-ion battery for electric vehicle comprises rechargeable electrochemical cells using lithium intercalation compounds in graphite anodes and metal-oxide cathodes, typically operating at nominal voltages of 3.2–3.7 V with energy densities exceeding 250 Wh/kg for premium automotive applications. These systems store and discharge electrical energy to power traction motors, enabling zero-emission propulsion for battery electric and plug-in hybrid vehicles. Prismatic cells dominate the French OEM procurement landscape due to their efficient pack-level space utilization and thermal management integration. LFP chemistry is gaining structural traction among fleet operators and entry-level passenger models where cost stability and cycle longevity outweigh energy density requirements. Solid-state technology occupies the premium development tier, with stakeholders monitoring its potential to displace liquid electrolyte architectures in next-generation French-designed platforms.
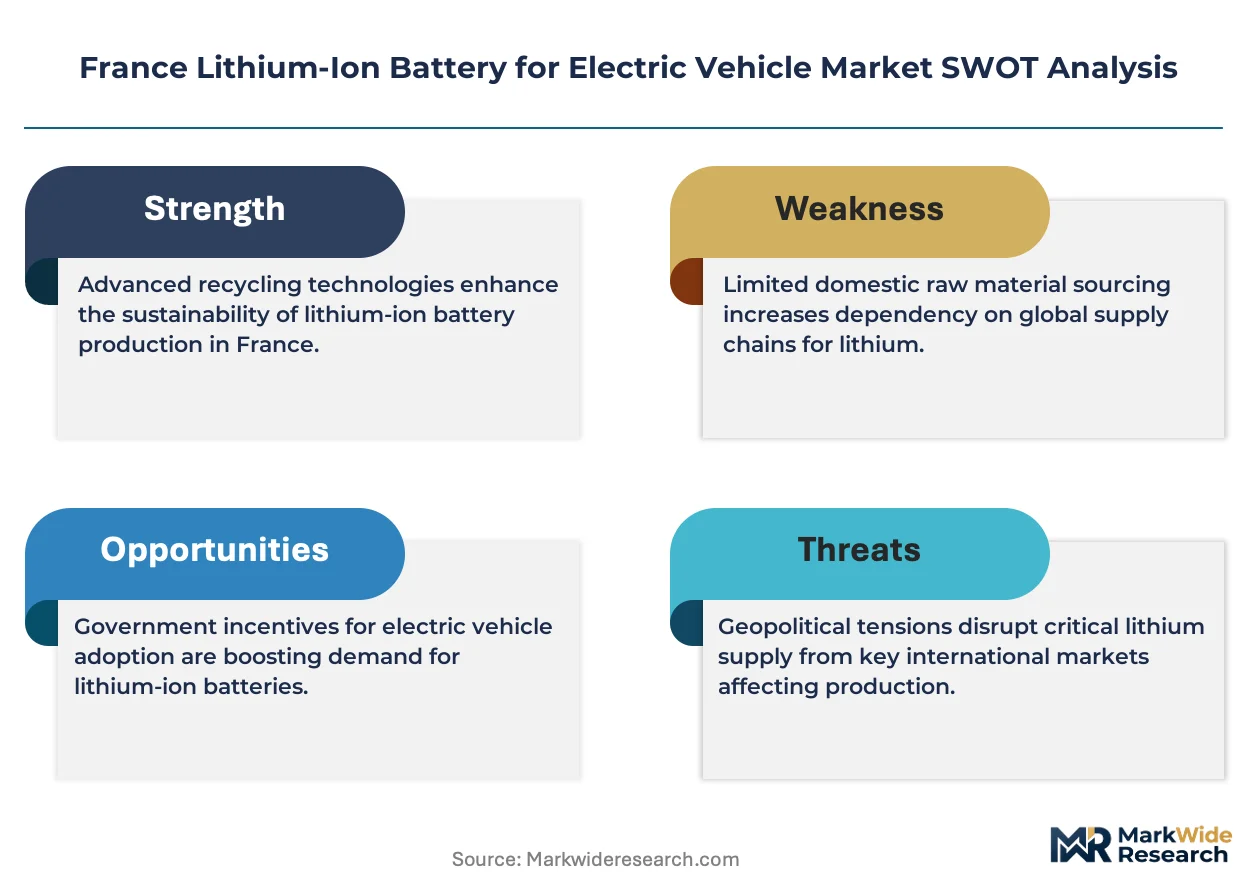
France's national implementation of the EU Battery Regulation, enforced by national market surveillance authorities under CE marking frameworks, mandates minimum recycled lithium and cobalt content while requiring supply chain due diligence documentation. The country's adherence to REACH chemical restrictions and the EU Green Deal's carbon border adjustments shapes cell import economics and local manufacturing investment decisions. Stakeholders must monitor how France's national low-carbon electricity grid interacts with battery production energy intensity rules to determine siting advantages for new gigafactory capacity.
Market Dynamics
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are restructuring supplier-OEM relationships across France, forcing domestic gigafactory investments to secure compliance advantages.
Growth Catalysts
- EU Green Deal carbon border adjustments:French manufacturers gain siting advantages from the country's low-carbon electricity grid, attracting cell production investment to northern industrial zones.
- Fleet operator electrification:Entry-level passenger and commercial vehicle segments are driving LFP chemistry adoption for its cost stability and cycle longevity.
- CE marking enforcement:National market surveillance authorities are tightening compliance documentation requirements, favoring established domestic suppliers with traceable supply chains.
Market Restraints
- Asian cell import concentration:French OEMs remain dependent on Korean and Chinese suppliers for high-Ni cathode materials, creating supply security vulnerabilities.
- Raw material cost volatility:Lithium and cobalt price fluctuations compress margin visibility for domestic gigafactory projects with long-dated offtake contracts.
- Solid-state technical limitation:Liquid electrolyte architectures retain manufacturing maturity advantages, delaying next-generation platform adoption timelines.
Strategic Opportunities
- Hauts-de-France industrial cluster:The Dunkirk-Douai corridor offers brownfield infrastructure and port access for cathode precursor import and finished cell export.
- REACH chemical restriction convergence:Stricter solvent and additive rules are accelerating water-based electrode coating process development.
- Second-life stationary storage:Retired automotive packs are finding grid-scale applications, extending value capture across battery lifecycles.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management expertise concentrates among a small pool of specialists with industrial battery backgrounds.
- Gigafactory capex intensity:Dry electrode coating and formation equipment requires multi-year capital commitment before revenue generation.
- EU Battery Regulation certification timeline:Supply chain due diligence documentation and recycled content verification are extending product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Lithium-Ion Battery for Electric Vehicle Market |
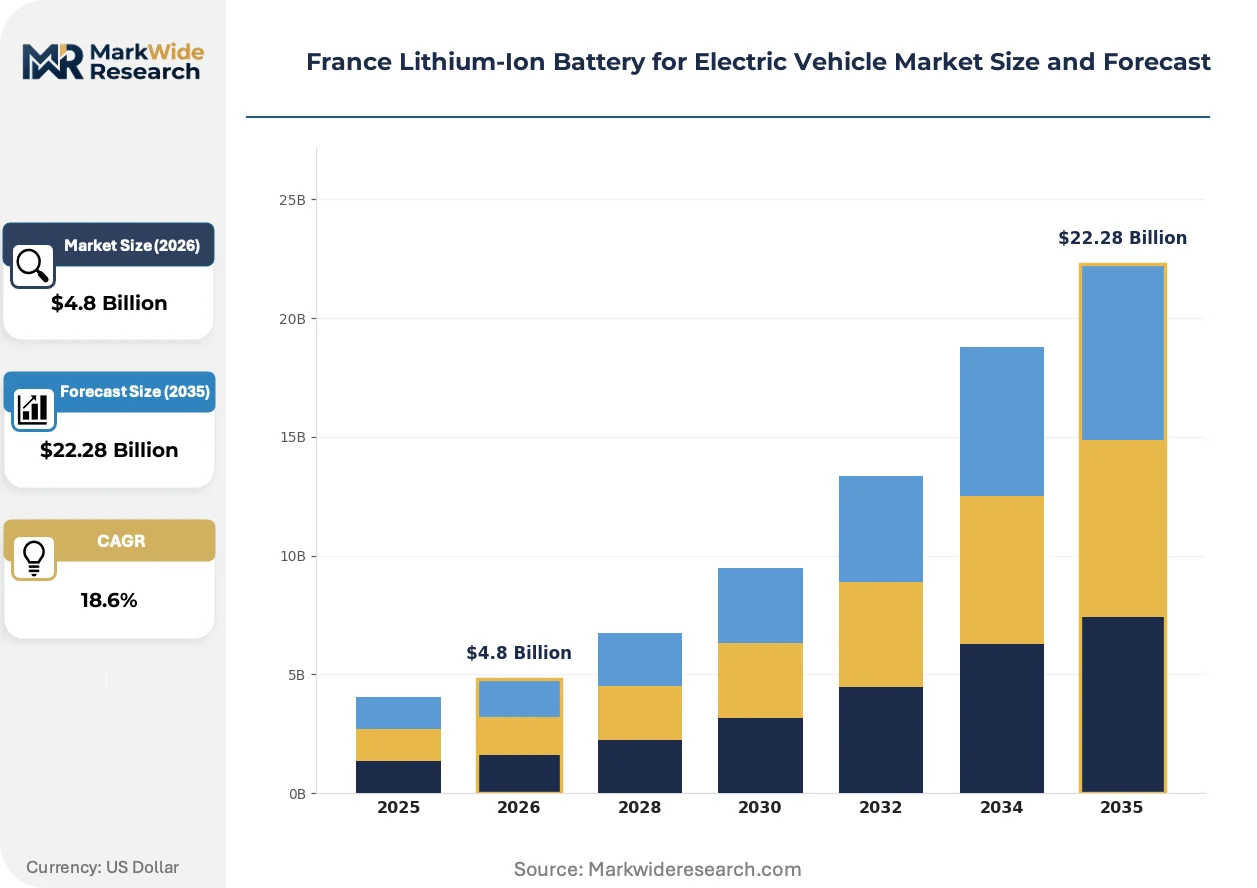
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Prismatic, Pouch, Customized End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Technology: NMC, LFP, NCA, Solid-State Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | Automotive Cells Company, Verkor, Saft Groupe SA, LG Energy Solution Ltd, Contemporary Amperex Technology Co Limited, Panasonic Holdings Corporation, BYD Company Limited, Automotive Energy Supply Corporation, Envision AESC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Lithium-Ion Battery for Electric Vehicle Market Trends and Innovations
Cell manufacturing processes are converging with digital quality systems and renewable energy integration, reshaping how French suppliers compete on compliance and cost simultaneously.
Prismatic cell formats are digitizing pack-level engineering workflows through integrated thermal management and battery management system architectures. French OEM procurement teams specify these formats for their efficient space utilization and modular serviceability. The technology is digitizing how vehicle platforms achieve range targets without redesigning chassis structures.
France's national implementation of the EU Battery Regulation enforces minimum recycled lithium and cobalt thresholds through ANSM-coordinated market surveillance. Cell importers must submit carbon footprint declarations and supply chain due diligence documentation before CE marking authorization. Domestic gigafactory projects are responding by anchoring cathode precursor partnerships within the EU economic zone.
French automotive OEMs are consolidating direct supplier relationships to control chemistry specifications and delivery timelines. Volume commitments are replacing spot market purchases, with long-term offtake agreements now standard for NMC and LFP formulations. This pattern is most visible among Stellantis-aligned suppliers securing dedicated capacity from ACC and Verkor facilities.
France Lithium-Ion Battery for Electric Vehicle Market Segmentation
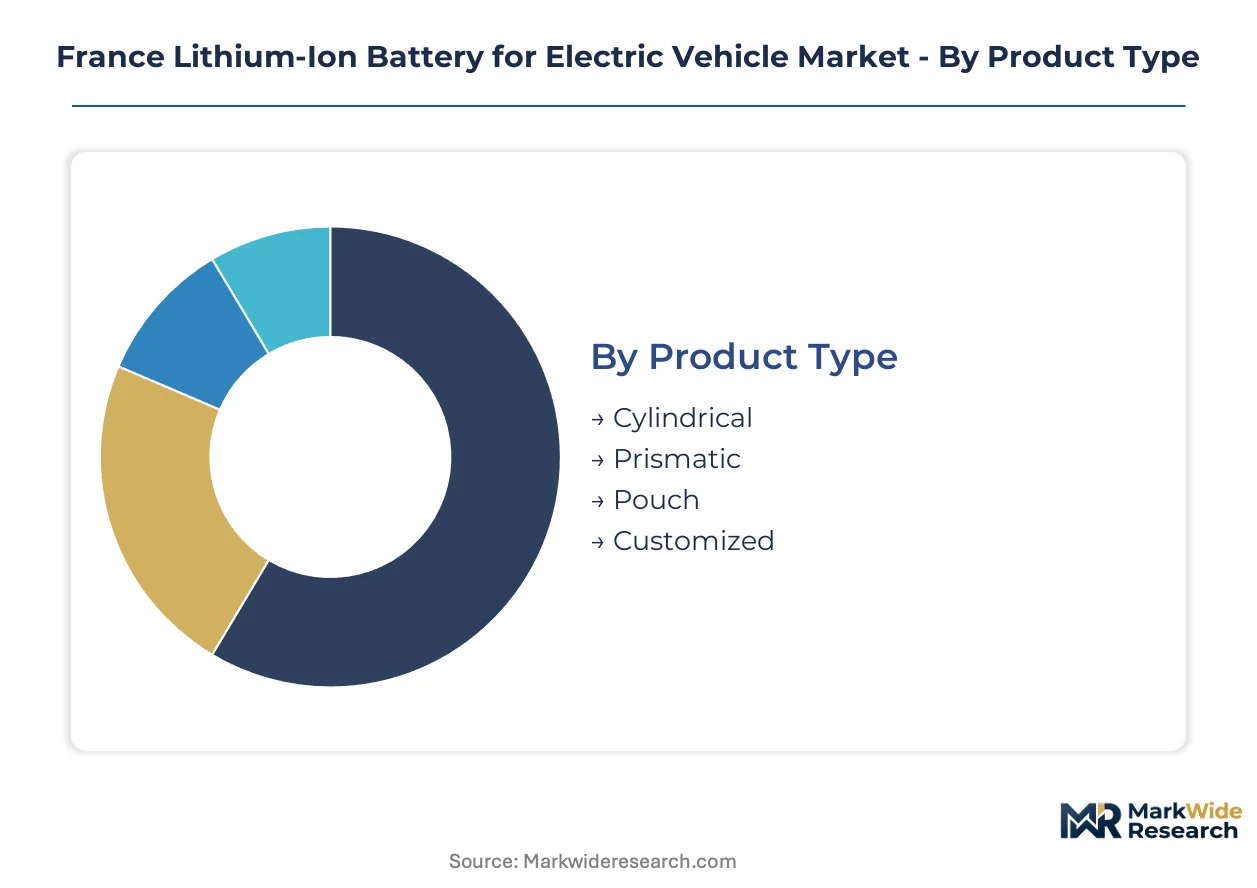
French OEM procurement teams segment battery supply by form factor, chemistry, and channel to align pack engineering with platform economics. Each dimension carries distinct warranty obligations and service lifecycle implications that shape supplier selection criteria.
Product Type:
After-sales service intensity varies sharply across cell geometries, with prismatic formats requiring specialized thermal management recalibration and cylindrical designs enabling modular swap programs at dealership networks.
- Prismatic:Rectangular aluminum-cased cells with stacked electrode layers dominate French OEM procurement for their efficient pack-level space utilization and integrated cooling channel compatibility. Stellantis and Renault specify prismatic formats for their dedicated BEV platforms manufactured at Douai and Maubeuge facilities, where thermal management integration reduces assembly complexity.
- Cylindrical:Rolled electrode jellyrolls in steel cans offer mature manufacturing economics and automated production scalability. The format concentrates demand among fleet operators and aftermarket retrofit providers seeking standardized replacement protocols across mixed vehicle populations.
- Pouch:Flexible polymer-laminated cells with stacked electrodes enable thin-profile pack designs for hybrid architectures where packaging space constraints dominate. French premium SUV platforms utilize pouch cells for their specific energy advantages in floor-integrated battery layouts.
- Customized:Bespoke cell dimensions and terminal configurations serve low-volume specialty vehicle manufacturers and motorsport applications with non-standard chassis constraints.
By volume, prismatic leads. By growth pace, cylindrical is climbing the fastest as fleet electrification standardizes on serviceable formats.
End User:
Cost tier stratification separates capital-intensive OEM integration projects from working-capital-light aftermarket and fleet channels with diverging payment terms and volume commitments.
- OEMs:Direct supply relationships with Stellantis, Renault, and Alpine specify chemistry, form factor, and delivery cadence through multi-year offtake agreements. ACC and Verkor anchor their capacity planning around these volume commitments with qualification timelines extending 18-24 months.
- Fleet Operators:Postal services, utility fleets, and ride-hail platforms procure LFP-based packs through leasing structures emphasizing cycle longevity over energy density. TotalEnergies' fleet solutions division coordinates aggregated demand across municipal and corporate accounts.
- Aftermarket Providers:Independent service networks source replacement modules for out-of-warranty vehicles, with demand concentrating on popular legacy models from Renault Zoe and Peugeot iOn lineages.
- Dealerships:Authorized retailer networks handle warranty battery replacements and software updates, capturing service revenue from OEM-mandated maintenance programs.
By revenue concentration, OEMs dominate. By margin expansion, fleet operators are gaining share fastest as electrification mandates accelerate replacement cycles.
Technology:
Maturity curves separate commercially deployed liquid electrolyte systems from pre-commercial solid-state architectures with diverging manufacturing readiness and certification timelines.
- NMC:Nickel-manganese-cobalt layered oxide cathodes deliver premium energy density for long-range passenger applications. French OEMs specify high-Ni formulations for C-segment and above, though cobalt supply constraints and REACH chemical restrictions are accelerating alternative chemistry evaluation.
- LFP:Lithium iron phosphate olivine structures trade energy density for thermal stability and cost predictability. The chemistry is displacing NMC in entry-level passenger and urban delivery segments where daily range requirements remain modest.
- NCA:Nickel-cobalt-aluminum formulations occupy a narrowing niche among performance-oriented applications requiring specific power output.
- Solid-State:Ceramic or sulfide electrolyte architectures promise energy density step-changes and enhanced safety profiles. The technology remains in pilot production with French automotive R&D consortia monitoring manufacturing scalability before platform integration decisions.
By installed capacity, NMC retains leadership. By technology transition momentum, LFP is expanding most quickly as cost stability outweighs energy density in procurement criteria.
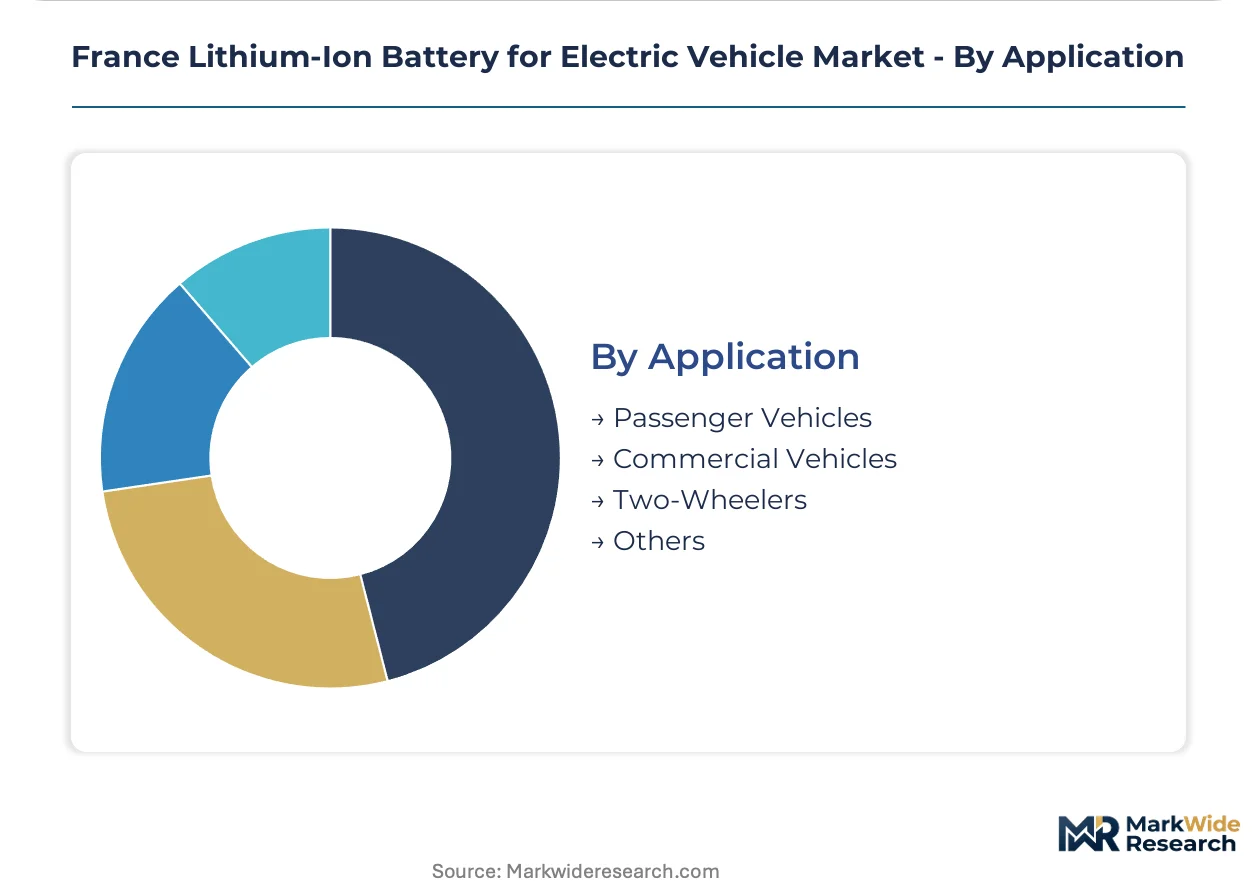
Application:
Supply concentration differs across vehicle classes with passenger platforms driving cell standardization and commercial segments fragmenting around duty-cycle-specific requirements.
- Passenger Vehicles:C-segment hatchbacks, SUVs, and premium sedans absorb the majority of French cell demand with pack capacities ranging from 50-100 kWh. Renault's Megane E-Tech and Stellantis' STLA Medium platform anchor volume forecasts for ACC's Douai gigafactory.
- Commercial Vehicles:Light commercial vans and medium-duty trucks require durable cycling performance under variable load conditions. The segment is fragmenting around depot-charging versus opportunity-charging architectures with diverging pack sizing.
- Two-Wheelers:Electric motorcycles and scooters utilize smaller-format cells with distinct safety certification pathways through France's national market surveillance authority.
- Others:Specialty applications including off-highway equipment and marine propulsion utilize adapted automotive cell formats with modified thermal management.
By manufacturing scale, passenger vehicles lead. By electrification mandate intensity, commercial vehicles are gaining share fastest as urban access restrictions tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Dunkirk's deep-water access and rail connections to European industrial corridors anchor northern France's emergence as a cell manufacturing gateway. Grid interconnections with Belgium and Germany enable cross-border renewable energy sourcing for carbon-intensive formation processes.
Germany
Volkswagen Group's PowerCo subsidiary and BMW's cell procurement commitments drive cathode material demand through the Rhine-Ruhr logistics corridor. The KBA enforces UNECE R100 battery safety certifications for all imported modules. Production investment clusters around Salzgitter and Erfurt, where PowerCo's gigafactory anchors a supplier ecosystem of separator and electrolyte specialists.
Spain
SEAT-Volkswagen's Martorell electrification and Renault's Valladolid battery assembly create dual demand centers for NMC and LFP formulations. Spain's national recovery plan allocates public capital to Galicia and Extremadura lithium extraction projects. The Basque Country hosts electrolyte additive production facilities serving Iberian and French gigafactories.
Italy
Stellantis' Mirafiori complex and Ferrari's electrification roadmap concentrate premium cell demand in Piedmont and Emilia-Romagna. The Ministry of Enterprise enforces EU Battery Regulation compliance timelines through national market surveillance coordination. Lombardy's chemical industry corridor near Milan supplies cathode precursors to ACC's supply chain.
Poland
LG Energy Solution's Wrocław facility and emerging European cell demand position Poland as a volume manufacturing alternative to Asian imports. The Polish Investment and Trade Agency administers gigafactory incentive packages tied to local content thresholds. Lower Silesia's industrial zones attract separator and copper foil suppliers from South Korea and Japan.
France Lithium-Ion Battery for Electric Vehicle Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct tiers: established Asian conglomerates with European distribution networks, emerging European gigafactory operators securing domestic OEM offtake, and industrial battery specialists pivoting toward automotive traction applications. Strategic archetypes include chemistry-agnostic volume producers, vertically integrated national champions, and high-performance niche formulators. Dominant competitive moves encompass long-term capacity reservation agreements with automotive OEMs and backward integration into cathode precursor refining.
Within the European gigafactory tier, Automotive Cells Company exemplifies the consortium-structured national champion archetype, while Verkor occupies the independent volume challenger position. Among established industrial specialists, Saft Groupe SA represents the high-performance formulation pivot archetype, leveraging legacy electrochemical expertise into automotive-qualified cell architectures. These three entities anchor the domestic supply base against Korean and Chinese import competition.
| Leading Market Players |
|---|
| Automotive Cells Company |
| Verkor |
| Saft Groupe SA |
| LG Energy Solution Ltd |
| Contemporary Amperex Technology Co Limited |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| Automotive Energy Supply Corporation |
| Envision AESC |
| Others |
Pricing and Supply Chain Analysis
Gigafactory undercapacity in northern France is compressing supplier margins while amplifying pricing power for qualified domestic cell producers with secured OEM offtake agreements. ACC and Verkor's constrained output relative to Stellantis and Renault demand volumes is forcing buyers into long-term contract structures that sacrifice flexibility for supply security.
Pricing Analysis
Volume-discount tiering structures separate OEM direct procurement from fleet operator leasing arrangements and aftermarket spot purchases. Three-tier pricing stratification across premium NMC, standard LFP, and economy refurbished modules reflects certification grade and cycle warranty differentiation. Cost compression in entry-level LFP segments is intensifying because Chinese import competition and domestic gigafactory ramp-up are expanding effective supply. Fleet operators exhibit the highest price sensitivity, while premium OEM platforms prioritize energy density over unit economics.
Supply Chain Analysis
Extended payment terms from French OEMs are cascading stress onto cathode precursor suppliers, accelerating supply-chain finance facility adoption among Korean and Chinese material providers. Cell production draws from concentrated cathode active material sources in China, South Korea, and Japan, with lithium hydroxide feedstock anchored in Chile, Australia, and Argentina. Single-source vulnerability around high-Ni cathode formulations creates structural exposure to export license restrictions. Distribution runs through port-centric logistics corridors at Dunkirk and Antwerp, with rail links to Douai and Maubeuge assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
French OEM consolidation around Stellantis and Renault is shifting buyer power toward volume-commitment leverage, squeezing supplier margin structures and accelerating qualification timeline compression for new cell entrants.
For Market Incumbents: Build chemistry-agnostic production flexibility as the defensive moat against LFP displacement of NMC in entry-level segments. ACC should anchor backward integration into cathode precursor refining through its TotalEnergies partnership to secure EU Battery Regulation recycled content compliance. Verkor must accelerate Dunkirk capacity commissioning to defend against Korean import price competition before 2026 volume windows close. For New Entrants and Emerging Players: Second-life stationary storage applications for retired automotive packs represent the most penetrable entry point for capital-light market participation without gigafactory scale requirements. Fleet operator LFP procurement through TotalEnergies' aggregated demand platform offers faster qualification pathways than OEM direct supply. Target aftermarket service networks for out-of-warranty Renault Zoe and Peugeot iOn replacements as a channel-building strategy. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state pilot production facilities, favoring selective exposure over broad sector allocation. Long-term viability over a decade horizon rests on EU Battery Regulation compliance infrastructure rather than pure manufacturing scale. Watch for ANSM enforcement discretion on CE marking timelines as the critical inflection signal for domestic versus import competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | ACC's TotalEnergies partnership secures EU-sourced recycled content for regulatory compliance. |
| Gigafactory Capacity Expansion | Verkor's Dunkirk facility anchors northern France's industrial cluster with port and grid access. |
| LFP Chemistry Platform Diversification | Fleet operator demand is displacing NMC in entry-level segments where cost stability dominates. |
| Second-Life Stationary Storage Deployment | Retired automotive packs extend value capture through grid-scale applications beyond vehicle life. |
| Direct OEM Supply Relationship Consolidation | Stellantis and Renault are replacing spot purchases with multi-year offtake agreements. |
Research Methodology
A standing panel of gigafactory operations directors, OEM platform engineers, cathode material procurement leads, and ANSM regulatory coordinators provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from EU Battery Regulation implementation documents, French customs trade statistics, and SEC filings of listed battery producers. Bottom-up cell production capacity modeling triangulated against top-down OEM electrification volume commitments.
Scenario-bracketing framed optimistic and conservative demand trajectories across the projection horizon without fixing specific year-endpoints. Segmentation dimensions modeled include cell form factor, chemistry type, end-user channel, and vehicle application class alongside regional production cluster economics. CAGRs derived from installed capacity ramp schedules and OEM platform launch cadences, with lithium carbonate price volatility and EU carbon border adjustment implementation treated as sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial electricity pricing or Chinese export financing terms would shift the trajectory. Forecasts reflect documented assumptions on gigafactory commissioning schedules and regulatory enforcement timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Lithium Battery in Myanmar Market