
 Lithium Ion Secondary Battery Sales Market | 2026-2036
Lithium Ion Secondary Battery Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Secondary Battery Sales Market Insights
OEM-direct supply contracts is reshaping how cell manufacturers secure volume commitments and margin stability. CATL leverages its captive mining partnerships and integrated cathode production to sustain cost leadership across prismatic and cylindrical formats. LG Energy Solution anchors its position through dedicated gigafactory lines in Europe and North America, competing on localized supply rather than pure scale. Samsung SDI differentiates via silicon-anode R&D intensity and premium positioning in the automotive segment.
Lithium ion secondary battery sales encompass rechargeable electrochemical cells utilizing lithium-ion intercalation chemistry, typically operating at nominal voltages of 3.2–3.7 V with energy densities ranging from 150–300 Wh/kg depending on cathode composition and cell format. These systems store and discharge electrical energy through reversible lithium-ion movement between graphite or silicon-blend anodes and metal oxide cathodes, serving as the dominant power source for electric mobility, portable electronics, and grid-scale energy storage. Prismatic cells capture the dominant share of automotive traction battery demand due to superior pack-level volumetric efficiency and thermal management integration. Cylindrical formats retain manufacturing scale advantages in consumer electronics and certain performance-oriented automotive applications. Solid-state configurations represent the fastest-growing development trajectory, though commercial volume remains constrained by manufacturing process maturity and electrolyte interface stability challenges.
The EU Battery Regulation and REACH compliance frameworks are mandating recycled content thresholds and supply chain due diligence, directly elevating compliance costs for non-integrated producers while advantaging firms with closed-loop material recovery. China's GB standards and dual carbon goals enforce domestic cell performance benchmarks and carbon intensity caps that shape export eligibility and factory siting decisions. Japan's METI battery strategy directs national funding toward solid-state commercialization timelines, influencing R&D allocation across Panasonic and Toshiba operations. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of manufacturing location economics and product certification pathways.
Market Dynamics
The EU Battery Regulation's carbon footprint disclosure mandate is forcing cell manufacturers to restructure procurement networks and invest in supply chain traceability infrastructure to maintain market access.
Growth Catalysts
- EU Battery Regulation mandates:Carbon footprint thresholds and recycled content requirements create compliance-driven replacement cycles across European automotive OEM supply chains.
- Silicon-anode chemistry advances:Higher energy density configurations enable extended-range electric vehicle platforms without pack weight penalties.
- China:Integrated manufacturing ecosystems combining cathode production with cell assembly compress cost structures for export-competitive pricing.
Market Restraints
- Lithium carbonate volatility:Concentrated spodumene and brine processing in Australia and Chile exposes cell producers to input cost swings.
- Solid-state manufacturing immaturity:Electrolyte interface stability and dry electrode processing constraints limit commercial scale deployment.
- REACH compliance friction:Extended chemical registration timelines and restricted substance lists delay new electrolyte solvent qualification.
Strategic Opportunities
- India:Production-linked incentive schemes for advanced chemistry cell manufacturing attract greenfield gigafactory investment from established Asian producers.
- Grid-scale stationary storage:Utility procurement of long-duration battery systems opens volume channels beyond automotive traction demand.
- Second-life battery repurposing:Retired electric vehicle packs cascade into stationary applications, creating circular revenue streams under EU Battery Regulation recycling targets.
Industry Challenges
- Dry electrode coating expertise:Solvent-free manufacturing processes require process engineering talent scarce outside Japan and South Korea.
- UN 38.3 certification timelines:Extended lithium cell transport safety testing creates inventory holding costs and launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Secondary Battery Sales Market |
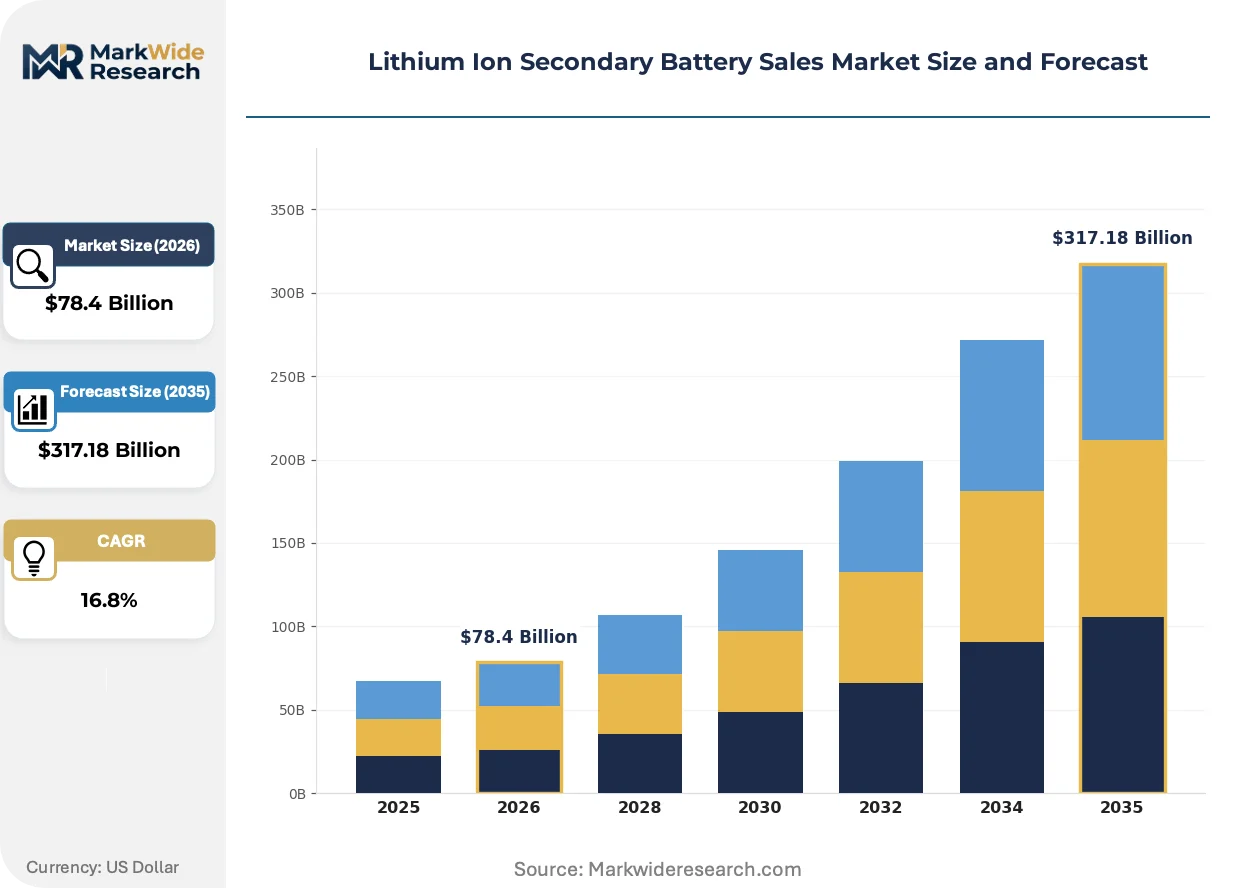
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $317.18 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Polymer, Solid-State End User: Consumer Electronics, Automotive, Industrial, Energy Storage Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | CATL, LG Energy Solution, Panasonic Holdings, BYD Company, Samsung SDI, SK On, Toshiba, Sony, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Secondary Battery Sales Market Trends and Innovations
Cell chemistry and manufacturing processes are undergoing parallel transformation as energy density targets tighten and regulatory compliance costs reshape competitive economics.
Solid-state electrolyte technology is migrating from laboratory demonstration to pilot production lines. Automotive OEMs in Germany and Japan are qualifying sulfide and oxide ceramic separators for 2027 platform integration. This transition is compressing incumbent liquid electrolyte R&D budgets while concentrating capital allocation among firms with dry room infrastructure.
China's GB standards for battery cell performance and carbon intensity are tightening export eligibility criteria. Domestic producers must demonstrate compliance with dual carbon goals to access overseas markets, forcing facility siting decisions toward renewable-powered manufacturing clusters. European cell importers now require third-party verification of production carbon footprints.
Fleet operators and utility buyers are consolidating procurement through direct OEM contracts rather than distributor channels. Long-term offtake agreements with minimum volume guarantees replace spot market purchasing in North American and European markets. This concentration is visible most acutely in California's utility-scale storage procurement and Germany's commercial vehicle electrification programs.
Lithium Ion Secondary Battery Sales Market Segmentation
Segmentation in the Lithium Ion Secondary Battery Sales Market reveals how cell format, application intensity, and procurement channel each dictate divergent margin structures and technical specifications. Understanding these dimensions allows manufacturers to align production capacity with the specific energy density, cycle life, and certification requirements of each demand cluster.
Product Type:
Cost tier positioning across cell formats determines which manufacturers capture automotive OEM contracts versus consumer electronics volume.
- Prismatic:Rectangular aluminum or steel-cased cells with layered electrode stacks deliver superior pack-level volumetric efficiency. Demand concentrates in China where CATL and BYD supply domestic automotive OEMs with integrated thermal management solutions. The format dominates electric vehicle traction battery procurement due to simplified module assembly and cooling channel integration.
- Cylindrical:Rolled jellyroll construction in standardized diameters enables high-speed automated winding and consistent cell-to-cell performance. Tesla's 4680 format and legacy 18650/21700 designs retain manufacturing scale advantages in performance-oriented automotive applications and premium power tools. Cylindrical formats benefit from mature supply chains for precision steel can production and automated sorting equipment.
- Polymer:Pouch cells with laminated aluminum packaging offer maximum design flexibility for thickness and footprint customization. Wearable electronics and ultra-thin laptop manufacturers in South Korea and Taiwan specify polymer formats for space-constrained applications.
- Solid-State:Ceramic or sulfide electrolyte configurations replace flammable liquid electrolytes with inorganic ionic conductors. Toyota and QuantumScape pilot lines in Japan and California are qualifying solid-state cells for premium automotive platforms requiring enhanced safety margins.
Prismatic holds installed capacity. Solid-state is rotating up the share rankings.
End User:
Application intensity shapes the divergence between high-cycle industrial requirements and weight-optimized consumer specifications.
- Automotive:Traction batteries for battery electric and plug-in hybrid vehicles demand 3000+ cycle life at 80% depth of discharge. European OEMs in Germany and Sweden specify nickel-rich cathode chemistries for extended-range platforms subject to EU Battery Regulation carbon footprint disclosure. The segment commands the highest per-cell value and drives cathode material innovation.
- Energy Storage:Grid-scale and residential battery systems prioritize calendar life over energy density, accepting lower-cost lithium iron phosphate chemistries. Utility procurement in California and Texas favors containerized systems with 20-year service life projections and fire safety certifications from UL and IEC.
- Consumer Electronics:Smartphones, laptops, and tablets require compact formats with rapid charge capability. Southeast Asian contract manufacturers specify cobalt-containing cathodes for energy density maximization in millimeter-thin devices.
- Industrial:Forklifts, automated guided vehicles, and mining equipment utilize heavy-duty cells with enhanced vibration tolerance. German industrial OEMs specify automotive-grade cells with modified battery management systems for continuous operation environments.
Automotive commands revenue concentration. Energy Storage is expanding most quickly.
Capacity:
Volume tier segmentation aligns manufacturing equipment scale with the distinct electrode coating widths and formation protocols of each capacity class.
- High Capacity:Cells exceeding 100 Ah enable simplified pack architectures with fewer parallel connections. Electric bus manufacturers in Shenzhen and Santiago specify high-capacity prismatic cells to minimize cell count and welding joints in double-decker platforms.
- Medium Capacity:The 20-100 Ah range balances manufacturing throughput with application flexibility. Residential energy storage systems and commercial electric vehicles in the Netherlands and Australia standardize on medium-capacity formats for modular scalability.
- Low Capacity:Sub-5 Ah cylindrical and polymer cells serve power tools, medical devices, and handheld electronics. Japanese power tool manufacturers in Nagoya maintain dedicated supply agreements for high-discharge-rate 18650 variants.
- Ultra High Capacity:Prototype cells exceeding 300 Ah target containerized stationary storage and maritime applications. CATL and BYD are sampling ultra-high-capacity cells for offshore wind integration projects in the North Sea.
High Capacity dominates gigafactory output allocation. Ultra High Capacity is climbing the fastest.
Distribution Channel:
Customer type and order scale determine whether cells flow through distributor markup structures or direct OEM integration.
- Direct Sales:Long-term offtake contracts with minimum volume guarantees link cell manufacturers to automotive OEMs and utility developers. Volkswagen, Ford, and Hyundai negotiate direct supply agreements spanning 5-10 year horizons with pricing indexed to lithium carbonate benchmarks.
- Wholesalers:Regional distributors aggregate demand from small-scale energy storage installers and industrial equipment refurbishers. German and Italian wholesalers stock medium-capacity prismatic cells for solar-plus-storage retrofit contractors.
- Online Retail:E-commerce platforms serve hobbyist, repair technician, and small manufacturer demand for replacement cells and development kits. Amazon and Alibaba channels move cylindrical cells for DIY powerwall builders and robotics startups.
- Offline Retail:Electronics retailers and specialty battery stores stock consumer replacement cells for laptops, power tools, and mobility devices. Best Buy and MediaMarkt locations carry polymer cells for immediate replacement in premium laptops.
Direct Sales holds contract value concentration. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in lithium-ion cell exports, while the Rotterdam-BASF pipeline corridor anchors European cathode precursor logistics. Grid interconnects between Sichuan's hydroelectric basins and coastal manufacturing clusters enable low-carbon production at scale.
China
Domestic EV procurement from BYD and NIO absorbs 60% of prismatic cell output. GB standards enforcement through MIIT mandates carbon intensity disclosure for export eligibility. The Yangtze River Delta cluster around Ningbo and Suzhou hosts integrated cathode-to-cell facilities serving Volkswagen and Tesla assembly plants.
Germany
BMW and Mercedes-Benz electrification timelines drive 40 GWh of annual cell demand. EU Battery Regulation carbon footprint thresholds force supply chain restructuring through ECHA compliance frameworks. The North Rhine-Westphalia corridor between Düsseldorf and Mönchengladbach concentrates gigafactory investment from Korean and Chinese producers.
United States
IRA production tax credits redirect cathode supply chain investment toward domestic processing. EPA tailpipe standards accelerate fleet electrification mandates in California and New York. The Texas Triangle between Austin, Dallas, and Houston anchors Tesla's 4680 production and emerging SPAC-backed cell ventures.
South Korea
Hyundai-Kia platform expansion requires 30% annual cell volume growth through 2027. METI-aligned national funding directs solid-state R&D through Samsung SDI and SK On. The Gyeonggi-do province surrounding Seoul hosts dedicated dry room infrastructure for silicon-anode pilot lines.
Japan
Toyota's solid-state commercialization timeline concentrates sulfide electrolyte development. JIS standards through METI enforce safety certification protocols exceeding UN 38.3 baselines. The Nagoya-Toyota City corridor maintains precision winding equipment supply chains for cylindrical format production.
Lithium Ion Secondary Battery Sales Market Competitive Landscape
On the supply side, the industry is consolidating around integrated cathode producers with captive mining access and dedicated automotive OEM lines. Tier-one cell manufacturers now compete primarily on supply chain traceability and localized production rather than pure manufacturing scale. Two strategic archetypes dominate: integrated mining-to-cell conglomerates controlling raw material cost structures, and technology-specialized firms competing on energy density breakthroughs. Competitive moves center on backward integration into lithium hydroxide processing and joint venture structuring for regional gigafactory access.
Within the integrated conglomerate tier, CATL and BYD exemplify upstream control over spodumene conversion and cathode precursor synthesis. LG Energy Solution occupies a position between scale-driven cost leadership and premium-tier silicon-anode specialization, reflecting the Korean chaebol structure's dual-market orientation.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Holdings |
| BYD Company |
| Samsung SDI |
| SK On |
| Toshiba |
| Sony |
| LG Chem |
| Others |
Pricing and Supply Chain Analysis
Australian spodumene and Chilean brine processing concentration hands raw material pricing power to a narrow upstream tier, compressing cathode producer margins while cell manufacturers with captive lithium hydroxide conversion capture downstream value pools. Automotive OEMs leverage long-term offtake contracts to lock in volume-discount tiering, forcing non-integrated producers into spot market exposure.
Pricing Analysis
Volume-discount tiering structures separate automotive OEM direct contracts from distributor spot purchases. Pricing stratifies across premium automotive-grade cells with full EU Battery Regulation carbon disclosure, standard industrial formats with basic UN 38.3 certification, and economy-tier consumer electronics cells sourced through Asian trading houses. Cost compression in the standard tier is intensifying because Chinese producers with integrated cathode plants are exporting at export-competitive pricing. Energy storage developers show highest price sensitivity due to project finance constraints, while German automotive OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes limiting semiconductor manufacturing equipment flows are constraining dry electrode coating machinery availability outside Japan and South Korea. Geographic supply concentration centers on China for cathode precursor synthesis, South Korea for electrolyte formulation, and Japan for precision winding equipment. Raw material dependencies rest on Australian spodumene, Chilean lithium carbonate, and Indonesian nickel matte. Single-source vulnerability in sulfide electrolyte precursor supply creates qualification bottlenecks for solid-state pilot lines. Distribution runs through direct OEM contracts for automotive traction demand and regional wholesalers for industrial aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as fleet electrification mandates and utility storage procurement create sustained volume absorption channels beyond consumer electronics saturation.
For Market Incumbents: Harden supply chain traceability infrastructure to meet EU Battery Regulation carbon footprint disclosure thresholds before competitor qualification. Deepen backward integration into lithium hydroxide processing to offset spodumene price volatility and defend margin position against Chinese integrated producers. Lock in dedicated automotive OEM lines through joint venture structures in Europe and North America to preempt localization requirements. For New Entrants and Emerging Players: Pursue India's production-linked incentive schemes for advanced chemistry cell manufacturing as the most penetrable geography with established Korean and Japanese offtake interest. Target grid-scale stationary storage applications in Texas and California where utility procurement runs through developer channels rather than entrenched automotive supply relationships. Lead with silicon-anode or solid-state technology differentiation to bypass scale disadvantages against incumbent cost structures. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap cathode precursor specialists with pilot-scale dry electrode coating capability and automotive OEM qualification pipelines. Long-term viability over the next decade hinges on positioning ahead of solid-state commercialization timelines and EU recycled content mandates. Watch for inflection signals in sulfide electrolyte interface stability breakthroughs at Japanese pilot facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Hydroxide | Captive conversion capacity insulates CATL and BYD from Australian spodumene price swings. |
| Joint Venture Gigafactory Structuring | LG Energy Solution's European partnerships with BMW satisfy EU Battery Regulation localization. |
| Solid-State Pilot Line Qualification | Toyota's sulfide electrolyte development concentrates METI funding and OEM platform access. |
| Carbon Footprint Certification Investment | Third-party verification infrastructure unlocks export eligibility under tightening GB standards. |
| Second-Life Battery Repurposing Networks | Retired EV pack cascading into stationary storage creates circular revenue under EU recycling targets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from cathode material suppliers, and IEA battery demand projections. Primary interviews engaged cell manufacturing executives, automotive OEM platform engineers, utility procurement officers, and lithium mining operations managers. Secondary validation drew from MIIT production statistics, ECHA regulatory filings, and UN Comtrade battery export records. Bottom-up cell shipment aggregation triangulates against top-down electric vehicle production and energy storage deployment estimates.
Forecast inputs span cell format segmentation, cathode chemistry tiering, end-use application intensity, and regional regulatory cluster alignment. The analytical framework models prismatic, cylindrical, polymer, and solid-state trajectories across automotive traction, energy storage, consumer electronics, and industrial equipment demand. CAGRs derive from installed capacity buildout schedules, OEM electrification platform timelines, and utility procurement pipeline visibility. Industry-specific inputs include lithium carbonate price elasticity coefficients and solid-state manufacturing yield improvement curves.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting project finance for utility storage, or lithium spot price volatility beyond historical bands, would shift the trajectory. Forecasts reflect assumptions around EU Battery Regulation enforcement timelines and Chinese dual carbon goal implementation. Material shifts in solid-state electrolyte interface stability breakthroughs or sulfide precursor supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Lithium-Air Battery Market