
 Global Pin Type Lithium-Based Battery Market | 2026-2036
Global Pin Type Lithium-Based Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pin Type Lithium-Based Battery Market Outlook
The gap between consumer-grade cylindrical formats and medical-grade pin cells is narrowing as miniaturization demands converge across sectors. Panasonic Holdings Corporation leverages its century-long electrode manufacturing heritage to sustain premium positioning in implantable device power systems. LG Energy Solution competes through dedicated cleanroom production lines that anchor South Korean supply to European medical OEMs. Samsung SDI differentiates via proprietary separator technologies that extend cycle stability in compact form factors.
Pin type lithium-based batteries are compact cylindrical cells featuring axial terminal pins rather than radial can contacts, typically manufactured through precision winding of lithium cobalt oxide or nickel manganese cobalt cathodes paired with graphite anodes, then sealed in nickel-plated steel housings with glass-to-metal feedthrough terminals; their primary purpose is delivering stable discharge profiles in space-constrained, high-reliability devices such as pacemakers, tire pressure monitors, and industrial sensors. Rechargeable Cells command widening application scope as wireless medical implants shift from primary to secondary cell architectures, while Specialty Cells occupy the deepest margin pools due to qualification barriers and lot-traceability requirements. The LFP chemistry segment within the Technology dimension is accelerating in industrial equipment deployments where thermal runaway tolerance outweighs energy density priorities.
The FDA enforces stringent quality system regulations for lithium cells destined for active implantable medical devices, while China's SAMR administers GB 31241 safety certifications that govern domestic pin cell circulation. Japan's METI coordinates with PMDA to align battery reliability standards with pharmaceutical device approvals, creating multi-layered compliance pathways for cross-border suppliers. Stakeholders must monitor evolving chemistry-specific transportation restrictions from ICAO and IATA, as pin cell energy density thresholds trigger differentiated handling protocols that reshape logistics costs and regional sourcing decisions.
Market Dynamics
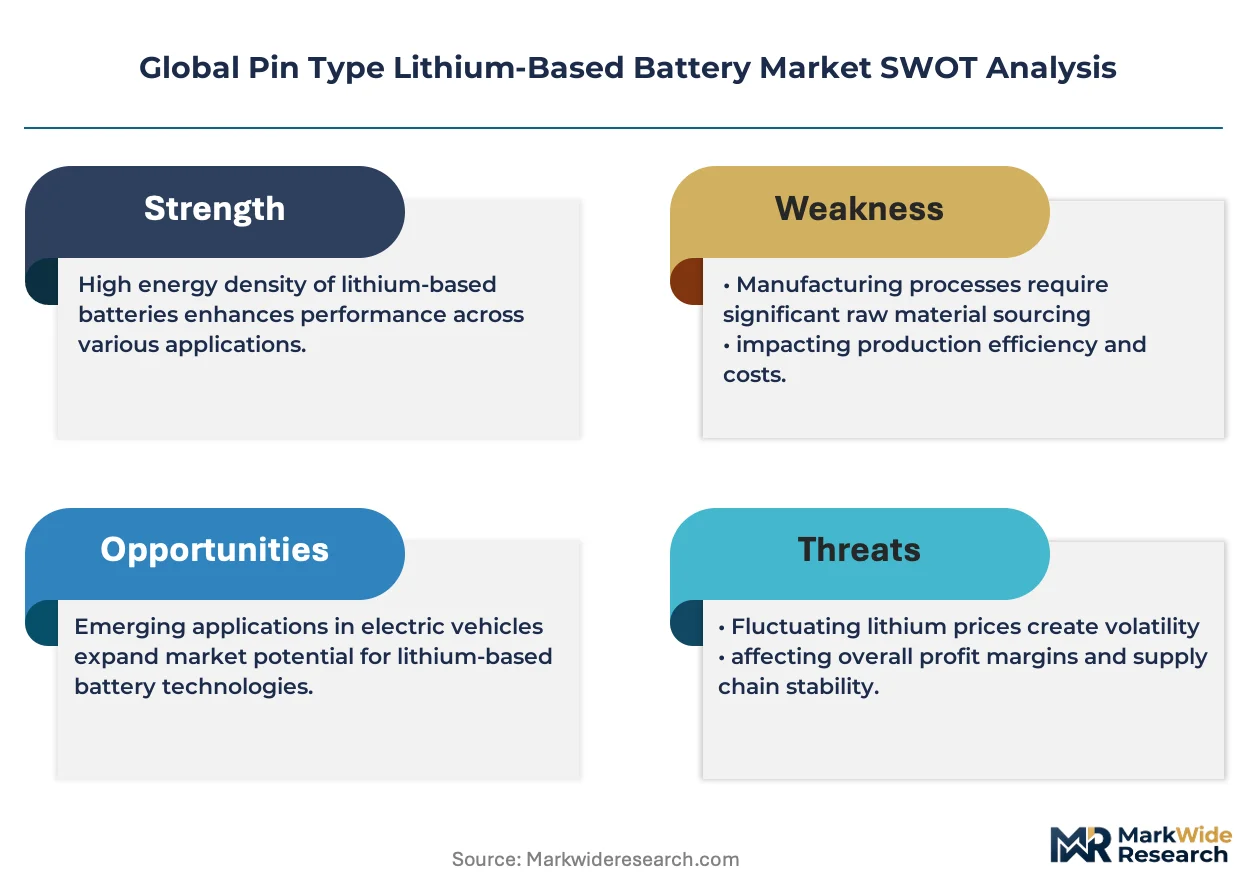
Medical device miniaturization is compressing form factor tolerances to sub-millimeter precision, forcing cell architectures toward axial pin terminals that integrate directly with PCB-mounted interconnects rather than radial can contacts. This structural shift concentrates procurement power among implantable device OEMs who specify lot-traceable cleanroom production.
Growth Catalysts
- Wireless implantable cardiac monitors:Secondary cell architectures in pacemakers and neurostimulators are displacing primary silver oxide systems, expanding addressable volume for rechargeable pin cells.
- Japan's PMDA-METI coordination:Aligned battery-device approval pathways reduce regulatory duplication, accelerating time-to-market for cross-border suppliers targeting Japanese medical OEMs.
- South Korea's Ulsan-Gumi battery belt:Concentrated cathode active material production and specialized winding equipment clusters enable rapid prototyping for premium industrial sensor applications.
Market Restraints
- Cobalt price volatility:NMC cathode formulations remain exposed to DRC supply concentration, compressing margin buffers for mid-tier cell assemblers.
- Cleanroom capex thresholds:ISO 14644 Class 7 certification for medical-grade production lines requires capital outlays that exclude regional second-tier entrants.
- Solid-state substitution timeline:Thin-film lithium polymer alternatives threaten long-term share in ultra-miniature implantables despite current energy density limitations.
Strategic Opportunities
- India's CDSCO medical device rules:New risk-classification frameworks for active implants create first-mover positioning for qualified pin cell suppliers in an underpenetrated surgical device market.
- Industrial IoT sensor networks:Machine condition monitoring in German automotive plants is adopting wireless vibration sensors requiring decade-scale primary cell lifespans.
- EU MDR battery documentation:Enhanced technical file requirements for implantable power sources favor suppliers with pre-existing lot-traceability systems, creating compliance-based switching costs.
Industry Challenges
- Glass-to-metal seal engineering:Hermetic feedthrough design for corrosive electrolyte containment requires specialized metallurgical expertise concentrated among Japanese and Swiss component houses.
- IATA Section II configuration:Pin cell energy density thresholds trigger differentiated cargo handling protocols, fragmenting logistics networks and extending fulfillment timelines to remote clinical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pin Type Lithium-Based Battery Market |
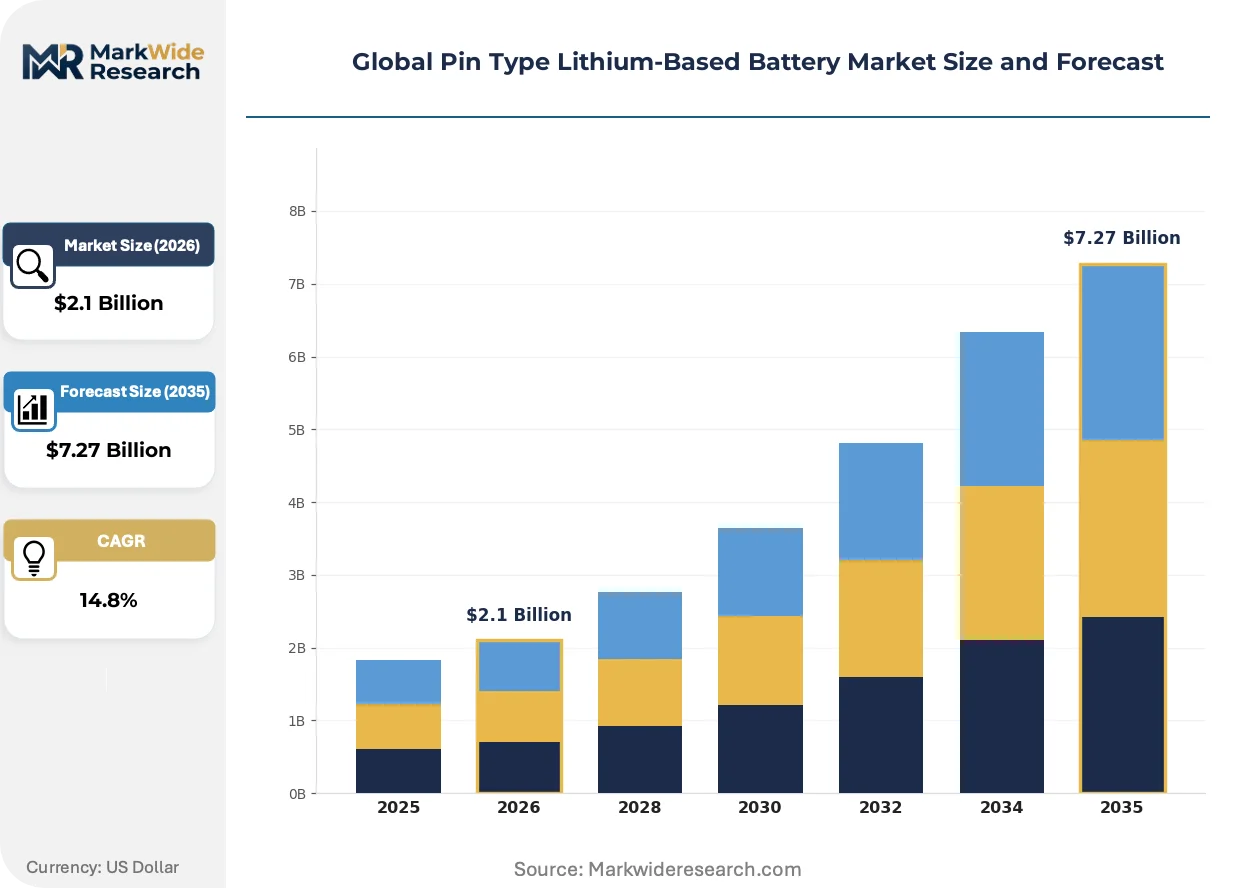
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.27 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cells, Rechargeable Cells, Specialty Cells, Cylindrical Cells End User: Consumer Electronics, Automotive Applications, Industrial Equipment, Renewable Energy Storage Size: Small, Medium, Large, Extra Large Technology: LFP, NMC, NCA, LiCoO2 |
| Companies Covered | Panasonic Holdings Corporation, Aucopo, JNJ, Contemporary Amperex Technology Co., Limited, LG Energy Solution, BYD Company Limited, Samsung SDI, SK On, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pin Type Lithium-Based Battery Market Strategic Shifts
Precision winding automation and laser-welded terminal attachment are collapsing the cost gap between consumer cylindrical formats and medical-grade pin cells, enabling chemistry standardization across reliability tiers.
Silicon-dominant anode formulations are rendering obsolete graphite-based capacity ceilings in compact cylindrical architectures. Implantable neuromodulation device OEMs in Switzerland and Minnesota are qualifying silicon-blend cells for 40% energy density gains. This chemistry transition is compressing the performance premium historically commanded by primary lithium thionyl chloride systems.
China's GB 31241-2022 safety standard revisions are tightening nail penetration and overcharge thresholds for domestic circulation. Cell assemblers serving the Chinese industrial sensor market are migrating toward LFP cathode chemistries to satisfy thermal runaway containment requirements. This regulatory pressure is bifurcating supply chains between export-oriented NMC production and domestic LFP-certified lines.
Buying committees at European medical device OEMs are consolidating supplier panels from twelve to four qualified vendors per chemistry type, compressing qualification timelines and unbundling after-sales technical support into separate service contracts. This concentration is most visible in German and Dutch cardiovascular device manufacturing clusters, where procurement functions now report directly to chief quality officers rather than supply chain directors.
Global Pin Type Lithium-Based Battery Market Segmentation
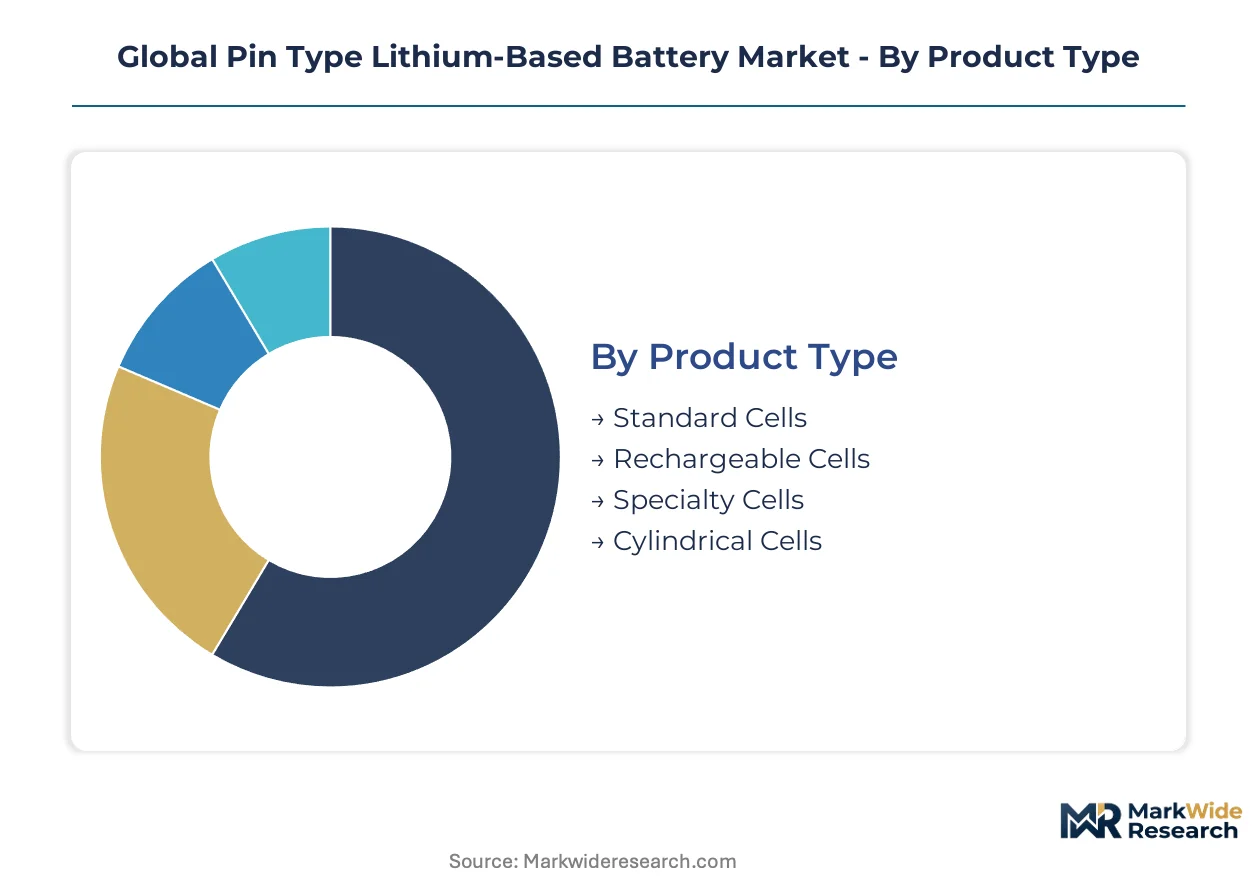
Pin cell procurement cycles vary dramatically across applications, from decade-long implantable device programs to quarterly consumer electronics replenishment. Understanding these velocity differentials enables suppliers to align inventory and qualification investments with segment-specific cash conversion patterns.
Product Type:
Cycle times stretch from 18-month medical qualification timelines for hermetic specialty cells to 6-week consumer-grade cylindrical turnover, compressing working capital efficiency for premium manufacturers.
- Specialty Cells:Glass-to-metal sealed architectures with lot-traceable cleanroom production meet ISO 14644 Class 7 standards for implantable neuromodulation and cardiac rhythm management. Swiss and Minnesota-based OEMs concentrate procurement here, with FDA quality system regulations extending qualification cycles to 24-36 months. These constraints deepen margin pools but limit supplier entry.
- Rechargeable Cells:Secondary lithium-ion architectures with axial pin terminals enable wireless cardiac monitors and neurostimulators to shift from primary silver oxide systems. South Korea's Ulsan-Gumi battery belt anchors production for European medical OEMs, with silicon-dominant anode formulations now displacing graphite capacity ceilings.
- Standard Cells:Non-hermetic cylindrical formats serve industrial sensor networks with 5-7 year primary cell lifespans.
- Cylindrical Cells:Radial can contact designs dominate high-volume consumer applications with compressed procurement cycles.
Specialty Cells dominate installed base value. Rechargeable Cells are where expansion concentrates as wireless implants proliferate.
End User:
Cost tiers stratify sharply, with medical device OEMs absorbing 8-12x premiums over consumer electronics for equivalent cell capacities due to qualification overhead and liability structures.
- Industrial Equipment:Machine condition monitoring in German automotive plants drives demand for decade-scale primary cell lifespans in wireless vibration sensors. China's GB 31241-2022 safety standards are pushing this segment toward LFP chemistries to satisfy thermal runaway containment requirements, bifurcating supply chains between export NMC and domestic LFP-certified lines.
- Automotive Applications:Tire pressure monitoring systems and telematics modules require pin cells with extended temperature tolerance from -40°C to 125°C. South Korean suppliers anchor tier-2 automotive procurement through dedicated cleanroom production lines, with Samsung SDI's proprietary separator technologies extending cycle stability in compact form factors.
- Consumer Electronics:Hearing aids and wearable devices concentrate volume in East Asian manufacturing clusters.
- Renewable Energy Storage:Grid-scale applications remain nascent for pin form factors due to capacity constraints.
Industrial Equipment commands the steepest price premiums. Automotive Applications are climbing the fastest as electric vehicle telemetry requirements multiply.
Size:
Volume concentration follows miniaturization imperatives, with sub-millimeter precision tolerances compressing viable supplier pools as form factors shrink.
- Small:Sub-10mm diameter cells with axial terminal pins integrate directly with PCB-mounted interconnects in implantable cardiac monitors and hearing aids. Japan's PMDA-METI coordination reduces regulatory duplication for cross-border suppliers targeting this segment.
- Medium:10-18mm formats balance energy density with manufacturing yield, serving industrial IoT sensor networks.
- Large:18-26mm diameters accommodate higher capacity requirements in automotive telematics.
- Extra Large:Above 26mm formats remain limited to specialized industrial equipment with relaxed space constraints.
Small formats dominate medical installed base. Medium formats concentrate expansion as industrial IoT deployments scale.
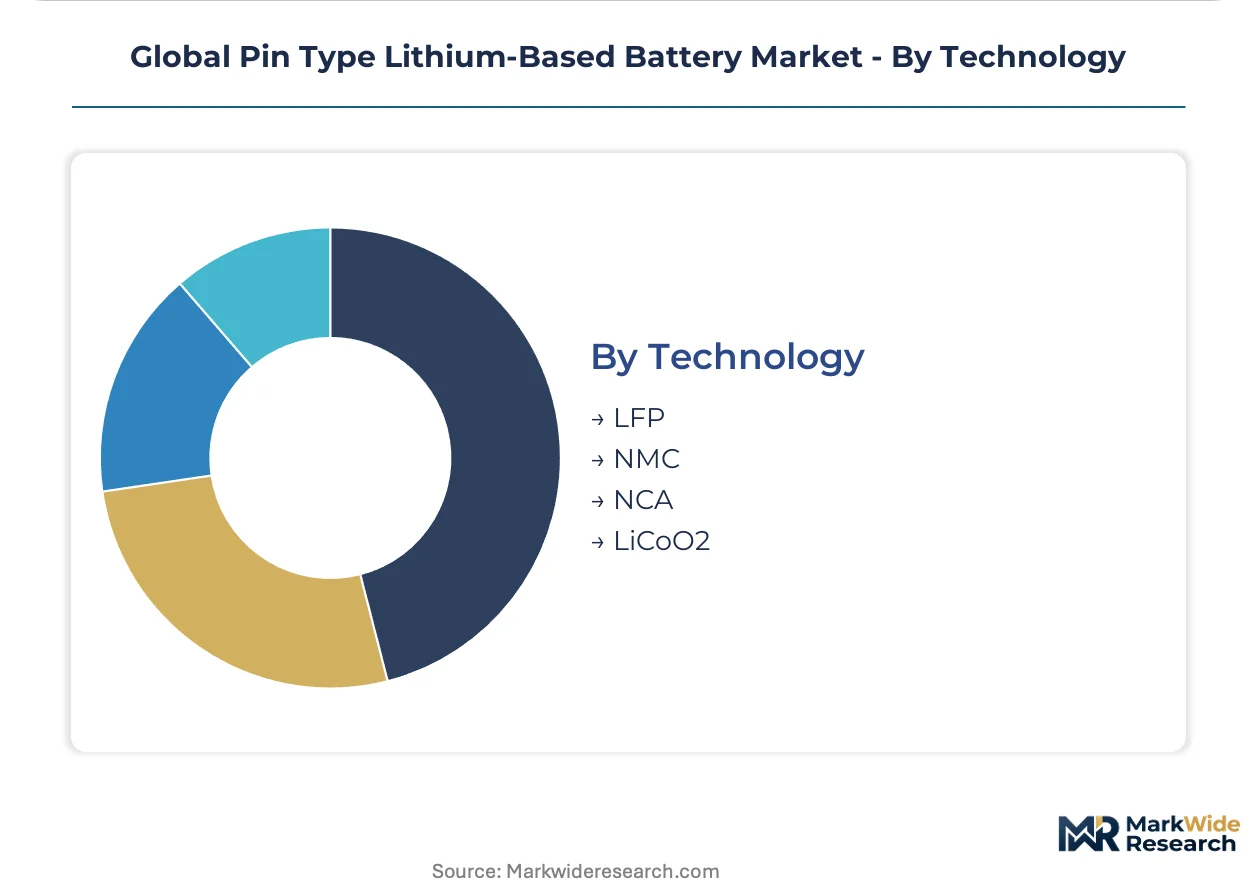
Technology:
Supply concentration varies by chemistry, with NMC cathode active material production clustering in South Korea and China while LFP lines expand domestically under regulatory pressure.
- NMC:Nickel manganese cobalt formulations deliver highest energy density for premium implantable devices but remain exposed to DRC cobalt supply concentration. Panasonic Holdings leverages century-long electrode manufacturing heritage to sustain positioning here despite price volatility.
- LFP:Lithium iron phosphate chemistries sacrifice energy density for thermal runaway tolerance, accelerating in Chinese industrial equipment deployments under GB 31241 certification requirements. Cell assemblers are migrating dedicated domestic lines to satisfy these containment thresholds.
- NCA:Nickel cobalt aluminum variants serve high-discharge applications in automotive telemetry modules.
- LiCoO2:Lithium cobalt oxide maintains presence in legacy implantable device platforms with established reliability records.
NMC dominates current medical-grade revenue. LFP is gaining share fastest as Chinese safety standards tighten and industrial thermal tolerance priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Implantable device OEMs in Switzerland and Minnesota concentrate procurement power for medical-grade pin cells, while industrial sensor demand clusters in German automotive corridors and Chinese manufacturing zones. Regulatory alignment between Japan's METI and PMDA accelerates cross-border qualification timelines. South Korea's Ulsan-Gumi battery belt anchors specialized production for premium tier-2 applications.
United States
FDA quality system regulations govern lithium cells for active implantable medical devices, extending qualification cycles to 24-36 months. Minnesota-based neuromodulation OEMs and Massachusetts cardiac device manufacturers drive demand for hermetic specialty cells with lot-traceable cleanroom production. The FDA's stringent documentation requirements deepen compliance-based switching costs for qualified suppliers.
Germany
Machine condition monitoring in automotive plants requires decade-scale primary cell lifespans for wireless vibration sensors. EU MDR battery documentation mandates enhance technical file requirements for implantable power sources. The Baden-Württemberg and Bavaria industrial corridors concentrate procurement for industrial IoT sensor networks.
China
GB 31241-2022 safety standard revisions tighten nail penetration and overcharge thresholds for domestic pin cell circulation. SAMR-administered certifications push industrial equipment deployments toward LFP chemistries to satisfy thermal runaway containment. Yangtze River Delta manufacturing clusters bifurcate supply chains between export-oriented NMC and domestic LFP-certified lines.
Japan
PMDA-METI coordination aligns battery reliability standards with pharmaceutical device approvals, reducing regulatory duplication for cross-border suppliers. Implantable cardiac monitor OEMs in Tokyo and Osaka specify sub-10mm diameter cells with axial terminal pins. Precision winding equipment manufacturers in the Nagoya corridor support rapid prototyping for premium applications.
South Korea
MFDS medical device regulations interface with international battery safety standards for implantable applications. The Ulsan-Gumi battery belt concentrates cathode active material production and specialized winding equipment for European medical OEMs. Samsung SDI and LG Energy Solution anchor cleanroom production lines that supply premium industrial and automotive tier-2 segments.
Global Pin Type Lithium-Based Battery Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure concentrates among vertically integrated battery conglomerates with century-long electrode manufacturing heritage and dedicated cleanroom capabilities. Strategic archetypes include hermetic seal specialists, silicon-anode innovators, and LFP chemistry migrators. Dominant competitive moves encompass backward integration into separator technologies and geographic expansion into underpenetrated medical device markets.
Among East Asian battery conglomerates, Panasonic Holdings Corporation exemplifies the heritage-tier archetype through its century-long electrode manufacturing lineage. LG Energy Solution and Samsung SDI occupy positions within the South Korean supply cluster, with the former representing dedicated cleanroom production capabilities and the latter anchoring proprietary separator technology development. Contemporary Amperex Technology Co., Limited sits within the scale-driven chemistry diversification tier.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Aucopo |
| JNJ |
| Contemporary Amperex Technology Co., Limited |
| LG Energy Solution |
| BYD Company Limited |
| Samsung SDI |
| SK On |
| EVE Energy |
| Others |
Value Chain & Pricing Dynamics
Cathode active material production in South Korea's Ulsan-Gumi corridor anchors cost structures downstream, concentrating margin capture among qualified cleanroom operators serving FDA-regulated medical OEMs while compressing buffers for second-tier assemblers exposed to cobalt price volatility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange cobalt indexation dominate NMC cathode supply agreements, creating transparent pass-through mechanisms that shield integrated manufacturers from raw material swings. Three-tier pricing structure across medical-grade specialty, industrial standard, and consumer cylindrical levels separates lot-traceable cleanroom production from non-hermetic formats. Pricing pressure stems from silicon-anode qualification timelines as implantable device OEMs demand 40% energy density gains. Consumer electronics buyers exhibit highest price sensitivity; Swiss neuromodulation OEMs absorb premiums for hermetic glass-to-metal seals.
Supply Chain Analysis
Contract manufacturing concentrates at LG Energy Solution's Gumi cleanroom complex and Samsung SDI's Ulsan separator-integrated lines, with Panasonic's Osaka electrode facilities anchoring premium medical supply. Raw material dependencies span DRC cobalt concentrates, Australian spodumene, and Japanese precision winding equipment. Single-source vulnerability runs through Swiss glass-to-metal feedthrough suppliers for hermetic medical cells. Distribution runs through authorized medical device distributors with lot-traceability systems rather than open electronic component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state thin-film alternatives threaten long-term displacement in ultra-miniature implantables, forcing incumbents to accelerate silicon-anode roadmaps and defend qualification-based switching costs before energy density gaps close.
For Market Incumbents: Build regulatory moats through simultaneous FDA quality system and Japan PMDA-METI alignment investments, compressing cross-border approval cycles for medical-grade specialty cells. Anchor backward integration into proprietary separator technologies following Samsung SDI's model, reducing exposure to commodity cathode volatility. Defend against solid-state substitution by accelerating silicon-dominant anode qualification with Minnesota and Swiss neuromodulation OEMs. For New Entrants and Emerging Players: Pursue India's CDSCO risk-classification framework for active implants, where qualified supplier scarcity creates first-mover positioning in surgical device power systems. Target German automotive vibration sensor networks requiring decade-scale primary cell lifespans, leveraging LFP chemistry migration under EU MDR documentation requirements. Establish direct technical service contracts with Baden-Württemberg industrial OEMs, unbundling after-sales support from product supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade cleanroom production, as ISO 14644 Class 7 certification thresholds exclude regional second-tier entrants and deepen consolidation logic. Five-to-ten-year viability favors suppliers with pre-existing lot-traceability systems and multi-regulatory approval footprints. Monitor silicon-anode qualification announcements from Swiss and Minnesota implantable OEMs as inflection signals for chemistry transition velocity. Quarterly review of cobalt LME price volatility and GB 31241-2022 certification timelines is advised to detect supply chain repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644 Class 7 lines at Ulsan-Gumi anchor South Korean supply to European medical OEMs. |
| Silicon-Anode R&D Partnership | Collaboration with Swiss neuromodulation device makers accelerates 40% energy density qualification timelines. |
| Multi-Regulatory Approval Pathway | Simultaneous FDA and PMDA-METI alignment reduces cross-border duplication for implantable power systems. |
| LFP Chemistry Migration | Domestic Chinese lines under GB 31241-2022 satisfy thermal runaway containment for industrial sensor networks. |
| Glass-to-Metal Seal Backward Integration | Captive feedthrough production reduces dependency on Swiss and Japanese component houses. |
Study Parameters
Cross-validation between primary interviews with biomedical engineers at Minnesota cardiac device manufacturers and secondary analysis of FDA 510(k) filings anchors the qualitative findings on qualification timeline structures. Plant managers at South Korean cathode active material facilities, procurement leads at German automotive Tier 1 suppliers, and GPO contracts managers at US hospital systems provided operational data. SEC 10-K disclosures from battery conglomerates, SAMR GB 31241 certification records, and EU MDR technical file databases supplied downstream validation. Bottom-up cell shipment estimates and top-down medical device production forecasts were reconciled across triangulation points.
Calibration against historical qualification cycle data and cobalt price elasticity responses shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user application, size format, and cathode chemistry technology. CAGRs were derived from slope analysis of installed base replacement curves and expansion coefficients for wireless implantable devices. Silicon-anode penetration assumptions and LFP chemistry migration rates under Chinese safety standards served as chemistry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in DRC cobalt supply stability, yen-euro exchange rates affecting Japanese medical exports, or Chinese industrial sensor demand would shift the trajectory. Forecasts reflect documented assumptions on cleanroom capacity expansion timelines and regulatory approval velocity. Supply chain concentration risks, solid-state substitution timelines, and transportation restriction evolution from ICAO and IATA represent specific revision factors. Quarterly review of silicon-anode qualification announcements, GB 31241 certification issuance rates, and cobalt LME price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market