
 Lithium-Ion Battery Rechargeable Hearing Aids Market | 2026-2036
Lithium-Ion Battery Rechargeable Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Rechargeable Hearing Aids Market Insights
OTC hearing aid regulations from FDA is pivoting competitive dynamics by lowering barriers for direct-to-consumer entrants. Sonova leverages its audiology clinic network to sustain premium channel control. Demant anchors European manufacturing scale while WS Audiology competes across multiple price tiers through brand diversification. Starkey specializes in American-made positioning to differentiate against Asian battery suppliers.
Lithium-ion battery rechargeable hearing aids integrate compact cylindrical cells with integrated power management circuits, typically delivering 24-30 hours of operation per three-hour charge cycle for mild-to-profound hearing loss compensation. The primary commercial purpose centers on eliminating disposable zinc-air battery dependency while improving moisture resistance through sealed charging contacts. RIC configurations capture widening margin pools as audiologists prioritize receiver flexibility combined with rechargeable convenience. Audiology clinics dominate distribution channels for fitting-dependent BTE and ITE segments, though online retail accelerates for self-adjusting CIC models targeting mild hearing loss consumers.
FDA oversees device safety and OTC classification thresholds in the United States, while CE marking under EU MDR governs European market access with escalating clinical evidence requirements. EMA coordination with national health technology assessment bodies shapes reimbursement velocity across member states. Battery transport regulations from ICAO and IATA constrain lithium-ion cell logistics, forcing manufacturers toward regional cell assembly partnerships. Stakeholders must monitor how FDA OTC enforcement discretion evolves against state-level audiology licensing board pushback.
Market Dynamics
FDA OTC pathways are compressing prescription timelines while Medicare Advantage hearing benefits expand coverage pools, creating dual-channel pressure on traditional audiology-dependent distribution models.
Growth Catalysts
- Medicare Advantage Hearing Benefits:United States private plans now bundle hearing coverage, expanding addressable elderly populations beyond traditional fee-for-service Medicare limitations.
- EU MDR Streamlined Pathways:CE marking harmonization under Medical Device Regulation accelerates cross-border market access for rechargeable device manufacturers.
- Lithium-Ion Cell Miniaturization:Cylindrical cell energy density improvements enable 24-hour operation in smaller ITE and CIC form factors previously constrained by power budgets.
Market Restraints
- Cobalt Supply Concentration:Democratic Republic of Congo dominance in cobalt mining creates geopolitical input cost volatility for battery cathode supply chains.
- ICAO/IATA Lithium Transport Restrictions:Air freight limitations on lithium-ion cell shipments force regional assembly partnerships, fragmenting manufacturing scale economies.
- Zinc-Air Disposable Residual Demand:Price-sensitive users in developing markets continue preferring low upfront-cost disposable battery devices, slowing rechargeable penetration.
Strategic Opportunities
- Japan Aging Demographics:METI healthcare technology adoption incentives target hearing aid penetration among the country's super-aged population cohorts.
- Direct-to-Consumer Online Channels:Self-fitting algorithms and smartphone-based hearing tests enable bypass of traditional audiology clinic gatekeepers.
- AI-Powered Adaptive Sound Processing:Machine learning integration with rechargeable power management creates premium differentiation through real-time environment classification.
Industry Challenges
- Audiologist Workforce Constraints:United States licensing board restrictions on technician-performed fittings create bottleneck capacity for prescription-channel growth.
- Battery Degradation Certification:IEC 62133 secondary cell cycle-life testing requirements extend product validation timelines before market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Rechargeable Hearing Aids Market |
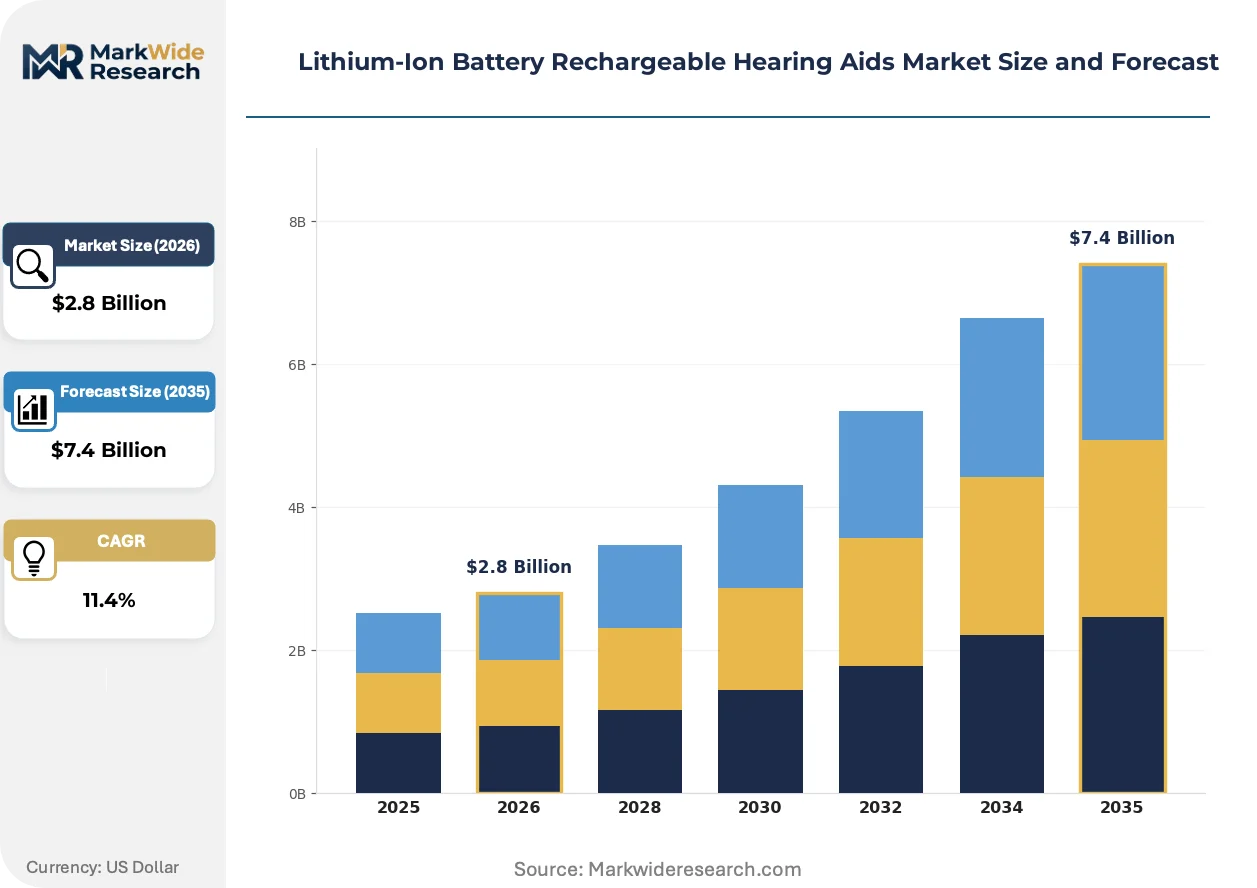
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BTE, ITE, RIC, CIC Battery Technology: Lithium-Ion, NiMH, NiCd, Zinc-Air End User: Elderly, Adults, Children, Hearing Impaired Distribution Channel: Pharmacy, Online Retail, Audiology Clinics, Specialty Stores |
| Companies Covered | Sonova, Demant, WS Audiology, GN Store Nord, Starkey, Eargo, Phonak, Widex, VARTA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Rechargeable Hearing Aids Market Trends and Innovations
Power management semiconductor integration and adaptive signal processing algorithms are compressing device form factors while regulatory frameworks restructure channel access rules.
Bluetooth Low Energy audio streaming is modularizing hearing aid architecture by decoupling wireless connectivity from core amplification circuits. Premium RIC manufacturers adopt this separation to enable firmware-upgradable connectivity without hardware replacement. The approach is modularizing product lifecycle management, extending replacement cycles while creating recurring revenue through software subscription tiers.
EU MDR clinical evidence requirements are intensifying post-market surveillance obligations for rechargeable hearing aid manufacturers. Device registries and real-world performance data collection now accompany initial CE marking, elevating compliance costs for smaller entrants. German and French notified bodies are processing submissions most aggressively, concentrating regulatory expertise in Central European assessment institutions.
Self-directed hearing assessments via smartphone applications are displacing clinical audiogram dependencies for mild-to-moderate loss consumers. United States OTC channel entrants leverage this behavioral shift to target younger presbycusis patients uncomfortable with traditional clinic stigma. Germany and Japan show parallel demand rotation toward discreet self-adjusting devices among working-age professionals seeking occupational hearing support.
Lithium-Ion Battery Rechargeable Hearing Aids Market Segmentation
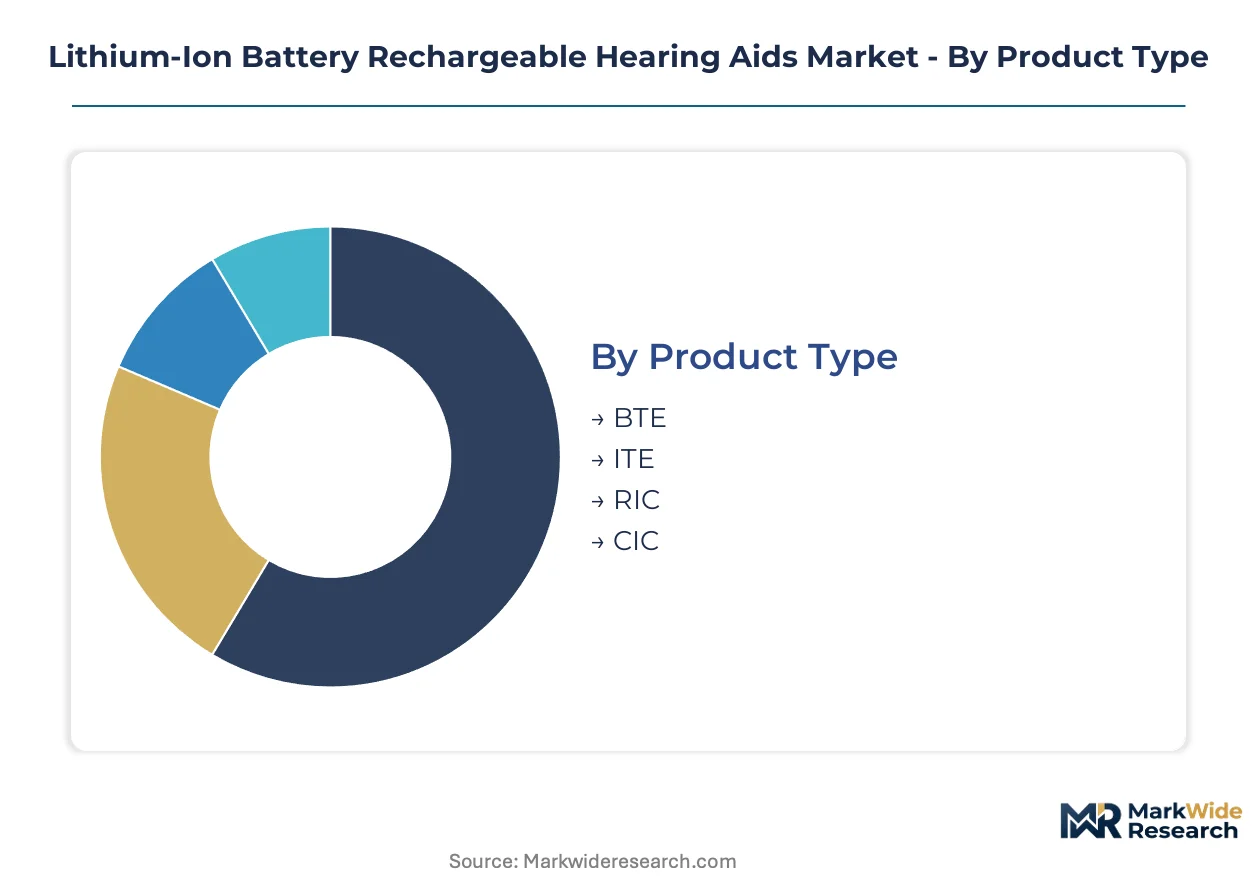
Device replacement cycles vary dramatically across form factors and user demographics, creating distinct upgrade windows that manufacturers must align against. Segmentation reveals where rechargeable technology commands premium positioning versus where disposable alternatives retain residual share.
Product Type:
Upgrade timing diverges sharply by form factor, with behind-the-ear models cycling every 4-5 years while completely-in-canal devices compress toward 3-year replacement as miniaturization accelerates.
- RIC:Receiver-in-canal architectures separate the speaker from the main housing, enabling audiologists to swap receiver power levels without full device replacement. Demand clusters in United States Medicare Advantage populations where flexible fitting justifies premium rechargeable positioning.
- BTE:Behind-the-ear configurations house the largest lithium-ion cells, delivering 30-hour operation cycles that dominate severe-to-profound loss prescriptions. Germany's statutory health insurance reimbursement favors these higher-power units for elderly beneficiaries.
- ITE:In-the-ear devices sacrifice battery capacity for cosmetic discretion, typically achieving 24-hour operation in mild-to-moderate loss applications.
- CIC:Completely-in-canal miniaturization strains power budgets, limiting rechargeable viability to premium tiers with advanced cell chemistry.
Volume placements concentrate in BTE configurations; the faster expansion belongs to RIC as fitting flexibility drives audiologist preference.
Battery Technology:
Cost tier stratification separates premium rechargeable systems from economy disposable alternatives, with chemistry choice determining both upfront device pricing and lifetime ownership economics.
- Lithium-Ion:Cylindrical cells with cobalt-based cathodes deliver highest energy density for sealed, moisture-resistant designs. United States FDA OTC entrants leverage this chemistry to differentiate direct-to-consumer offerings against legacy zinc-air competitors.
- Zinc-Air:Disposable button cells retain dominant share in price-sensitive developing markets where low initial acquisition cost outweighs lifetime disposable expense.
- NiMH:Nickel-metal hydride alternatives occupy mid-tier positioning with lower energy density but reduced raw material volatility versus cobalt-dependent lithium-ion.
- NiCd:Nickel-cadmium chemistry persists only in legacy device servicing due to environmental restrictions under EU RoHS and REACH directives.
Shipment volumes favor lithium-ion in reimbursed markets; zinc-air retains residual dominance where out-of-pocket payment prevails.
End User:
Customer type segmentation maps directly to hearing loss progression curves, with presbycusis driving replacement velocity in aging populations versus congenital or occupational loss profiles.
- Elderly:Age-related hearing loss generates the steepest replacement cycles as sequential device upgrades track declining auditory function. Japan's super-aged demographics concentrate demand here, with METI incentives accelerating rechargeable adoption among 75-plus cohorts.
- Adults:Working-age users with early-onset presbycusis or noise-induced loss show strongest preference for discreet rechargeable CIC and ITE form factors that minimize occupational stigma.
- Hearing Impaired:This broader category captures severe-to-profound loss patients requiring maximum amplification power, typically served by BTE and high-output RIC configurations.
- Children:Pediatric fittings demand ruggedized, tamper-resistant designs with parental-controlled charging systems and growth-accommodating physical fit.
Elderly users account for dominant placement volumes; adult working-age segments are climbing the fastest as early intervention norms shift.
Distribution Channel:
Channel concentration reflects fitting complexity, with professional-dependent segments resisting disintermediation longer than self-adjusting alternatives.
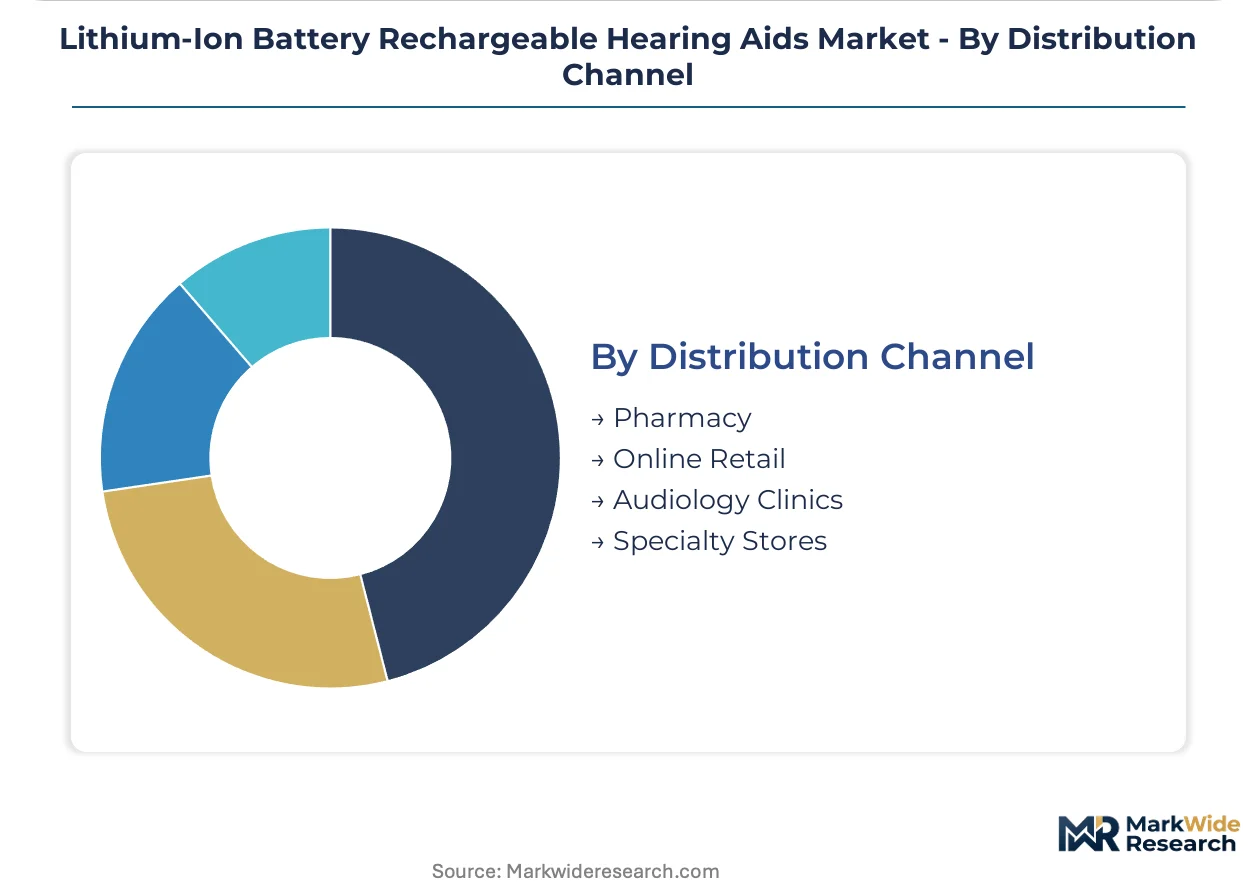
- Audiology Clinics:Professional fitting services dominate BTE and RIC distribution, capturing recurring revenue through verification protocols and device reprogramming. German and French clinic networks maintain particularly dense geographic coverage.
- Online Retail:Direct-to-consumer platforms accelerate for self-fitting CIC and ITE models targeting mild-to-moderate loss, leveraging smartphone-based hearing tests to bypass traditional gatekeepers.
- Pharmacy:Retail pharmacy chains increasingly stock entry-level rechargeable devices in markets with pharmacist-permitted hearing aid dispensing regulations.
- Specialty Stores:Consumer electronics retailers and optical chains experiment with hearing aid kiosks, though fitting capability constraints limit penetration beyond basic amplification devices.
Transaction volume concentrates in audiology clinics; online retail channels show steepest expansion trajectory as OTC regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates the highest placement volumes, with Medicare Advantage hearing benefits and FDA OTC pathways restructuring channel access. Germany and Japan follow as aging demographics expand rechargeable device penetration among elderly cohorts.
United States
Medicare Advantage plans now bundle hearing coverage, expanding addressable populations beyond fee-for-service limitations. FDA OTC regulations compress prescription timelines and enable direct-to-consumer channels. Minnesota and Massachusetts host dense audiology clinic networks where rechargeable RIC fittings dominate severe-to-profound loss prescriptions.
Germany
Statutory health insurance reimbursement favors higher-power BTE units for elderly beneficiaries. CE marking under EU MDR governs market access with escalating clinical evidence requirements. Berlin and Munich concentrate notified body expertise and manufacturing scale for lithium-ion cell integration.
Japan
METI healthcare technology adoption incentives target hearing aid penetration among super-aged 75-plus cohorts. The country's national pharmaceutical regulator coordinates with health technology assessment bodies on reimbursement velocity. Tokyo and Osaka anchor domestic distribution networks for discreet rechargeable ITE devices.
United Kingdom
NHS hearing aid provision creates volume demand for cost-optimized rechargeable BTE configurations. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards. London and Manchester audiology clinics drive premium RIC adoption among privately insured working-age professionals.
South Korea
MFDS medical device approval pathways accelerate market entry for rechargeable hearing aid manufacturers. Occupational hearing support programs expand demand among manufacturing workforce segments. Seoul Capital Area concentrates electronics supply chain partnerships for battery cell sourcing.
Lithium-Ion Battery Rechargeable Hearing Aids Market Competitive Landscape
Swiss and Danish producers anchor premium-tier positioning; American specialists hold direct-to-consumer channels. The market structure consolidates around five major audiology conglomerates controlling clinic networks and manufacturing scale. Three archetypes dominate: integrated audiology clinic operators, component-scale battery suppliers, and direct-to-consumer platform entrants. Competitive moves center on brand portfolio diversification and regional cell assembly partnerships to bypass ICAO transport restrictions.
Within the integrated audiology tier, Sonova and Demant exemplify clinic-network-dependent positioning, while WS Audiology occupies multi-brand scale coverage. These three entities represent the dominant archetype of audiology clinic integration with rechargeable device manufacturing. VARTA AG anchors the component-supplier archetype as a German cell manufacturer. Eargo sits within the direct-to-consumer vector targeting mild-to-moderate loss users through online self-fitting platforms.
| Leading Market Players |
|---|
| Sonova |
| Demant |
| WS Audiology |
| GN Store Nord |
| Starkey |
| Eargo |
| Phonak |
| Widex |
| VARTA AG |
| Others |
Pricing and Supply Chain Analysis
Cylindrical cell miniaturization for ITE and CIC form factors is compressing unit economics while concentrating cathode chemistry sourcing among East Asian suppliers. This dual shift elevates pricing power for integrated manufacturers with captive cell partnerships while pressuring pure-play device assemblers exposed to spot cobalt markets.
Pricing Analysis
Volume placements concentrate in standard-tier BTE configurations where Medicare Advantage reimbursement caps limit margin expansion, while premium-tier RIC devices with AI-powered processing sustain wider spreads through audiologist channel control. Price differentiation hinges on FDA certification tier and after-sales fitting service bundling. Pricing pressure stems from OTC entrants compressing mid-market positioning through direct-to-consumer self-fitting platforms. Elderly beneficiaries under statutory insurance schemes exhibit highest price sensitivity, whereas working-age professionals purchasing discreet CIC models for occupational use demonstrate lowest sensitivity to upfront device cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from integrated audiology conglomerates, while regional assembly partnerships serve fragmented clinic networks. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active materials drawing from cobalt feedstock anchored in the Democratic Republic of Congo. Supply chain risk centers on ICAO lithium transport restrictions forcing geographic fragmentation of final assembly. Distribution runs through audiology clinic networks for fitting-dependent BTE and RIC segments, with online retail emerging for self-adjusting CIC alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as lithium-ion rechargeable systems displace legacy zinc-air disposable dependency across reimbursed patient populations.
For Market Incumbents: Acquire regional cell assembly capacity to bypass ICAO air freight restrictions and secure cobalt cathode supply continuity. Consolidate audiology clinic network control through exclusive fitting software licensing to defend against OTC channel disintermediation. Prioritize backward integration into power management semiconductor sourcing as analog chip shortages threaten production schedules. For New Entrants and Emerging Players: Capture self-fitting CIC demand among working-age professionals in Germany and Japan where occupational stigma drives discreet device preference. Target online retail channels with smartphone-based hearing test integration to bypass traditional clinic gatekeepers. Position through direct-to-consumer subscription models bundling device replacement with remote audiologist support. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated audiology conglomerates seeking battery technology capabilities. Long-term viability favors manufacturers with FDA OTC clearance and CE marking under EU MDR already secured. Watch FDA enforcement discretion against state audiology licensing board pushback as the critical inflection signal for channel structure stability.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cell Assembly Partnership | ICAO transport restrictions force geographic diversification of lithium-ion cell final assembly. |
| FDA OTC Clearance Pathway | Direct-to-consumer channel access compresses traditional prescription timeline dependencies. |
| AI-Powered Adaptive Processing Integration | Machine learning differentiation sustains premium pricing against commoditized amplification. |
| Audiology Clinic Network Consolidation | Fitting-dependent BTE and RIC segments resist disintermediation through professional service bundling. |
| Cobalt Cathode Supply Agreement | DRC mining concentration creates input cost volatility requiring long-term offtake security. |
Research Methodology
Multi-period observation of FDA submission timelines, CE marking velocity under EU MDR, and Medicare Advantage hearing benefit expansion anchored the trend analysis, supplemented by interviews with audiology clinic operators, biomedical engineers at hearing aid manufacturers, procurement managers at lithium-ion cell suppliers, and GPO contracts managers at hospital systems. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, CMS Medicare Advantage plan benefit filings, and customs trade data on lithium cell imports. Bottom-up shipment estimates by form factor and top-down reimbursement spend analysis were triangulated against manufacturer production disclosures.
Input-output matrices mapped rechargeable device unit economics against cobalt cathode pricing, power management semiconductor availability, and audiology labor capacity constraints across the projection horizon. Segmentation dimensions modeled included form factor architecture, battery chemistry tier, end-user age cohort, and distribution channel structure. CAGRs were derived from curve-fitting historical placement velocities against demographic hearing loss prevalence projections and regulatory pathway acceleration assumptions. Forecast inputs incorporated METI healthcare technology adoption incentive trajectories and ICAO lithium transport restriction enforcement patterns.
The model holds under stable FDA OTC enforcement discretion and continued Medicare Advantage hearing benefit expansion; deviation in state audiology licensing board regulatory pushback or DRC cobalt supply disruptions would shift channel structure and input cost assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
HEV Li-Ion Battery Market